
Company News
October 27, 2022
Olin Earnings Call Epoxy Highlights
Olin Corp (OLN) Q3 2022 Earnings Call Transcript
Oct. 27, 2022 12:33 PM ETOlin Corporation (OLN)
Q3: 2022-10-26 Earnings Summary
EPS of $2.15 beats by $0.30 | Revenue of $2.32B (-0.79% Y/Y) misses by $26.01M
Olin Corp (NYSE:OLN) Q3 2022 Earnings Conference Call October 27, 2022 9:00 AM ET
Company Participants
Steve Keenan – Director, IR
Scott Sutton – President, CEO & Chairman
Todd Slater – SVP & CFO
Scott Sutton
Thanks, Steve, and good morning to everyone. The Olin team is all about delivering on opportunities. We have 2 major opportunities before us. I’ll start with opportunity, number one. We are experiencing recessionary conditions, and the opportunity is to show Olin will perform remarkably different than history may indicate. Over the next 4 quarters, we forecast delivering more than $1.1 billion of levered free cash flow.
This is remarkably different. Don’t worry that we had to pull back from the EDC market, while prices cratered, creating a major PBC value morass and don’t worry that we had to optimize our epoxy participation to support our advanced partners while Asia liquidity temporarily lowered others. These necessary activities are respectful of our core theme to focus on value, set our market participation based on the weak side of the ECU and by liquidity where necessary to lift the value of the ECU, which we did in the third quarter.
Kevin McCarthy
And then I know you’re throttling back on volumes in an effort to support the market. That effort appears to be succeeding. But Nevertheless, can you talk about what your operating rates were in the quarter in chlor alkali and epoxy and how you see that utilization progressing here October?
Scott Sutton
Yes. Well, maybe instead of all of those operation rates, I’ll at least share with you what we’re doing in epoxy if you were to think about the equivalent operating rates, all of our resin production facilities, we’re running below 50% there in order to preserve value. And remember, our recession case said that we could move the whole company down to that level. And so I would just say we have plenty of room left across the rest of the company to make our recession prediction come true.
Hassan Ahmed
I just wanted to revisit the Q4 guidance, particularly in light of recessionary conditions and the like. I mean, look, I understand Q4 tends to be seasonally weak. You guys have consistently talked about certain sort of markets, be it EDC, be epoxy conditions over there being even below trough conditions.
But if I were to annualize the lower end of your Q4 guidance, I still come up with, call it, $1.75 billion in EBITDA, which obviously is kind of the midpoint of the $1.5 billion to $2 billion of the guidance range for a trough that you guys have given. So with the conditions evolving the way they are, I mean I just wanted to sort of get your take on how comfortable you guys continue to be with that trough EBITDA guidance range.
Scott Sutton
Yes. I mean, look, I mean, it’s still our guidance range. And in fact, it’s been our guidance range now for the last 3 quarters as we’ve really been preparing this window to show that Olin delivers a different level of free cash flow than we did before. I will say, of course, I understand annualized in the fourth quarter, and you’re right, get exactly to that conclusion, even though the fourth quarter has traditionally weak factors on top of all the extraordinary factors that are going on in the world right now. I will just again sort of caution that we may experience 1 or 2 quarters that are lower than that in order to set the value equation right for the rest of the year, though.
I mean we’re not going to hesitate to take the proper actions in advance to make sure that value doesn’t decline. We’re not having to do that yet, but it could certainly happen as the recession plays out.
Michael Sison
Just curious in terms of your — the volume declines in cab and epoxy down with 1729. What do you think the fundamental volume declines are? And I guess the one way to think about it, too, is if your volumes are flat and your ECU PCI did improve, would your EBITDA — could that — should that have been up year-over-year?
Scott Sutton
Yes. And so if you — Mike, if you’re asking about sort of what’s the fundamental decline in the marketplace, it’s likely to be less than the decline in Olin volumes because remember, Olin tends to eat those shortfalls in demand from a production standpoint. We may not completely eat it from a sales standpoint because we go out and buy liquidity out of the marketplace at that moment, to fill in that gap a little bit. So you’re going to see our production down more than the decline in the marketplace, you’ll still see our sales volume down more than the decline in the marketplace, but our sales volume declines aren’t as big as our production volume declines.
Unidentified Analyst
It’s Chris Perrella on for Josh. The — I was curious as to what you’ve done to hedge out natural gas costs into the fourth quarter and out to next year and at what level?
Todd Slater
Yes. Chris, this is Todd. We are, as you know, an active hedger for natural gas as that’s directionally about 70% of our fuel source for power. We — a quarter out, we are very heavily hedged and generally have a rolling 4-quarter program. So you can imagine that we have a portion of 2023 already covered with active hedges.
Unidentified Analyst
All right. And then to your earlier comments about flexing down the chlor alkali rate to protect value and cash flow on the shoulder seasons. Is the expectation for that to sort of hold the chlor-alkali rate, your operating rate steady into the first quarter, assuming EDC and epoxy stays where they are now?
Scott Sutton
Well, look, without getting too specific, Chris, I would just say that there’s going to be shifts and changes in our production rate relative to the liquidity that we buy out of the marketplace. And we’ve already said that limited our participation in the vinyls chain. And it’s certainly not impossible that we choose to limit that participation even further as we enter 2023.
Operator
The next question is from Matthew Blair with TPH.
Matthew Blair
I had a question on the epoxy feedstocks. It looks like propylene and benzene are coming down quite a bit in Q4. Would that be a feedstock benefit to epoxy in Q4? Or do you have hedges and to really think about this as potentially flowing through into 2023?
Todd Slater
Matthew, this is Todd. As we think about — especially in North America, the costs have come down from the third quarter. And therefore, that does lower our costs. But once you start around the globe on an international basis, those lower costs really, you’ll see that benefit in Epoxy in the first quarter.
Unidentified Analyst
That’s helpful. And then my follow-up is just on the epoxy market. Have you seen any change in behavior since the end of September, either in terms of buying dynamics or selling dynamics?
Scott Sutton
I would say the same principal trend stays in place. With the China demand shortfall, but yet still running at expanding assets there. We’ve seen traditional trade flows temporarily reversed. So a lot of that material is ending up either in the U.S. or Europe or a lot of material that used to be produced in other countries in Asia and used to — for import into China is coming to the U.S. and Europe. And that really hasn’t changed.
I would say that the good news is there’s been some moderation of the rate of change there. And so there’s some stability there, and we’ve settled with a group of advanced customers that value the Olin solution and also value the fact that our epoxy resin carries a CO2 footprint that’s probably below the CO2 footprint of all that material that’s making its way out of China. So there’s some moderation there.
https://seekingalpha.com/article/4549910-olin-corp-oln-q3-2022-earnings-call-transcript
October 27, 2022
Dmitris is Headed to Repi
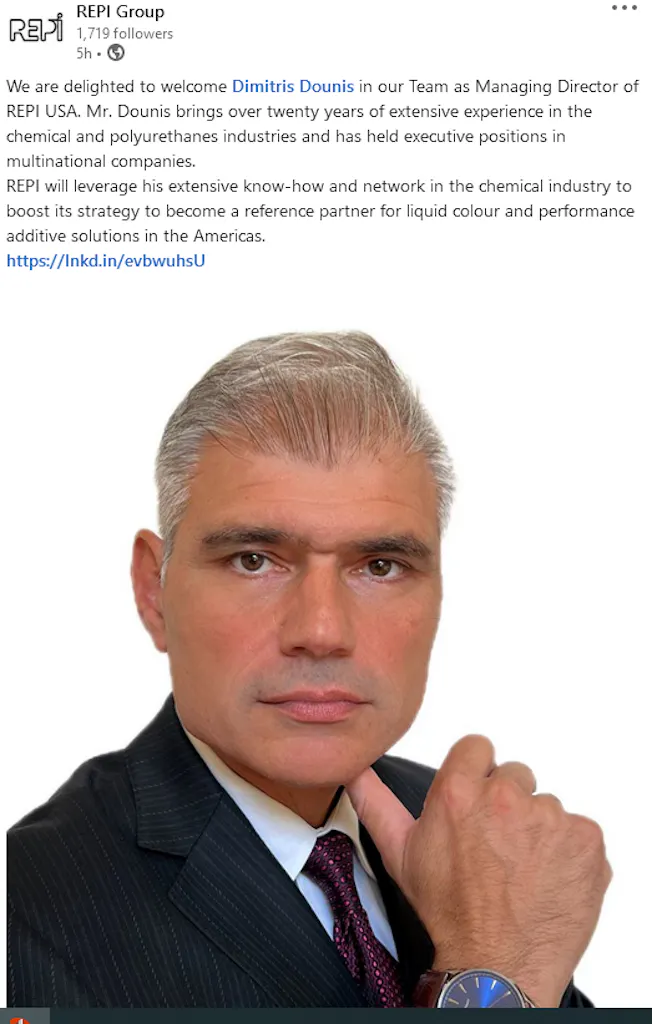
October 27, 2022
Dmitris is Headed to Repi
October 27, 2022
West Fraser Results
WEST FRASER ANNOUNCES THIRD QUARTER 2022 RESULTS
share:
Share on FacebookTweet on TwitterPost to Reddit
October 26, 2022 – 5:01 pm
VANCOUVER, BC, Oct. 26, 2022 – West Fraser Timber Co. Ltd. (“West Fraser” or the “Company”) (TSX and NYSE: WFG) reported today the third quarter results of 2022 (“Q3-22”). All dollar amounts in this news release are expressed in U.S. dollars unless noted otherwise.
Third Quarter Highlights
- Sales of $2.088 billion and earnings of $216 million, or $2.50 per diluted share
- Adjusted EBITDA1 of $426 million, representing 20% of sales
- Lumber segment Adjusted EBITDA1 of $160 million, including $81 million of export duty recovery
- North America Engineered Wood Products (“NA EWP”) segment Adjusted EBITDA1 of $215 million
- Pulp & Paper segment Adjusted EBITDA1 of $29 million
- Europe Engineered Wood Products (“Europe EWP”) segment Adjusted EBITDA1 of $24 million
- Repurchased 2.224 million shares for aggregate consideration of $182 million
| 1. Adjusted EBITDA is a non-GAAP financial measure. Refer to the “Non-GAAP and Other Specified Financial Measures” section of this document for more information on this measure. |
“West Fraser generated solid financial results in the third quarter of 2022 and returned more than $200 million of capital to shareholders through share repurchases and a quarterly dividend. Overall, West Fraser continues to benefit from product and geographic diversity and a track record of disciplined capital allocation,” said Ray Ferris, West Fraser’s President & CEO. “We saw considerable improvement in the transportation challenges that had impacted our business earlier this year. However, ongoing inflationary cost pressures and slowing demand for many of our key products impacted our financial results this quarter. Our team continues to prioritize financial discipline as we navigate near-term market uncertainties to ensure we are best positioned to take advantage of the more favourable demand markets we envision over the medium and longer term.”
“To that end, with the support of the local community, we are pleased to announce the planned addition of a new state-of-the-art lumber manufacturing complex with the brownfield development at our Henderson, Texas facility. This project is another important step in our strategy of optimizing our lumber portfolio by continuously driving cost efficiency through deployment of advanced technologies utilized by our skilled and engaged teams.”
Results Summary
Third quarter sales were $2.088 billion, compared to $2.887 billion in the second quarter of 2022. Third quarter earnings were $216 million, or $2.50 per diluted share, compared to $762 million, or $7.59 per diluted share in the second quarter of 2022. Third quarter Adjusted EBITDA1 was $426 million compared to $1,124 million in the second quarter of 2022.
Outlook
Markets
Several key trends that have served as positive drivers in recent years are expected to continue to support medium and longer-term demand for new home construction in North America.
The most significant uses for our North America lumber, OSB and wood panel products are residential construction, repair and remodelling and industrial applications. Over the medium-term, we expect that an aging housing stock, lagging completions of previously started new home construction and greater acceptance of work-from-home practices may help to offset near-term headwinds and spur repair and renovation spending that supports lumber, plywood and OSB demand. Over the longer-term, growing market penetration of mass timber in industrial and commercial applications is also expected to become a more significant demand growth driver for wood building products in North America.
The seasonally adjusted annualized rate of U.S. housing starts averaged 1.44 million units in September 2022, with permits issued averaging 1.56 million units, according to the U.S. Census Bureau. However, demand for new home construction and our wood building products may decline in the near-term should interest rates continue to rise and consumer sentiment and housing affordability continue to be impacted.
The demand for our European products is also expected to remain robust over the longer-term as use of OSB as an alternative to plywood continues to grow, and an aging housing stock supports long-term repair and renovation spending and additional demand for our wood building products. Near-term challenges, including rising interest rates, ongoing geopolitical developments and inflationary pressures, are expected to cause a temporary slowing of demand for our products in Europe, however, we are confident that we will be able to navigate through these periods and capitalize on opportunities for long-term growth ahead.
https://www.stocktitan.net/news/WFG/west-fraser-announces-third-quarter-2022-2wl86ducfhas.html
October 27, 2022
West Fraser Results
WEST FRASER ANNOUNCES THIRD QUARTER 2022 RESULTS
share:
Share on FacebookTweet on TwitterPost to Reddit
October 26, 2022 – 5:01 pm
VANCOUVER, BC, Oct. 26, 2022 – West Fraser Timber Co. Ltd. (“West Fraser” or the “Company”) (TSX and NYSE: WFG) reported today the third quarter results of 2022 (“Q3-22”). All dollar amounts in this news release are expressed in U.S. dollars unless noted otherwise.
Third Quarter Highlights
- Sales of $2.088 billion and earnings of $216 million, or $2.50 per diluted share
- Adjusted EBITDA1 of $426 million, representing 20% of sales
- Lumber segment Adjusted EBITDA1 of $160 million, including $81 million of export duty recovery
- North America Engineered Wood Products (“NA EWP”) segment Adjusted EBITDA1 of $215 million
- Pulp & Paper segment Adjusted EBITDA1 of $29 million
- Europe Engineered Wood Products (“Europe EWP”) segment Adjusted EBITDA1 of $24 million
- Repurchased 2.224 million shares for aggregate consideration of $182 million
| 1. Adjusted EBITDA is a non-GAAP financial measure. Refer to the “Non-GAAP and Other Specified Financial Measures” section of this document for more information on this measure. |
“West Fraser generated solid financial results in the third quarter of 2022 and returned more than $200 million of capital to shareholders through share repurchases and a quarterly dividend. Overall, West Fraser continues to benefit from product and geographic diversity and a track record of disciplined capital allocation,” said Ray Ferris, West Fraser’s President & CEO. “We saw considerable improvement in the transportation challenges that had impacted our business earlier this year. However, ongoing inflationary cost pressures and slowing demand for many of our key products impacted our financial results this quarter. Our team continues to prioritize financial discipline as we navigate near-term market uncertainties to ensure we are best positioned to take advantage of the more favourable demand markets we envision over the medium and longer term.”
“To that end, with the support of the local community, we are pleased to announce the planned addition of a new state-of-the-art lumber manufacturing complex with the brownfield development at our Henderson, Texas facility. This project is another important step in our strategy of optimizing our lumber portfolio by continuously driving cost efficiency through deployment of advanced technologies utilized by our skilled and engaged teams.”
Results Summary
Third quarter sales were $2.088 billion, compared to $2.887 billion in the second quarter of 2022. Third quarter earnings were $216 million, or $2.50 per diluted share, compared to $762 million, or $7.59 per diluted share in the second quarter of 2022. Third quarter Adjusted EBITDA1 was $426 million compared to $1,124 million in the second quarter of 2022.
Outlook
Markets
Several key trends that have served as positive drivers in recent years are expected to continue to support medium and longer-term demand for new home construction in North America.
The most significant uses for our North America lumber, OSB and wood panel products are residential construction, repair and remodelling and industrial applications. Over the medium-term, we expect that an aging housing stock, lagging completions of previously started new home construction and greater acceptance of work-from-home practices may help to offset near-term headwinds and spur repair and renovation spending that supports lumber, plywood and OSB demand. Over the longer-term, growing market penetration of mass timber in industrial and commercial applications is also expected to become a more significant demand growth driver for wood building products in North America.
The seasonally adjusted annualized rate of U.S. housing starts averaged 1.44 million units in September 2022, with permits issued averaging 1.56 million units, according to the U.S. Census Bureau. However, demand for new home construction and our wood building products may decline in the near-term should interest rates continue to rise and consumer sentiment and housing affordability continue to be impacted.
The demand for our European products is also expected to remain robust over the longer-term as use of OSB as an alternative to plywood continues to grow, and an aging housing stock supports long-term repair and renovation spending and additional demand for our wood building products. Near-term challenges, including rising interest rates, ongoing geopolitical developments and inflationary pressures, are expected to cause a temporary slowing of demand for our products in Europe, however, we are confident that we will be able to navigate through these periods and capitalize on opportunities for long-term growth ahead.
https://www.stocktitan.net/news/WFG/west-fraser-announces-third-quarter-2022-2wl86ducfhas.html
 Everchem Updates Archive
 Sign Up for Email Updates