
Technology
June 25, 2026
China Bans HCFC-141b Use in Rigid Foams
HCFC-141b Ban Enters the Countdown: Is the PU Rigid Foam System About to Change?
June 15, 2026 6 min read
Viewing the Green Upgrade of Rigid Foam Through Blowing-Agent Substitution: Costs, Compliance and Order Thresholds
| Core view: After July 1, the transition window for HCFC-141b in spray polyurethane foam products will close. The policy may not directly lift total demand for PU rigid foam, but it will reshape formulation systems, cost structures and order-entry thresholds for premixed polyols, spray rigid foam and downstream insulation projects. |
As the July 1 deadline approaches, the PU rigid foam industry is reaching an important environmental-compliance watershed. According to Ministry of Ecology and Environment Announcement No. 28 of 2025, from January 1, 2026, the production of premixed polyols and polyurethane products using HCFC-141b as the blowing agent is prohibited, except for spray polyurethane foam products; from July 1, 2026, the production of spray polyurethane foam products using HCFC-141b as the blowing agent will also be prohibited.
This means premixed polyols and most polyurethane products have already entered the ban stage, while spray rigid foam is about to exit its final transition window. For the industry, this is not simply a matter of switching to another blowing agent; it is a system-wide adjustment affecting formulations, production, construction practices and customer compliance requirements.
1. Policy Deadline Nears: Spray Rigid Foam Enters Its Final Transition Window
In terms of policy timing, January 1, 2026 was the first threshold, mainly targeting premixed polyols and polyurethane products that use HCFC-141b as the blowing agent. In principle, premixed-polyol producers, rigid-foam product manufacturers and related polyurethane product companies other than spray foam can no longer continue using HCFC-141b as a blowing agent in production.
The July 1 deadline mainly targets spray polyurethane foam products. Unlike factory-made rigid-foam boards, pipe shells and other products, spray rigid foam is often formed on site. Its applications include building insulation, cold-storage insulation, fishing-vessel insulation, roof waterproofing and insulation, warehouse insulation and some pipeline insulation. Because construction participants are more dispersed, project scenarios are more complex and regulatory chains are longer, the policy previously granted a longer transition period.
Starting July 1, however, this transition window will also close. Spray polyurethane foam products using HCFC-141b as the blowing agent will then be banned from production. For spray-construction companies, premixed-polyol suppliers and downstream project customers, compliance requirements will shift from “gradual switching” to “mandatory switching.”

Figure 1: Key Timeline for the HCFC-141b Ban
2. The Impact Goes Beyond Blowing Agents: Rigid Foam Systems Will Re-segment
HCFC-141b has historically been widely used in PU rigid foam, mainly because of its foaming effect, thermal-insulation performance, process adaptability and cost advantages. However, a rigid-foam system usually consists of premixed polyols, isocyanates, blowing agents, catalysts, flame retardants and surfactants. Once the blowing agent changes, cell structure, thermal conductivity, dimensional stability, flame-retardant performance, construction window, spray adhesion and curing speed may all change accordingly.
Therefore, companies can hardly complete the upgrade by simply replacing HCFC-141b with another blowing agent. They need to readjust formulation systems and construction parameters. Current substitution routes available to the industry include water-blown systems, hydrocarbon blowing agents, HFCs and HFOs. These routes differ in environmental attributes, cost, equipment requirements, safety management and performance stability.
Water-blown systems and some hydrocarbon routes have relative cost advantages, but they place higher demands on formulations, equipment and on-site safety management. Low-GWP routes such as HFOs have stronger environmental attributes but higher costs, making them more suitable in the near term for customers with higher requirements for performance, certification and export compliance. Although HFCs are not ODS, they have already entered a longer-term greenhouse-gas control framework, so companies cannot evaluate substitution routes based only on immediate cost.
This also means the impact of the ban may not necessarily appear as a sudden increase in rigid-foam demand. It is more likely to show up as a re-segmentation of the market structure. Companies with formulation R&D capabilities, experience applying substitute blowing agents, testing capabilities and compliance-document management will be better positioned to take high-standard orders. Smaller companies that compete mainly on low prices and low compliance costs may face greater operating pressure.

Figure 2: Transmission Path of the HCFC-141b Ban Through the PU Rigid Foam Value Chain
From a cost perspective, substitute blowing agents, formulation validation, equipment adaptation, construction training and testing certification will all raise overall costs. However, this cost pressure may not be fully passed downstream. Demand for building insulation, cold-storage construction, insulated pipelines and some industrial insulation is still affected by real estate, infrastructure schedules, investment appetite and project-payment cycles, and end customers remain price-sensitive.
A more realistic judgment is therefore that the ban itself may not significantly expand total rigid-foam demand, but it will change order structure and profit distribution. Products that are highly compliant, high-performing and traceable may gain stronger bargaining power, while low-priced, opaque products that cannot prove the source of their blowing agents may gradually be excluded from key projects, branded customers and standardized construction scenarios. Environmental regulation will not create demand out of thin air, but it will raise the threshold for entering order systems.
3. Corporate Response Priorities: From Inventory Switching to a Closed Compliance Loop
Premixed-polyol companies are a critical link in this adjustment. Downstream foam companies and construction firms do not necessarily purchase single-component blowing agents directly; instead, they buy premixed-polyol systems that already contain the blowing agent. As a result, premixed-polyol companies are not only formulation providers but also key nodes in the chain of compliance responsibility.
After July 1, the room for HCFC-141b-containing systems to continue flowing into the spray-foam sector will basically close. Premixed-polyol companies need to focus on three issues: first, how to compliantly dispose of existing HCFC-141b-containing inventory; second, whether substitute blowing-agent systems can meet downstream construction and performance requirements; and third, whether contracts, labels, quality-inspection reports, blowing-agent declarations and customer filing materials can form a complete closed loop.
The spray-construction side also needs to upgrade in parallel. The special feature of spray PU rigid foam is on-site formation: construction environment, temperature and humidity, spray thickness, equipment pressure and operator practices all affect final quality. After blowing-agent substitution, construction companies need to become familiar with the operating window of the new system to avoid foam shrinkage, hollow spots, fluctuations in thermal performance, insufficient interlayer adhesion or higher on-site losses.

Figure 3: Response Checklist for Premixed-Polyol and Rigid-Foam Companies Before July 1
In the short term, companies should focus on three tasks: first, complete inventory checks as soon as possible, distinguishing standalone HCFC-141b, HCFC-141b-containing premixed polyols, orders in transit and project inventory; second, complete substitute-system validation and verify performance across scenarios such as cold storage, building insulation, fishing-vessel insulation and pipeline insulation; and third, improve compliance-document management by retaining procurement, sales, filing, test reports, blowing-agent declarations and contract clauses to reduce subsequent traceability risk.
Overall, the HCFC-141b ban entering the July 1 countdown marks a more thorough stage of blowing-agent substitution in the PU rigid foam industry. In the short term, it may bring higher costs, formulation adjustments and construction-adaptation pressure. In the long term, however, it will push the industry away from low-price competition and toward competition based on technology, compliance and service capabilities.
The PU rigid foam market may not expand rapidly because of one ban, but the rules of competition are changing. After July 1, rigid-foam companies will compete not only on price, but also on whether they can prove their products are more environmentally friendly, more stable and more compliant. This may be the deepest impact of the HCFC-141b ban on the polyurethane industry.
Sources: Ministry of Ecology and Environment Announcement No. 28 of 2025 and related policy Q&A; China Polyurethane Industry Association, Regulations on Ozone-Depleting Substances and Compliance Operations for Polyurethane Enterprises.
March 10, 2026
BASF introduces biomass balance polyether polyol product portfolio for the sleep products, automotive and CASE industries
WYANDOTTE, MI – MARCH 10, 2026 – BASF has announced the first commercial production of its biomass balance (BMB)[1]polyether polyols in North America, manufactured at the company’s Verbund site in Geismar, Louisiana. The new product line broadens BASF’s portfolio of sustainable polyurethane raw materials and represents a significant milestone in advancing the company’s sustainability goals.
The BMB polyether polyols are certified under the internationally recognized ISCC PLUS certification[2], ensuring full traceability and verification of sustainable biomass inputs across the value chain. Using the biomass balance approach, BASF replaces a share of fossil-based feedstocks at the beginning of the production process with renewable, bio‑circular materials, while maintaining identical product quality and performance compared with conventional polyether polyols.
Polyether polyols play a central role in polyurethane chemistry. They are a primary raw material that reacts with isocyanates to create polyurethane polymers. BASF’s biomass balance polyols provide a drop‑in solution that helps customers reduce the product carbon footprint (PCF) of flexible foam formulations used in countless industrial applications. Because BMB products retain the same specifications and processing characteristics as their fossil-based counterparts, manufacturers can adapt quickly without operational disruption.
“Expanding our BMB portfolio to include polyether polyols produced in Geismar further strengthens the trust our customers place in BASF to deliver reliable, sustainable solutions,” said Stefan Doerr, BASF Senior Vice President, Monomers North America. “Customers in the sleep products, automotive, and CASE industries can transition to these new solutions without any reformulation or process changes – making the shift both seamless and immediately actionable.”
BASF’s Monomers division continues to advance an ambitious sustainability roadmap, including the development of low‑PCF and circular product options across its major product lines. The launch of ISCC PLUS-certified BMB polyether polyols in North America complements the division’s existing BMB isocyanate offerings and reinforces BASF’s integrated approach to more sustainable polyurethane systems.
To learn more about BASF’s Biomass Balance portfolio and certification process, please visit us at https://chemicals.basf.com/north-america/en/Monomers/isocyanates-and-polyols/about-us/sustainability
[1] Biomass balance method (BMB): Fossil raw materials required for the manufacture of BASF products are replaced with renewable feedstock along the integrated production chain. The corresponding share of renewable material is attributed to the specific sales product via a certified mass balance approach. Production methods of this kind save fossil resources and reduce CO2 emissions at the same time. Renewable feedstock is not traceable in the BASF product.
[2] ISCC PLUS is a sustainability certification scheme for the use of sustainable biomass as raw material in the chemical industry. A certification according to this certification scheme confirms that the biomass used is sustainable and has been fed into the production system in the required amount. It also confirms that the sustainable biomass has been correctly attributed to the corresponding sales products. The certification is awarded on the basis of on-site audits conducted by independent auditors.
source: https://www.basf.com/us/en/media/news-releases/2026/03/P-US-26-11
January 7, 2026
AI Use in Logistics
How is C.H. Robinson using AI? Its CFO has a story to tell
Lee talks about what 2 of its 30 agentic tools are doing at the 3PL that has Wall Street abuzz
· Tuesday, January 06, 2026

Key Takeaways:
There are two numbers that might help define the impact of AI at 3PL giant C.H. Robinson.
One of them is 55.3%. That’s the growth in the company’s stock price during 2025. There are no other logistics companies that had a record like that in the recently-completed year. Every analyst would say AI is a key part of that surge.
The second is 30. That’s the number of actual agentic AI tools in use at C.H. Robinson.
Damon Lee, the company’s CFO, reviewed C.H. Robinson’s use of AI in a recent interview with FreightWaves. Lee’s comments moved away from the general message on AI usage that C.H. Robinson (NASDAQ: CHRW) has been touting–with profitability and operational figures to back it up–to more specific details on what the company is using AI to get done.
It’s impossible to know if 30 is a large number or a small one. There is no measuring stick for how many agentic AI tools a freight brokerage that will produce 2025 revenue somewhere close to $11 billion should have at this stage in the AI revolution.
But the verdict from investors seems to be that 30 is a good number, they like the results and are hoping for more in 2026.
Lots of companies read invoices
At the annual meeting of the Transportation Intermediaries Association in April, a parade of companies touted their freight tech applications at a day-long session with journalists. Most of them talked about AI, but the message at one point became sort of repetitive: we use AI to read invoices or take an incoming call and convert it to language-based data that a broker could use.
The reality is that many companies across the spectrum of industries–not just logistics–that have plunged into AI aren’t seeing benefits, at least not yet.
That isn’t surprising to Lee. “I believe people using an off-the-shelf solution for AI, in many cases, will be nothing but a cost adder for their business,” he said. “I don’t think they’ll ever see positive productivity to offset the cost that they’re incurring, because the pay-by-the drink model of AI is very expensive.”
450 men and women at work
That’s why C.H. Robinson has a team of 450 engineers writing their own AI applications. They are the source of the 30 agentic AI tools cited by Lee.
“We’re using bespoke customized AI solutions to drive demonstrable business results,” Lee said.
Lee spoke about one of the 30 agentic AI solutions in going from the theoretical to the specific.
C.H. Robinson receives requests for about 600,000 rate quotes each year at its North American Surface Transport (NAST), the division that includes its core over the road brokerage activities.
Historically, it had the ability to respond to about 60% to 65% of those quotes, Lee said.
“So when a person was manually doing that exercise, somewhere around a third of those requests either never got answers, or they got answered in a timeline that didn’t meet the customer expectations,” Lee said.
With an agentic AI tool now at the center of the process for responding to those requests, Lee said C.H. Robinson is able to respond to 100% of the queries.
“I’m now getting to a third of the universe of freight that was available to me before that I never got to,” Lee said. “The sophistication in how I’m responding to the customer has gone up exponentially.”
A human might have five to 10 data points to use in responding to a quote. But the agentic AI tool, Lee said, has “tens of thousand if not hundreds of thousands of data points available to them.”
The price quote from the human would be “unsophisticated,” Lee said. Response time was 17 to 20 minutes.
But Lee said the agentic AI tool will respond in 32 seconds.
Optimizing margin rapidly
Asked to describe “favorite AI agent number two,” Lee turned to a tool he said is designed to optimize revenue management.
Pricing strategy at C.H. Robinson, Lee said, would be “fairly unsophisticated. It was targeted to figure out ‘I want to try to get this much margin, or this much volume, at this much margin.’”
If the gross margin rate in that strategy is 40%, loads are accepted or rejected on that basis, Lee said. “At the end of the month or the quarter, I see how my pricing strategy did,” he said.
What he described as “course correction” in the middle of that strategy wasn’t easy, according to Lee.
With the strategy now being powered by an in-house developed agentic AI tool, “we’ll set a pricing strategy at 8 a.m. on Monday, and by 8:05, we’re testing that strategy,” Lee said. The tool asks the question, “is the strategy yielding the volume and the margin that I expected to get?”
And if the answer is no, Lee said, “it will change the strategy two minutes later.” That replaces a system, Lee said, where “you might have a 30-day increment with no adjustments, or even a 90-day increment with no adjustments.” In its place, Lee said, is an approach where “the strategy gets adjusted hundreds of times a day.”
Lee referred to that model as “gross margin arbitrage.” Previously, Lee said, playing that strategy was largely impossible.
“Folks would say gross margin is commoditized,” Lee said, defining gross margin as a formula of revenue per load minus the cost of capacity. “But we’re able to optimize price, and we’re able to optimize cost because of the frequency in which we’re able to test the market and react to the market in terms of price,” he said.
If the data coming from the agentic AI tool is showing “volume coming in hot, I can choose to optimize margin,” Lee said. But if “there’s not as many loads on the market, I can get more aggressive in price.”
That’s what every broker does. But C.H. Robinson’s message is they can do it far more rapidly because of AI.
C.H. Robinson does not disclose gross margin in its earnings. It’s a derivative of adjusted gross profits, which are published with the company’s earnings.
The most recent earnings report shows that in the three months ended September 30, C.H. Robinson’s adjusted gross profit in its truckload brokerage was down 2% year-on-year. That is a relatively small drop considering the freight market in 2025 compared to the already weak one in 2024.
But the 3PL’s adjusted gross profits in its LTL operations were up 10.5%. For the nine months, the figures were down 0.9% in truckload and up 6.7% in LTL
Not everybody is buying the C.H. Robinson story. For example, data on Yahoo Finance shows a 6.47% share of the company’s stock float was sold short as of December 15. That is a relatively high number.
The question is whether C.H. Robinson’s price has surged because it’s a brokerage play–hard to imagine that, given the performance of other 3PLs like RXO (NYSE: RXO) and Landstar (NASDAQ: LSTR)–or an AI play. Lee wouldn’t say it wasn’t because of brokerage, but he said “we’ve had a few investors tell us we may be the only company that is getting the level of benefits from AI that we’ve enjoyed in this ecosystem.”
Within the AI play, Lee said there are chip makers and data centers and other companies whose stocks are more of a pure AI play.
What are harder to find are the operating beneficiaries, Lee said, “examples of folks that are winning at the application layer. And that’s certainly where C.H. Robinson is winning.”
November 19, 2025
BASF to License Technology
BASF PolyTHF® technology now available for licensing
BASF will start offering state-of-the-art polytetrahydrofuran (PolyTHF®) 1800 production technology licenses to clients and partners. As a global leader in PolyTHF technology development, BASF operates three major production sites worldwide: Caojing in China, Ludwigshafen in Germany, and Geismar in the United States.
Franky Ruslim, Vice President, Global Technology Head, Intermediates Business, BASF
“In today’s fiercely competitive world, innovation is no longer optional but essential. By opening our PolyTHF 1800 patented technology for licensing, we are committed to driving new growth in industries like textiles, reshaping collaboration models, and creating value for both our clients and BASF.”
Zhai Yabi, Strategic, Project & Licensing Director, Asia Pacific, Intermediates Business, BASF
“Licensing our proven technology provides an attractive value proposition to clients and partners in the market, allowing them to access innovation, reduce R&D costs, and accelerate time-to-market for quick wins.”
PolyTHF is a key raw material for producing spandex elastic fibers, widely used in swimwear, sportswear, underwear, shirts, and stretch jeans. The elastic fibers maintain long-lasting wearing comfort while also providing moisture resistance and antibacterial properties. PolyTHF® is a registered trademark of BASF.
https://www.ccfgroup.com/newscenter/newsview.php?Class_ID=600000&Info_ID=2025111930007
October 22, 2025
The World We Live In
The AWS Outage Bricked People’s $2,700 Smartbeds
· Oct 22, 2025 at 9:40 AM
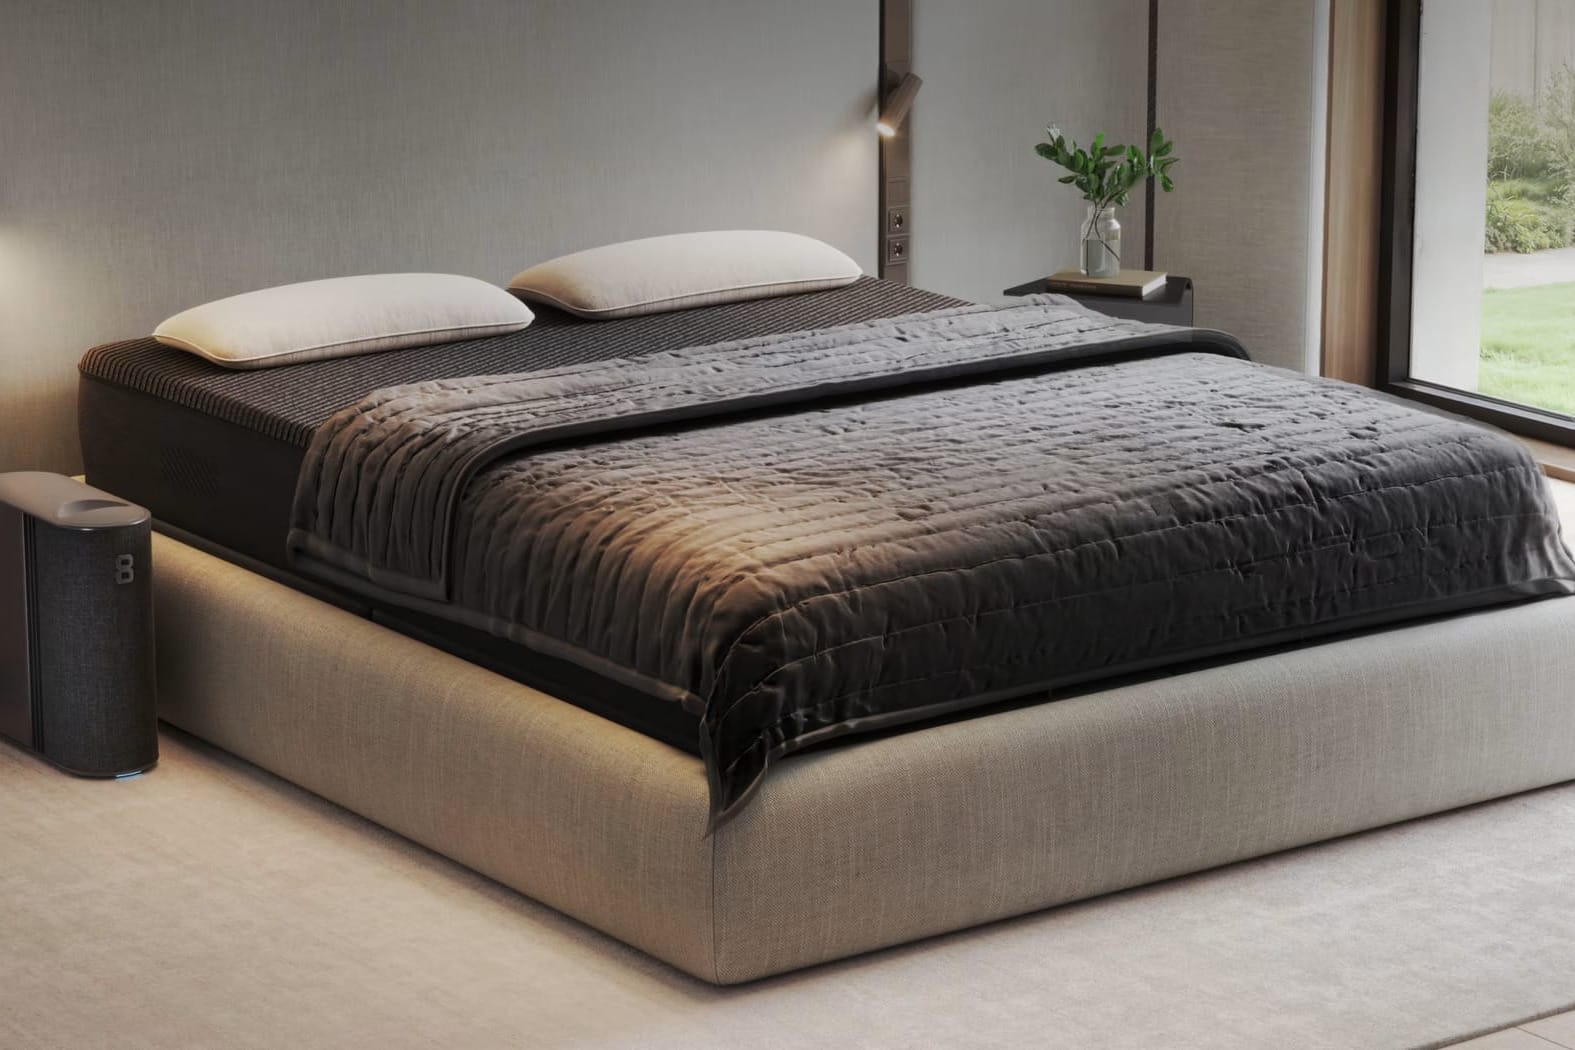
When Amazon Web Services went offline, people lost control of their cloud-connected smart beds, getting stuck in reclined positions or roasting with the heat turned all the way up.
Read More Here:
https://www.404media.co/the-aws-outage-bricked-peoples-2-700-smartbeds
 Everchem Updates Archive
 Sign Up for Email Updates