
Company News
November 18, 2026
OlinHuntsman Business Structure
Olin and Huntsman Announce Business Structure for OlinHuntsman, Designed to Deliver Higher Value and Growth
Download as PDFNovember 17, 2026 9:00am EST
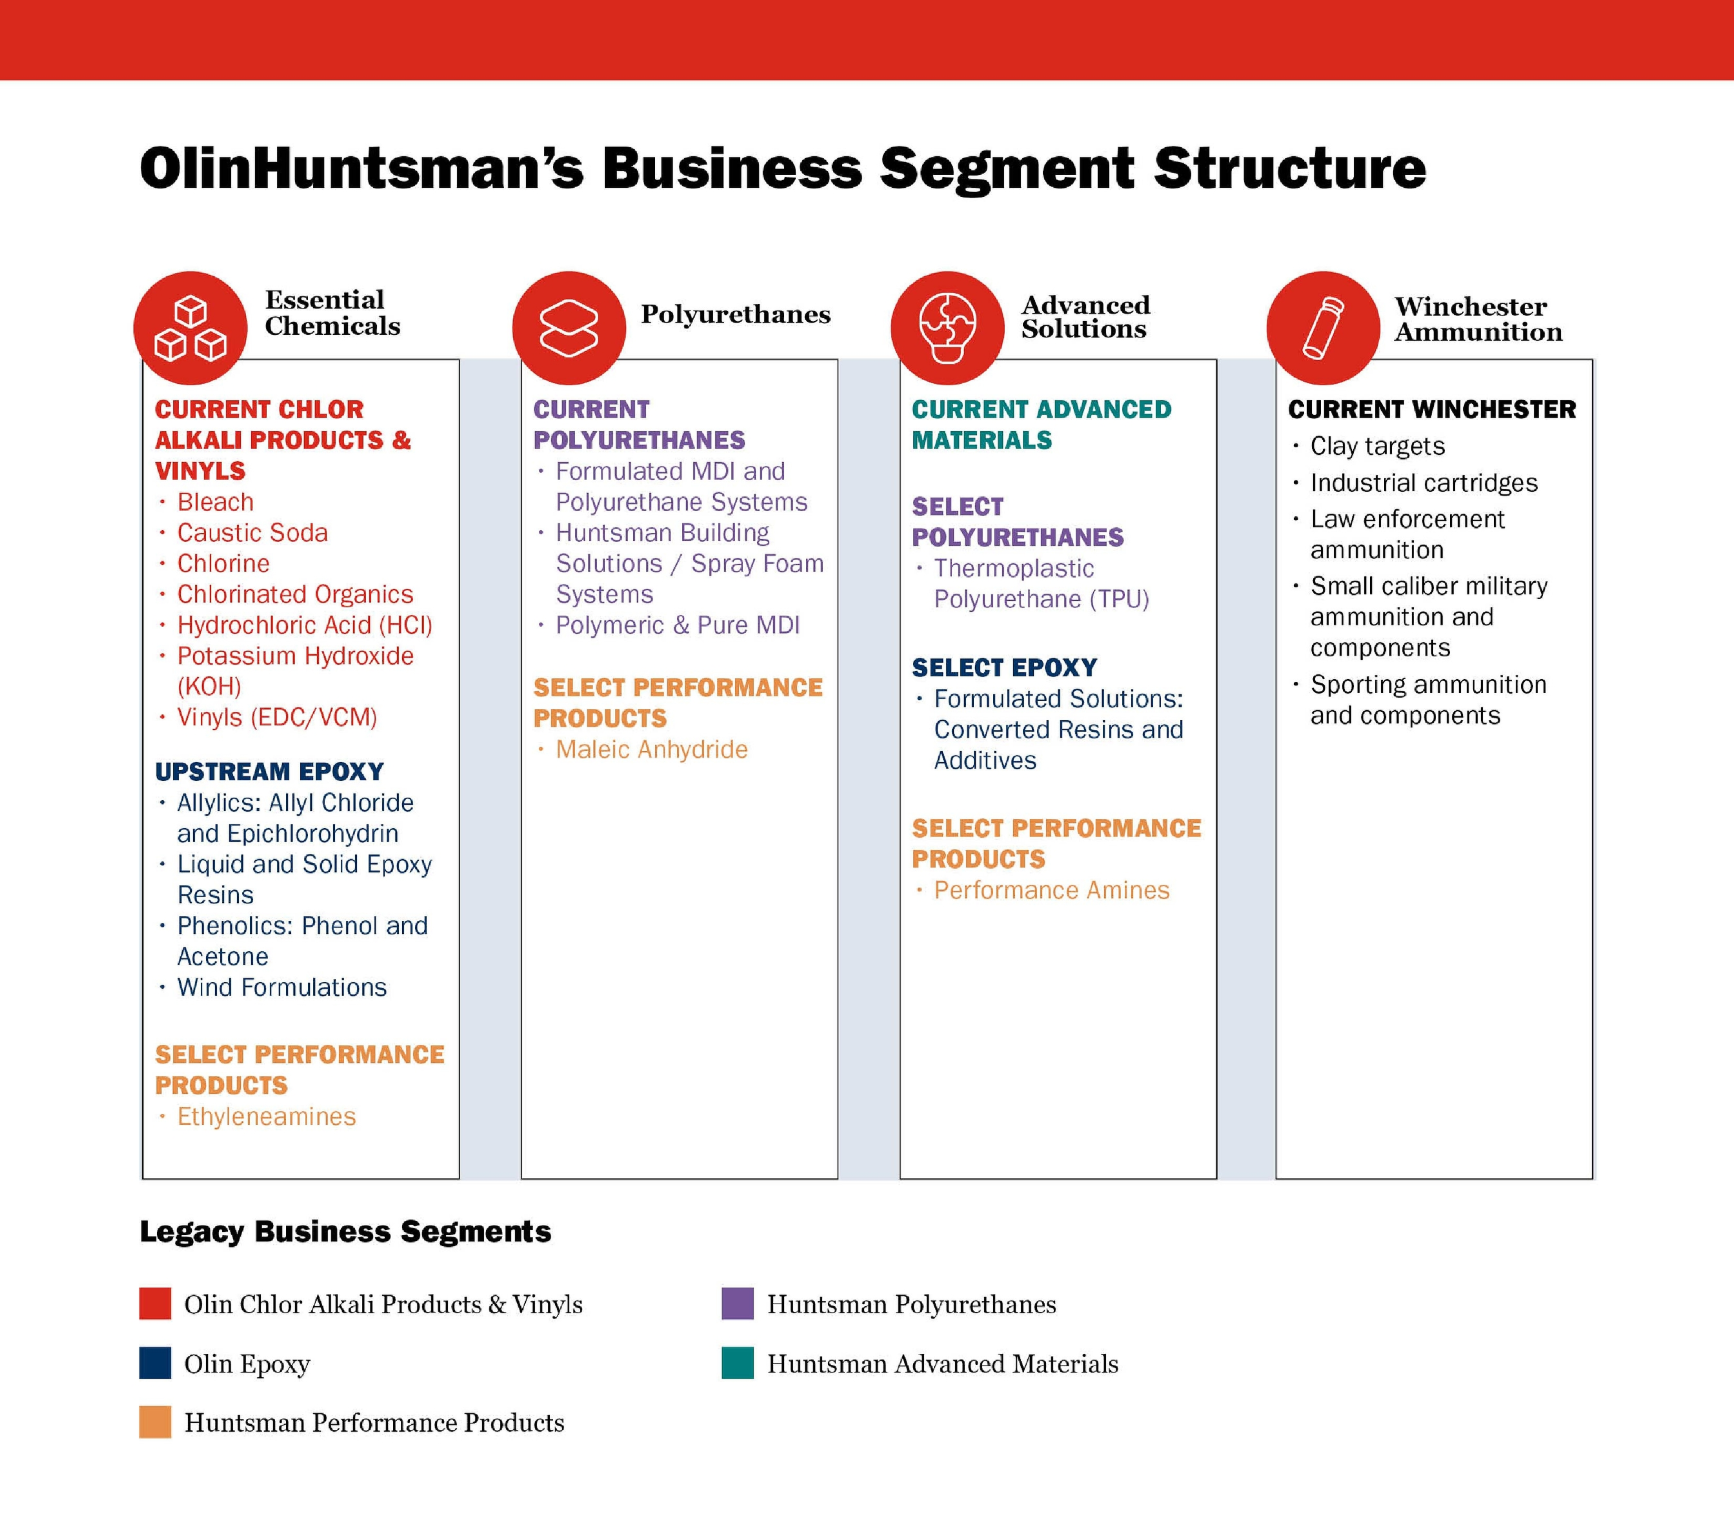
Upon transaction close, the combined company will operate through Essential Chemicals, Polyurethanes, Advanced Solutions and Winchester, and will trade under the ticker symbol OHN
CLAYTON, Mo. and THE WOODLANDS, Texas, Nov. 17, 2026 /PRNewswire/ — Olin Corporation (NYSE: OLN) and Huntsman Corporation (NYSE: HUN) today announced the segment structure and leadership expected to guide the combined company, OlinHuntsman Corporation, upon the closing of the previously announced merger between Olin and Huntsman.
“I am very confident this new company and the leadership we are announcing today will surpass the needs of an evolving chemicals landscape and become an industry leader,” said Ken Lane, President and Chief Executive Officer of Olin, who will serve as President and Chief Executive Officer of OlinHuntsman. “We are designing and building a new organization with proven leaders that will drive value across all of our businesses.”
This new company, OlinHuntsman, will operate under a four-division structure designed to leverage vertical integration and complementary capabilities across the portfolio, from world-scale, cost-competitive, essential chemicals to downstream businesses focused on profitable growth and innovation for customers. By simplifying the organization and strengthening connections across the value chain, the new structure positions OlinHuntsman as a cost leader in all businesses.
Deon Carter has been named Senior Vice President and President, Essential Chemicals, which represents approximately 40% of the combined companies’ 2025 sales. This segment will include Olin’s existing Chlor Alkali Products and Vinyls and upstream Epoxy businesses, along with the Ethyleneamines business from Huntsman’s Performance Products segment. By integrating global-scale chlorine and caustic soda production with these additional major chlorine derivatives, Essential Chemicals will deliver disciplined cost management and stronger cash generation. This integrated platform positions OlinHuntsman as an industry-leading, low-cost producer across a broader portfolio of chlorine derivatives.
Steen Weien Hansen has been named Senior Vice President and President, Polyurethanes, which represents approximately 30% of the combined companies’ 2025 sales. This segment will include Huntsman’s existing Polyurethanes segment (excluding Thermoplastic Polyurethanes) and Huntsman’s Maleic Anhydride business, which currently operates within Huntsman’s Performance Products segment. The Polyurethanes segment will be a global integrated leader and growth platform focused on operational excellence and select innovation using its versatile chemistry to deliver value-adding solutions. Starting in 2031, it will benefit from integrated chlorine supply from the Essential Chemicals segment.
Scott Wright has been named Senior Vice President and President, Advanced Solutions, which represents approximately 15% of the combined companies’ 2025 sales. This segment will combine Huntsman’s Advanced Materials, Thermoplastic Polyurethanes and Performance Amines businesses with Olin’s Epoxy Formulated Solutions business. Together, these businesses combine a broad range of technologies and application expertise, creating the innovative breadth to develop customer-focused solutions, accelerate margin growth and generate greater value. Advanced Solutions is backed by vertical integration across the Essential Chemicals and Polyurethanes segments, which supply best-in-class, reliable, cost-advantaged feedstocks.
Brett Flaugher has been named Senior Vice President and President, Winchester, which represents approximately 15% of the combined companies’ 2025 sales. As the industry leader in small caliber ammunition and the largest supplier of small caliber ammunition to the U.S. military, Winchester will continue to provide U.S. and international military ammunition and components, sporting ammunition, law enforcement ammunition, White Flyer clay targets and U.S. military project oversight. Winchester will build on its strong 160-year-old leading brand and deep customer relationships while applying the same focus on safety, performance and disciplined management.
The combined company is being designed around industry-leading benchmarks, building a lean, efficient company focused on the essential operations that create value for our customers, shareholders, and team members. We are also introducing an Enterprise Services group to accelerate the capture of integration and synergy benefits by centralizing supply chain, procurement, and IT for the chemicals businesses. The organizational design of the combined company will be data-driven, with clear lines of accountability and incentive programs that drive results.
As previously announced, Phil Lister will serve as Chief Financial Officer of OlinHuntsman and Todd Slater will serve as Chief Integration Officer.
“The new company’s operating structure and pre-closing integration planning positions us to ensure day one readiness and begin to capture $400 million of cost synergies and integration benefits immediately following closing,” said Lane. “This is the right team of leaders who bring the experience and passion to deliver on our priorities: operating safely, serving our customers and delivering long-term value to our shareholders.”
The new structure will take effect upon closing of the transaction, which is anticipated to occur early in the first quarter of 2027, subject to the satisfaction of customary closing conditions. Upon closing, shares of OlinHuntsman common stock will trade under the OHN ticker symbol.
APPENDIX
DIVISION LEADER BIOS
Deon Carter, Senior Vice President, and President Essential Chemicals: Deon Carter currently serves as Vice President and President, Chlor Alkali Products & Vinyls at Olin Corporation. Before joining Olin in June 2024, he served as Chief Operating Officer of Continental Industries Group since April 2023.
Brett Flaugher, Senior Vice President, and President Winchester: Brett Flaugher is currently the Vice President and President of Winchester at Olin Corporation. As a recognized leader in the commercial and military ammunition industry, Flaugher will continue to lead Winchester’s 160-year-old established brand and strong customer relationships in the new combined company.
Steen Weien Hansen, Senior Vice President, and President Polyurethanes: Steen Weien Hansen currently serves as Division President, Polyurethanes at Huntsman. Hansen was appointed to this position in June 2025. Prior to that time, he served as Senior Vice President for the Americas region, as well as Global Automotive and Global Elastomers for the Polyurethanes Division. Hansen has held several other leadership roles within the Huntsman organization since joining the company in 1999.
Scott Wright, Senior Vice President, and President Advanced Solutions: Scott Wright currently serves as Division President, Advanced Materials at Huntsman, a position he’s held since 2016. Prior to that time, Wright served as Vice President of Huntsman Advanced Materials – Europe, Africa and the Middle East. Before joining the Advanced Materials division, Wright spent 15 years in Huntsman’s Pigments division where he held several leadership roles.
November 12, 2026
BASF Inaugurates New MDI Plant
BASF inaugurates new $1 billion MDI production facility at its Geismar Verbund site
- BASF’s largest single investment made to date in the U.S.
- BASF becomes largest MDI producer in North America
- Customers benefit from reliable and local integrated supply
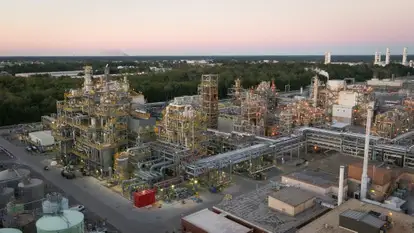
BASF today celebrated the inauguration of its new methylene diphenyl diisocyanate (MDI) production facility at the company’s Verbund site in Geismar, Louisiana. The ceremony marks the on-time completion of BASF’s largest wholly owned investment project to date in North America with a total volume of approximately $1 billion. The expansion almost doubles the annual MDI production capacity at the Geismar site to approximately 600,000 metric tons.
“The United States has long been a key market for BASF, and this $1 billion investment is a strong commitment to our customers and to our future here. With our new world-scale MDI facility in Geismar, we are strengthening our core businesses, driving innovation and bringing more production closer to our customers,“ said Dr. Markus Kamieth, Chairman of the Board of Executive Directors of BASF SE. “I am particularly proud that our team has delivered this complex project on time and want to thank everyone who made it possible.”
MDI is a key raw material used in the production of polyurethanes, a high-performance plastic contributing to energy efficiency, durability and performance in a wide range of applications. The additional production capacity in Geismar will support the long-term growth of BASF’s customers in applications including construction, appliances, transportation, automotive, footwear, furniture and other polyurethane-based industries.
“This significant investment reflects our confidence in the continued growth of the polyurethane market and ensures that our customers benefit from a highly reliable, competitive and locally integrated supply source for years to come. With this expansion BASF is taking the lead in MDI production in North America,” said Ramkumar Dhruva, President of BASF`s Monomer Division.
The project was executed in three phases beginning in 2018. A new MDI synthesis unit was commissioned in 2020, followed by expansions of several upstream units in 2021. The final phase included new upstream units and a splitter, incorporating state-of-the-art technology, advanced digitalization and the highest safety standards. The additional capabilities increase production flexibility and strengthen BASF’s reliable and competitive supply of MDI in North America. As part of the expansion, BASF also increased its aniline production capacity in Geismar, strengthening the site’s integrated value chain and creating additional availability to serve North American customers in the agricultural chemicals, rubber and dyes and pigments industries.
The Geismar site in Louisiana is BASF’s largest Verbund site in the United States, benefiting from integrated infrastructure, reliable raw material supply and operational synergies. BASF has a strong local footprint in the United States with more than 150 locations across 40 states. In 2025, approximately 90% of the €13.1 billion sales came from products manufactured in the country.
You can find more information and the latest photos on this website:
https://www.basf.com/global/en/media/news-releases/2026/11/p-26-194
November 10, 2026
Somnigroup Q3 Call Highlights
Somnigroup projects 2026 adjusted EPS of $2.85-$2.95 while targeting more than 2,500 Mattress Firm stores
Nov 09, 2026, 5:02 PM ETSomnigroup International Inc. (SGI) StockAI-Generated Earnings Calls Insights
Earnings Call Insights: Somnigroup International Inc. (SGI) Q3 2026
Management View
- “Although a bit below our expectations, we are pleased to report that in the third quarter, against a cautious consumer backdrop and ongoing macroeconomic uncertainties, we delivered record net sales of $2.4 billion, record adjusted EBITDA of $448 million and record adjusted EPS of $1.04 a share” (Chairman of the Board, CEO & President Scott Thompson).
- “Our first highlight is the successful combination of Leggett & Platt in late August” and “The combination brings together Leggett & Platt’s deep expertise in component engineering with Somnigroup’s scale” (Chairman of the Board, CEO & President Thompson).
- “Dreams experienced an unexpected decline in reported sales of approximately 35%” and “All in all, we estimate the cost of about $50 million in sales and $25 million in adjusted EBITDA versus prior year” (Chairman of the Board, CEO & President Thompson).
- “We see a compelling opportunity to begin in 2027 to leverage Mattress Firm’s proven retail model… to pursue a disciplined multiyear store expansion strategy” and “We see the opportunity to grow over time, our Mattress Firm store count, to more than 2,500 locations” (Chairman of the Board, CEO & President Thompson).
- “Going forward, we will report results across 3 channels: direct bedding, wholesale bedding and furnishings; and specialized products” (Executive VP & CFO Bhaskar Rao).
- “In the third quarter of 2026, consolidated sales were a record $2.4 billion, and adjusted earnings per share was $1.04” and “we delivered robust operating cash flow of $349 million and free cash flow of $290 million” (Executive VP & CFO Rao).
Outlook
- “We expect adjusted earnings per share to be between $2.85 and $2.95 for the full year” and “This guidance range contemplates a sales midpoint of approximately $8.65 billion after intercompany eliminations” (Executive VP & CFO Rao).
- “Our annual guidance also reflects our updated expectation that the global bedding industry will be down mid-single digits in the back half of the year” (Executive VP & CFO Rao).
- “The Tempur Sealy North America like-for-like sales are flattish” and “International business sales are flattish with expected sequential improvement in Dreams trends from the third to fourth quarter” (Executive VP & CFO Rao).
- “Like-for-like Mattress Firm sales down low-single digits” and “for like-for-like Leggett sales in the fourth quarter to be approximately $875 million after intercompany elimination” (Executive VP & CFO Rao).
- “Regarding capital expenditures, we expect ’26 CapEx of approximately $255 million” and “We expect CapEx to normalize to $300 million in future years” (Executive VP & CFO Rao).
- “If something doesn’t change… then I would anticipate that we would have a price increase sometime in the first half of next year” (Chairman of the Board, CEO & President Thompson).
Financial Results
- “Mattress Firm adjusted gross margins decreased 100 basis points to 34.6%” and “Mattress Firm adjusted operating margins increased approximately 20 basis points to 9.6%” (Executive VP & CFO Rao).
- “Net sales through Leggett were $373 million in the third quarter” and “For the full quarter… Leggett sales were $973 million on a like-for-like basis” (Executive VP & CFO Rao).
- “Turning to Tempur Sealy North America. Sales declined 4% on a like-for-like basis” and “North America adjusted gross margins increased… to 65.5%” (Executive VP & CFO Rao).
- “International net sales declined 12%… largely due to transitory ERP disruptions at Dreams” and “Our international operating margin declined 870 points to 9.4%” (Executive VP & CFO Rao).
- “At the end of the third quarter, consolidated debt less cash was $5 billion, and our leverage ratio was 2.7x” (Executive VP & CFO Rao).
Q&A
- Susan Maklari, Goldman Sachs Group, Inc., Research Division: “Can you talk about how the business performed… and what that could mean… into 2027?” Chairman of the Board, CEO & President Thompson: “third quarter started relatively weak, then improved” and “I can’t say we’ve seen anything significant” post-election.
- Pedro Gil Garcia Alejo, Morgan Stanley, Research Division: asked whether Stearns & Foster weakness was retailers waiting for new product. Chairman of the Board, CEO & President Thompson: “Stearns & Foster launch is going well to what I call very well” and “there is some weakness that you would expect” as retailers “burn through the old stock.” Executive VP & CFO Rao: “it’s about 6% lift from a slot standpoint.”
- Robert Griffin, Raymond James & Associates, Inc., Research Division: asked what changed vs. two months ago and an EPS bridge to 2027. Chairman of the Board, CEO & President Thompson: “call it a run rate exit that we’re targeting for ’27 of $3.40” and “we’re still kind of tracking to the $5.15.” Executive VP & CFO Rao: “Dreams was worse than expected” (“about $25 million of EBITDA”) and transportation inflation “about $15 million.”
- Rafe Jadrosich, BofA Securities, Research Division: asked about price/cost and additional pricing. Chairman of the Board, CEO & President Thompson: “we’re incurring some extra costs that we have not passed on” and “it’s likely” price increases in “the first half of next year.” Executive VP & CFO Rao: described losing an expected “$10 million benefit” and “incurred a bit on top of it.”
- Michael Lasser, UBS Investment Bank, Research Division: asked about affordability, imports, and how to sensitize models around $3.40. Chairman of the Board, CEO & President Thompson: “no, there’s no evidence that we have imports flooding” and “we are not seeing any issues… where closing rates are declining.” Executive VP & CFO Rao: “a point of industry growth would give us about $0.10” of EPS.
- Bradley Thomas, KeyBanc Capital Markets Inc., Research Division: asked about scale risk, non-Mattress Firm channel, and Leggett customer retention. Chairman of the Board, CEO & President Thompson: “we held share” in “other other” and “I haven’t seen any issues in customer churn” at Leggett.
- Peter Keith, Piper Sandler & Co., Research Division: asked about AI search and ad spend. Chairman of the Board, CEO & President Thompson: “we’ve noticed it… and are working on it” and “advertising spend… moves around with demand and efficiency.” Executive VP & CFO Rao: Dreams is “managing advertising to just manage the customers’ expectations.”
- Marius Morar, Zelman & Associates LLC: asked about Mattress Firm online softness. Chairman of the Board, CEO & President Thompson: “they’ve underperformed” and “we’ve overdone it” shifting spend, and “we’re pivoting back”; “more recently… online sales have improved.”
- Jonathan Matuszewski, Jefferies LLC, Research Division: asked what “modest” store growth means and why now. Chairman of the Board, CEO & President Thompson: “The store count has drifted down” while the company studied real estate, and now “we are very comfortable”; “the opportunity is more like 2,500.”
- Phillip Blee, William Blair & Company L.L.C., Research Division: asked about ASP lift and cross-marketing from Stearns & Foster launches. Executive VP & CFO Rao: “you’re going to get some ASP increase” and the heritage line is “a halo project.” Chairman of the Board, CEO & President Thompson: “the retailers actually asked for it.”
Sentiment Analysis
- Analysts tone was slightly negative to neutral, with repeated pressure on demand drivers and guide changes, including “what changed versus 2 months ago” (Robert Griffin, Raymond James) and questions on affordability/imports (Michael Lasser, UBS).
- Management tone was slightly positive in prepared remarks (“This was the best performing quarter in the company’s history” (Executive VP & CFO Rao)) but more defensive on disruptions (“the near-term execution fell short of our plan” (Chairman of the Board, CEO & President Thompson)).
- Versus Q2, the tone shifted toward troubleshooting execution issues: Q2 described Dreams as an ERP rollout “that is going well, but has created some transitory challenges” (Chairman of the Board, CEO & President Thompson), while Q3 characterized it as an “outlier” with quantified sales/EBITDA impact.
Quarter-over-Quarter Comparison
- In Q2, Leggett & Platt was framed as a pending deal (“We’re expecting to close the transaction before the end of the third quarter” (Chairman of the Board, CEO & President Thompson)); in Q3, management presented it as completed (“successful combination… in late August” (Chairman of the Board, CEO & President Thompson)) with a new segment/channel reporting structure (Executive VP & CFO Rao).
- 2026 adjusted EPS guidance tightened lower: Q2 said “between $2.85 and $3.15” (Executive VP & CFO Rao) versus Q3 “between $2.85 and $2.95” (Executive VP & CFO Rao), with Q3 attributing the change to Dreams and transportation inflation in Q&A.
- Q2 described Dreams ERP as manageable (“at most, that’s maybe another 1 quarter” (Chairman of the Board, CEO & President Thompson)); Q3 reported the disruption drove an “unexpected decline” with expected normalization “in early first quarter 2027” (Chairman of the Board, CEO & President Thompson).
- Q3 added a specific strategic expansion target for Mattress Firm retail (“more than 2,500 locations” and “an average payback period per store of approximately 1.5 years” (Chairman of the Board, CEO & President Thompson)), while Q2 referenced being “back in store growth mode here pretty soon” without a numeric target.
Risks and Concerns
- “The headwinds were a bit more than we expected” and “the industry remains pressured” (Chairman of the Board, CEO & President Thompson), with management tying pressure to macro uncertainty and consumer confidence.
- “Dreams experienced an unexpected decline” after an ERP go-live that created “temporary operational disruption” and “poor customer satisfaction and lost orders” (Chairman of the Board, CEO & President Thompson), with mitigation described as “reallocated resources” and expected resolution “in early first quarter 2027.”
- “Transportation inflation” and petroleum-driven cost pressure were cited as a guidance headwind (Executive VP & CFO Rao), with management signaling potential pricing actions if costs persist (Chairman of the Board, CEO & President Thompson).
Final Takeaway
Management framed Q3 as a record quarter that incorporated the Leggett & Platt acquisition and introduced a new reporting structure, while also quantifying an unexpected Dreams ERP disruption and transportation inflation that narrowed full-year 2026 adjusted EPS guidance to $2.85-$2.95. The call emphasized near-term operational recovery at Dreams, a 2027 product cadence led by Stearns & Foster and the next-generation Tempur-Pedic Breeze, and a new multi-year Mattress Firm store expansion plan targeting more than 2,500 locations with an estimated ~1.5-year enterprise-wide payback per store.
October 29, 2026
BASF Q3 Results
BASF forecasts €7.4B-€7.8B 2026 EBITDA before special items while keeping €1.5B-€2.3B free cash flow range
Oct 28, 2026, 8:11 AM ETBASF SE (BASFY) Stock, BFFAF StockAI-Generated Earnings Calls Insights
Earnings Call Insights: BASF SE (BASFY) Q3 2026
Management View
- “Before we start the discussion of our Q3 results, I would like to address the possible combination of BASF and Evonik upfront.” (CEO & Chairman of the Board of Executive Directors Markus Kamieth) “A potential combination with Evonik would be a logical and meaningful step in this direction.” (CEO & Chairman of the Board of Executive Directors Kamieth) “We will only pursue a potential transaction if it is value accretive for our shareholders. We will not overpay.” (CEO & Chairman of the Board of Executive Directors Kamieth)
- “BASF delivered another strong quarter with considerable growth in EBITDA before special items driven by all core businesses.” (CEO & Chairman of the Board of Executive Directors Kamieth) “Disciplined capital allocation enabled us to further reduce net debt, strengthen our balance sheet and continue our share buybacks.” (CEO & Chairman of the Board of Executive Directors Kamieth) “The strong year-to-date performance of our core businesses gives us confidence to narrow our forecast range for EBITDA before special items upward.” (CEO & Chairman of the Board of Executive Directors Kamieth)
- “We divested the Decorative Paints business in 2025 and completed the transaction with Carlyle in 2026 at a combined multiple of 13x, resulting in net cash inflows of more than EUR 6 billion.” (CEO & Chairman of the Board of Executive Directors Kamieth) “The preparations for the planned IPO of Agricultural Solutions are on track, giving us confidence that the business will be IPO-ready by mid-2027.” (CEO & Chairman of the Board of Executive Directors Kamieth)
- “At EUR 6.4 billion, EBITDA before special items increased by more than EUR 900 million compared with the prior year period.” (CFO & Chief Digital Officer Dirk Elvermann) “Net income came in at EUR 5.2 billion, including the disposal gain of EUR 3.5 billion after tax from the Coatings transaction with Carlyle.” (CFO & Chief Digital Officer Elvermann)
Outlook
- “We expect EBITDA before special items of between EUR 7.4 billion and EUR 7.8 billion.” (CEO & Chairman of the Board of Executive Directors Kamieth) “Compared with our previous forecast, we have raised the lower end of the range and slightly increased the upper end.” (CEO & Chairman of the Board of Executive Directors Kamieth)
- “Given the continuing uncertainty surrounding further geopolitical and global economic developments and their impact on oil and gas prices, in particular, we maintain the forecast range for the free cash flow of between EUR 1.5 billion and EUR 2.3 billion.” (CEO & Chairman of the Board of Executive Directors Kamieth)
- Compared with the prior quarter, “we now anticipate EBITDA before special items of between EUR 6.9 billion and EUR 7.7 billion in 2026” (CEO & Chairman of the Board of Executive Directors Kamieth, Q2 2026) shifted to “between EUR 7.4 billion and EUR 7.8 billion” (CEO & Chairman of the Board of Executive Directors Kamieth, Q3 2026), while the free cash flow range stayed “between EUR 1.5 billion and EUR 2.3 billion” (CEO & Chairman of the Board of Executive Directors Kamieth, Q2 2026; CEO & Chairman of the Board of Executive Directors Kamieth, Q3 2026).
October 29, 2026
Wanhua Q3 Results
Wanhua Chemical’s Q3 Profit Rises 84% as Polyurethane Sales Top RMB 70 Billion
October 29, 2026 1 min read
Wanhua Chemical reported third-quarter revenue of RMB 66.55 billion, up 24.80% year on year, while net profit attributable to shareholders rose 84.38% to RMB 5.60 billion. Profit growth accelerated from the 64.35% increase recorded in the first half, although revenue growth eased from H1’s 31.26%.
For January–September, Wanhua’s revenue reached RMB 185.87 billion, up 28.87% year on year. Attributable net profit climbed 70.99% to RMB 15.66 billion, exceeding the company’s full-year 2025 profit.
| Period | Revenue | Year-on-year change | Attributable net profit | Year-on-year change |
| H1 2026 | RMB 119.32bn | +31.26% | RMB 10.06bn | +64.35% |
| Q3 2026 | RMB 66.55bn | +24.80% | RMB 5.60bn | +84.38% |
| Jan–Sep 2026 | RMB 185.87bn | +28.87% | RMB 15.66bn | +70.99% |
Polyurethane series products generated RMB 70.37 billion in sales revenue over the first nine months. Wanhua reported production of 5.2 million tonnes and sales volume of 5.1 million tonnes for the series during January–September, including material used internally between product series.
Wanhua said polyurethane prices fluctuated upward in Q3. Average market prices were approximately RMB 21,200/tonne for pure MDI, RMB 17,000/tonne for polymeric MDI and RMB 16,800/tonne for TDI. Flexible polyether polyols averaged around RMB 10,000/tonne. The company cited recovering demand in some end uses and support from exports, while noting that domestic flexible-polyol sales remained weak.
The figures show that Wanhua maintained strong earnings growth through September, despite uneven conditions across polyurethane applications. Its Q3 profit increase outpaced its revenue growth, extending the improvement reported in the first half.
Source: Wanhua Chemical’s 2026 third-quarter report
 Everchem Updates Archive
 Sign Up for Email Updates