
Current Affairs
November 9, 2026
Residential Furniture Optimism
Residential furniture orders extend YOY growth streak
November 6, 2026 | 12:02 pm CST Print

Photo by Spacejoy on Unsplash.
HIGH POINT, N.C. — New residential furniture orders dropped 4% in August compared to July figures, but were up 11% compared to August 2025, continuing the year-over-year growth streak for a fourth straight month, according to the October issue of Furniture Insights. Approximately two-thirds of participants reported increases in August compared to a year ago.
Year to date, new orders remain up 5% over 2025 figures.
Shipments were down 2% compared to July 2026, but up 1% from August 2025, with approximately two-thirds of the survey participants reporting increases compared to the year prior, according to Mark Laferriere, assurance partner at Smith Leonard, the accounting and consulting firm that produces the monthly report. Year to date, shipments remain up 1% over 2025 numbers.
August backlogs were up 2% compared to July and up 17% compared to 2025. Receivable levels were up 1% from July, but down 2% from August 2025, according to the report. Inventories were down 1% from July 2026, but up 1% from last year.
“As stated before, hopefully the elevated backlogs (up 17% over last year) will provide good momentum for the remainder of our reporting year despite various headwinds,” Laferriere said.
On a seasonally adjusted basis, sales at furniture and home furnishings stores in September were up 1.3% compared to August, and up 4.9% compared to September 2025. Year-to-date on a non-adjusted basis, sales were down 1.5% according to October’s Furniture Insights.
This latest report followed the recent High Point Market, where, Laferriere noted, “Lots [of] discussions about tariffs, supply chain challenges, AI implementations, retail trends, interest rates, and the ‘K-shaped economy,’ but overall sentiment was high.”
https://www.woodworkingnetwork.com/furniture/residential-furniture-orders-extend-yoy-growth-streak
November 1, 2026
Middle East Polyurethane Update
Expensive to Import, Hard to Sell: The Middle East PU Market’s Supply-Demand Squeeze
October 27, 2026 4 min read
The Middle East PU market continues to face a difficult balance. Local supply remains limited, while replacing it with imports is expensive. Chinese-origin TDI and PMDI prices have stayed firm, supported by high import costs, but downstream manufacturers are struggling to absorb those prices. Material is still moving into the region; the difficulty is selling it at a workable price and in meaningful volumes.
Buyers are keeping purchases close to current production needs. For traders, committing to a costly cargo involves both a high landed cost and the possibility that customers will delay orders by the time it arrives. These pressures have kept the market active enough to meet immediate requirements, but without a broader recovery in demand.
Firm import prices meet cautious buyers
Mid-October price indications show how costly replacement supply remains for GCC buyers:
| Product | Chinese-origin Middle East price indication |
| TDI | $2,800–3,000/tonne |
| PMDI | $2,700–2,800/tonne |
| Conventional flexible polyol, 3,000 MW | $2,000–2,100/tonne CIF |
TDI and PMDI indications were broadly unchanged recently. Flexible polyol prices were also stable after Chinese export quotations rose earlier in October. The lack of another increase offers buyers some relief, but current levels remain difficult for many downstream businesses.
TDI illustrates the problem particularly well. Chinese-origin imports continue to play a major role in GCC supply, yet flexible foam producers have resisted higher prices and kept orders focused on immediate production. PMDI faces a similar limit: restricted regional availability supports firm import indications, while cautious purchasing prevents that firmness from turning into stronger trade. For flexible polyols, stable offers have likewise brought little incentive for buyers to rebuild stocks while affordability remains a concern.
Limited local supply keeps the region dependent on imports
Sadara’s PU production has not returned to normal. Although a small part of the large complex is operating, that activity has not restored regular local MDI, TDI and polyol supply. Earlier expectations of a broader return by the end of September have given way to continued uncertainty over when these materials will again be available consistently.
Local stocks can cover some customers, particularly established buyers in Saudi Arabia, but buyers across the wider Middle East still rely on traders or direct imports. That dependence leaves them exposed to Chinese supplier prices, shipping costs and delivery times.
Market reports have also suggested that Dow may consider selling its 35% stake in Sadara. Aramco, already the majority owner, has been mentioned as a possible buyer and could become the sole owner if it acquired Dow’s stake. Some in the market wonder whether the unresolved ownership discussions are contributing to the cautious pace of production, although there is no confirmation of a connection. For buyers, the immediate issue remains the absence of a dependable return of local PU supply.
Freight keeps replacement costs high
Ocean freight from China to the Middle East remains expensive. Recent quotations for a 40-foot container imply an ocean freight cost of roughly $400 per tonne to Jebel Ali and around $500 or more per tonne to Saudi destinations, assuming a 23-tonne cargo load.
| Shanghai to | Recent ocean freight, 40-foot container | Approximate cost at 23 tonnes |
| Jebel Ali | $9,000 | $391/tonne |
| Jeddah | $11,433 | $497/tonne |
| Dammam | $12,333 | $536/tonne |
Freight has stayed high even without a sharp further increase in recent weeks. Saudi routes carry a particularly heavy burden. Inland transport, handling and other charges can add to the cost, while long transit times make it harder for traders to match incoming cargoes to customers’ changing needs.
This freight table shows the shipping burden on an illustrative container load. Across all three products, though, expensive logistics remain a central part of the region’s supply problem.
High costs continue to restrain downstream demand
The market’s difficulty is not simply a shortage of material. Downstream manufacturers also need finished-product orders that justify buying expensive raw materials. Flexible foam, insulation and other PU users are sensitive to both the product price and the cost of getting it delivered. When those costs rise faster than customers will accept, manufacturers limit purchases and avoid building inventory.
This leaves the market in a persistent squeeze. Restricted local production and costly imports keep TDI, PMDI and polyol replacement prices firm. At the same time, weak downstream purchasing limits trading volumes. Buyers may need material for current orders, but many have little reason to commit to larger quantities at today’s costs.
Conditions differ across nearby markets. Egyptian activity has improved in some areas, yet available stocks and competitive local offers continue to restrain prices. In East Africa, high material costs and shipment delays have affected affordability, although the approaching seasonal period could bring more activity. Neither market should be used as a direct measure of Gulf demand, but both show how supply costs and customers’ ability to pay can pull prices in different directions.
What could change the balance?
A sustained return of local PU production would reduce dependence on costly imports. Lower Chinese-origin product prices, cheaper freight or both would make replacement material more affordable for downstream manufacturers. Demand is unlikely to strengthen substantially unless buyers can obtain raw materials at delivered costs their own customers can support.
Until that happens, the Middle East PU market is likely to remain caught between firm import prices and restrained purchasing. Cargo can move, but expensive supply is still proving hard to sell.
October 19, 2026
Data Centers Drive Construction Growth
Construction backlog rises for second consecutive month, backed again by data center projects
By Dakota Smith
October 13, 2026 | 9:52 am CDT Print
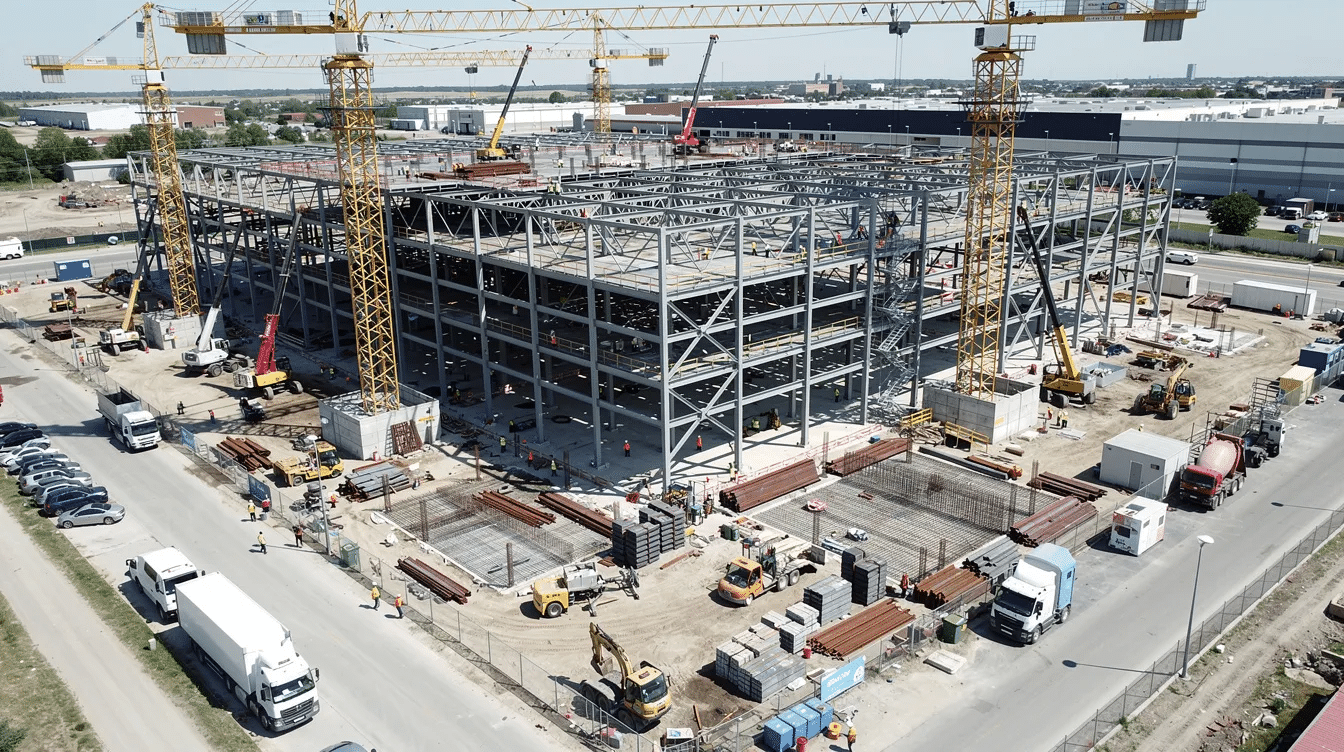
WASHINGTON, D.C. — Associated Builders and Contractors reported that its Construction Backlog Indicator increased to 8.7 months in September, according to an ABC member survey conducted Sept. 21 to Oct. 5. The reading is up 0.2 months on both a monthly and yearly basis.
View the full Construction Backlog Indicator and Construction Confidence Index data series.
Commercial and institutional backlog, which dipped in the middle of 2026, rose to the highest level since July 2025. Heavy industrial backlog, while still up 0.5 months over the past year, fell to its lowest level since March.
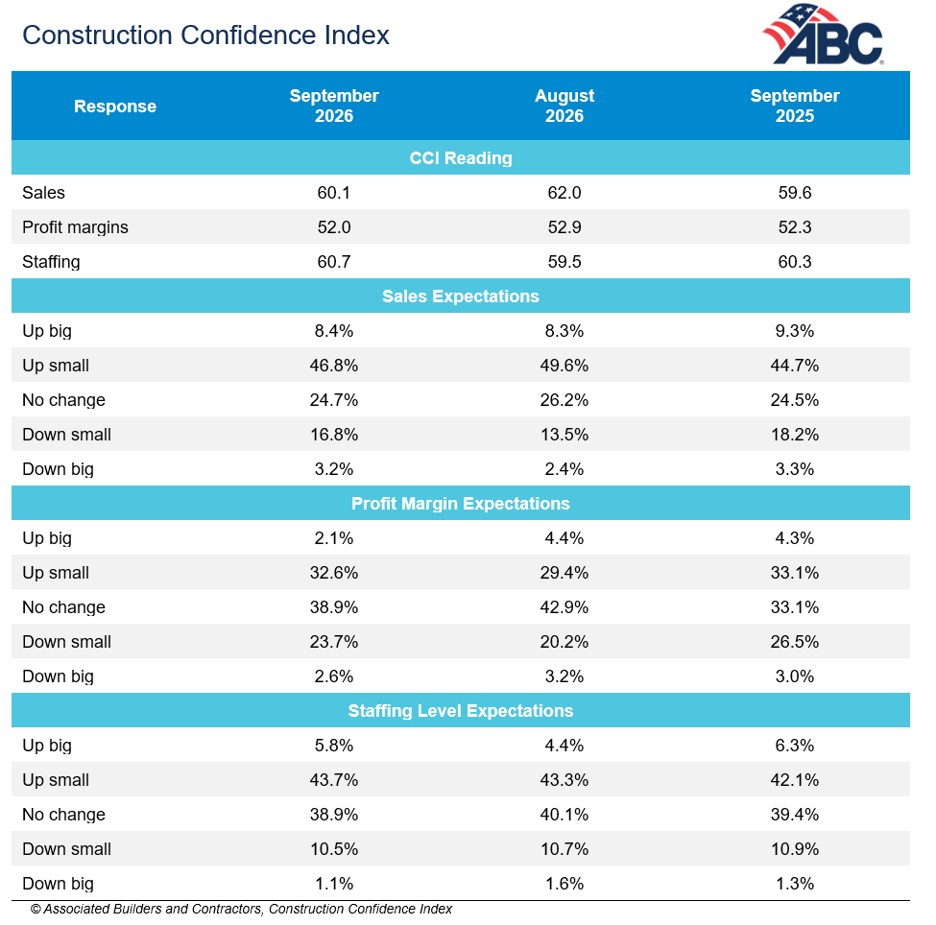
“Backlog increased for the second straight month in September as data center work continues to keep contractors busy,” said ABC Chief Economist Anirban Basu. “The 15% of ABC members under contract to work on data centers averaged 11.3 months of backlog in September, a full three months more than ABC members that are not. This disproportionately benefits the largest contractors; 39% of contractors with greater than $100 million in annual revenues have data center work right now compared to just 1 in 10 contractors with fewer than $100 million in annual revenues.
“At the same time, rising materials and labor and borrowing costs continue to put pressure on contractors,” said Basu. “More than 1 in 4 contractors expect their profit margins to contract over the next six months, the highest share since November 2025. Those same cost pressures have suppressed sales expectations, which also fell to an 11-month low in September.”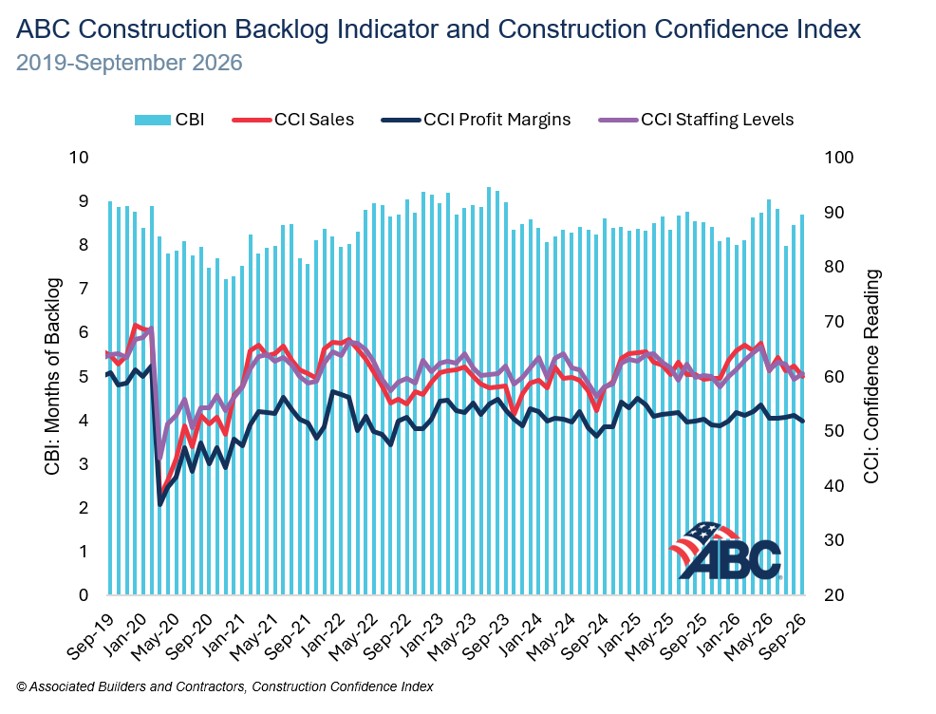
September 13, 2026
Changes in Trade Flows
Chinese imports fall sharply in first half of 2026 U.S. imports from China are down 23% in H1 2026, but the country still dominates critical consumer and industrial categories 5-MINUTE READ
What you’ll learn in this article:
How America’s trade with China has evolved since the start of President Trump’s second term. Which industries have weathered the tariff wars, and which have not. What to expect from Xi Jinping’s upcoming meetings in Washington DC.
🎯 Best for: Business planners and strategists, supply chain managers, VPs of Procurement. As U.S. President Donald Trump prepares to host Chinese President Xi Jinping on September 24, America’s efforts to reduce its trade dependency on China are reshaping supply chains, but the results vary dramatically by industry, according to U.S. Census Bureau data analyzed by ImportGenius.
The data shows that total U.S. imports from China are down 23% in the first 6 months of 2026 compared to the same period last year. China continues to dominate the market for products such as children’s goods and some crucial industrial inputs. But China’s dominance in other areas — particularly the lucrative computer industry — is experiencing significant decline. “China still has a chokehold on the supply of certain goods, but in other areas it has now lost substantial ground,” says ImportGenius CEO Michael Kanko. “The data shows that some global supply chains are being reorganized right before our eyes.” On the decline: computers, electronics, aluminum goods During the six-month period from January to June 2026, China’s role as a source of computers, computer accessories, and electronic equipment for the United States has continued to erode. The table below shows some of the largest declines for the most significant import categories by value. 
Source: ImportGenius In addition to electronics, the table shows that American businesses and consumers are also finding new sources for such products as aluminum wheels, gas-powered appliances, and lithium-ion batteries. Countries such as Mexico and Vietnam have stepped in to make up the shortfalls.
“In essence, for computers and everything that connects to them, China now accounts for less than 50% of total U.S. imports,” says Kanko. “It’s a remarkable shift that’s taken place in only about two years.”Still made in China: Kid stuff, microwave ovens, herbicide Meanwhile, China still dominates some other import markets, most notably for anything to do with children’s transportation — from strollers to car seats — as well as children’s books. It remains impossible to raise a family in America without Chinese goods.
As the table below shows, China also provides more than 90% of America’s total imports for multiple other high-value categories, from fireworks to artificial plants to microwave ovens. And its dominance in some industrial inputs, such as glyphosate and glufosinate, has raised national security alarms. 
Source: ImportGenius Glyphosate and glufosinate are broad-spectrum herbicides. Glyphosate, the active ingredient in Roundup, is manufactured in the United States by Bayer. The company recently petitioned for antidumping and countervailing duties against Chinese glyphosate, prompting the U.S. International Trade Commission to launch an investigation. Global trade is changing in real time This latest data on U.S.-China trade underlines two of the themes in ImportGenius’ Global Trade Outlook report from earlier this year. First, America’s trade diversification is real, but still evolving — and creating opportunities as supply chains adjust. Second, trade data has become a leading indicator for signaling competitive shifts and policy impacts.
That next policy shift could come soon, because America’s shrinking dependency on Chinese goods has yet to apply much pressure on China. The country has replaced its shrinking American imports with sales to countries in Latin America, Africa and beyond, insulating its economy from any shock. At the G20 meeting earlier this month, the United States and 18 other countries criticized “non-market based economies pushing out a never-ending stream of cheap exports.”
“The trade data shows how policies set in Washington reverberate on the other side of the globe,” says Kanko. “And if Xi’s visit to Washington this month results in new policy shifts and decisions, their impact will show up first in the data.”
https://mail.google.com/mail/u/0/?shva=1#inbox/FMfcgzQhWLSTJNSppLStkWRdKvNGlhXq
September 2, 2026
New Home Sales Update
Economic uncertainty weighs on new home sales, reports homebuilding association
By Dakota Smith
August 31, 2026 | 9:42 pm CDT

Elevated borrowing costs, rising inflation and broad economic uncertainty continue to curb buyer demand and hold back new home sales.
Sales of newly built single-family homes declined 10.5% in July to a seasonally adjusted annual rate of 607,000, following a sharply upwardly revised June estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales was 6.3% lower than a year earlier.
“New home sales fell in July to their slowest pace since the start of the year as affordability challenges limited home buyer traffic,” said Bill Owens, chairman of the National Association of Home Builders (NAHB) and a home builder and remodeler from Worthington, Ohio. “NAHB surveys show that a majority of builders continue to offer sales incentives, including mortgage rate buydowns, to support new home sales.”
“The single-family home building market is on track for a second consecutive annual decline in 2026,” said NAHB Chief Economist Robert Dietz. “New home sales are down more than 4% on a year-to-date basis. NAHB research and economic data show community builders continue to outperform the broader market, while the Northeast remains a relative bright spot, with new home sales up nearly 9% year-to-date.”
A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the July reading of 607,000 units is the number of homes that would sell if this pace continued for the next 12 months.
New single-family home inventory in July rose to 488,000 units, up 1.9% from June, and down 1.6% compared to a year ago. This represents an elevated 9.6 months’ supply at the current building pace, the highest measure since January.
The median new home sales price in July fell 2.3% from June to $393,800 and was down 0.9% from a year ago. The new home sales market is showing relative strength at the higher end of the market. The market share of new home sales priced above $800,000 increased from 5% a year ago to 8% in July.
Regionally, on a year-to-date basis, new home sales are up 8.8% in the Northeast but fell in the other three regions, with declines of 6.4% in Midwest, 3.7% in the South and 6.4% in the West.
 Everchem Updates Archive
 Sign Up for Email Updates