
Company News
August 16, 2021
Indorama to Purchase Oxiteno
Indorama Ventures agrees to buy Brazil-based Oxiteno to create a unique portfolio in high-value surfactants
16 August 2021
Bangkok, Thailand – 16 August 2021 – Indorama Ventures Public Company Limited (IVL), a global chemicals producer, today announced it agreed to acquire Brazil-based Oxiteno S.A. Indústria e Comércio, a subsidiary of Ultrapar Participações S.A. The acquisition gives IVL a unique portfolio in high-value surfactants and significantly extends its existing Integrated Oxides and Derivatives (IOD) business.
Oxiteno is a leading integrated surfactants producer, catering to highly attractive end-use markets in LATAM. The acquisition brings an excellent management team, world-class expertise in green chemistry innovation, strong customer relationships in Brazil, Uruguay and Mexico, and substantial growth potential in attractive end markets, including the U.S. through a new facility in Pasadena, Texas. Oxiteno has a strong commitment to environmental governance, and its focus on lowering greenhouse gas emissions will also enhance IVL’s ESG credentials.
Through the acquisition, IVL will assume a unique market position in technologies catering to niche, IP-rich and value-added applications in home & personal care, agrochemicals, coatings and oil & gas markets. The surfactants market has seen consistent growth over the last decade, driven by trends in population growth, urbanization and increasing hygiene awareness amid the Covid-19 pandemic.
With 11 manufacturing plants, customers in 4 continents, and an experienced management team, Oxiteno will complement IOD’s footprint in the U.S and Latin America, while its 5 research and technology centers will add to IVL’s innovation credentials in green chemistry. The extended footprint has potential to drive expansion in Europe and Asia by leveraging on IVOX’s surfactants business in Australia and India and IVL’s global presence in 34 countries. IVL expects to realize synergies of US$100 million by 2025 through portfolio adjustments, asset optimization and operational excellence.
IVL will purchase Oxiteno for US$1.3 billion (subject to adjustments at closing), with a deferred payment of $150 million in 2024. The transaction is subject to customary conditions to closing, including approval of relevant regulatory authorities. The transaction is expected to close in Q1 2022 and will be earnings accretive immediately. Financing is secured through deferred payment, using existing extra cash on our balance sheet, free cash flow generated from existing businesses, short term loans against working capital and the balance as long-term debt.
Oxiteno and Indorama Ventures both have family-business origins and share a similar mindset, which positions people as a key business differentiator and values innovation and investments in an increasingly diversified and efficient portfolio.
Mr Aloke Lohia, IVL Group CEO, said, “This acquisition is a natural fit for us. We have a solid track record of continuously driving value for shareholders through successfully integrating 50 acquisitions over the past 20 years. With Oxiteno, we are creating a global leader in surfactants. By bringing our companies together, we are strengthening our customer value proposition, our market reach, and our experienced team. Like us, Oxiteno grew as a family enterprise with an entrepreneurial mindset. The combination of our teams is unmatched in our industry, and we look forward welcoming them to our family.”
Frederico Curado, CEO of Ultra Group, said, “It is important to ensure that Oxiteno will benefit from integrating the new majority shareholder into the business, which is strategically positioned to lead the company through its growth path.”
Oxiteno’s HVA growth portfolio complements IVL’s existing IOD business
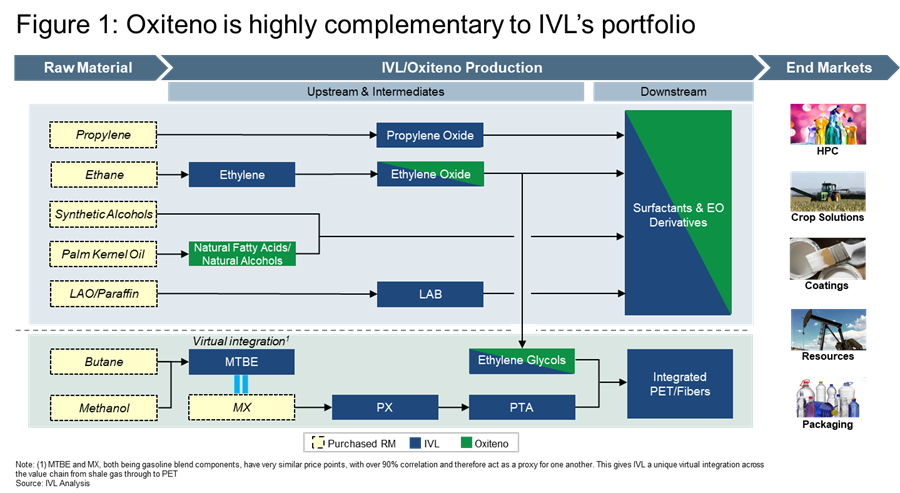
Oxiteno’s innovation-led HVA offering is a significant complement to IVL’s growth platform (Figure 1), and a key driver of IVL’s EBITDA projection over the next two years, which is 15% above the company’s forecast in January 2021. Together with IVL’s world-class assets, which were acquired from U.S.-based Huntsman in 2020 (Spindletop transaction), the acquisition of Oxiteno will lead IVL’s newest IOD business segment as a major high-margin growth driver alongside its traditional PET commodities business, creating a stronger and more resilient hybrid platform.
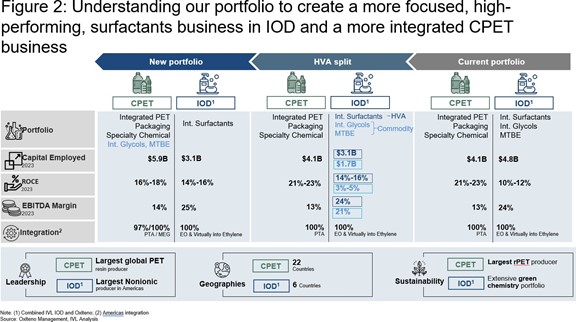
The linkages between IOD, Oxiteno’s high-performing surfactants, and the Combined PET businesses through their crude oil, shale and oleo feedstocks gives IVL integration benefits across the value chain, which is key to the company’s sustainable business model as the world’s largest producer of PET resin and a large geographic footprint in non-ionic surfactants in the Americas (Figure 2).
Oxiteno’s green chemistry innovation credentials also strengthen IVL’s ambitious sustainability objectives as a leader in PET circularity and bio-ingredients. Brazil is home to the largest inventory of ethanol, used to produce bio-ethylene to enhance EOD and PET sustainability. Today, IVL is the largest producer of resin used in recycled PET bottles and aims to recycle a minimum of 750,000 metric tons of PET globally by 2025, investing up to US$1.5 billion to achieve this goal.
Mr D K Agarwal, Chief Executive Officer of Combined PET, IOD and Fibers Business, said, “The combination of Oxiteno and IVL’s existing Integrated Oxides & Derivatives business is highly complementary. It gives us a presence in the high-growth Latin American markets, and we also become a more reliable supplier to our global customers, especially in Europe and the US. It will drive sustainable long-term value creation by accelerating our expansion in downstream chemicals, increasing our exposure to high-quality markets, and adding to our R&D and sustainability credentials. The portfolio will accelerate revenue and EBITDA growth, and deliver cost synergies.”
Driving enterprise growth through a proven strategy
IVL has built a strong global platform based on some 50 successful acquisitions over 20 years, and is embarking on a program of continuous improvement through its 5 strategic priorities of costs transformation, asset optimization, adjacency growth, circularity, and organization excellence. These include significant investments in transformation, savings, and efficiency projects, which are driving expansion in IOD, strengthening its Fibers business segment, and enhancing value in its traditional Combined PET segment.
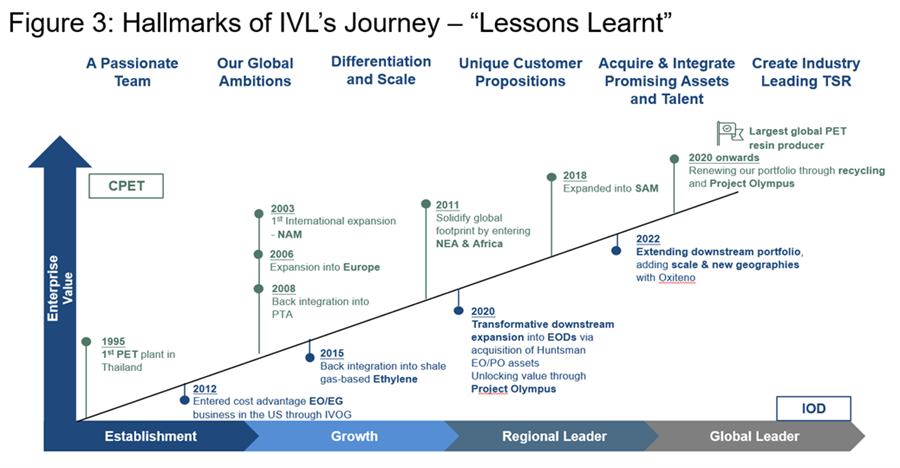
Mr Aloke Lohia, IVL Group CEO, added, “Since 2014 I have been very clear about our strategy of making big bets on HVA and innovation-led products that help us build global leadership positions. From our first PET plant in 1995, we have grown to our current global leadership position through a sound track record of acquiring and integrating new assets and teams that give us scale and differentiate us in the marketplace. This, and our focus on sustainable and circular models, our transformation and efficiency programs, and our ability to grow organically and from acquisitions, will continue to drive enterprise value.” (Figure 3)
August 6, 2021
Covestro Results
Covestro reports second-quarter beat due to strong selling prices
By Zuzanna Szymanska, Anneli Palmen
3 Min Read
(Adds CFO quotes from call)
Aug 6 (Reuters) – German chemicals maker Covestro reported a better than expected final second-quarter profit on Friday as it maintained selling prices above raw material costs thanks to a continued demand recovery.
All industries including chemicals have been heavily affected by recent raw material price inflation, but Covestro, which makes foams and plastics for products including car seats and phone cases, said it was largely successful passing on the costs to customers in the second quarter.
“We produce things that are extremely important for our customers, such as adhesives or coatings, but which only account for a small part of the total cost of the product. This explains why they are willing to pay very high prices,” financial chief Thomas Toepfer told Reuters, adding Covestro was still far from the 2017-2018 historic selling price highs.
Asked about risks from the spread of the more contagious delta coronavirus variant, the CFO said Covestro’s product mix should help it resist the pressure as it did in late 2020.
“The high demand for such products as wind turbine coatings or light materials for electric cars is driven by sustainability trends that haven’t really been affected by the pandemic,” Toepfer said.
He added chip shortages in the automotive industry, which accounts for 20% of Covestro’s sales, have not hurt Covestro’s growth thanks to its solid order book.
“Since late 2020, we have been completely sold out as far as our production capacities are concerned, so getting fewer orders from automakers is almost a relief for us,” he said.
Covestro said its second-quarter net income came in at 449 million euros ($530.76 million), compared to the 433 million euros expected on average by analysts in a company-provided poll, and confirmed the preliminary core earnings and 2021 forecast it announced on July 12. ($1 = 0.8460 euros) (Reporting by Zuzanna Szymanska and Anneli Palmen; additional reporting by Veronica Snoj in Gdansk; Editing by Tomasz Janowski and David Evans)
https://www.reuters.com/article/covestro-results-idUSL8N2PD0R7
August 6, 2021
Covestro Results
Covestro reports second-quarter beat due to strong selling prices
By Zuzanna Szymanska, Anneli Palmen
3 Min Read
(Adds CFO quotes from call)
Aug 6 (Reuters) – German chemicals maker Covestro reported a better than expected final second-quarter profit on Friday as it maintained selling prices above raw material costs thanks to a continued demand recovery.
All industries including chemicals have been heavily affected by recent raw material price inflation, but Covestro, which makes foams and plastics for products including car seats and phone cases, said it was largely successful passing on the costs to customers in the second quarter.
“We produce things that are extremely important for our customers, such as adhesives or coatings, but which only account for a small part of the total cost of the product. This explains why they are willing to pay very high prices,” financial chief Thomas Toepfer told Reuters, adding Covestro was still far from the 2017-2018 historic selling price highs.
Asked about risks from the spread of the more contagious delta coronavirus variant, the CFO said Covestro’s product mix should help it resist the pressure as it did in late 2020.
“The high demand for such products as wind turbine coatings or light materials for electric cars is driven by sustainability trends that haven’t really been affected by the pandemic,” Toepfer said.
He added chip shortages in the automotive industry, which accounts for 20% of Covestro’s sales, have not hurt Covestro’s growth thanks to its solid order book.
“Since late 2020, we have been completely sold out as far as our production capacities are concerned, so getting fewer orders from automakers is almost a relief for us,” he said.
Covestro said its second-quarter net income came in at 449 million euros ($530.76 million), compared to the 433 million euros expected on average by analysts in a company-provided poll, and confirmed the preliminary core earnings and 2021 forecast it announced on July 12. ($1 = 0.8460 euros) (Reporting by Zuzanna Szymanska and Anneli Palmen; additional reporting by Veronica Snoj in Gdansk; Editing by Tomasz Janowski and David Evans)
https://www.reuters.com/article/covestro-results-idUSL8N2PD0R7
August 2, 2021
Leggett & Platt Q2 Results
Leggett & Platt Reports Record 2Q Results
Aug. 02, 2021 4:10 PM ETLeggett & Platt, Incorporated (LEG)
CARTHAGE, Mo., Aug. 2, 2021 /PRNewswire/ —
- 2Q sales were a quarterly record1 $1.27 billion, a 50% increase vs 2Q20
- 2Q EBIT was $172 million, an increase of $149 million vs 2Q20
- 2Q record adjusted2 EBIT was $144 million, up $94 million vs 2Q20
- 2Q EPS was $.82, up $.87 vs 2Q20; 2Q adjusted2 EPS was $.66, up $.51 vs 2Q20 adjusted2 EPS
- Acquired Kayfoam, an Ireland-based provider of specialty foam and finished mattresses
- Increasing 2021 guidance: sales of $4.9–$5.1 billion; EPS of $2.86–$3.06; adjusted2 EPS of $2.70–$2.90
Diversified manufacturer Leggett & Platt (LEG) reported record1 quarterly sales in second quarter of $1.27 billion, a 50% increase versus second quarter last year.
- Organic sales were up 50%
- Volume was up 31%, reflecting strong recovery in most of our businesses and increased demand versus 2Q 2020, which was significantly impacted by the COVID-19 pandemic
- Raw material-related selling price increases of 16% and currency benefit of 3% added to sales growth
- Acquisitions and divestitures offset each other
Second quarter EBIT was $172 million, up $149 million from second quarter 2020. Adjusted2 EBIT was $144 million, a second quarter record and an increase of $94 million from second quarter 2020 adjusted2 EBIT
- EBIT and adjusted2 EBIT benefited primarily from volume growth and metal margin expansion
- Maintained $20 million of fixed cost reductions implemented in 2020 (versus $36 million in 2Q20)
- 2Q 2021 adjustment for a $28 million gain on the sale of real estate associated with our exited Fashion Bed business
- 2Q 2020 adjustments include a $25 million goodwill impairment charge related to our Hydraulic Cylinders business and $2 million of restructuring charges primarily from pandemic-related cost reductions
- EBIT margin was 13.5% and adjusted2 EBIT margin was 11.3%, up from 6.0% in the second quarter of 2020
Second quarter EPS was $.82, an increase of $.87 versus second quarter 2020. Second quarter adjusted2 EPS was $.66, up $.51 versus adjusted2 EPS in second quarter 2020.
CEO COMMENTS
Chairman and CEO Karl Glassman commented, “Our employees continued to drive strong results in the second quarter despite a challenging macroenvironment. Due to their tremendous efforts, we are pleased to deliver all-time quarterly record1 sales along with record second quarter adjusted2 EBIT and EBITDA. While we continue to navigate inflationary pressures along with supply chain disruptions, consumer demand remains strong and we are increasing our full year guidance.
“We are also pleased to announce that on June 4, we acquired a leading provider of specialty foam and finished mattresses primarily serving customers in the UK and Ireland. The company, Kayfoam, is located near Dublin and has two manufacturing facilities with combined annual sales of approximately $80 million. Kayfoam expands the capabilities of our European Bedding business and establishes a platform in foam technology and finished mattress production. Similar to our U.S. Bedding business, this acquisition allows us to support our European bedding customers anywhere in the value chain from innerspring and foam components to finished products including private label mattresses, toppers, pillows, and other bedding accessories.
“Finally, we remain focused on cash generation while reducing debt and deploying capital in a balanced and disciplined manner that positions us to capture near- and long-term growth opportunities, both organically and through strategic acquisitions.”
https://seekingalpha.com/pr/18418497-leggett-and-platt-reports-record-2q-results
August 2, 2021
Leggett & Platt Q2 Results
Leggett & Platt Reports Record 2Q Results
Aug. 02, 2021 4:10 PM ETLeggett & Platt, Incorporated (LEG)
CARTHAGE, Mo., Aug. 2, 2021 /PRNewswire/ —
- 2Q sales were a quarterly record1 $1.27 billion, a 50% increase vs 2Q20
- 2Q EBIT was $172 million, an increase of $149 million vs 2Q20
- 2Q record adjusted2 EBIT was $144 million, up $94 million vs 2Q20
- 2Q EPS was $.82, up $.87 vs 2Q20; 2Q adjusted2 EPS was $.66, up $.51 vs 2Q20 adjusted2 EPS
- Acquired Kayfoam, an Ireland-based provider of specialty foam and finished mattresses
- Increasing 2021 guidance: sales of $4.9–$5.1 billion; EPS of $2.86–$3.06; adjusted2 EPS of $2.70–$2.90
Diversified manufacturer Leggett & Platt (LEG) reported record1 quarterly sales in second quarter of $1.27 billion, a 50% increase versus second quarter last year.
- Organic sales were up 50%
- Volume was up 31%, reflecting strong recovery in most of our businesses and increased demand versus 2Q 2020, which was significantly impacted by the COVID-19 pandemic
- Raw material-related selling price increases of 16% and currency benefit of 3% added to sales growth
- Acquisitions and divestitures offset each other
Second quarter EBIT was $172 million, up $149 million from second quarter 2020. Adjusted2 EBIT was $144 million, a second quarter record and an increase of $94 million from second quarter 2020 adjusted2 EBIT
- EBIT and adjusted2 EBIT benefited primarily from volume growth and metal margin expansion
- Maintained $20 million of fixed cost reductions implemented in 2020 (versus $36 million in 2Q20)
- 2Q 2021 adjustment for a $28 million gain on the sale of real estate associated with our exited Fashion Bed business
- 2Q 2020 adjustments include a $25 million goodwill impairment charge related to our Hydraulic Cylinders business and $2 million of restructuring charges primarily from pandemic-related cost reductions
- EBIT margin was 13.5% and adjusted2 EBIT margin was 11.3%, up from 6.0% in the second quarter of 2020
Second quarter EPS was $.82, an increase of $.87 versus second quarter 2020. Second quarter adjusted2 EPS was $.66, up $.51 versus adjusted2 EPS in second quarter 2020.
CEO COMMENTS
Chairman and CEO Karl Glassman commented, “Our employees continued to drive strong results in the second quarter despite a challenging macroenvironment. Due to their tremendous efforts, we are pleased to deliver all-time quarterly record1 sales along with record second quarter adjusted2 EBIT and EBITDA. While we continue to navigate inflationary pressures along with supply chain disruptions, consumer demand remains strong and we are increasing our full year guidance.
“We are also pleased to announce that on June 4, we acquired a leading provider of specialty foam and finished mattresses primarily serving customers in the UK and Ireland. The company, Kayfoam, is located near Dublin and has two manufacturing facilities with combined annual sales of approximately $80 million. Kayfoam expands the capabilities of our European Bedding business and establishes a platform in foam technology and finished mattress production. Similar to our U.S. Bedding business, this acquisition allows us to support our European bedding customers anywhere in the value chain from innerspring and foam components to finished products including private label mattresses, toppers, pillows, and other bedding accessories.
“Finally, we remain focused on cash generation while reducing debt and deploying capital in a balanced and disciplined manner that positions us to capture near- and long-term growth opportunities, both organically and through strategic acquisitions.”
https://seekingalpha.com/pr/18418497-leggett-and-platt-reports-record-2q-results
 Everchem Updates Archive
 Sign Up for Email Updates