
Epoxy
October 3, 2021
Plus a 10 Day National Holiday
A Dip In Shipping Rates: The End Of The Nightmare, Or Just The Eye Of The Hurricane
by Tyler DurdenSaturday, Oct 02, 2021 – 07:00 PM
This year, spot ocean container rates have reached record highs and could be at a crucial inflection point this week. News of 40-foot container rates on the world’s most important shipping lane, that is, China and the U.S., plunged amid a power crunch shutting down factories across multiple Chinese provinces leading speculators to sell their shipping spots, according to Chinese media outlet Caixin Global.
Caixin spoke with an executive at a Shanghai freight company Thursday who said 40-foot container rates from China to the U.S. West Coast sank this week, plummeting from $15,000 to just $8,000. For the same container, the spot rate for China to the U.S. East Coast dropped from $20,000 to around $15,000.
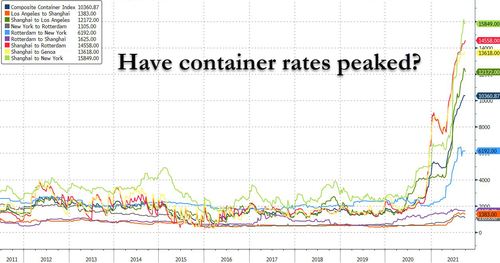
The decline in international shipping costs is primarily due to at least 20 Chinese provinces and regions making up more than 66% of the country’s GDP have announced some form of power cuts in recent weeks, which has shuttered energy-intensive manufacturing industries and so their need for containerized shipping has diminished.
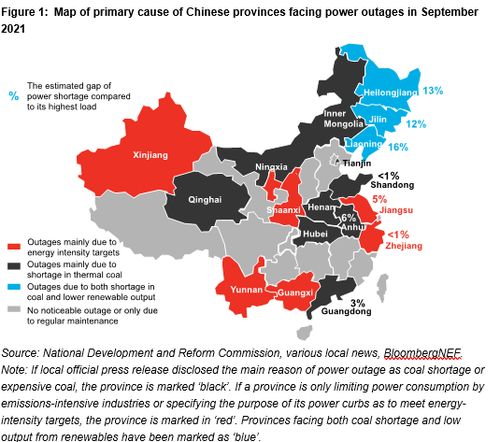
We have noted Foxconn, the world’s biggest iPhone assembler and a key supplier of Apple and Tesla, halted production earlier this week. Another Apple supplier, Unimicron Technologies, suspended operations. There are countless reports of other energy-intensive companies that suspended operations.
An analyst at Tianfeng Securities Co. Ltd. said the decline in shipping rates was primarily caused by the imminent off-season and a reduction in manufacturing due to China’s power crunch. The analyst said rates should decline as export growth in China will decrease in the fourth quarter, and seasonally ocean freight slows down.
A report by CSC Financial Co. Ltd. outlined rates will stay stubbornly high for the next two weeks as port congestion remains a problem in China and the U.S. But after that, rates may stall on slow growth from China.
We so far understand China’s power crunch is having a sizeable impact on economic growth and has resulted in a slump for containerized shipping demand. What comes next is either shipping rates continue a downward spiral or bounce back as China will ultimately restart its manufacturing base near term.
https://www.zerohedge.com/commodities/dip-shipping-rates-end-nightmare-or-just-eye-hurricane
October 1, 2021
Propane/Propylene Forecast
September 29, 2021
The Propane Nightmare Before Christmas: Tight Fundamentals Will Dampen Propylene Margins
The notion that global supply chains have been severely impacted by COVID is not new, as consumers have been dealing with scarcity of home appliances, automobiles, and other goods. But even within this context of supply chain challenges, the potential price spikes pertaining to propane/propylene/polypropylene could prove to be unprecedented and could severely impact margins across the supply chain.
One main culprit behind the expected price increase is the current US stock levels, which are at their lowest in five years, because of lower-than-usual supply coupled with additional global demand. Additionally, the low stock levels are occurring at the same time that the market is entering the highest seasonal demand period, which typically spans between September to February of each year.

It is also important to consider what has happened from a global perspective, including the impact of COVID-19 on the propane markets. Worldwide refining activity started increasing towards March of this year once the jitters associated with the second wave of COVID-19 settled down with the onset of vaccinations. Consequently, global refinery production of LPG increased significantly towards June 2021. However, with the impact of the Delta variant, the rebound in refining activity stagnated, and has been further affected by normal maintenance schedules starting in August and September. The combination has resulted in a decline in refinery-provided propane.
With regards to demand, during the pandemic US propane demand actually increased. There was also significant seasonal withdrawal during the winter of 2020/2021 because of the unusual cold weather that affected not only the northern part of the US, but also the southern part of the US, reaching all the way down to the Gulf Coast. Demand growth is expected to remain strong through the rest of the year and through 2022 (see Global NGLs).
An additional impact on the propane balance was the result of elevated US propane exports experienced during the 2020/2021 winter when exports to Asia were especially robust because of the colder-than-usual winter.
All these elements combined are poised to create a challenging environment for propylene producers, who will struggle with high prices and propane availability.
https://stratasadvisors.com/insights/2021/0930201-propane_propylene-insight
October 1, 2021
Propane/Propylene Forecast
September 29, 2021
The Propane Nightmare Before Christmas: Tight Fundamentals Will Dampen Propylene Margins
The notion that global supply chains have been severely impacted by COVID is not new, as consumers have been dealing with scarcity of home appliances, automobiles, and other goods. But even within this context of supply chain challenges, the potential price spikes pertaining to propane/propylene/polypropylene could prove to be unprecedented and could severely impact margins across the supply chain.
One main culprit behind the expected price increase is the current US stock levels, which are at their lowest in five years, because of lower-than-usual supply coupled with additional global demand. Additionally, the low stock levels are occurring at the same time that the market is entering the highest seasonal demand period, which typically spans between September to February of each year.
It is also important to consider what has happened from a global perspective, including the impact of COVID-19 on the propane markets. Worldwide refining activity started increasing towards March of this year once the jitters associated with the second wave of COVID-19 settled down with the onset of vaccinations. Consequently, global refinery production of LPG increased significantly towards June 2021. However, with the impact of the Delta variant, the rebound in refining activity stagnated, and has been further affected by normal maintenance schedules starting in August and September. The combination has resulted in a decline in refinery-provided propane.
With regards to demand, during the pandemic US propane demand actually increased. There was also significant seasonal withdrawal during the winter of 2020/2021 because of the unusual cold weather that affected not only the northern part of the US, but also the southern part of the US, reaching all the way down to the Gulf Coast. Demand growth is expected to remain strong through the rest of the year and through 2022 (see Global NGLs).
An additional impact on the propane balance was the result of elevated US propane exports experienced during the 2020/2021 winter when exports to Asia were especially robust because of the colder-than-usual winter.
All these elements combined are poised to create a challenging environment for propylene producers, who will struggle with high prices and propane availability.
https://stratasadvisors.com/insights/2021/0930201-propane_propylene-insight
October 1, 2021
Propylene Falls 3c/lb in September

Chemical grade settled at $0.825/lb
October 1, 2021
Propylene Falls 3c/lb in September
Chemical grade settled at $0.825/lb
 Everchem Updates Archive
 Sign Up for Email Updates