
Mergers & Acquisitions
July 12, 2026
Unsolicited Offer!
Why Carlisle Companies targets Owens Corning for an M&A combo
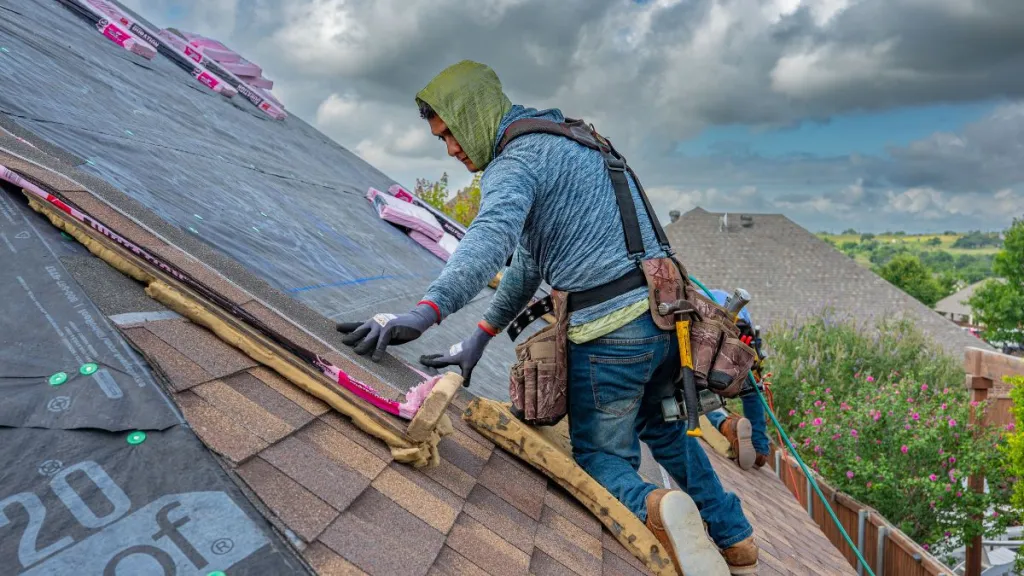
Owens Corning, which has a big presence in roofing, insulation and doors, would supercharge Carlisle Companies’ exposure to the residential construction market
June 30, 2026, 4:33pm by Tyler Williams
The Builder’s Daily > Products
Article Summary
A WSJ report said Carlisle has made repeated unsolicited bids to buy Owens Corning for well over $10B. Owens Corning has not entered meaningful talks, but the attempt highlights accelerating consolidation among building products players. AI Summary
As homebuilders grapple with questions of scale, access to capital and long-term competitiveness, many of their largest suppliers appear to be navigating similar strategic pressures.
Carlisle Companies‘ unsolicited pursuit of Owens Corning, reported Monday by the Wall Street Journal, suggests that the forces reshaping homebuilding boardrooms are also beginning to reshape the building-products companies that supply them.
Whether the transaction ultimately succeeds may prove less important than the question it raises: Has scale itself become one of the industry’s most valuable strategic assets?
While the exact value of the latest bid isn’t disclosed, it would reportedly be a “well-over $10 billion deal”. However, Owens Corning has yet to engage in meaningful discussions with Carlisle, suggesting that any potential deal remains highly preliminary and far from a slam dunk.
While the bid’s fate is uncertain, it has the potential to transform Carlisle into a far larger and more diversified building products manufacturer.
That logic increasingly resembles the thinking emerging elsewhere across residential construction.
Homebuilders, distributors and manufacturers alike are confronting a business environment where growth through operating execution alone is becoming more difficult. Technology investment, supply-chain resilience, customer concentration, labor shortages, insurance costs and capital requirements increasingly reward organizations capable of operating broader platforms rather than simply larger businesses.
In that sense, Carlisle’s interest in Owens Corning appears to reflect more than a desire to add revenue. It reflects an effort to assemble a more comprehensive building-envelope platform capable of serving customers across a wider range of residential and commercial applications.
If the acquisition gains steam, Carlisle could expand upon its current offerings, which include commercial roofing and waterproofing, and grow its presence in residential construction.
Owens Corning’s points of strength
Owens Corning primarily operates in residential construction, but it also has a significant commercial presence, bringing something increasingly valuable to any strategic acquirer: optionality.
Rather than depending on a single end market, its revenue spans new residential construction, residential repair and remodeling, commercial construction and non-discretionary repair activity. That diversification helps reduce cyclicality while providing exposure to multiple spending streams across the built environment.
According to an Owens Corning Q2 2026 investor presentation from May, 26% of the company’s revenue comes from non-residential projects. Meanwhile, 23% of revenue comes from new residential construction, 17% from the roughly $500 billion residential R&R sector and 34% from non-discretionary repair.
In today’s uncertain construction economy, that balance may be every bit as valuable as market share. Owens Corning focuses on three categories.
Insulation
The company is a leader in insulation for both residential and commercial products, with slightly more revenue coming from residential. According to company materials, Owens Corning’s insulation revenue has been relatively flat at about $3.7 billion annually since 2022. About 80% of that revenue comes from North American sales, while 20% derives from Europe.
Grand View Research reports that the North American insulation market is about $16.7 billion as of 2025, indicating that Owens Corning commands nearly 18% of the market.
Building code changes have increased demand for higher-performance insulation in North American homes, creating a favorable market opportunity. Owens Corning estimates that the average home now contains roughly 30% more insulation by weight than it did 10 to 15 years ago, indicating a growing market opportunity.
Roofing
Owens Corning’s roofing business, which peaked at $4.6 billion in revenue in 2024, generated $4.4 billion last year, nearly 90% of which came from business within the United States. Based on estimates that value the U.S. roofing market at about $33.5 billion in 2026, Owens Corning accounts for roughly 11% to 12% of the overall market.
About two-thirds of the firm’s roofing revenue comes from shingles, while the rest comes from components sales.
Evercore ISI’s Stephen Kim, in a research note, wrote that the takeover bid, even if it doesn’t come to fruition, reveals the “undervalued nature of the company’s roofing business.”
“Over the past year, the segment’s resilience in the face of declining industry volume set the stage for investors to rethink what is an appropriate multiple for this business. And while near-term challenges in the industry might prove to be a distraction over the next few months, we now believe the increased focus on roofing long-term earnings potential provides the missing catalyst for the shares,” Kim wrote.
Doors
Owens Corning entered the door business after it acquired Masonite International for $3.9 billion in 2024. In 2025, doors generated just over $2 billion in revenue, about 75% of which came from the United States, representing a small slice of the roughly $30 billion U.S. doors-and-windows market.
Why Owens Corning?
While Carlisle Companies has a well-established track record of acquiring smaller rivals, an acquisition of Owens Corning would be by far its largest deal to date. Carlisle generated about $5.0 billion in revenue in 2025, roughly half of Owens Corning’s top line. However, Carlisle’s $15.7 billion market capitalization exceeds Owens Corning’s roughly $11 billion valuation.
If the potential moves forward, it would significantly increase Carlisle’s scale. It would also broaden its product portfolio and greatly expand its exposure to the residential market. About 82% of Carlisle’s revenue came from commercial projects, with only 18% from residential.
Carlisle has significantly more strength in areas like waterproofing systems, building envelope technologies, commercial reroofing and replacement and single-ply commercial roofing membranes, which are designed to protect flat roofs.
Owens Corning, meanwhile, finds its strength in residential asphalt shingles, composite materials, doors and fiberglass insulation.
If the two businesses merge, Carlisle could expand into these product niches and gain significant exposure in the residential market, both new construction and repair. The combined business would create a leading roofing and insulation supplier, with additional offerings like composites, weatherproofing and doors.
Increasing M&A in building materials
Carlisle’s bid to acquire Owens Corning, even if it proves unsuccessful, signals that the highly fragmented building products distribution industry could undergo increasing consolidation in the years ahead.
The industry has already experienced significant M&A activity in recent years, led by the likes of QXO. The Brad Jacobs-backed company announced in April that it will acquire TopBuild for $17 billion, a deal that the two companies’ stockholders approved on Monday. QXO also bought Kodiak Building Partners for $2.25 billion earlier this year.
The Webb Analytics 2025 Deals Report found that 2025 generated the highest level of building materials M&A activity in a decade based on facilities acquired. Even though deal volume declined 30% and there were fewer acquirers, larger transactions played an outsized role.
Just four of the 120 reported deals last year represented 85% of all supply facilities acquired. This suggests that the industry’s largest players, like QXO, The Home Depot, Lowe’s and Builders FirstSource, are becoming increasingly influential in driving consolidation and capturing market share.
Another boardroom question
Carlisle’s unsolicited approach also arrives at a moment when public-company boards across housing-related industries are increasingly confronting similar strategic questions.
For homebuilders, recent transactions involving Taylor Morrison, Tri Pointe Homes, Landsea Homes and others have underscored how boards are weighing independence against the benefits of larger capital platforms.
Building-products manufacturers appear to be entering a comparable phase.
The question is no longer simply whether companies can continue growing independently.
It is whether shareholders may ultimately be better served through combinations capable of accelerating growth, broadening product portfolios and improving long-term competitive positioning.
Whether Owens Corning’s board reaches that conclusion remains to be seen.
But Carlisle’s proposal suggests those conversations are no longer confined to homebuilders.
July 6, 2026
Covestro Acquires Vencorex Sites
Covestro completes acquisition of former Vencorex sites in Thailand and the US
July 2, 2026 2 min read
• Covestro completes acquisition of two former Vencorex production sites for HDI derivatives in Rayong, Thailand, and Freeport, Texas, USA
• Additional capacities strengthen Covestro’s regional production network and improve supply resilience for coatings and adhesives customers
• Expanded footprint enhances reliable access to highperformance materials used in automotive, infrastructure, marine, wood furniture, electronics and other industrial applications
Leverkusen, Germany – On July 1, 2026, Covestro completed the acquisition of two former Vencorex production sites for HDI derivatives in Rayong, Thailand, and Freeport, Texas, USA.
With the acquisition, Covestro expands its production footprint for HDI derivatives and reaffirms its commitment in two important regions, while strengthening its ability to serve customers in the coatings and adhesives industry with greater flexibility and reliability.
HDI derivatives are essential building blocks for high-performance polyurethane coatings, adhesives and sealants. They are used in a broad range of applications, including automotive coatings, protective coatings for infrastructure, marine coatings, wood furniture, electronics and other demanding industrial applications.
“By adding these sites in Thailand and the US, we are strengthening our regional production capabilities and improving our ability to supply customers from locations close to them,” said Thomas Roemer, Head of the Business Entity Coatings and Adhesives at Covestro. “Reliable supply, regional availability and technical expertise are critical for our customers, especially in a challenging market environment. This acquisition helps us deliver even better on those needs.”
The two sites complement Covestro’s existing production network for HDI derivatives in major regions including Europe, Asia and North America. The additional capacities will further enhance Covestro’s ability to respond to customer demand and support long-term growth in high-performance and more sustainable coatings and adhesives applications.
“Strong customer relationships are built on trust, reliability and the ability to deliver value over time,” said Monique Buch, Chief Commercial Officer of Covestro. “This acquisition strengthens our position in a business where customers count on us for consistent quality, regional supply and application expertise.”
The acquisition follows Covestro’s earlier acquisition of the Resins & Functional Materials business from DSM and continued investments in organic growth, underlining the company’s commitment to the coatings and adhesives industry.
June 17, 2026
Huntsman and Olin M&A Call Highlights
Huntsman Corporation (HUN) M&A Call Transcript
Jun 16, 2026, 11:02 AM ETHuntsman Corporation (HUN) Stock
Huntsman Corporation (HUN) M&A Call June 16, 2026 8:00 AM EDT
Company Participants
Steve Keenan – Director of Investor Relations
Kenneth Lane – President, CEO & Director
Peter Huntsman – Chairman, President & CEO
Philip Lister – Executive VP & CFO
Steve Keenan
Director of Investor Relations
Thanks, Chelsea, and welcome, everyone. I’m joined on the call today by Ken Lane, President and Chief Executive Officer of Olin; and Peter Huntsman, Chairman, President and Chief Executive Officer of Huntsman. Todd Slater, Olin’s Senior Vice President and Chief Financial Officer; and Phil Lister, Huntsman’s Executive Vice President and Chief Financial Officer, will participate in the Q&A portion of today’s call. Before we begin, I’d like to remind everyone that today’s discussion regarding Olin and Huntsman includes forward-looking statements, including expectations regarding the proposed transaction. These statements are subject to risks and uncertainties, and we encourage you to review our related SEC filings for more detail. I would now like to turn the call over to Ken.
Kenneth Lane
President, CEO & Director
Thank you, Steve, and good morning, everyone. I appreciate you joining us. Today is a momentous one for Olin and Huntsman, two storied American companies with a shared commitment to safety, integrity, operational excellence and serving customers around the world, all while creating value for our shareholders. .
The all-stock merger of equals we announced this morning will create a greater than $12 billion chemicals leader with a strong North American anchor and complementary European and Asian portfolios. By integrating Olin’s strong upstream manufacturing and feedstock position with Huntsman’s differentiated downstream capabilities, we will have a world-scale, vertically integrated platform that is better positioned to serve customers and deliver resilient financial performance.
The combined portfolio also creates tangible integration opportunities across key value chains, supporting a lower cost position through the cycle. These strategic tailwinds are paired with more than $400 million of cost synergies and integration benefits. The combined business will have strong cash flow to support disciplined capital allocation including near-term deleveraging, returning capital to shareholders and investing in high-return growth projects.
I’ve spent my career in chemicals across both commodity and downstream businesses, including running a global polyurethanes business. I understand how to get the best out of these businesses in many respects, that means running them as complementary, but separate, and I’m confident we can do that while also delivering on the benefits of this transaction.
Olin’s stated strategy is to focus on strengthening our core businesses, maximizing valuations where we can achieve attractive returns through innovation and operational improvements. This transaction hits those marks. Further, as Olin Huntsman will be led by a team with the right experience and shared foundational values to ensure we are capturing all the opportunities available to us.
I’d now like to turn it over to Peter Huntsman to walk through the transaction structure and combined platform in greater detail. But before I do, I’ll take a moment to recognize Olin’s dedicated employees whose commitment and focus has made today’s milestone possible. I’m very proud to be part of the Olin team. I’d also like to acknowledge Peter and his team. As you might expect, over the course of reaching this agreement, Peter and I have spent a good deal of time together. It’s been clear what a world-class team Huntsman also has with great expertise, and most importantly, truly held values that we at Olin share.
Peter, I’m looking forward to working with you and the other directors of the Board. I know OlinHuntsman is going to do great things.
Peter Huntsman
Chairman, President & CEO
Ken, thank you very much. Good morning, everyone, and thank you for taking the time to join us. It is an honor to be here today, and I echo Ken’s enthusiasm for the opportunities ahead. As our industry continues to globalize, we compete more today against countries than companies, trade policies and global supply chains more than ever before. The opportunities this merger creates enables us to generate greater value for our shareholders, delivers exceptional services and products for our customers and provide greater opportunities and stabilities for our associates. This merger of equals takes 2 great companies and create a much stronger global leader.
So let me provide some further detail. Let’s turn to Slide #5. We have structured this combination as an all-stock merger of equals, which we believe capitalizes on the strength of both companies and present the best value creation opportunities for both sets of shareholders. Under the terms of the agreement, Huntsman shareholders will receive 0.576 shares of Olin for each Huntsman share they own, resulting in Olin shareholders owning approximately 54.5% and Huntsman shareholders owning approximately 45.5% of the combined company. The combined company will be named OlinHuntsman Corporation and will be headquartered in the Woodlands, Texas.
As Ken mentioned, we have identified more than $400 million of cost synergies and integration benefits. Our respective teams have spent a great deal of time together identifying and validating these synergies, and Ken will provide greater detail on how we will achieve them later in this presentation. The transaction is expected to close in the first half of 2027, subject to receipt of regulatory approvals and satisfaction of other customary closing conditions, including approval from both Olin and Huntsman shareholders. Following the close, I will serve as Non-Exec Chairman of the Board of Directors, and Ken will assume the role of Chief Executive Officer. Phil Lister, will serve as Chief Financial Officer; and Todd Slater, will serve as the Chief Integration Officer.
Let’s turn to Slide #6. Let me spend a moment on the scale and benefits of the combined company. Using 2025 reported financials on a pro forma basis, the combined company would have generated approximately $12.5 billion in revenue and approximately $1.3 billion of adjusted EBITDA, including expected cost synergies. We will be anchored in cost advantage in North American assets and feedstocks with integrated portfolios that create multiple channels for improved economics and value creation across a broad range of attractive end markets. We also have identified opportunities in Europe that capitalize on our integration and downstream capabilities. With Huntsman’s relationships in these global end markets, we have a unique opportunity to deliver for our customers more profitably by leveraging Olin assets to improve efficiency across the value chain.
We can turn to Slide #7. Our industry has changed a lot over the last 5 years. Cost position, reliability and integration matters more than ever. That is why I believe this type of integration is essential to driving optionality and higher profitability now and into the future. You see on Slide 7, Olin brings advantaged upstream leadership, including an efficient cost position from U.S. Gulf Coast economics and world-scale chemical assets. Huntsman brings downstream application expertise, including leading positions in MDI and polyurethane systems ride and advanced materials, supported by deep end-market customer relationships. Put simply, we believe this combination will drive value creation for our shareholders and unlock greater profitability.
So looking at Slide 8, there is a clear indication of how integration creates value for both companies across several key value chains. The combination brings together selected Olin and Huntsman capabilities across electrochemical units to polyurethanes, electrochemical units to amines and to epoxies. Olin is strong at the front end of the value chain with the ability to make chlorine and caustic soda safely, reliably and at world scale. Huntsman is strong downstream, particularly in polyurethanes, amines, advanced materials and formulation-driven applications. By combining these capabilities, we create more reliability and better integrated supply chains capable of generating greater value to shareholders and customers.
For example, today, Olin has several existing outlets for chlorine, including vinyls, epoxy, water treatment, chlorinated organics, merchant chlorine and hydrochloric acid. Through the combination, OlinHuntsman will have additional outlets across polyurethanes, amines and advanced materials broadening participation across the value chain. It also creates a vertically integrated U.S. MDI producer. Starting in 2031 as current supply contracts expire, we expect to add an additional $100 million or more of incremental synergies. The result is a more closely integrated set of chlorine-linked value chains that benefits both businesses and positions the combined company for future downstream opportunities across high-growth end markets.
Before turning our concluding comments back to Ken, I’d like to comment that from the first meeting nearly 4 months ago, we have both seen this as a merger of opportunities where the sum of the parts create greater benefits than both companies remaining separate. I have found in Ken, a leader that shares a vision and the capability to create greater value and opportunity in this merger. Ken?
Kenneth Lane
President, CEO & Director
Thank you, Peter. The expected cost synergies and integration benefits from this combination are significant and actionable. The companies have identified more than $400 million of value with clear line of sight. Of that, we see $300 million of synergies with much of that achieved in the first 24 months following close. These synergies are expected to come from several areas, including purchasing and raw materials integration, optimization of operations and SG&A savings.
As we’ve said, we also expect to capture more value internally with more than $100 million of additional raw material integration benefits in 2031 due to expiring contracts and Olin stepping in to fill supply. We expect the cost to achieve these synergies to be approximately $150 million to $200 million.
In addition, OlinHuntsman is expected to benefit from approximately $125 million of cash tax benefits from acceleration of tax NOLs, which is not included in the synergy figure. Both Olin and Huntsman have executed complex integrations before, including the Dow Chlorine Products business, where Olin delivered more synergies than originally announced, and Huntsman’s track record of integrating multiple acquisitions of different sizes and complexity over the years. We’ll bring that same discipline and accountability to this combination.
OlinHuntsman is expected to have improved profitability and cash flow through the cycle. As we mentioned earlier, despite a challenging market backdrop on a 2025 pro forma basis, OlinHuntsman would have generated over $900 million of adjusted EBITDA. When including the expected synergies of $400 million, the combined company would have generated approximately $1.3 billion of adjusted EBITDA.
Looking across the 2021 to 2025 period on a pro forma basis, OlinHuntsman would have generated approximately $2.7 billion of average adjusted EBITDA, including the $400 million of synergies. We believe this shows the capability of the combined company to deliver compelling profitability, substantial free cash flow and importantly, greater resilience across varying operating environments.
On the following slide, we provide some more detail on the pro forma financial profile of the business. We expect to have a healthy balance sheet with an evenly weighted maturity profile, no bond maturities before 2029, and an attractive blended cost of debt of approximately 5%. Pro forma year-end 2025 net leverage would have been 4.6 times or approximately 3.2 times with full synergy implementation. And as mentioned earlier, one of our initial priorities for our free cash flow will be to deleverage.
Beyond deleveraging, our cash flow will be an engine of shareholder value creation. First, maintenance capital. We expect to invest approximately $400 million per year on a combined basis to ensure safe and reliable operations. Second, the dividend. We expect to continue a stable dividend policy supported by resilient through-cycle cash flows of the combined company. And with excess cash, we’ll prioritize returning cash to shareholders and pursuing growth projects that meet a high return threshold.
To summarize, this combination is a compelling opportunity for both sets of shareholders today and into the future. Together, Olin and Huntsman will create a greater than $12 billion North American chemicals leader that will better serve customers across diverse and growing end markets. The combination creates a vertically integrated platform with a structurally lower cost position. We’ll approach integration with discipline, including how we segment and manage the combined company so that integrated manufacturing and downstream businesses can each succeed.
OlinHuntsman will benefit from a highly experienced management team with a shared focus on value creation. This strategic combination creates greater resilience, stronger cash generation and a balance sheet that will open multiple avenues for creating value for our shareholders.
Jeffrey Zekauskas
JPMorgan Chase & Co, Research Division
What are the cash costs of achieving the synergies? And for Peter, Huntsman may have had the possibility of combining with an MDI producer. Why was it better over a longer period of time to not wait and look for an MDI opportunity rather than to merge in more of a diversification transaction?
Peter Huntsman
Chairman, President & CEO
Jeff, excellent question. I think that as we look at the MDI industry, I think that you’re probably limited to some degree with various antitrust issues on a global basis. But more importantly than just MDI, which is certainly an important part of our company, but it is certainly not the entirety of our company. And as we look at a transaction that is going to impact our downstream advanced materials, our amines, our MDI, really across the entire supply chain, this has a much greater impact on that than I think just adding more MDI tonnage, being able to have a very competitive North American cost advantage, being able to have integration opportunity in Europe.
And I think that as we look at the growing markets in Asia for both companies, we see opportunities there to leverage existing contracts, existing customer relationships and so forth. So I think there probably would be a space there for an expansion in MDI. But as I look across the board, again, across what is going to have the greatest impact for creating shareholder value across the board, this would have a much greater impact.
June 16, 2026
Olin and Huntsman to Merge
OLIN and HUNTSMAN Announce Transformative Merger of Equals to Create a $12+ Billion Integrated North American Chemicals Leader


Download as PDFJune 16, 2026 6:00am EDT
Complementary upstream and downstream capabilities to enhance integration and enable the combined company to better create value across cycles, products and regions
$400+ million of identified and actionable cost synergies and integration benefits
Enhanced financial profile and cost position expected to provide greater performance through the cycle, cash flow generation and growth optionality
Ken Lane to serve as Chief Executive Officer and Peter Huntsman to serve as non-executive Chairman of the Board of Directors of the combined company
Joint investor call and webcast scheduled for June 16, 2026 at 8:00 a.m. Eastern Time
CLAYTON, Missouri and THE WOODLANDS, Texas, June 16, 2026 /PRNewswire/ — Olin Corporation (NYSE: OLN) and Huntsman Corporation (NYSE: HUN) today announced that they have entered into a definitive agreement to combine in an all-stock merger of equals to create a leading North American chemicals company. The transaction is expected to generate significant value for shareholders of both companies, with more than $400 million in total identified cost synergies and integration benefits.
The combined organization, which will be renamed OlinHuntsman Corporation (“OlinHuntsman”) following the close of the transaction, will benefit from enhanced scale, scope and expanded chlorine optionality, enabling it to create value across markets and cycles. The vertical integration of Olin and Huntsman’s highly complementary upstream and downstream businesses brings together cost-advantaged North American assets and feedstocks with differentiated formulations and high-value advanced materials. From its global manufacturing platform, OlinHuntsman will deliver to diverse and growing end markets including automotive, construction and infrastructure, and industrial applications. OlinHuntsman will have a structurally lower cost position and an expanded ability to convert advantaged Electrochemical Units production into downstream materials, unlocking more opportunities to grow.
“This combination provides a compelling opportunity for Olin and Huntsman to create a more resilient and value-focused chemicals company anchored in North America,” said Ken Lane, President and Chief Executive Officer of Olin. “Huntsman has built an impressive portfolio of polyurethane systems, formulation technologies and advanced materials serving technical, application-driven end markets. By integrating those capabilities with Olin’s world-scale chemicals assets and operations and identified synergies and benefits, we will create an industry leader with greater flexibility to serve customers across the value chain, generate stronger cash flow across the cycle and pursue opportunities that neither business could fully capture on its own. I’m excited by the opportunity to lead OlinHuntsman and deliver long-term value for our shareholders, customers, employees and communities.”
“As our industry continues to globalize, we compete more today against countries, than companies, trade policies and global supply chains than ever before,” said Peter Huntsman, Chairman, President and Chief Executive Officer of Huntsman. “The opportunities this merger creates enable us to generate greater value for our shareholders, deliver exceptional service and products for our customers and provide greater stability and opportunities for our associates. This merger of equals takes two great companies and creates a much stronger global leader.”
Strategic and Financial Rationale
- Creates a $12B+ North American Chemicals Leader. Together Olin and Huntsman would have 2025 revenue of approximately $12.5 billion on a combined company basis. Complementary portfolios and enhanced geographic footprint, including a significant presence in the U.S. Gulf Coast, will position OlinHuntsman to capitalize on regional sector dynamics. This, along with its presence in Europe and Asia, will enable it to better serve customers across key markets. Olin’s ammunition business, Winchester, will continue to operate as a key business within the combined company, growing its industry-leading brand and deepening its long-term relationships with sporting, law enforcement and military customers.
- Vertical Integration Improves Cost Position. The transaction will combine Olin’s manufacturing and feedstock capabilities, including chlorine and caustic soda, with Huntsman’s downstream products and formulation expertise. This platform will enable OlinHuntsman to grow with customers at multiple points in the value chain, utilize lower-cost producer economics to drive value globally and improve margins and cash flow through a more efficient operating model.
- $400M+ Cost Synergies and Integration Benefits. Olin and Huntsman have identified more than $300 million of cost synergies and integration benefits, with the vast majority realized within 24 months and all expected by the end of year three. These synergies will be driven by purchasing and raw material integration, optimization of operations and SG&A savings. The companies have also identified an additional $100 million of raw material integration benefits starting in 2031. In addition to the $400M+ synergies, OlinHuntsman expects to realize approximately $125 million of cash tax benefits through the acceleration of Net Operating Losses.
- Enhanced Scale and Disciplined Capital Allocation Drive Shareholder Value. The all-stock merger of equals structure will preserve balance sheet strength, and the combination is expected to improve earnings and cash flow generation through the cycle. OlinHuntsman will prioritize disciplined capital allocation focused on deploying maintenance capital to support safe and reliable operations, a stable dividend policy, near-term deleveraging and the deployment of future excess cash toward shareholder returns and high-return organic and inorganic growth projects.
Leadership, Governance and Headquarters
The combined company will benefit from a highly experienced management team and Board of Directors, drawing from both organizations. Upon closing of the transaction, current Olin President and Chief Executive Officer, Ken Lane, will serve as Chief Executive Officer of OlinHuntsman. Current Chairman, President and Chief Executive Officer of Huntsman, Peter Huntsman, will serve as non-executive Chairman of OlinHuntsman’s Board of Directors. Current Huntsman Executive Vice President and Chief Financial Officer, Phil Lister, will serve as the Chief Financial Officer of the combined company.
OlinHuntsman’s Board of Directors will consist of ten members, with equal representation from Olin and Huntsman, including Peter Huntsman and Ken Lane.
To underscore the commitment to deliver on the identified synergies, Todd Slater, current Senior Vice President and Chief Financial Officer of Olin, will serve as Chief Integration Officer of OlinHuntsman, reporting to the Chief Executive Officer. A Strategic Integration Committee of OlinHuntsman’s Board of Directors will oversee the integration and synergy realization.
Upon closing of the transaction, OlinHuntsman will be headquartered in The Woodlands, Texas.
Transaction Details
Under the terms of the agreement, Huntsman shareholders will receive 0.5476 shares in Olin for every one (1) share of Huntsman. Upon completion of the transaction, Olin shareholders will own approximately 54.5% and Huntsman shareholders will own approximately 45.5% of the combined company.
Peter Huntsman further stated, “Ken and I agreed to use an at-the-market exchange ratio using volume-weighted average prices over the trailing 30 days, measured as of the close of June 12, 2026. This delivers a premium to Huntsman’s shareholders relative to the historical averages while reflecting current market conditions. It is also equitable for Olin’s shareholders, smoothing out share price movements from last week’s trading. Looking ahead, our shared focus is on capturing the significant long-term value this transaction creates for both sets of shareholders.”
The transaction has been unanimously approved by the Boards of Directors of both companies and is expected to close in the first half of 2027, subject to the satisfaction of customary closing conditions, including receipt of required regulatory approvals and the approval of Olin’s shareholders and Huntsman’s shareholders.
Advisors
Lazard is serving as financial advisor to Olin, and Cravath, Swaine & Moore LLP and Sidley Austin LLP are serving as legal counsel.
Citi and Morgan Stanley & Co. LLC are acting as financial advisors to Huntsman and Kirkland & Ellis LLP is serving as legal counsel. David Fox & Co. LLC acted as advisor to Huntsman.
Conference Call and Additional Materials
Olin and Huntsman will host a joint investor conference call today at 8:00 a.m. Eastern Time to discuss the transaction.
The conference call will be available via live webcast on the investor relations section of each company’s website at www.olin.com/investors/investors-overview/ and www.huntsman.com/investors, or directly at the following web address:
Associated presentation materials will also be available for viewing on the respective websites prior to the call.
The conference call can also be accessed by dialing:
| Participant Toll-Free Number: | 800-420-1459 |
| Participant Direct/International Number: | 203-518-9861 |
| Conference ID: | OLNHUN |
About Olin
Olin Corporation is a leading vertically integrated global manufacturer and distributor of chemical products and a leading U.S. manufacturer of ammunition. The chemical products produced include chlorine and caustic soda, vinyls, epoxies, chlorinated organics, bleach, hydrogen, and hydrochloric acid. Winchester’s principal manufacturing facilities produce and distribute sporting ammunition, law enforcement ammunition, reloading components, small caliber military ammunition and components, industrial cartridges, and clay targets.
Visit www.olin.com for more information on Olin Corporation.
About Huntsman
Huntsman Corporation is a publicly traded global manufacturer and marketer of diversified chemical products with 2025 revenues of approximately $6 billion from our continuing operations. Our chemical products number in the thousands and are sold worldwide to manufacturers serving a broad and diverse range of consumer and industrial end markets. We operate more than 55 manufacturing, R&D and operations facilities in approximately 25 countries and employ approximately 6,000 associates within our continuing operations. For more information about Huntsman, please visit the company’s website at www.huntsman.com.
June 7, 2026
Huntsman Sells Gomet to Trelleborg
Huntsman Sells its Italian Based Automotive Aftermarket Business
Download as PDFJune 05, 2026 9:14am EDT
THE WOODLANDS, Texas, June 5, 2026 /PRNewswire/ — Huntsman Corporation (NYSE: HUN) announced today that it has sold Huntsman Gomet, a business located in Azeglio, Italy, to Trelleborg Group for €42.5 million (approximately $50 million), subject to customary post-closing adjustments. Gomet is a manufacturer of molded rubber and thermoplastic automotive aftermarket components, which was a business within Huntsman’s Polyurethanes division, and was acquired by Huntsman in 2014 as part of the Rockwood acquisition. In 2025, Gomet generated revenues of approximately €24 million. The proceeds from this transaction will be used to reduce outstanding borrowings.
Houlihan Lokey served as financial advisor and Freshfields LLP served as legal counsel to Huntsman Corporation.
 Everchem Updates Archive
 Sign Up for Email Updates