
The Urethane Blog
September 8, 2023
CertiPUR-US® Program Begins Certifying Biobased Foams
Future Foam, FXI, NCFI Polyurethanes and Kuka Home are first foam producers to offer CertiPUR-US® certified 25% biobased foams

(Rochester Hills, Mich. – September 8, 2023) The CertiPUR-US® foam certification program is now certifying biobased slabstock flexible polyurethane foam. To achieve biobased foam certification, foams must meet all current criteria for foam certification and contain a minimum of 25% biobased content.
U.S.-based foam producers Future Foam, FXI, NCFI Polyurethanes and Mexico-based Kuka Home are the first to offer CertiPUR-US certified biobased foam, having participated in the pilot program which was launched earlier this year.
“We praise the foam producers who are early adopters and expect many other foam producers to follow,” said CertiPUR-US Executive Director Michael Crowell. “We are confident that bedding and upholstered furniture manufacturers will see the tremendous environmental and marketing benefits in using biobased foam and will create demand for this category of certified foams.”
All certified foams must undergo emissions testing, chemical analysis and physical property testing to meet the rigorous standards set forth in the program’s Technical Guidelines. In addition, all biobased foams are tested by Beta Analytic laboratories in Miami to determine the percentage of biocontent.
Beta Analytic, an ISO/IEC 17025:2017 accredited laboratory, provides radiocarbon dating and biobased testing services. The biobased content of product ingredients is based on the ASTM D6866-22 Method B standard, which uses an Accelerator Mass Spectrometer (AMS) instrument to measure how much of the carbon within a product is derived from biomass. The result indicates the percentage of the product’s biobased carbon versus fossil-derived carbon.
Certified biobased foams will have permission to use an exclusive, new CertiPUR-US logo, which will be an easily recognized adaptation of the current CertiPUR-US logo and only used in association with products that contain certified biobased foams.
As with all certified foams, once a biobased foam is certified, it must be recertified six months later and annually thereafter. Random verification testing is conducted by the CertiPUR-US program to ensure continued compliance. Producers and their customers also must agree to new Terms of Use, which establish guidelines on how a CertiPUR-US biobased foam may be marketed.
The CertiPUR-US program, now celebrating its fifteenth year, is administered by a nonprofit organization. For more information about certified biobased foam and to contact foam producers currently offering certified biobased foam, visit certipur.us/biobased.
www.certipur.us
September 5, 2023
The perpetual truck driver shortage is not real
Number of trucking carriers has increased 45% since July 2019
Craig Fuller, CEO at FreightWaves
· Tuesday, September 05, 2023

Listen to this article
0:00 / 5:04BeyondWords
The seemingly perpetual marketwide truck driver shortage is not real, nor is it marketwide. While specific fleets can and do have driver shortages — i.e., unseated trucks — the trucking market quickly corrects.
There also are periods of capacity shortages, but those get addressed very quickly by the market.
With no barriers to entry, almost anyone can create a trucking company. That is exactly what has happened over the past four years.

Operating authority for motor carriers of property issued by the Federal Motor Carrier Safety Administration grew by 45% from July 2019 to August 2023, according to FreightWaves SONAR’s latest data, released in partnership with Carrier Details. Truckload demand as measured by the SONAR Outbound Tender Volume Index (OTVI) is only up about 11% during the same period.
The current difficult conditions in trucking are a result of too much capacity chasing too little freight.
Where does the perpetual driver shortage myth come from?
Generally speaking, the driver shortage myth stems from larger trucking companies that find it difficult to recruit drivers into their fleet operations. After all, fleets have to compete for truck drivers with other trucking companies. In addition, some licensed truck drivers go to work in other sectors of the economy, like construction and warehousing. But the fleets also have to compete against the growth of independent operators.
The American Trucking Associations propagates the narrative of the shortage. ATA members consist of midsize and large trucking fleets, which have increasingly become a smaller percentage of the trucking industry’s total capacity.
The ATA’s membership dues are indexed based on company size. For example, a large fleet with $4 billion in revenue will pay a much larger fee than a carrier with $50 million in revenue. Moreover, the ATA is a trade association and lobbying organization, which seeks to influence Congress when it considers legislation that impacts the trucking industry.
As the ATA encourages Congress to pass laws and appropriations that fund employee driver training and recruitment programs — while minimizing regulations that favor larger trucking fleets that employ drivers rather than independent owner-operators — it helps to paint a picture of a perpetual driver shortage.
After all, if Congress realized how fast capacity enters the market from independent operators when there is a capacity crunch, it would mitigate the need for employee driver recruitment and retention entitlement programs.
The FMCSA data tells the story about the growth of the small independent fleet
SONAR, FreightWaves’ proprietary data platform, collects data from a number of sources, including the FMCSA, the regulatory body that oversees the trucking industry. One of the FMCSA’s data sets tracks fleet registrations by the number of trucks that are assigned to a particular fleet.
SONAR breaks down the fleet sizes into cohorts to provide a more accurate reflection of the growth and fragmentation of trucking fleets.
In the SONAR chart below, the white line is the total number of tractors among fleets of one to six trucks; the purple line is the total number of tractors among fleets of seven to 11 trucks; the yellow line is the total number of tractors among fleets of 12 to 19 trucks; the blue line is the total number of tractors among fleets of 20 to 100 trucks; the orange line is the total number of tractors among fleets of 101 to 999 trucks; and the green line is the total number of tractors among fleets of 1,000 trucks and more.

Of the 2.9 million trucks in the market, 1.2 million are in fleets with more than 100 trucks — or just 41%. In 2010, fleets with more than 100 trucks comprised 54% of total trucking capacity.
Midsize and large fleets have problems recruiting new employee drivers, often due to lifestyle issues. Many drivers do not want to be away from home for days or weeks at a time, especially in a forced dispatch operation, which is typical of truck driver fleet operations.
For truck driving entrepreneurs who want to have the autonomy of their own operations, no such challenges exist. After all, if you want to dictate which loads make sense for you, based on destination, time in transit or even commodity, you can do so as an independent trucker with far more control than an employee fleet driver. Therefore, independent owner-operator entrepreneurs are constantly entering the market.
With the barriers to entry for new fleets becoming increasingly less burdensome, the number of smaller fleets in the industry will continue to grow. I broke down this phenomenon last week in an article on the growth of mom-and-pop trucking companies.
A downside to this trend? It is likely that boom and bust cycles in trucking become more pronounced and violent.
But for now, a capacity correction is underway and this is welcome news for everyone in the trucking industry.
August 31, 2023

August 31, 2023
Recticel Half Year Results 2023
Regulated information, Brussels, 31/08/2023 — 06:59 CET, 31.08.2023
- Net sales decrease from € 287.2 million in 2022 to € 266.1 million (-7.4%) in 2023
- Adjusted EBITDA: from € 31.7 million to € 18.2 million (-42.6%)
- Result of the period (share of the Group): from € 34.6 million to € 2.2 million
- Net cash position: € 142.3 million (31 December 2022: net financial debt of € 250.0 million; 30 June 2022: net financial debt of € 256.2 million)
- Agreement reached on the divestment of the 33% share in Orsa Foam
Sales and profits have been disappointing in the first half of 2023. Recticel is entirely dependent on the European construction markets, which have remained very challenging in most segments and countries during the period. In the residential markets, new build and renovation activities have been seriously impacted by a combination of high inflation and interest rate increases, weighing on disposable income. In the industrial and commercial markets, fewer projects were launched and some have been postponed. These market trends have been observed in most European countries, with the notable exception of France, which has remained quite dynamic.
As a consequence of these subdued markets, our volumes have been lower year-on-year by more than 15%, in a context of substantial competition leading to price deflation and pressure on margins.
After the closing of the Engineered Foams divestment to Carpenter on 12 and 13 June 2023, and the subsequent € 142.3 million net cash position, several acquisition opportunities are being pursued and progressing well, which will enhance our market and segment positions in Europe.
OUTLOOK
Input costs of chemicals, steel, and to a lesser extent mineral wool have decreased, which should create the conditions for volume growth going forward. Although still volatile, we see improvements in the demand, particularly in Insulated Panels.
In this context, we expect our full year 2023 Adjusted EBITDA to reach between € 40 and 45 million.
https://www.recticel.com/recticel-half-year-results-2023.html
August 31, 2023
European Auto Sales Rose 17% In July, Marking 12th Consecutive Month Of Gains
by Tyler Durden
Thursday, Aug 31, 2023 – 04:15 AM
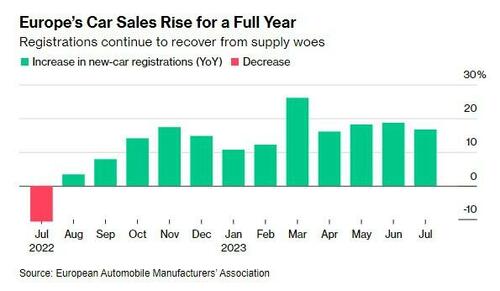
European vehicle sales are going to be on watch heading into the back half of the week after automobile sales in Europe rose for the 12th consecutive month in July, Bloomberg reported this morning.
Germany, France and Spain all saw double digit growth for the month, the report says. In sum, registrations of new cars were up 17% to 1.02 million vehicles, the report says, citing data from the European Automobile Manufacturers’ Association.
Volkswagen sold the most passenger cars in the region with 280,294 registrations, up 19% from a year prior. Buyers in Germany saw the biggest YOY rise, with 48,682 cars sold in July, up 69% from 2022.
Battery electric cars led the charge across Europe, rising 62%, at the same time sales of diesel models fell 9%.
As we have reported, Tesla’s Model Y was the best selling vehicle in Europe in the first half of the year, but manufacturers like Volkswagen AG, Stellantis NV and BMW AG are setting up to challenge the EV maker’s dominance with new model releases in the second half of the year.

Several of these models are expected to debut at next week’s IAA car show in Munich, Bloomberg wrote.
After battling through endless supply chain challenges and dealing with a semiconductor shortage as a result of the pandemic, automakers are finally seeing operations resemble a return to normal in 2023.
However, new challenges for the industry include a worldwide rising cost of living and higher borrowing costs, with Central Banks hiking interest rates far higher than during the pandemic.
https://www.zerohedge.com/markets/european-auto-sales-rise-17-july
 Everchem Updates Archive
 Sign Up for Email Updates

