
The Urethane Blog
November 3, 2025
Covestro AG (COVTY) Q3 2025 Earnings Call Transcript
Oct. 30, 2025 12:36 PM ETCovestro AG (COVTY) Stock, CVVTF StockCOVTY, CVVTF
Covestro AG (OTCPK:COVTY) Q3 2025 Earnings Call October 30, 2025 10:00 AM EDT
Company Participants
Ronald Kohler – Head of Investor Relations & Corporate Controlling
Christian Baier – CFO & Member of Management Board
Carsten Intveen – Investor Relations Director
Christian Baier
CFO & Member of Management Board
Thank you, Ronald, and good afternoon, everybody. I would like to start my presentation with some insights into a recent acquisition. Following the successful completion of the purchase of Pontacol in Q3 2025, Covestro has signed another value-accretive transaction, which is expected to close in Q1 2026, depending on regulatory approvals. This deal will also benefit our Solutions & Specialties segment with the acquisition of 2 HDI derivative production facilities from Vencorex in Rayong, Thailand and Freeport in the U.S.
This strategic move enhances Covestro’s global aliphatics production footprint in attractive growth regions, particularly the U.S. and Asia Pacific. Aliphatics isocyanates are essential raw materials for light stable coatings, paints and adhesives, primarily used in the mobility sector, but also in construction and furniture applications. The acquisition strengthens Covestro’s position in the coatings and adhesives market, expanding its capacity to meet customer demand across key regions.
After Solutions & Specialties, we now turn to the Performance Materials segment. Sales declined 16.2% year-over-year, driven by negative contributions of 9.8% from pricing, 3.3% from FX and 3.1% from volumes. The volume reduction was primarily attributable to production disruptions in TDI and basic chemicals stemming from the Dormagen incident. Quarter-over-quarter, sales declined in EMLA and North America, while APAC was flat. The Q3 ’25 EBITDA of EUR 174 million is higher year-over-year, mainly due to an increase and — mainly due to an insurance reimbursement and cost savings, while pricing delta, volume and FX all contributed negatively.
Sebastian Bray
Joh. Berenberg, Gossler & Co. KG, Research Division
I have 2, please. The first to come back on Dormagen. Is this done in January of ’26, the plant is fixed and everything goes back online? Or is it not quite that simple? And my second question was on the comments around September mark-to-market pricing for key products implying about EUR 750 million of EBITDA for the year FY ’25. And I’m looking at MDI, a little bit of polycarbonate and some other commodity prices, and these all appear to have deteriorated significantly in excess of raw material prices through October. If you were to perform the same analysis again with mark-to-market October prices, is EUR 700 million a more reasonable figure? Or does it not differ very much?
Christian Baier
CFO & Member of Management Board
Yes. Thank you, Sebastian, for your questions. Happy to address those. I think with respect to Dormagen, it is basically a multifold analysis that is being done. We already have ramped up parts of the various production entities. I think the key one was to restore relevant parts of the power supply in order to also ramp up trains on various of the subproducts. But just answering specifically your question, no early in January ’26, this is not all going to be fixed at that point of time, but we will be ramping up throughout that year on the key products in order to then basically come back to full TDI availability at that point of time, but we’re very confident together with the external partners that are important here also on that external fire incident to ramp up reasonably quickly at that point of time.
With respect to the September mark-to-market, yes, certainly, there is always some fluctuations between the various months, but we very much remain confident with the guidance range that we have narrowed today of this also being the relevant one to look at for the full year outlook also on the back of current trends that we see in the last couple of weeks.
Sebastian Bray
Joh. Berenberg, Gossler & Co. KG, Research Division
Could I just follow up on this? So we’re comparing Q4 versus Q3, I appreciate there are various bits and pieces of noise around semiconductor supply to automotive in Europe and so on. But it is notable how much some of these prices have declined, let’s say, October versus year average — versus quarter average for quarter 3. Is this because one who are ramping up further MDI supply? Is it entirely demand led? What is your own view on why prices are seemingly weak in October?
Christian Baier
CFO & Member of Management Board
Yes. Well, as we are not commenting then on competition, but what we basically see is some headwinds certainly on the products that you quoted. It’s in the end a combination of various factors that we see there. There certainly is demand development that also from a seasonal perspective is ramping in, providing some pressure. And given that we have seen some additional volumes in this year, hitting that demand situation, supply-demand certainly is something to be improving over time. But at the moment, that’s the balance that we see. And still, it’s consistent with our expectations for the full year.
November 3, 2025
Stepan Company (SCL) Q3 2025 Earnings Call Transcript
Oct. 29, 2025 2:06 PM ETStepan Company (SCL) StockSCL
Q3: 2025-10-29 Earnings Summary
EPS of $0.48 misses by $0.14
| Revenue of $590.28M (7.94% Y/Y) misses by $3.37M
Stepan Company (SCL) Q3 2025 Earnings Call October 29, 2025 9:00 AM EDT
Company Participants
Ruben Velasquez – VP & Chief Financial Officer
Luis Rojo – President, CEO & Director
Luis Rojo
President, CEO & Director
Thank you, Ruben. Good morning, and thank you all for joining us today to discuss our third quarter 2025 results. I plan to share highlights of the quarterly performance and we will also share updates on our key strategic priorities, while Ruben will provide additional details on our financial results.
We delivered 9% adjusted EBITDA growth through the first 9 months of 2025, bringing year-to-date adjusted EBITDA to $165 million.
These results were restrained by the significant increase in oleochemical raw material prices, which continues to impact Surfactant margins and by higher start-up costs related to our new Pasadena, Texas facility.
We remain focused on gradually recovering our margins and keeping a healthy balance between volumes and margins. Third quarter adjusted EBITDA was $56 million, up 6% year-on-year.
Specialty Products adjusted EBITDA increased significantly, driven by favorable order timing within the pharmaceutical business.
Polymers delivered volume growth across rigid polyols and commodity PA, while EBITDA was slightly lower due to unfavorable mix and margin pressures.
Surfactant adjusted EBITDA declined versus the prior year, driven by higher Pasadena start-up costs, oleochemical raw material cost inflation and lower demand within our global commodity consumer products end market.
Total company sales volumes grew 1%, with Polymers up 8% and our NCT product line up 26%, while Surfactants volume declined 2%. In Surfactants, we continue to experience double-digit volume growth within the crop productivity business and mid-single-digit growth in the oilfield end market.
This growth was offset by lower demand within the global commodity consumer products end market. North America Rigid Polyol and commodity PA volumes were both up double digits, while European Rigid Polyol volumes continue to be impacted by macroeconomic uncertainties and low construction activity.
Despite a very challenging environment for the chemical sector, we remain encouraged by the volume growth across several of our key strategic end markets.
We finished the third quarter of 2025 with $10.9 million of adjusted net income, down 54% versus the prior year, largely reflecting a higher effective tax rate, higher interest net and higher depreciation, none of which had cash impact.
Free cash flow was positive at $40 million during the quarter, driven by reduced working capital and disciplined capital spending. During the third quarter of 2025, the company paid $8.7 million in dividends to shareholders.
Ruben Velasquez
VP & Chief Financial Officer
This was partially offset by improved product and customer mix. Moving to Slide 8, Polymers net sales were $143.9 million for the quarter, a 4% decrease versus the prior year.
Selling prices decreased 14%, primarily due to the pass-through of lower raw material costs and competitive pressures. Sales volume increased 8% in the quarter.
North America Rigid Polyol volume grew double digits and our commodity Phthalic Anhydride business continued to deliver strong growth.
Global Specialty Polyols volume grew mid-single digits despite the continued challenging overall environment.
European and China Rigid Polyols volume was impacted by softer demand across their respective regional end markets.
Luis Rojo
President, CEO & Director
Thank you, Ruben. I will focus my comments on our strategic priorities. Our customer will always remain at the center of our strategy and innovation efforts.
Our Tier 1 customer base remains a solid foundation of our business. Continuing our new customer acquisition within Tier 2 and Tier 3 customers remains a key priority. This is an important and profitable growth channel within our Surfactant business. For the third quarter of 2025, our volume grew low single digits year-over-year, and we added over 350 new customers.
Our end market diversification strategy remains a key focus area. For the third quarter, we continue to see a strong growth in our crop productivity and oilfield businesses. We are pleased to see our North America Rigid Polyol business continue to deliver year-over-year growth.
This growth was enhanced by our new product introduction in the growing spray-foam end market. Our supply chain operation and resiliency continue to improve, and we delivered another solid quarter in all our key operational metrics.
Michael Harrison
Seaport Research Partners
All right. And then over on the Polymers business, just a couple of questions here. First of all, do you believe that there is pent-up demand in the commercial roofing and commercial insulation space? And I’m curious, do you think that lower interest rates could help to stimulate some additional activity there?
Luis Rojo
President, CEO & Director
[ Fully aligned ] Mike. There is — we believe there is a lot of pent-up demand from all the construction that happened in the early 2000. I mean if you look at all the construction that happens in industrial construction, warehousing, plants, flat roofs in early 2000, which was a huge peak a lot of those buildings need renovation in the next 5 years.
We’re aligned 100% with the belief from some of our customers that all that reroofing needs to happen. It’s not going to happen overnight, but it needs to happen and PIR insulation is the preferred choice for all those flat roof projects coming up.
And you are 100% right that, I mean, we should see another interest rate reduction today, 98% probabilities now of an interest rate reduction in December Fed meeting.
So we believe 2026 will give us some upside on the construction activity if the interest rate continues the way they are and inflation rates continues the way they are, right? I mean we need shelter and rental inflation to keep coming down so we can achieve — so the Fed can achieve their 2% inflation target.
Michael Harrison
Seaport Research Partners
All right. And just to follow up on Polymers. From the margin side, I believe you mentioned that unit margins are down, the pricing was down quite a bit. You referred to some competitive dynamics that are challenging. Is your expectation that if we started to see some recovery in demand that we would also see some recovery in unit margins as well?
Luis Rojo
President, CEO & Director
Look, I mean, we’re happy — look, we always can improve our margins, right? But if you look at the first 9 months of the Polymers business, we were able to grow EBITDA modestly, very little, but modestly, we were able to grow despite sales down. So EBITDA margins are improving slightly in the Polymers business despite everything that is going on in Europe and especially in Europe, which is a very tough situation.
So we believe we want to grow the top line. We want to grow the volumes, and we need to keep inching up the margins as we drive scale. I mean, the benefit of higher volumes and scale should improve our margins, but we are not planning a significant increase. But we’re happy with the margins that we have, and we need to continue inching those up as we grow our business. And we had a negative impact on margin as we grow PA and as we grow in some of the other markets because those are typically a mix impact to the overall Polymers business.
David Storms
Stonegate Capital Partners, Inc., Research Division
I wanted to start, you mentioned on the call, spray foam has really been a nice driver for you in the Poly section. Could we — I guess my question is, how much more room for growth do you think there is there? And could we maybe see a second wave of growth if the European environment improves?
Luis Rojo
President, CEO & Director
Great question, Dave. Look, we have talked about spray foam in the past few quarters. We’re serious about this end market. We have developed great technologies and products to serve the high-growth margin, and we started this year. So I’m pleased with what the team has delivered and with the benefits that we are starting to get.
This is very early. And it’s a good market. It’s a good market that has a lot of potential to grow not only in the U.S., eventually in Europe in the future. But we are happy with our participation, and we need to grow more share. We are starting. We are starting from almost 0 share, and we are committed to continue investing and developing this business. And when you think about Europe, of course, we had higher expectations of our European region to start growing more on the construction activity.
And when you think about the war in Ukraine and all of those things, the reality is that construction activities are very muted still in the European region. Now as interest rates come down, as they keep focusing on energy conservation, which is a huge issue in Europe and the biggest opportunity is to consume — is to reduce the consumption of energies in the buildings. So we believe the market trends are there for the future. It’s not going to happen in the short term for sure. But we believe this is a good industry for the next 3 and 5 years, and we are committed to continue investing and to continue growing our European Polymers business.
https://seekingalpha.com/article/4834892-stepan-company-scl-q3-2025-earnings-call-transcript
November 2, 2025
Former Carpenter CEO Stan Pauley Inducted Into Hall of Fame
Stanley F. Pauley, former CEO and chair of Richmond, Virginia-based Carpenter Co., was posthumously inducted into the American Home Furnishing Hall of Fame on Oct. 26.
He, along with Jeffrey S. Child, president of R.C. Willey Home Furnishings; William A. Hinks, founder and chair of Furniture Mart USA; and Norman Waxman of Norman Waxman Consulting, joined the 139 members of the Hall of Fame.
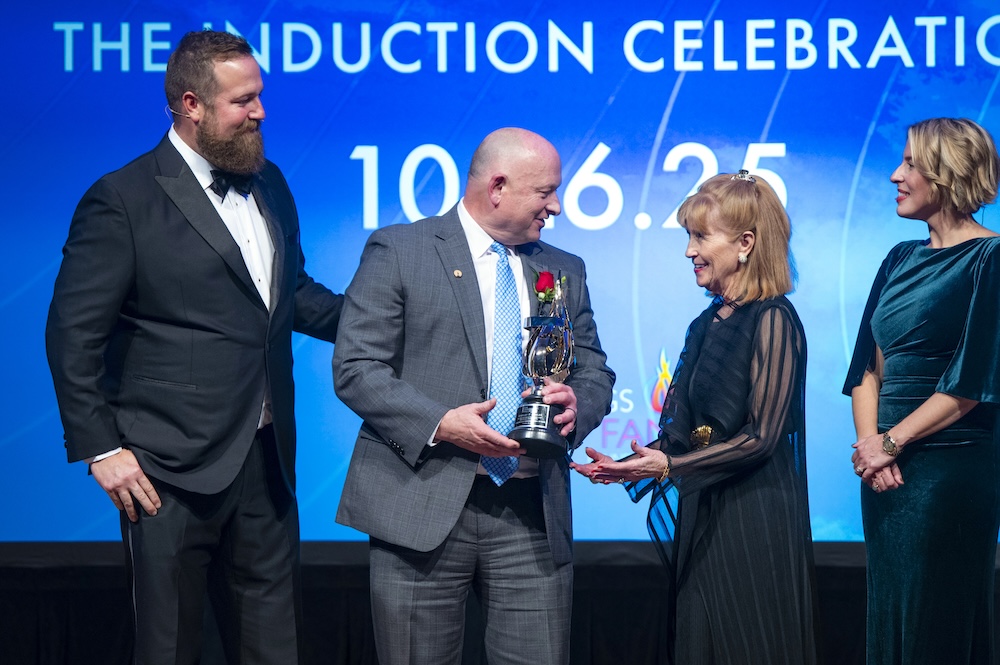
The induction began with a pinning ceremony at noon at the American Home Furnishings Hall of Fame building in High Point. The new Hall of Fame members have plaques on the Wall of Fame and named bricks will be placed in the Walk of Fame in front of the building.
The day concluded with an induction celebration and dinner at the Sheraton Greensboro Four Seasons, hosted by Erin and Ben Napier, authors, business owners and stars of HGTV’s “Home Town” and other shows.
Brad Beauchamp, president and CEO of Carpenter, spoke on Pauley’s behalf.
Pauley was born in Winnipeg, Canada, and grew up during the Great Depression. “He knew what it was like to make do with what was available and to appreciate what resources he had available to him,” Beauchamp said. “He also learned the value of hard work, and he exhibited those qualities throughout his life, continuing to lead the company until shortly before he passed away in November 2020 at the age of 93.”
An engineer by training, Pauley guided many of the innovations that became standards in the foam and fiber industry, including the continuous pouring of polyurethane foam, Beauchamp said.
“He was never afraid to invest in the business, believing that we needed to be moving forward, and that to stay stationery was to fall behind,” Beauchamp said. “Stan’s career at Carpenter spanned more than 60 years. Just imagine giving your time, talent, energy, and enthusiasm to a pursuit for that length of time. It truly shows his love for the business and an enjoyment he received from being active and engaged with Carpenter.”
Carpenter appreciates the recognition bestowed upon “someone who has had such an outsized impact on the industry,” Beauchamp said. “We thank you very much for this honor.”
https://bedtimesmagazine.com/2025/10/former-carpenter-ceo-inducted-into-hall-of-fame
October 30, 2025
Covestro trims full-year guidance, says ADNOC deal on track to close in Q4
October 30, 20253:06 AM EDTUpdated 6 hours ago

Covestro AGOct 30 (Reuters) – German chemicals maker Covestro (narrowed its full-year core profit forecast on Thursday due to soft demand, but said its financial stability would be secured as the $17 billion takeover by Abu Dhabi state oil firm ADNOC is set to close in the fourth quarter.
Covestro, which had already cut its outlook twice this year, now sees its yearly earnings before interest, taxes, depreciation and amortization between 700 million and 800 million euros ($816 million and $933 million). Its previous forecast was for the EBITDA to come in a range of 700 million to 1.1 billion euros.
Get a daily digest of breaking business news straight to your inbox with the Reuters Business newsletter. Sign up here.
The company, whose products include foam chemicals used in mattresses, car seats and insulation for buildings, had said earlier this year that the prospect of higher U.S. tariffs was leading to a huge oversupply of products to the market there, particularly from the Asia-Pacific region, which had then caused a big drop in prices.
Covestro also said on Thursday that a fire at an external substation in Dormagen, Germany would have a negative impact in a low three-digit million euro range for the full year.
Its third-quarter EBITDA fell 15.7% to 242 million euros, beating an analysts’ average estimate of 183 million euros in a company-provided consensus.
CLOSING OF ADNOC’S TAKEOVER ON TARGET
Regulatory approvals for the takeover by ADNOC, currently being examined by the European Commission, are progressing as expected and the deal is on track for closing in the final quarter of the year, the company said.
The EU regulator was concerned that ADNOC, in its biggest acquisition yet and one of the largest foreign takeovers of an EU company by a Gulf state, may be using state subsidies to acquire the chemicals company.
($1 = 0.8575 euros)
Reporting by Bartosz Dabrowski in Gdansk, editing by Milla Nissi-Prussak
October 29, 2025
BASF SE (BASFY) Q3 2025 Earnings Call Transcript
Oct. 29, 2025 6:11 AM ETBASF SE (BASFY) Stock, BFFAF StockBASFY, BFFAF

BASF SE (OTCQX:BASFY) Q3 2025 Earnings Call October 29, 2025 3:30 AM EDT
Company Participants
Stefanie Wettberg – Senior Vice President of Investor Relations
Markus Kamieth – CEO & Chairman of the Board of Executive Directors
Dirk Elvermann – Member of the Board of Executive Directors, CFO & Chief Digital Officer
Markus Kamieth
CEO & Chairman of the Board of Executive Directors
Yes. Thank you, Stefie. Good morning, everyone. Dirk and I welcome you to our Q3 conference call. In the third quarter of 2025, market dynamics for the chemical industry continued to be challenging. Upstream margins were still under pressure and customer buying behavior in almost all industries and regions remained cautious. Even in this demanding environment, BASF earnings came in slightly above market expectations and only slightly below the level of the prior year quarter.
Let’s start with a closer look at the sales performance of BASF Group compared with the prior year quarter. Overall, sales declined slightly on account of strong currency headwinds and lower prices. We were, however, able to achieve slightly higher volumes due to growth in the Surface Technologies, Chemicals and Materials segments.
From a regional perspective, we recorded 12% volume growth in China, slightly — slight volume growth in South America and fairly flat volume development in Europe. In North America, volumes were slightly down.
Compared with the prior year quarter, prices declined in 4 out of our 6 segments, particularly in Chemicals. In the Surface Technologies and Nutrition & Care segments, we managed to achieve price increases. Currency effects dampened sales in all divisions and were mainly related to the strong depreciation of the U.S. dollar, Chinese RMB and the Indian rupee. Portfolio effects slightly supported sales growth. Reflecting this underlying sales development, EBITDA before special items came in at over EUR 1.5 billion compared with EUR 1.6 billion in the prior year quarter.
Here is a snapshot of how the markets and our segments’ volumes and specific margins developed in the third quarter. Due to a continued imbalance between supply and demand and the resulting pressure on margins, the business environment in our upstream segments remained challenging. Despite these market headwinds, the Chemicals segment achieved solid volume growth in both divisions. However, the segment faced significantly lower prices and sharply reduced specific margins.
The Materials segment recorded slightly higher volumes despite the difficult market environment due to higher volumes in Monomers and stable volume development in Performance Materials. Prices declined in both divisions. However, our overall margins in the segments were lower driven by the Monomers division.
I will now give a short update on our Verbund side in South China. Let me begin with what we communicated at the recent Capital Market Update in Antwerp. We will complete this mega project with capital expenditures around EUR 1.3 billion lower than originally planned. We achieved this CapEx reduction through tight budgetary discipline, scope changes and excellence in procurement.
As a result of the currently long markets in China, we will have a slower-than-anticipated ramp-up of the overall earnings contributions. In the coming years, we expect most markets and value chains to rebalance. We, therefore, confirm the targeted EBITDA before special items of EUR 1 billion to EUR 1.2 billion by 2030.
Now this slide illustrates the impressive progress the Zhanjiang team has achieved since May. This includes the successful mechanical completion of the steam cracker and downstream petrochemical plants. The infrastructure and utility plants are already in steady operation. Additionally, we have safely and successfully started up various downstream plants, including butyl acrylate, 2-ethylhexyl acrylate, formaldehyde, neopentyl glycol and glacial acrylic acids with more start-ups to come. Thus, we are transitioning the project from construction to operational readiness. These achievements mark steady progress towards the site’s full operational start-up at the end of 2025.
 Everchem Updates Archive
 Sign Up for Email Updates