
Company News
September 29, 2026
OCI to Exit TDI Production and Sales
South Korea’s OCI announced its withdrawal from the TDI business, and will cease production and sales from December 18.
2026-09-29 15:07:48Source: Toocle Headlines
On September 29, 2026, South Korea’s OCI announced that its board of directors had approved the termination of the toluene diisocyanate (TDI) manufacturing and sales business, and plans to officially cease relevant production and sales from December 18, 2026. OCI’s current TDI production capacity is approximately 50,000 tons per year.
According to the announcement, OCI’s TDI business achieved sales of approximately 117.947 billion Korean won in 2025, accounting for 5.87% of the company’s consolidated sales. The company stated that the exit from TDI is mainly to “sort out marginal businesses and improve profitability”, and it will enhance corporate and shareholder value by optimizing the business portfolio, rather than packaging and selling the plant.
OCI also reminded that the specific suspension date may be adjusted according to the progress of the exit. With its withdrawal from the TDI sector, the execution of existing orders, inventory digestion and the supply pattern of TDI in the Asia-Pacific region and globally deserve continuous attention.
September 22, 2026
BASF Studying Indian MDI Project
BASF India evaluates MDI investment in Dahej, Gujarat
4 min read·Published on Sep 21, 2026 · 1:35 PM IST

BASF India Limited, a prominent player in the chemical industry, has announced plans to potentially expand its operations in India with a significant investment in methylene diphenyl diisocyanate (MDI) production. The company, under the broader umbrella of BASF SE, is considering the establishment of an MDI production complex in Dahej, Gujarat. This decision is part of BASF’s ongoing commitment to address increasing customer demand in the region.
The company disclosed that it is in the advanced stages of conducting a feasibility study concerning this new venture. As part of this potential expansion, BASF India has already secured an industrial land parcel in Dahej through its subsidiary, BASF India Polyurethanes Private Limited. The outcome of this study, alongside necessary regulatory approvals, will ultimately dictate the final investment decision.
MDI, a crucial component in the manufacture of polyurethane products, is instrumental across various industries. It plays a significant role in applications ranging from building insulation and refrigeration systems to automotive parts, furniture, and consumer goods. This development aligns with BASF’s strategic vision to bolster its production capabilities in response to the dynamic needs of these sectors.
BASF’s consideration of expanding its MDI production capacity underscores the importance of the Indian market in the company’s global strategy. The investment, if approved, would not only support BASF’s growth ambitions but also contribute to the technological and industrial advancement of the Indian chemical sector.
This announcement reflects BASF’s strategic foresight in identifying growth opportunities and its dedication to enhancing its service offerings tailored to regional market demands. As BASF continues its feasibility study, stakeholders will be keenly observing developments, anticipating a positive outcome that could further cement the company’s presence in India.
https://businessupturn.com/business/basf-india-evaluates-mdi-investment-in-dahej-gujarat
September 21, 2026
Kumho R&D Plans
Kumho Petrochemical boosts R&D spending despite downturn, targets high-value and eco-friendly materials
Sep 21, 2026, 09:53 am
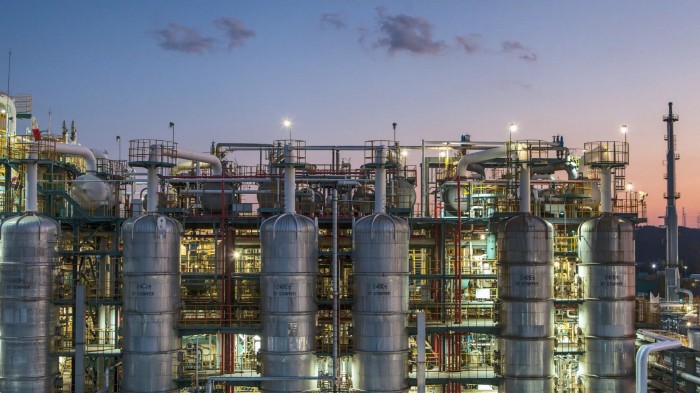 |
| A view of Kumho Petrochemical’s Ulsan rubber plant. / Kumho Petrochemical |
Kumho Petrochemical Group is turning to research and development to weather the prolonged downturn in the petrochemical industry. Rather than expanding output of commodity products, the group plans to increase the share of high-value specialty and eco-friendly materials while broadening research into new areas such as next-generation batteries to secure both profitability and future growth.
According to Kumho Petrochemical Group on Sept. 21, major affiliates including Kumho Petrochemical, Kumho P&B Chemicals, Kumho Mitsui Chemicals and Kumho Polychem are concentrating their R&D capabilities on upgrading existing core products, developing eco-friendly processes and advancing materials for future mobility.
Kumho Petrochemical is strengthening its competitiveness in high-performance synthetic rubber, particularly solution styrene-butadiene rubber, or SSBR, used in tires for electric vehicles and other applications. The company completed a 35,000-ton capacity expansion last year and began commercial production. SSBR improves tire durability, fuel efficiency and wear performance, and demand is expected to rise alongside growth in the electric vehicle market.
In the environmental sector, the company has built carbon capture, utilization and storage facilities capable of capturing about 76,000 tons of carbon dioxide annually. It has also developed technology to convert recycled ABS recovered from discarded home appliances into materials for automotive interiors. The company expects the material to meet automotive standards for heat resistance and impact strength while reducing carbon emissions by about 16%.
Kumho Petrochemical is also expanding beyond conventional petrochemicals into battery materials. The company is participating with POSCO Future M and BEI in the development of next-generation anode-free lithium-metal batteries.
Kumho P&B Chemicals is expanding its eco-friendly product lineup centered on epoxy. The company is developing waterborne epoxy products to reduce volatile organic compound emissions and low-carbon epoxy technologies using bio-based feedstocks. It plans to combine equipment investment with certification efforts to meet demand for eco-friendly materials in construction, shipbuilding, electrical and electronics industries.
Kumho Mitsui Chemicals is pursuing higher-value products while expanding production capacity for methylene diphenyl diisocyanate, or MDI, a key raw material for polyurethane. From December last year through the end of this year, the company is carrying out a 100,000-ton annual debottlenecking investment that will raise total capacity to 710,000 tons. It is also developing bio-content polyurethane systems, lightweight materials for automotive seats and products for high-performance sound absorption.
Kumho Polychem is focusing on increasing the value of ethylene propylene diene monomer, or EPDM, a specialty synthetic rubber. With the recent addition of a fifth production line with annual capacity of 70,000 tons, the company has established a total annual production system of 310,000 tons. It has also improved productivity and quality stability by applying ultra-low-temperature polymerization technology.
The company is also improving production processes to reduce energy use and carbon emissions, including the introduction of low-pressure chillers and waste-heat recovery systems.
Going forward, Kumho Polychem plans to expand its product lineup into materials that reduce EV driving noise, lightweight materials and thermal-conductive and insulating materials. The aim is to broaden its business from conventional products for automotive parts, hoses and cables into high-value materials for eco-friendly mobility.
Kumho Petrochemical Group plans to reduce its dependence on petrochemical market cycles by strengthening the technological competitiveness of core products such as SSBR, epoxy, MDI and EPDM while expanding its R&D scope into recycled materials, carbon reduction and next-generation batteries.
September 16, 2026
Dow Urethane Comments in Laguna
Dow Inc. (DOW) Presents at Morgan Stanley’s 14th Annual Laguna Conference Transcript
Sep 16, 2026, 3:51 PM ETDow Inc. (DOW) Stock
Dow Inc. (DOW) Morgan Stanley’s 14th Annual Laguna Conference September 16, 2026 1:00 PM EDT
Company Participants
Jeffrey Tate – Chief Financial Officer
Jeffrey Tate
Chief Financial Officer
Great. Thank you, [ Mark. ] And good morning, everyone, and thank you for having me today. Before we get into your questions, I’d like to begin with just a few remarks to paint a picture of how the third quarter has evolved. I’ll share Dow’s views on the external factors and market conditions that have the greatest impact on our business as well as an overview of our self-help actions, continued financial discipline and our near-term priorities.
Now I’ll start on Slide 2, with the current environment. The macro backdrop remains dynamic and largely unchanged from what we outlined in July at our earnings. Specific to Dow, our strategically advantaged global footprint and local supply chains in every region continue to be differentiators for us. The oil-to-gas spread remains elevated as geopolitical tensions in the Middle East continue, supported by recent material escalation of crude pricing, while gas remains largely unaffected. This reinforces the competitive advantage of Dow’s purpose-built asset base and feedstock position that we’ve developed over decades. And while the tariff landscape has become more complex, Dow’s direct exposure remains minimal.
That said, continued volatility and uncertainty in the early part of the third quarter have created some headwinds that we’re working to offset.
Several market developments are working in our favor, which we expect to at least partially offset some of the impacts, but we’ve got more work to do. More specifically, July polyethylene prices in the Americas settled down $0.10 per pound. This reflected declining feedstock prices and margins in the early part of the month when initial expectations for a durable solution to the Middle East conflict began to surface.
In August, however, widespread reporting indicated those expectations were not realistic in the immediate term. In the month, we saw some improvement in the global operating environment along with higher oil prices. This ultimately led to polyethylene prices selling flat month-over-month.
So far in September, we are seeing a strengthening order book, including in Asia. Along with the recent sharp escalation in global feedstock costs, this supports our announced global price increases globally, including $0.10 to $0.12 per pound for polyethylene in the Americas. With a rapidly rising cost environment, we are implementing these price increases with urgency.
So looking at some of the key markets that Dow serves across our portfolio, consumers remain selective with spending trends favoring essential items. Additionally, the building and construction and automotive markets continue to face challenges amid a cautious monetary policy environment. Shipping through the Strait of Hormuz and other regional water was also remains constrained, tightening global supply further. And low water levels in Europe, including the Rhine, are constraining competitor supply across several products, which is leading to higher market prices across our Industrial Intermediates & Infrastructure segment.
So to summarize, the geopolitical and macro backdrops remain volatile and demand signals are mixed. While polyethylene price declines early in the quarter represent a headwind, Dow continues to lead with deliberate actions, and we remain focused on controlling what we can control. Our self-help actions and the breadth of our portfolio are helping to partially offset this impact, and we now expect to deliver EBITDA of $1.5 billion to $1.6 billion for the third quarter. This represents our best estimate based on what we see today, recognizing that a continued volatile environment this month could ultimately influence the outcome.
Next, I’ll share some examples on Slide 3 that outline the ways in which we are taking decisive actions to improve our financial strength. First and foremost, we continue to enhance Dow’s balance sheet and near-term financial performance. To start, our major planned maintenance for the year is now complete at several of our largest assets, which should provide a tailwind in the fourth quarter. In addition, we received the remaining tax withholding related to the NOVA litigation settlement earlier this quarter. We are also actively prioritizing deleveraging with excess cash, and we expect to release more than $500 million of net working capital in the second half of this year.
Looking longer term, we have no substantive debt maturities until 2029. And importantly, we continue to deliver our self-help actions, including our recently upsized in-year target for Transform to Outperform. With this, we now expect to deliver $1.3 billion in total benefits from self-help in 2026.
Our intentional actions continue to strengthen Dow’s credit profile as improved earnings, balanced capital allocation and self-help actions drive higher cash generation and lower leverage. This was evident by a recent rating agency outlook upgrade.
Next on Slide 4. I’ll unpack some additional details on how Transform to Outperform is delivering value as a significant contributor to our self-help improvements. We expect Transform to Outperform will deliver an upsized benefit of approximately $700 million this year, clearly demonstrating the early value we are capturing. Importantly, we remain confident in the more than $2 billion total opportunity that our transformation will deliver, and we’re seeing significant early results from every work stream. A broad range of actions will contribute to the benefits we expect in the second half of this year. And let me highlight just a few examples.
We already implemented approximately 70%, 7-0, of the total Dow role reductions, and we expect to implement nearly all of them before the end of this year. This is expected to contribute more than $200 million of EBITDA uplift in the second half.
Unknown Analyst
Interesting. Let’s shift gears maybe over to Industrial Intermediates & Infrastructure. You touched on some of the softness we’re seeing in some of these markets, housing, obviously, being one of them. But you’re expecting a normal seasonal decline in building and construction in Q3 with some margin pressures in Europe. We’ve all been waiting for this recovery now in the housing market for some time, and yet housing starts and existing home sales are still well below historic averages. What are you seeing thus far this quarter in building and construction? And how are you managing the business through the current higher-for-longer rate environment?
Jeffrey Tate
Chief Financial Officer
Sure. I mean when you look at building and construction for us and specifically in the II&I segment, there are a couple of dynamics that I think are worth mentioning. One, yes, building and construction is a significant portion of the portfolio, but it’s a mixed bag from a demand perspective because data centers also do provide some level of a tailwind within that segment for us. The other thing that I would also mention, [ Mark, ] is we have our Dow Industrial Solutions business as well, that is an II&I segment. That’s the alkoxylation investments that we’ve made over the past couple of years. So again, you think about home care, personal care, pharma, electronics as well, those are areas that are growing higher margin, faster than GDP, which will continue to provide that tailwind for us as we think about year-over-year growth.
Unknown Analyst
Interesting. All right. Maybe just keeping on II&I, you flagged that normalization of peer MDI and PO capacity, which had been disrupted in Q2, is expected to be a headwind in Q3. Market commentary had indicated that the upstream carbon monoxide issue had flared up in early July before fading again. Can you help us size that perhaps? And how quickly have peers restarted, if they have even? And what’s the EBITDA headwind from MDI and PO margin compression that’s embedded in the Q3 guide?
Jeffrey Tate
Chief Financial Officer
Well, the interesting thing is that because of the industrial gas supply issue that I think you’re referring to, the industry supply is still tight. So we’re actually seeing some pricing momentum in this period of tighter supply, which we’re being able to really execute on as we ramp up our operating rates on the U.S. Gulf Coast related to MDI. So that’s one of the areas where if you looked at the beginning of the quarter versus where we are now, it’s giving us a slight tailwind to close out third quarter, which is positive for us.
September 2, 2026
Highlights from Somnigroup Discussing L&P Acquisition
Somnigroup International Inc. (SGI) Discusses Strategic Acquisition of Leggett & Platt and Enhanced Vertical Integration Transcript
Sep 02, 2026, 12:44 PM ETSomnigroup International Inc. (SGI) Stock

Somnigroup International Inc. (SGI) Discusses Strategic Acquisition of Leggett & Platt and Enhanced Vertical Integration September 2, 2026 8:00 AM EDT
Company Participants
Lauren Avritt – Director of Investor Relations
Scott Thompson – Chairman of the Board, CEO & President
Bhaskar Rao – Executive VP & CFO
Scott Thompson
Chairman of the Board, CEO & President
Thank you, Lauren, and good morning, everyone. Today is a significant day. We have officially closed the Leggett & Platt transaction, and I’m pleased to welcome the Leggett & Platt team to the Somnigroup family. This milestone marks the next chapter in our strategic journey and one we believe strengthens Somnigroup’s competitive position around the world.
A few facts on Somnigroup post-closing. Over $11 billion in trailing 12-month sales, over $750 million trailing 12 months net income, $20 billion enterprise value, $15 billion market cap. Over 170 manufacturing plants around the world. 2,800-plus retail stores with various formats customized for each international market. Over 40 e-commerce websites, selling direct to consumer with aggregate sales of over $500 million per year. 36,000 talented associates led by a very experienced management team. And customers, both retail and wholesale in over 100 countries. We are building a special vertically integrated company with numerous competitive advantages, outstanding cash flow generation attributes, a diversified customer base and a passionate workforce dedicated to customers in various markets and industries.
What we see in Leggett & Platt is a company with 143-year long legacy of exceptional people, world-class manufacturing, strong commitment to customer service and best-in-class expertise in bedding components. They also have a long track record as one of our most important suppliers. We know them well, and they know us well. That familiarity is an asset as we move forward as a combined company. First and foremost, the combination deepens our vertical integration, and it adds significant scale expanding sourcing opportunities, enhancing operational flexibility to a portfolio of assets that is already industry-leading. It also extends our reach across industries beyond bedding which will provide the company solid free cash flow and growth as markets normalize and these strategies are implemented. Strategically and economically, this is the right deal at the right time with the right partner.
Let me take you through how this transaction advances the strategic pillars we outlined at our Investor Day last March. Global scale and vertical integration, relentless consumer-centric innovation, relentless cash generation, disciplined capital allocation and a uniquely favorable position in the $120 billion global bedding market recovery. The Leggett & Platt acquisition checks every one of these boxes. Most directly, it strengthened our vertical integration advantages. Leggett & Platt is a primary supplier of important components to the bedding industry and particularly to our own manufacturing operations. They supply innerspring units, specialty foam and other key components to producers around the world, bringing their capabilities in-house further fortifies our supply chain in an uncertain world and allows us to optimize cost and drive quality end-to-end in the supply chain. The combination brings component engineering closer to mattress design and closer to the consumer insights we generate every day across our retail platform. That proximity supports accelerated innovation cycles. It means we can develop more cost-effective and consumer-centric products.
In addition to expanding our addressable market in bedding, Leggett & Platt’s product portfolio includes automotive seating systems, furniture components, geo components, and hydraulic cylinders also allow us to participate in industries beyond global bedding. These diversified sales streams as well as Leggett & Platt’s geographic footprint broadens our earnings base, and mitigates reliance on any single category, product or geographic market.
Let me say a word about how we intend to operate Leggett & Platt within the Somnigroup portfolio. Leggett & Platt will operate as a stand-alone business unit within Somnigroup, consistent with our approach with Tempur Sealy, Mattress Firm and Dreams. We believe this decentralized operating model is one of our structural advantages. It allows each business unit to stay close to its customers and markets and quickly respond and develop strategies in an ever-changing world, while also benefiting from Somnigroup’s expertise, scale, strong balance sheet and operational leverage.
A word on leadership. First, we’re very fortunate that Leggett & Platt has an experienced workforce dedicated to quality and customer service, which is led by a strong committed executive team with depth and a passion to succeed. To enhance their leadership structure, you most likely saw we announced the appointment Tyson Hagale as President of Leggett & Platt. Tyson is a 25-year Leggett & Platt veteran with a broad expertise across all corners of the business, including strategic planning, operational leadership and M&A. Most recently, he served as President of the Bedding Products segment, delivering results and operational improvements through some of the most dynamic conditions in the industry has ever seen. He knows Leggett & Platt well, including the non-bedding components. Karl Glassman will continue to lead Leggett & Platt as CEO over the near term, working closely with Tyson and Somnigroup executives as we bring the companies together. I’m looking forward to working with Karl and Tyson.
Moving to near-term strategic initiatives. We expect some early wins. We have long believed that high-quality innerspring systems represent a meaningful point of differentiation and important feature for customers. While the mattress category has traditionally emphasized finished product branding, we see the opportunity to elevate awareness of underlying technologies and components that contribute to comfort, support, durability and overnight fleet quality. Simply put, what is in your mattress matters. As a result, we are working to amplify the differentiated innovation by incorporating Leggett & Platt innerspring branding on the exterior selected mattress products. We believe this approach helps highlight the value of the technology inside the mattress while creating greater transparency and confidence for customers at the point of purchase. This initiative will initially roll out with our launch of the all-new Stearns & Foster collection this fall. It represents an important step in our broader strategy to increase consumers’ recognition of the premium component of engineering that differentiates our products. We believe stronger visibility of the Leggett & Platt innerspring technology can enhance the consumer shopping experience, support our retail partners’ merchandising efforts and further reinforce the value proposition of mattresses that incorporate our technology.
Ultimately, we view this as much more than a branding initiative. This is a reflection of the strategic vision behind the acquisition of Leggett & Platt’s bedding business and the unique capabilities that the transaction creates. By bringing ownership of innersprings, the heart of the bed, into the portfolio we are now able to more closely integrate component innovation, mattress design, driving consumer engagement. We believe that position enables us to set higher standards for innovation, durability, quality and transparency across the industry, while creating connection between the technology inside the mattress and the magic consumers experience every night. We should also note that Mattress Firm as it continues to focus on customer first, recently communicated to its supplier base, new and more stringent merchandising criteria, including the qualification of key component inputs, both Leggett & Platt’s innerspring systems and the foams produced by ECS, their specialty foam operations have been qualified under these enhanced standards. This is direct validation of the quality and consistency that Leggett & Platt brings us to our supply chain. I’ll say it again, what is inside your mattress matters.
In closing, I want to leave you with a few key thoughts. We are the leading vertically integrated bedding company in the world. We now forge our own steel, create our own springs and foam. We design and build our own products. We develop and market our brands and sell our products, which cover all price points in a balanced omnichannel format across the world. We believe that the $120 billion global bedding market remains structurally intact and positioned to normalize from its historically depressed levels. Now let’s be clear, the bedding market has experienced an extended period of weakness, and we have used that time deliberately to build the platform you see today, while also growing adjusted EPS and deleveraging. We are investing ahead of the recovery and building our brands, driving upper funnel advertising and strengthening our infrastructure. It’s not a question if the bedding market is going to turn around. It’s a question of when and whether you are positioned to lead when it does, and we are positioned to win and win big.
Bhaskar Rao
Executive VP & CFO
Thank you, Scott. Let me start with some housekeeping items on our reporting structure going forward. Leggett & Platt will be reported as a single consolidated reportable segment within Somnigroup, consistent with our other reporting segments, Tempur Sealy North America, Tempur Sealy International and Mattress Firm. Now moving to synergies. When we announced this transaction, we identified approximately $50 million in synergy opportunities on an annual run rate basis, focused on sourcing, operations and product innovation. That figure was based primarily on our internal diligence work at that time. Since then, we have worked with Leggett to refine our expectations. As a result of the team’s combined efforts, we are increasing that synergy estimate by 50% to $75 million on an annual run rate basis with additional opportunities in our synergy funnel that will be evaluated over the next year. .
Within sourcing, we see opportunities to expand profitability by bringing select components in-house and/or improving purchasing economics across our supplier base. To date, we have included $35 million of sourcing related synergies in our target. One of the most immediate and tangible examples is innersprings. Beginning in January 1, 2027, we expect to manufacture over 90% of our total U.S. spring needs internally, creating a meaningful cost savings opportunity and further strengthening integration across the business. We are reviewing additional supply chain opportunities and expect our combined sourcing efforts to support greater cost efficiency, particularly in chemicals. In addition, we expect the broader platform to create savings across third-party professional services.
Rafe Jadrosich
BofA Securities, Research Division
I just wanted to follow-up on the sourcing synergies that the 90% of — the expectation that you’ll be 90% internal sourcing for your springs. Can you talk about where that is today, like what that delta is? How much you’re getting from Leggett versus either other suppliers or internal right now, so like what that changes? And then does that include anything with Elite Comfort Systems in the foam side? Or is that all — that sourcing number all innersprings?
Scott Thompson
Chairman of the Board, CEO & President
Yes. We were under a long-term contract with Leggett pre-combination of 80% of our springs in the U.S., this is just a U.S. comp discussion coming from Leggett, so you should think about it as incrementally 10%, and we’ll probably be a little bit north of 90% over time would be my guess. That number is in the synergies. There’s nothing significant currently in the synergy number on the ECS side as we work through the ECS side of the house. We have a great supplier currently, what I’m going to call base foam, and they’re doing a great job, and we’re working with them and working with ECS and trying to find an optimal structure there, but we’ve got great suppliers on the base foam already.
Michael Lasser
UBS Investment Bank, Research Division
There are very few examples where one company such as Somnigroup control such a disproportionate amount of the profitability within the sector, and the bedding industry is interesting in that historically, it’s relied heavily on pricing as a key contributor to the overall growth of the sector. So my two-part question is, a, Scott, do you see any changes in the overall economics of the bedding industry as a result of Somnigroup’s unique position; and b, how are you looking at the overall pricing architecture of the industry moving forward as a key contributor to the overall top line results?
Scott Thompson
Chairman of the Board, CEO & President
Thank you for the question, and there’s probably some of my lawyers on the phone now that are going like, I hope he doesn’t really say much on that question, but let me talk about — first of all, you’re right. It’s a couple of things that are really unique. It’s really unique that a company was able to take a downturn, and the downturn has been, on a historical basis, it’s been the worst downturn ever, and be able to build what we’ve built. I mean it really is game changing. And you’re right, I don’t know what percentage of worldwide bedding profits Somnigroup now has, but it’s large, we’ll say it.
As far as the pricing architecture, I think the profitability of the bedding industry is going to be enhanced as we take out redundant costs and we add synergies. I think the economists and certainly, history would be the FTC would look at that and expect that some of that would creep into the customers’ pocket. And maybe it does, maybe it doesn’t. But from a competitive advantage standpoint, it certainly should create a competitive advantage in the marketplace.
Peter Keith
Piper Sandler & Co., Research Division
Big picture on the industry and potential rebound, so it looks like we’re now entering our fifth year of mattress industry sales declines. We do have positive GDP growth, there’s been a tax refund cycle earlier in the year. When you guys are thinking about the industry rebounding and getting better, what do you think needs to happen in the economy looking forward? And I understand housing would be an easy answer, but we all agree that, that’s a minority of total mattress sales purchases?
Scott Thompson
Chairman of the Board, CEO & President
The real answer is housing is an incremental headwind or incremental tailwind usually not hugely material, but you’d rather have a tailwind than a headwind. It’s consumer confidence which I would point back into a little less — a little more stable environment because look, these are discretionary goods, they are expensive and so when consumers are not confident and sentiment is really negative, they have — some portion of the customers tend to postpone. It’s interesting because it’s in-floor traffic. The customer who actually is in the funnel to purchase a bed, once in the funnel, gets through the funnel fairly quickly, or in standard form and it gets into the store and the closing rates are very strong.
So you don’t have an issue on pricing. You don’t have an issue on quality of products, quite frankly, the products, ours and others in the bedding industry are good. You’ve got a strong kind of health and wellness concept that goes through the industry. People do care about their bed. They do care about their health, and people with means are showing up and buying. Who’s not showing up are the more of the entry-level customers, if you want to say, the K economy or whatever or people who are a little unsettled by current events. So the first thing I’d say is we just need less drama in the world. And we’ve had it a few times, okay, where there’s a period where there’s a little less drama, and you can see it in the numbers. I mean, floor traffic picks up, sales pick up, but then we get some tariff drama, some Middle East drama and people’s hands go back into their pockets. That would be my first answer to that.
And the second answer is we need to continue to have the industry advertise, have effective advertising, make sure it’s compelling and get it placed in a way in the marketplace that consumers are seeing the ads and that it’s influencing them to think about their bed to get into the purchase funnel. The biggest — the issue is getting people triggered to think about their beds. If you look at the installed base, and this isn’t like the car business where you can look at a VIN and you know exactly what the average age of all the cars are on the road, how many miles they’ve driven. We don’t have that kind of data, but there is no question if you look at the volume declines over what — you’re right, into the fifth year that the products that are in the marketplace are probably older than they’ve ever been. There’s also no question that beds do wear out, and there’s no question that people are going to sleep on beds. The industry is structurally sound. There’s nothing that’s threatening the industry from a structural standpoint. So that’s why I kind of go back to — I don’t know, I can’t tell you the exact turn, but there’s — but everything points to what we just need is a little more stability in the way the consumers are thinking about the world.
 Everchem Updates Archive
 Sign Up for Email Updates