
Company News
April 30, 2019
Huntsman Results
Huntsman Announces First Quarter 2019 Earnings; Stable Downstream Margins
THE WOODLANDS, Texas, April 30, 2019 /PRNewswire/ —
First Quarter Highlights
- First quarter 2019 net income of $131 million compared to $350 million in the prior year period; first quarter diluted earnings per share of $0.51 compared to $1.11 in the prior year period.
- First quarter 2019 adjusted net income of $108 million compared to $237 million in the prior year period; first quarter 2019 adjusted diluted earnings per share of $0.46 compared to $0.96 in the prior year period.
- First quarter 2019 adjusted EBITDA of $257 million compared to $405 million in the prior year period.
- First quarter 2019 net cash used in operating activities was $31 million. Free cash flow was a use of $101 million for the quarter.
- Huntsman achieved investment grade rating and issued $750 million of senior notes due 2029. Proceeds were used to redeem $650 million of our senior notes due 2020 and for general corporate purposes. Balance sheet remains strong with a net leverage of 1.6x.
- First quarter 2019 share repurchases of approximately 1.5 million shares for approximately $34 million.
- Segment Analysis for 1Q19 Compared to 1Q18
Polyurethanes
The decrease in revenues in our Polyurethanes segment for the three months ended March 31, 2019, compared to the same period of 2018 was due to lower average MDI and MTBE selling prices, partially offset by higher MDI sales volumes. MDI average selling prices decreased primarily due to a decline in polymeric MDI selling prices in China and Europe. MTBE average selling prices decreased primarily as a result of lower pricing for high octane gasoline. MDI sales volumes increased primarily due to the start-up of our new Chinese MDI facility in 2018 and the acquisition of Demilec in the second quarter of 2018. The decrease in adjusted EBITDA was primarily due to lower MDI margins driven by lower MDI pricing and lower MTBE margins, partially offset by higher sales volumes.
- https://seekingalpha.com/pr/17492175-huntsman-announces-first-quarter-2019-earnings-stable-downstream-margins
April 29, 2019
Arsenal Closes Fund V
|
|
April 29, 2019
Arsenal Closes Fund V
|
|
April 29, 2019
Amazon Goes Into Freight
A “Nightmare Come True”: Amazon Launches Freight Brokerage, Slashes Prices By 30%
In what is being called a “nightmare come true” for freight brokers and carriers, Amazon did what it traditionally does every time it enters a new market, and took its own digital freight brokerage platform live while undercutting prevailing market prices by 26% to 33% in the latest deflationary race to the pricing bottom in order to grab market share, according to FreightWaves.
Late last week, Morgan Stanley equities analyst Brian Nowak had predicted this was going to happen, stating: “We see AMZN’s 1-day Prime shipping raising consumer expectations and increasing the cost to compete in e-commerce. Over the long term, we also see this as a Trojan horse for Amazon to grow its next disruptive business… a third party logistics network.”
Amazon already has an extensive network of trucking carriers as it moves an enormous amount of freight across the country. Having their own third-party logistics network was just an obvious next step for the behemoth of a company that relies so much on shipping. The benefits are plentiful for Amazon: they get to hedge against the volatile price of trucking capacity and they get to expand their infrastructure, while turning part of their costs into revenue. Amazon is already a top 10 international freight forwarder for Asian ocean freight inbound to North America.

Amazon explained the company’s strategy by stating: “The advantages that then come from disintermediation and the monetization of those capabilities are secondary to the immediate need of self-preservation, but then serve to feed very critical needs of Amazon’s ability to continue to succeed. This innovation and growth then manifests as continuously evolving towards the ability to sell everything and anything that is or can be sold. That’s the true Amazon flywheel: disintermediate to survive; monetize to fund innovation; innovate to grow; disintermediate to survive…”
Amazon’s entry into freight brokerage is an attempt to re-accelerate its top line, which has slowed from 30% annually three years ago to less than 15% this year. The company is trying to not allow trucking capacity to constrain its growth and, for now, it is coming in at price points that are far below market prices. This indicates that Amazon is not trying to realize enormous gross margins at first. The company’s new portal is intended for those who want Amazon‘s rates for full truckload dry van freight in Connecticut, Maryland, New Jersey, New York, and Pennsylvania. Based on these rates, the company is essentially a “free, marginless brokerage”.
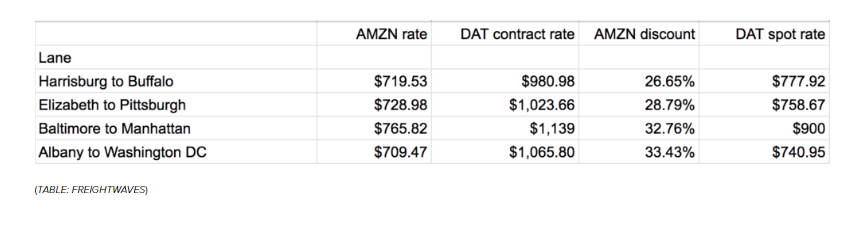
Eventually, down the road, the company will monetize this. But for right now, the company is focused on deploying a massive amount of capital to rapidly scale up its network on thin margins to get started. Prices will eventually creep up once Amazon has penetrated the market (read obliterated the competition), not unlike Amazon’s original business model decades ago.
Amazon’s new business will surely result in even more carnage in the Class 8 “heavy duty” order industry, where as we reported a few weeks ago, order for Class 8 trucks collapsed an astounding 66%, which decline is attributed to a 300,000+ vehicle backlog potentially prompting fleets to halt purchases in the near term, however it is also likely that concerns about the economic slowdown are also playing a major part in the latest collapse. Specifically, March Class 8 net orders were just 15,700 units (16,000 SA; 192,000 SAAR), down 66% YoY from 49,600 a year ago and down 6.7% sequentially.
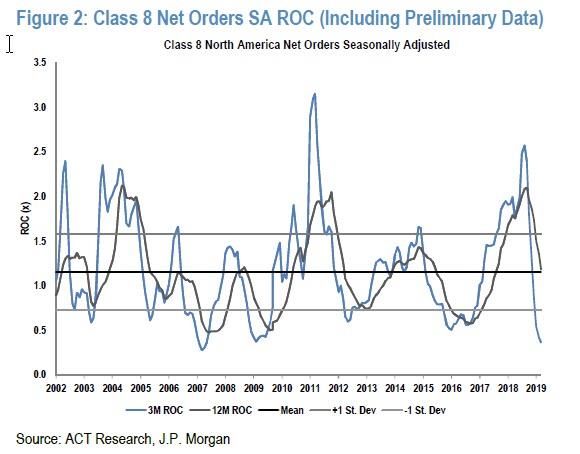
“March marks the fourth consecutive month of orders meaningfully below the current rate of build,” said Steve Tam, vice president of ACT. During that four-month period, Class 8 orders have been booked at a 194,000 seasonally adjusted annual rate, or SAAR. This is down significantly from 489,000 SAAR for the same period a year earlier, Tam said.
And it’s only going to get worse now that Amazon is taking over. The company spent $7.3 billion on transportation in the first quarter of 2019, which is lumped together with sortation and delivery costs in its “shipping cost” line item. Amazon’s shipping costs for the year, annualized, are approximately $87.6 billion and FreightWaves predicts that it could be years before investors start asking about margins on this business.
Building out this network could also allow Amazon to “blowout retail peak season”. By sacrificing margins up front, the company will have capacity locked up to move record breaking volumes during the holiday season. This is also another step Amazon is taking to try and get a leg up against competitors like Walmart. We just reported hours ago that Walmart was looking to get into one day shipping without a membership fee to compete with Amazon. Now, it looks as though Amazon has volleyed that ball right back into Walmart’s court.
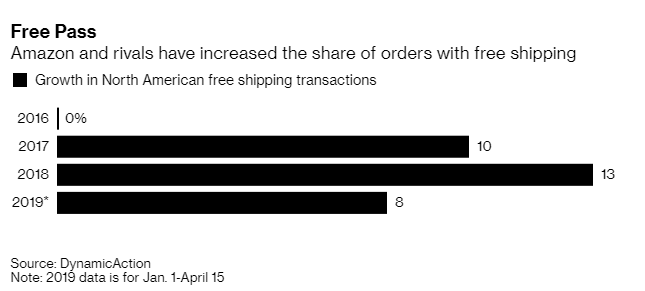
Walmart has offered free two-day shipping on orders of $35 or more since early 2017, which helped it keep up with Amazon. And while Amazon still accounts for about half of all e-commerce spending in the United States, this $35 threshold has also been taken on by other retailers, like Target, to help offset the cost of delivery.
Total retail transactions with free shipping were up 13% in North America last year and were up 8% through April 15 of this year. Amazon Prime now charges customers monthly and annual fees, amounting to about $119 in the US for a year. Prime customers get shipping discounts and free two day delivery on most items.
 Everchem Updates Archive
 Sign Up for Email Updates