
Company News
May 13, 2024
Wind Turbine Issues
Thousands of Old Wind Turbine Blades Pile Up in West Texas
Officials in Sweetwater say an out-of-state company has made their town a dump for the seldom-seen trash created by renewable energy.
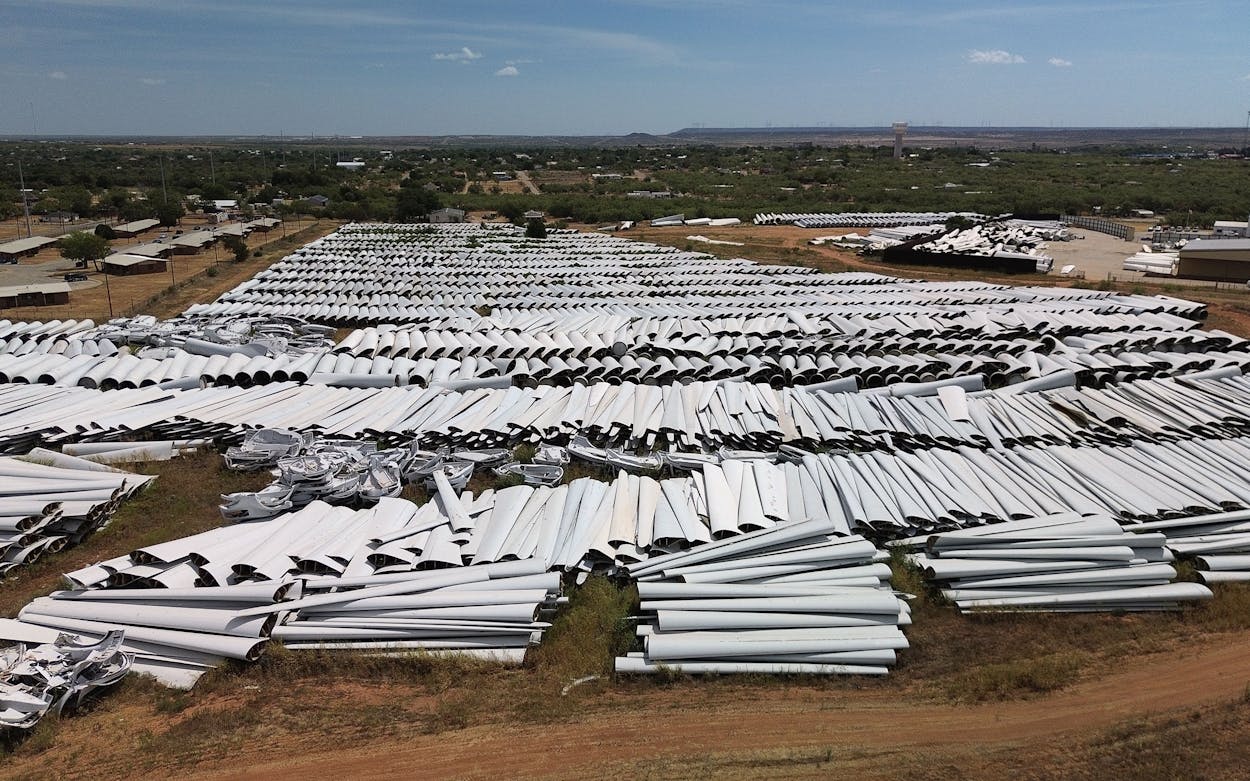
Discarded wind turbine blades fill thirty acres on the west side of Sweetwater.
Update, May 6, 2024: Despite earlier assurances from Global Fiberglass Solutions that they would be removed with months, the blades remain in Sweetwater.
Update, September 25: General Electric filed a lawsuit last week claiming that Global Fiberglass Solutions has failed to fulfill its promise to recycle thousands of blades. GE says it paid the company $16.9 million to recycle about five thousand wind turbine blades, but that GFS instead stockpiled them at facilities in Sweetwater and Iowa. “Only after GFS took millions of dollars from GE, did GFS all but shut down its operations without recycling the Blades,” reads the complaint, filed in U.S. district court in New York.
GE says it later contracted with another company to recycle its blades and is seeking damages to cover these costs as well as reputational damage. Global Fiberglass has not responded to the lawsuit. GE removing its blades from Sweetwater wouldn’t clean up the giant dump; blades manufactured by other companies would still remain.
Every year since 1958, the West Texas town of Sweetwater has hosted the World’s Largest Rattlesnake Roundup, which is exactly what it sounds like. Thousands of the venomous ophidians are rooted out of their dens and brought to the Nolan County Coliseum to be gawked at, “milked,” and often beheaded and skinned. It started as a way for the region to rid itself of some of its least-welcome residents. Now community leaders wish they could do the same with several giant piles of scrap that have for too long been left to bake in the sun. But that’s proving to be much trickier than wrangling reptiles.
About forty miles west of Abilene on Interstate 20, Sweetwater has unwittingly become home to what is possibly the world’s largest collection of unwanted wind turbine blades. When forklifts deposited the first of these in a field behind the apartment complex where Pamala Meyer lives, on the west side of town, in 2017, she wasn’t initially bothered. But then the blades—between 150 and 200 feet in length and mostly made of composite materials such as fiberglass with a binding resin—kept coming. Each was cut into thirds, with each segment longer than a school bus. Thousands arrived over several years, eventually blanketing more than thirty acres, in stacks rising as high as basketball backboards. Every few dozen feet, a break among the stacks leads into an industrial hedge maze.
“It’s just a hazard all the way around,” Meyer said. She worries about neighborhood children exploring the unfenced piles and says that stagnant pools of water inside the blades breed swarms of mosquitos. Matt Jackson, who works in a nearby warehouse, has other concerns. The piles create shaded nooks and crannies, perfect for Sweetwater’s unofficial mascot. “It’s just a big rattlesnake farm,” he said.
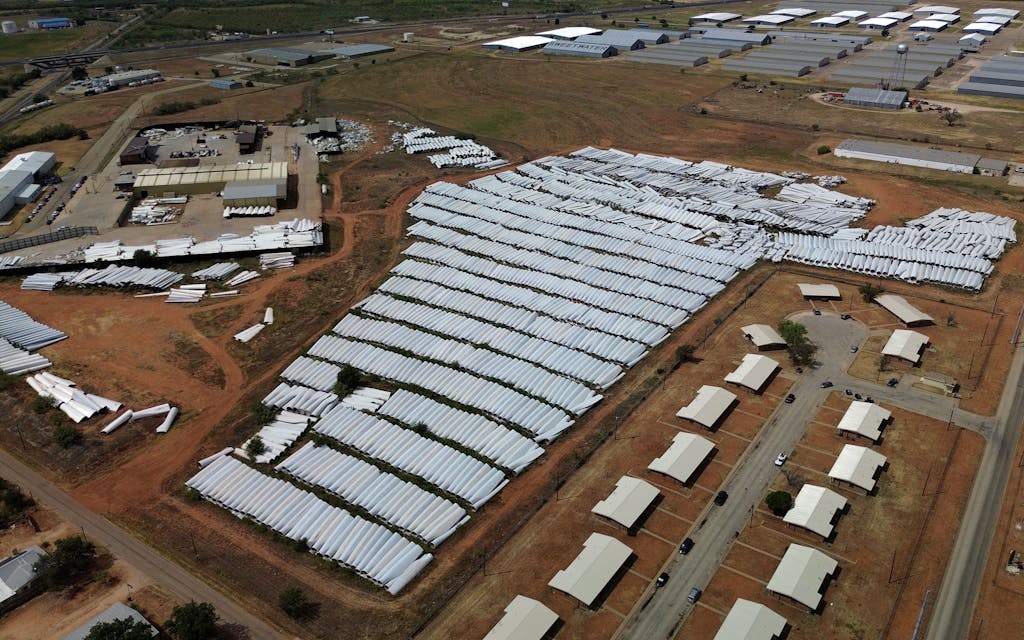
The blades were brought here by Global Fiberglass Solutions, a company based in Washington State that announced in 2017 its intention to recycle blades from wind farms across the region. Instead of ending up in landfills, they would be ground up into a reusable material that could be turned into pallets, railroad ties, or flooring panels. Global Fiberglass is one of a few companies attempting to develop a viable business from recycling blades.
Besides the main boneyard—behind Meyer’s apartment—stacks of blades also occupy ten acres a couple miles south of town, and the company is storing blades in other locations in the county. “They have, in my view, abandoned them there,” said Samantha Morrow, the Nolan County attorney. “The county doesn’t have and cannot find millions of dollars to clean this up.”
The Sweetwater piles are also at least partly the indirect result of a rule clarification the Internal Revenue Service issued in 2016. Before then, a wind farm could collect valuable federal tax credits for only its first ten years of operation. But the IRS determined that it would restart the clock on the credits if a wind farm “repowered” its turbines—replacing most of their equipment with newer parts. So, despite the expected two-decade lifespan for turbine blades, wind farms across Texas and other states began replacing many that remained in good shape years early.
Some paid Global Fiberglass to remove the older blades and haul them away. The company set up shop in an empty industrial facility in Sweetwater that was once an aluminum recycling plant, but Don Lilly, the managing director of Global Fiberglass, told me that only a handful of blades have ever been ground up there. He said the company was close to ramping up and would soon mill the blades into pieces the size of coarse sand. “The blade material is sold,” he said, “but I can’t go into that part yet.”
Sweetwater has heard such pledges before. The county declared the stockpile a public nuisance a year ago. City attorney Jeff Allen said Sweetwater’s local ordinances are aimed at overgrown lots, not turbine blades, leaving the city with limited legal options. He said he believes Global Fiberglass “intended to be a viable business” but at some point “it just came off the rails.” (Lilly disputes this and says the delays have come from ensuring “all systems were engineered.”)
Sweetwater benefits from the wind-energy industry, including two large wind farms nearby. Drivers arriving on I-20 from either direction are welcomed by a giant wind turbine blade painted with the town’s name. But even the community’s biggest boosters of renewable energy long ago ran out of patience with Global Fiberglass’s mess. “We’d like to see them gone,” said Karen Hunt, director of the local chamber of commerce. “The sooner the better.”
Sweetwater isn’t the only place Global Fiberglass has stockpiled blades. It has a total of 1,300 in Newton, Iowa, and two other cities in that state, according to the state’s Department of Natural Resources. After an investigation, the agency concluded in 2021 there was no recycling going on, nor was any likely to happen. It declared the company to be running an unpermitted dump.
Frank Liebl, executive director of the Newton Development Corporation, testified at a state hearing that the initial excitement in 2017 of recruiting a blade-recycling company soon soured. In the intervening years, he asked Global Fiberglass many times when it would begin its recycling. He always got “the same answer: ‘Soon,’ ” he said.
By July 2021, the company owed more than $1 million in unpaid rent in Newton, according to testimony at the Iowa hearing from its landlord’s attorney. In Texas, it failed to pay taxes to Nolan County in 2020 and is now three years in arrears, according to tax records. Last year, the Texas Commission on Environmental Quality fined the company $10,255 for what it described as illegally stored solid waste. It allowed the company to pay the penalty in monthly installments for three years. In June, Global Fiberglass defaulted, according to the commission.
In Newton, pressure from the state of Iowa seems to have worked. Craig Armstrong, a city employee, said that General Electric recently acquired the blades. It’s unclear whether GE purchased them from Global Fiberglass or from the landlord who was owed the $1 million in rent, who may have taken possession of the blades. The city was promised that they would be sent to a recycling center by the end of the year, although none had been removed by mid-August, according to a Newton city official.
Lilly declined to talk about the Iowa blades. He said the situation in Sweetwater is different and insists that Global Fiberglass will grind down and recycle these blades. “If you come back nine months from now, you will not see the material,” he said. We’re marking our calendars and will check back in May.
https://www.texasmonthly.com/news-politics/sweetwater-wind-turbine-blades-dump/
May 12, 2024
CVC Buys Into Hempel
Private equity CVC Funds buys into Hempel
Photo: Hempel
CVC Funds is becoming a minority investor in the coatings company which has been solely owned by Hempel Foundation for 75 years.
Marcus Hand | May 08, 2024
The move by Hempel Foundation to bring CVC in as an investor into Hempel A/S is designed to help support both its organic growth strategy and to pursue merger and acquisition opportunities.
CVC will as a minority investor subscribe to new shares equating to up to a 30% stake in Hempel over time. The value of the investment was not revealed.
Related: Hempel launches underwater hull inspections using ROVs
Richard Sand, Chair of the Hempel Foundation Board of Directors said that they believed the value of Hempel’s shares would increase more over the next five to 10 years with CVC as a minority shareholder than without.
“The Hempel Foundation has been the sole owner of Hempel for 75 years and has an ongoing commitment to secure Hempel’s financial base and ensure its future growth. After careful consideration, the Hempel Foundation has decided to welcome a minority investor that brings both unique experience and capital to support Hempel’s accelerated growth journey,” he stated.
Related: Hempel invests $100m in new China factory
Hempel Foundation will continue to be the majority shareholder in Hempel.
Michael Hansen, Group President and CEO of Hempel A/S said, “We have already made solid progress on our strategy of driving profitable growth, both organically and inorganically through M&A activity, delivering record-breaking results in 2023.
“This new partnership will considerably strengthen our industry position, will ignite further growth in our winning brands and means we are well-placed to seek out transformative acquisition opportunities.”
From the CVC side, Partner Michael Lavrysen, commented: “CVC Strategic Opportunities invests in high-quality businesses with longer growth horizons, often partnering with likeminded families and foundations looking for specific expertise to advance expansion.”
The transaction is expected to close in the second half of the year subject to regulatory approval.
https://www.seatrade-maritime.com/finance-insurance/private-equity-cvc-funds-buys-hempel
May 8, 2024
LyondellBasell Weighs Options
LyondellBasell Weighs Strategic Options for European Assets

HOUSTON and LONDON, May 8, 2024 /PRNewswire/ — LyondellBasell today announced the formal launch of a strategic review of the European assets of its Olefins & Polyolefins and Intermediates & Derivatives business units. The assessment will evaluate the assets through the lens of the company’s strategy to Grow & Upgrade the Core, Build a Profitable Circular and Low Carbon Solutions Business, and Step Up Performance & Culture.
“At the 2023 Capital Markets Day, we stated our intent to concentrate our portfolio around businesses with long-lasting competitive advantage and to reinvest around those advantaged areas generating superior returns at meaningful scale,” said Peter Vanacker, LyondellBasell chief executive officer. “These criteria have not changed.”
The company’s investments in a commercial-scale MoReTec plant, LyondellBasell’s proprietary technology to convert plastic waste into liquid raw materials, and the development of a circularity hub in the Cologne, Germany region will continue as planned. LyondellBasell will also continue to invest and leverage its differential technology position as a key enabler to grow and upgrade the core asset base.
“The company will prioritize its investments to align operations with our circularity and net zero ambitions,” Vanacker added. “We understand that strategic assessments can create uncertainty for our employees and customers, but we are committed to operate our assets safely and reliably throughout this process.”
Media Inquiries
LyondellBasell Media Relations
Phone: +1 713 309 4791
Email: mediarelations@lyondellbasell.com
Or:
Robert Kleissen, External Affairs Europe
Phone: +31 6 273 573 98
Email: robert.kleissen@lyondellbasell.com
About LyondellBasell
We are LyondellBasell (NYSE: LYB) ― a leader in the global chemical industry creating solutions for everyday sustainable living. Through advanced technology and focused investments, we are enabling a circular and low carbon economy. Across all we do, we aim to unlock value for our customers, investors and society. As one of the world’s largest producers of polymers and a leader in polyolefin technologies, we develop, manufacture and market high-quality and innovative products for applications ranging from sustainable transportation and food safety to clean water and quality healthcare. For more information, please visit www.lyondellbasell.com or follow @LyondellBasell on LinkedIn.
https://lyondellbasell.mediaroom.com/index.php?s=43&item=1487
May 7, 2024
L & P Urethane Highlights from Earnings Call
Leggett & Platt, Incorporated (LEG) Q1 2024 Earnings Call Transcript
May 01, 2024 11:07 AM ETLeggett & Platt, Incorporated (LEG) Stock
Q1: 2024-04-30 Earnings Summary
EPS of $0.23 misses by $0.01 | Revenue of $1.10B (-9.62% Y/Y) misses by $22.67M
Leggett & Platt, Incorporated (NYSE:LEG) Q1 2024 Earnings Call Transcript May 1, 2024 8:30 AM ET
Company Participants
Cassie Branscum – VP, IR
Mitchell Dolloff – President & CEO
Benjamin Burns – EVP & CFO
Tyson Hagale – EVP & President, Bedding Products
Mitchell Dolloff
Good morning, and thank you for joining our call today. First, I want to share that this will be Cassie’s last earnings call with us, as she will be leaving the company for an exciting new opportunity later this month. Cassie has been an instrumental part of our IR team since 2018 and has been an incredible asset to the company throughout her various positions over the last 19 years. We wish her the best in her new role and will sincerely miss her.
Before reviewing first quarter results, I’d like to spend a few minutes discussing who we are, where we stand today, and where we are going in the future. Across most of our businesses, we are positioned as a leading provider of differentiated engineered products with opportunities to increase content over time, while collaborating with our customers to provide solutions. Our core businesses have strong market positions in industries with large and attractive addressable markets.
In Bedding Products, our 2019 acquisition of ECS meaningfully increased our addressable bedding market, allowing us to expand into specialty foam and compressed mattresses, trends which have significantly changed the domestic bedding landscape in the last 10 years. Although the bedding market has been challenged recently, the strategic rationale for that acquisition remains intact and should enable us to drive long-term growth and product innovation.
In Specialized Products, all three of our businesses supply technical, critical components that are developed with a deep customer relationship and collaborative design. For example, our automotive business is aligned with trends of increasing comfort and convenience features. Our ability to partner directly with OEMs to solve specific problems means we compete on differentiation rather than just price. In Furniture, Flooring & Textile Products, most of our businesses are mature and stable with steady margins and solid cash generation. These businesses tend to compete based on high levels of customer service or product differentiation and include our home furniture, work furniture and flooring operations. Within textiles, our geo components business leverages sourcing synergies from our fabric converting operations to supply fabrics for applications such as erosion control and landscaping. Geo components competes in a fragmented industry with sizable opportunities for growth.
With that context in mind, I’ll now address our near-to-mid-term strategic priorities, which are a blueprint for ensuring the sustainable long-term success of our business. Our priorities are: One, strengthening our balance sheet and liquidity; two, improving margins by optimizing operations and our general and administrative cost structure; and three, positioning the company for profitable growth opportunities. We’re committed to maintaining our long-held financial strength and have recently taken action to support this objective. In March, we proactively amended the agreement for our existing revolving credit facility to provide us with additional liquidity and flexibility. The leverage ratio was increased from 3.5 times to 4 times through June 30, 2025, creating a bigger cushion in a time of near-term weak demand in residential end markets.
Yesterday, we announced that the Board of Directors declared a quarterly dividend of $0.05 per share. The decision to reduce the dividend was made following a very thorough evaluation. This action will free up capital to invest in driving improvements in our business and solidify our long-held financial strength. Additionally, we continue to advance our initiatives across our business to drive operational excellence and enhance our efficiency. We expect these initiatives will allow us to drive margin improvement and continue to strengthen our financial foundation in the near to mid-term.
Domestic bedding manufacturers are facing numerous challenges, including low demand, overcapacity and increased pressure for finished mattress imports, resulting in financial stress across the industry. The domestic mattress market has changed dramatically in a relatively short timespan. The landscape has shifted from a largely domestic OEM-produced innerspring mattress market to one where innerspring, foam and hybrid mattresses are sold at a wide range of price points through a variety of channels and produced by a mix of fewer large domestic OEMs, domestic private label producers and import manufacturers. These changes have effectively reduced the size of the domestic innerspring mattress market by a third.
While we anticipate that import mattresses will always have a place in the market, any volume reshored to the US as a result of the ongoing anti-dumping case is beneficial for the domestic industry. In such a dynamic environment, we recognize that we must also make changes to profitably compete in the bedding market today and in the future.
Across our Bedding Products segment, we are executing on the restructuring plan announced in January to optimize our manufacturing and distribution footprint. We are making steady progress and remain on track to achieve our objectives. To date, we have closed four smaller US spring distribution facilities, transitioned manufacturing out of three facilities and into our four larger remaining spring production facilities, and closed a small specialty foam operation. We still expect the consolidation activities within US Spring to be completed by year-end and are currently downsizing our Chinese innerspring operation.
Finally, two additional specialty foam facility consolidations are underway and should be complete by year-end. As previously announced, restructuring actions will be complete by the end of 2025. I want to thank our entire team for their dedication and hard work during this time of transition. Our rod, wire and spring business continues to have healthy margins as a result of our refocused strategy targeting higher-value content, combined with disciplined cost management from our operations team. However, volume recovery, restructuring activities, and other operational initiatives will drive meaningful improvement.
Specialty Foam is a significant drag on our company profits, but we continue to drive operational improvements and margin recovery through our four-wall manufacturing improvement plan. Efforts to diversify our customer base have seen initial success, but we have more work to do in the current low-demand environment where many market participants are increasingly financially constrained. In adjustable bed, low demand and a market shift towards lower-value products have been a meaningful drag on profit. We are working hard to reduce cost and simplify the supply chain to drive profit and cash flow improvements.
Our European bedding business faces market conditions that are very similar to our domestic challenges. The team continues to drive profitability in innersprings but has opportunities to improve our Kayfoam business where the customer base has changed meaningfully since acquisition. We remain confident that our unique positioning in the bedding industry enables us to drive value for our branded customers and we are addressing our cost structure to do so as competitively as possible.
In Specialized Products, operational improvement activities are ongoing within each business. In automotive, the team continues to make good progress improving profitability. We continue to evaluate efficiency enhancement opportunities and options to leverage automation and vertical integration. In both aerospace and hydraulic cylinders, efforts to improve production efficiencies are underway. In hydraulic cylinders, we are shifting some production to our operations in India to reduce cost and improve profitability.
Restructuring initiatives in the Furniture, Flooring & Textile Products segment are also on track. We have closed a flooring products production line and redeployed the manufacturing equipment to one of our other production facilities. In home furniture, we closed one plant and have transferred that production to other remaining facilities. We expect to market that real estate by mid-summer. In work furniture, we continue to explore opportunities to reduce cost and improve profitability. Beyond our manufacturing operations, we are evaluating our general and administrative cost structure to drive further improvements in profitability.
Shifting our focus to the future, in the long term, we plan to invest in key focus areas, including Bedding, Automotive and geo components. The changes underway now in our bedding business support our future ability to drive product synergies across specialty foam and innersprings and capture greater product content through semi-finished and private-label finished goods. We are committed to leveraging our capabilities in springs and foam to expand our hybrid mattress programs and drive value for our customers through product development activities. Additionally, we expect that future growth in adjustable beds will stem from higher attachment rates and innovative product designs tailored to meet consumer needs.
In automotive, we see growth potential in our convenience products offerings such as motors and actuators, particularly as vehicle technology and electrification increases. Our geo components business has grown via greenfields and small bolt-on acquisitions over time, and we anticipate further growth as we continue to expand our product lines and geographic footprint. We are confident that the actions we are taking in the near to mid-term will better position us for the future and enhance shareholder value. Our current profitability does not meet our expectations, but we are taking the necessary steps to improve our performance.
Moving on to first quarter 2024. Results were in line with our expectations at the beginning of the year. First quarter sales were $1.1 billion, down 10% versus the first quarter of 2023 from volume declines, primarily in residential end markets and raw material-related selling price decreases. First quarter EBIT was $63 million, down $26 million versus the first quarter of 2023. Adjusted EBIT was $64 million, down $25 million versus first quarter 2023. EBIT and adjusted EBIT decreased primarily from lower volume, increased bad debt reserve, less benefit from a reduction to a contingent purchase price liability associated with a prior year acquisition, and the non-recurrence of pandemic-related cost reimbursements. These decreases were partially offset by lower current-year amortization expense.
Restructuring costs during the quarter were $11 million, comprised of $6 million in cash cost and $5 million in non-cash cost. The restructuring charges were mostly offset by gains from idle real estate sales and insurance proceeds of $8 million and $2 million, respectively. First quarter earnings per share and adjusted earnings per share were $0.23, a 41% decrease from first quarter 2023 EPS of $0.39.
Moving on to segment results. Sales in our Bedding Products segment decreased 15% versus first quarter 2023. Ongoing weakness in domestic and international bedding markets negatively impacted volume this quarter as demand continues to bounce along the bottom. US Spring volume was down 15% versus first quarter 2023, driven by declines in open coil and wire grids, partially offset by growth in higher-value semi-finished products, such as combination pocket and EcoBase. Domestic mattress market production was likely down high single-digits and we saw similar trends in ComfortCore demand. For the full year, we expect US mattress consumption to be slightly down versus 2023.
Susan Maklari
Good morning. My first question is, I want to start on the dividend. I guess, Mitch, can you just give us a bit more perspective on how the Board arrived at that $0.05, and maybe even some color on what it implies for the future earnings of Leggett? How do you think about what the business can generate once you get past the restructuring and all the changes that you’re implementing? Just any color there on how we should be thinking about those two pieces.
Mitchell Dolloff
Sure, Susan. Making a change to the dividend was, of course, a decision that we took very seriously. And it was important for us to consider a variety of options in making that change, as well as near and long-term impacts to our business. So the downturn in our residential end market demand has continued to pressure earnings for longer than we originally anticipated.
As we went through this process, we shifted from considering it to be a question of how can we fund the dividend at the current levels to whether we should fund the dividend at the current levels, as it became harder to balance our lower earnings, the increasing leverage and the elevated dividend payout ratio.
So, we’ve landed at the $0.20, because reducing to that level allows us to deleverage our balance sheet in a reasonable timeframe, continue to invest in our business, which we’ve mentioned before, we hadn’t been compromising CapEx or things like that. But as this drag on and the payout ratio continued to be really high, it was putting us in a spot to maybe we have to make some changes. And it also gives us the flexibility to refine our portfolio in the future if we think that’s appropriate.
So we remain committed to returning capital to shareholders, and we’re not walking away from that priority, but we’ll balance that with retaining this flexibility to invest in future growth. And we’ll also think about that — the shareholder returns, both through dividends and share repurchases over time.
To your question about the future earnings, we still feel really good about the restructuring activity that’s underway and some of the additional actions that we talked about in our reporting of operational improvements and looking at our G&A cost structure, things like that. So we feel like we still see that improvement in our earnings even in this near-term low-demand environment. We continue to see improvement and growth in Specialized Products earnings. And demand will start to come back at some point, but it’s hard to estimate when that is. Probably it depends on interest rates and inflation and some things like that.
So we’re really focused on dealing with the situation that we have on our hands today and driving improvement in our earnings in the near term, the midterm, and then returning to longer-term growth when things normalize a bit. So we’re confident in the situation we’re in and the opportunities that we have. But we felt like this was an appropriate action to give us the flexibility that we need to run our business for the long term.
May 7, 2024
Urethane Highlights from Stepan’s Investors Call
Stepan Company (NYSE:SCL) Q1 2024 Earnings Call Transcript
Scott Behrens: Good morning and thank you all for joining us today to discuss our first quarter 2024 results. I plan to share highlights from our first quarter performance, and we’ll also share updates on our key strategic priorities, while Luis will provide additional details on our financial results. The company reported first quarter adjusted EBITDA of $51.2 million, up 5% year-over-year. Global sales volume was up 1% year-over-year. Volume weakness in the agricultural market due to continued inventory destocking and lower phthalic anhydride volumes due to ongoing operational issues at our Millsdale site, mostly offset the strong recovery in volumes across our other core markets. Global sales volume, excluding the impact of agricultural and PA was up 4%.
Surfactants experienced double-digit volume growth in Personal Care and Oilfield end markets and with our distribution partners. As expected, Latin American surfactant volumes grew strong double-digits as we recovered volumes in Mexico. First quarter sales volume in Mexico was a record. Overall, volumes in our global Consumer, Laundry and Cleaning and our Institutional Cleaning businesses have stabilized and we believe destocking has run its course. Within Polymers, Rigid and Specialty Polyols grew mid-single digits, while Specialty Products volume was up double-digits. From a company perspective, margins were in line with expectations despite unfavorable product mix. Net sales in the first quarter of 2024 decreased 15% year-over-year, primarily due to lower selling prices that were mainly attributable to the pass-through of lower raw material costs and less favorable product mix.
These lower selling prices were partially offset by a 1% increase in global sales volume, as mentioned above, and the favorable impact of foreign currency translation. We generated positive free cash flow of $11.4 million as capital expenditures returned to historical levels, and these results give us confidence that we will close 2024 with positive free cash flow. The company is on track to deliver our $50 million cost reduction goal for 2024 through disciplined efforts in supply chain and workforce productivity actions taken in the last quarter of 2023. We expect these reductions to help offset higher operating costs related to operational interruptions at our Millsdale site and pre-commissioning expenses at our new alkoxylation facility in Pasadena, Texas.
Scott Behrens: Thanks, Luis. I’ll focus my comments on our cost initiatives, business strategy and the progress of our major capital investments
Our Polymers business continues to focus on developing the next-generation Rigid Polyol technologies that can increase the energy efficiency and cost performance of our customers’ insulation products. Moving to Slide 11, construction on our new alkoxylation production facility in Pasadena, Texas is approximately 90% complete and we now expect the plant to start up in the fourth quarter of 2024 due to a contractor delay. The underlining alkoxylation business that supports the Pasadena investment, excluding the agricultural destocking, continued its volume growth during the first quarter of 2024 at very attractive unit margins. After completing a 3-year capital investment program last year, Stepan now has the largest installed low 1,4-dioxane production capacity serving the North American merchant market.
Our first quarter volumes grew strong double-digits versus prior year and volumes should continue to ramp throughout the year as more customer and product qualifications are completed. As already reported in our February earnings call, our Millsdale site was impacted by a series of power disruptions combined with below freezing temperatures in January with the main impact to the phthalic anhydride and polyol unit operations. All operations other than phthalic anhydride have been in our back in production and we were able to minimize supply disruptions to our polyol customers through our production network. The PA unit experienced several restart challenges but has since been restarted and is producing products. In addition to the power weather interruption, we also experienced unplanned maintenance and operational issues with the Millsdale wastewater treatment plant.
Our team has been actively addressing these issues through infrastructure and process improvements. These operational issues impacted first quarter results primarily from higher maintenance and operational expense and higher tolling costs. We anticipate second quarter expenses related to these issues to be similar to the first quarter expenses. We anticipate to go back to normal and lower spending levels in the second half of the year. Looking forward, we believe sales volumes will continue to gradually improve due to the ongoing recovery in Rigid Polyols and growth in surfactant volumes, including the expected recovery of the agricultural business in the second half of this year. We remain focused on delivering $50 million in pre-tax cost reductions to help offset inflationary pressures, the expenses associated with commissioning our new Pasadena alkoxylation assets, higher incentive-based compensation and incremental expenses associated with the operational issues at Millsdale.
https://ca.finance.yahoo.com/news/stepan-company-nyse-scl-q1-144023127.html
 Everchem Updates Archive
 Sign Up for Email Updates