
Company News
November 2, 2023
Huntsman Earnings Call Urethane Highlights
Huntsman Corporation (HUN) Q3 2023 Earnings Call Transcript
Nov. 01, 2023 3:44 PM ETHuntsman Corporation (HUN)

141.44K Followers
Q3: 2023-10-31 Earnings Summary
EPS of $0.15 misses by $0.04 | Revenue of $1.51B (-25.11% Y/Y) misses by $60.92M
Huntsman Corporation (NYSE:HUN) Q3 2023 Results Conference Call November 1, 2023 10:00 AM ET
Company Participants
Ivan Marcuse – VP, IR
Peter Huntsman – Chairman, CEO & President
Phil Lister – EVP, CFO
Peter Huntsman
Ivan, thank you very much, and thank you all for taking the time to join us this morning. This past week, I had the opportunity to visit one of our largest aerospace customers with our Board of Directors. We watched firsthand as Huntsman’s composite raw materials were applied to some of the most fuel efficient and modern aircraft built anywhere in the world today. We also visited one of our plants that is making Germany’s premier sports cars lighter and consume less electricity. We spoke to our associates at the same plant who are responsible for making components for a smarter, more reliable power distribution and grid system.
I’d go on about the numerous applications that Huntsman is now pushing to serve a less energy intensive, but more energy-reliant economy. All this give me cause for optimism, and it’s a great reminder about our company’s position in the global marketplace.
Over the past 24 months, we’ve seen some of the strongest economic performance as we recovered from a global pandemic and subsequently among the most chaotic economic conditions as European energy policy seemingly collapsed, China’s bounced back stumbled along and North America’s construction markets took a beating over high interest rates and consumer uncertainty.
As we now have some visibility into the beginning of the fourth quarter, as I said during our last earnings call, we expect this to be a tough quarter depending on the amount of customer deinventoring we see and lack of consumer confidence. Our projections for the fourth quarter remain murky, as the real year-end seasonality does not yet start for a couple more weeks.
However, our customer and plant business demonstrates how vital our products are in an evolving global economy. We continue to see the recovery of the aerospace industry. In all of our other divisions, we will be a vital supplier to both the EV and ICE automotive industry. We continue to see growing demand in power and electronics, building insulation materials, cleaner solvents for the chip industry and expanding markets for lightweight and stronger materials.
We will pace our share buyback program to make sure we are both returning value to our shareholders and preserving a strong balance sheet that will assure our flexibility and allow us to capitalize on M&A opportunities.
During 2024, we will complete a $280 million cost realignment, a European restructuring program we announced over the past 2 years. This will help offset inflation, flatten our organization and allow us to compete more aggressively and respond quicker to market conditions.
As mentioned in our prepared remarks, we will be very conservative on our capital spend this next year. We will spend what is needed to assure our reliability and safety as well as investing in high-priority growth projects. Depending on the speed of an expected recovery in 2024, we will be ready to proceed with other projects as market conditions may warrant.
In short, as we conclude what has been a year with more challenges and opportunities, we believe that we’re in a unique position to rebound quickly as markets shift direction. We will also be calibrating our operations around a conservative approach to and capital allocation towards long-term shareholder return and reliability.
Aleksey Yefremov
Peter, it seems like China could be one of the main reasons, things global or so tough in MDI, in particular. Do you see anything in China to suggest a path for better 2024?
Peter Huntsman
Well, I think that it’ll — actually, first of all, it’s good to hear from you. And as I look at China, look, we’ve been saying for the past year that we’re seeing a slow and steady recovery taking place in China. I think we’re a little bit of an outlier earlier in the year when we were saying that people we’re expecting that there was going to be a very sudden bounce back. But I — we’re seeing in the housing market that interest rates are dropping. And typically, that will mean that there’ll be a recovery following, but we’re not overly reliant on that.
I think where we are invested on the domestic energy conservation in China around insulation, around building materials, around the EV market. We continue to get market share in the auto, both in ICE and in EV and in consumer goods and appliances. So our focus is not on the export segment of the Chinese economy rather the domestic consumption and building side of the Chinese economy.
And in that, I think that we’re going to just continue to see slow but steady growth and recovery in that area. And to that end, as I look at Chinese prices from the beginning of the year, they’re actually slightly up from where they started the year. And I think that we’re going to continue to see continued improvement throughout 2024 in China.
Phil Lister
Yes. Aleksey, I think it’s clear we’ve got a headwind going to the fourth quarter, particularly when you look at benzene, which averaged about $3.10 in quarter 3. It settled in October over $4. It settled for November at $3.65. Spot price is lower, but that is our largest raw material. Natural gas in Europe has also risen from approximately $10 a Btu to about $14 to $15 today. So some headwinds there, there are some benefits in the chlorine chain, with chlorine coming down, epichlorohydrin is falling. But those are outweighed by benzene and natural gas.
Michael Sison
Peter, when you think about, I guess, Polyurethanes in total, you’ve done a lot of things over the last several years going downstream and trying to improve the quality of the business. This year’s, for a lot of businesses, look really tough to see those changes. But when you think about, again, just thinking where the business see when things recur, maybe talk about whether EBITDA margins can get back to all this destock in difficult times end?
Peter Huntsman
Yes. I think that as we look at MDI, fundamentally, I do think that we’re in unprecedented downdraft right now with MDI, putting it mildly. The reason I say that is this is a product since I’ve been in it for the last 25 years, and some of the veterans that been in the last 30-plus years, we’ve not seen 2 consecutive years of falling demand. And that’s largely not about because of macroeconomic conditions. We’re not seeing competing materials. We’re not seeing a lots of people that are — or stopped building homes with OSP. They’ve stopped using MDI and furniture and bedding. And so it wasn’t anything. We see MDI continuing to expand its application base, its chemistry base and getting better.
So — I mean, if I look at the bare fundamentals, there’s absolutely no reason why this material during normal economic conditions, or even normal economic minus a bit, shouldn’t be doing immensely better than it’s doing today. And so I think that getting back to what I would see as mid-teens — plus mid-teens sort of margins. I personally don’t think that it’s going to take a great deal of change just from the sense that I don’t see any fundamentals in the business that have changed the broader outlook of MDI.
When U.S. housing comes back, that’s obviously a very large component of MDI demand. When people buy a new home, not only did the product that goes and build the home, but also to furnish a home and — means of furniture, bedding and paints and coatings, electronics and so forth. When you look at the automotive industry, particularly this last quarter, while we weren’t directly hit with strikes that we saw in North America, our customers weren’t hit by that. That did put more MDI on the market than you otherwise would have seen, probably having a detrimental effect.
And as we look at the global energy conservation and insulation areas around spray foam and insulation materials again, I look at those big macro issues. I see no reason why MDI shouldn’t recover. And when it recovers, I gladly predict — when it recovers, I think it’s going to surprise me how quickly it does.
Michael Sison
And as a quick follow-up. You referenced a Chinese MDIs in the prepared remarks. Where are we in the U.S. and Europe? And how much lower do you think will go into the fourth quarter on those prices? And do you think — what’s your thought about ’24? And what needs to happen to shore up all the regions?
Peter Huntsman
Well, fundamentally, in ’24, people need to stop tolerating losing money. And I think that, that fundamentally has to be a broad issue. It’s the age-old issue of any product that’s being bought and sold at very low margins, is that what’s the discipline of an industry to be able to sell a product and set a price to return money to shareholders. And right now, MDI is not doing that. And so fundamentally, I think that there needs to be a change in the entire MDI market.
Now that doesn’t just come about without economic recovery. It doesn’t come about through without customer demand returning. And those things will happen. But as I look at how close much of this is getting to fixed cost sort of return, it seems like we’re there. As I look at pricing in Europe, we’ve been able to get some modest increases in the fourth quarter. I’d like to say that’s because demand is improving, but I think it’s more just discipline. And there are signs that I’m saying or at least feeling that we’re to the bottom. But unfortunately, I think I’ve probably said that in the past. And so I’m not ready to call the bottom out, but I think that we’re very close to it.
Hassan Ahmed
On the polyurethane side of things, obviously, a bunch of questions around trying to sort of forecast demand, obviously, in our industry is always challenging to do. But it seems that the supply side of thing’s easier to forecast, right? So as you sort of sit there and look at polyurethane, sort of cost curves. I mean, in the response to one of your earlier questions, you talked about how margins are same for some of the marginal producers. You guys, yourselves, reported 8% EBITDA margins this quarter.
So I’m just trying to understand the marginal guys presumably are losing money right now. So with the supply looking the way it’s looking, I mean, do you forecast potentially shutdowns, more delays in capacity additions and the like and how will that play out as it pertains to a potential recovery going forward?
Peter Huntsman
I’m not sure that the recovery going forward is going to be dependent on any shutdowns. I am a bit surprised that, that hasn’t happened yet. As I look at the various regions, I look at the U.S. I don’t see a lot of shutdowns of total facilities in the U.S. because the major producers in the U.S. only have one facility. And I don’t see somebody exiting the North American market. And I think the same can be said for China.
Now there are people that are like — that have multiple facilities in China but I personally just don’t see them shutting one of down. They’re very competitive. They start with foam and they work their way through on a competitive set of economics.
Europe, in my opinion, longer term, when I look at the size of the facilities that are in Europe and the number of people that have multiple facilities in Europe, I do question the longer-term viability of some of those assets. But again, I’m not privy to decisions that are made, obviously. In those companies, I don’t know what their economics are. To the degree that they’ve got longer-term contracts with government-assisted money or with unions and so forth, I have no idea what limitations there might be on that. But fundamentally, I think that the industry is shutting down lines more than they’re shutting down facilities. And I think you’re probably going to continue to see that.
Phil Lister
The only supply coming to the market, Hassan, will really be 1 month over the next sort of 4 to 5 years, but there’s nothing else major that’s been announced and if the industry returns to its 4.5%, 5% growth level, then that will have strip supply as a rebound occurs.
Q – Unidentified Analyst
Perfect. And just a follow-up on the raw materials for MDI, besides a well-known increase in benzene prices, can you provide us a little bit with what you are assuming for Q4 in each of the key regions, Europe, China and the U.S. for other key raw materials, chlorine, et cetera?
Phil Lister
Yes. I think we said — so we outlined benzene, we outlined natural gas was headed in Europe intended to 15. Chlorine caustic under a little bit of downward pressure overall, so we built that in. This will remain I think — which are the two main raw materials, although they still represent a minority of Advanced Materials is coming off as well.
And then you’ve got ammonia, which is obviously a big raw material into Performance Products, which has been moving upwards. It moved down throughout the year, but it’s been moving upwards. That also impacts Polyurethanes in nitric — into nitric acid. So that’s the way to think about our raw material base pending still remains the biggest raw material that we purchase globally.
Peter Huntsman
And certainly, the most volatile — a lot of those products that Phil just mentioned on longer-term contracts or pass-through contracts with natural gas and so forth.
Matthew Blair
Peter, so it’s obviously a tough market, but your prepared comments did mention that building solutions volumes were up both quarter-over-quarter as well as year-over-year. So I don’t know that seems encouraging in the tough construction market. Should that be the read-through for investors? And do you have any more color here? And also, is this because you’re gaining share in the spray foam market or are there other dynamics at play?
Peter Huntsman
Well, a couple of things. First of all, last year, third quarter was a pretty tough year. I mean, it was a low point, I think, as we look at the overall business. But as you look at the third quarter, we’re up 2% from — versus the prior quarter. We’re up 10% a year ago.
If you look at some of our other products like the composite wood products and so forth, as we look at the order patterns thus far into fourth quarter, and I don’t want to get ahead of myself, but we’re seeing a positive year-on-year comparison there. And that’s the first time we’ve seen a positive comparison there for probably over a year on a quarterly basis.
So again, I’m not — I don’t want to get overly encouraged by this, but these are signs you first have to hit the bottom, and then you’re going to see a bounce back. So as I look at things from where we are in the third quarter, I think there’s some positive signs I’m seeing in HBS and the building solutions, all around in — areas around our total insulation business. From the prior quarter, it was up 3%.
From a year ago and again, this isn’t just spray foam. This is our installation that goes into rigid panels, construction panels and so forth, we’re down 4% over a year ago but up 3% sequentially. So starting to see, I think, signs that we’re hitting the bottom in some of these areas, and I’d like to think that we’re recovering in others of them.
So I would take those as — we call them green shoots, but I think it’s a tired metaphor because we’ve used it now the course in — and we haven’t seen much more than green shoots. But no, I think there’s probably more of those we see today than we did certainly a quarter ago.
November 1, 2023
Urethane Highlights from Covestro’s Investors Call
Covestro AG (CVVTF) Q3 2023 Earnings Call Transcript
Oct. 27, 2023 4:24 PM ETCovestro AG (CVVTF), COVTY
141.28K Followers
Covestro AG (OTCPK:CVVTF) Q3 2023 Earnings Conference Call October 27, 2023 9:30 AM ET
Company Participants
Ronald Koehler – Head, IR
Markus Steilemann – CEO
Christian Baier – CFO
Markus Steilemann
After these encouraging news, let us now come to the highlights of the last quarter. On the next page, you see the overall economic situation has not improved during the last quarter. Low demand and industry-wide price pressure as a result of oversupply across many core products are still ongoing.
With that, in the normal pass-through mechanism of lower raw material costs, our sales were significantly down year-on-year to €3.6 billion. In line with our guidance, we achieved a third quarter EBITDA of €277 million. Free operating cash flow strongly improved in the third quarter 2023 and came out at €308 million. This was supported by our ongoing stringent working capital management. As usually, with our Q3 results, we are narrowing our guidance range for the full year 2023.
Before ending on the highlights, let me briefly address the ADNOC situation. On September 8th, we announced to enter into open-ended discussions with Abu Dhabi National Oil Company. We are pursuing these discussions in good faith, open-minded, and in the interest of our shareholders and all other stakeholders.
We remain fully compliant in our communication approach and will only comment on the progress of the negotiations, if required by the European Market Abuse Regulation. As that is currently not the case we will refrain from any additional comments regarding the ADNOC topic.
Let’s move to the next page. Despite the still economically challenging times, we keep investing into the growth of our business. In the second quarter 2022, we presented to you our investment plans for our solutions and specialties entities Elastomers and Coatings and Adhesives.
A little more than one year later and exactly on time and on budget, I have the great pleasure to announce the completion and soon start of operation of both expansions. The first ramp-up was done early Q3 with the new elastomer production line in our integrated site in Shanghai. This plant and its products will especially serve renewable energy markets like wind energy and solar panels and also heavy-duty applications. In line with our strategy, the business unit elastomers will continue to regionally enlarge its production footprint.
In our business entity Coatings and Adhesives, the investments in two plants for polyester resins and polyurethane dispersions reached the milestone of full mechanical completion.
Now, further work is ongoing to get the plan to the ramp-up phase in the first quarter 2024. This is the first plant that has been constructed in a modular way in line with our build faster and cheaper program, underlining our cost-leading asset structure.
The products coming from these units are supporting the profitable growth of our CA business in a variety of products, catering for the automotive, construction, sports, and leisure as well as furniture industry.
Let’s now turn to the next page. Coming now to the volume development in the third quarter of 2023. Year-on-year, the global sales volume decreased by 3.8%. This was caused by ongoing demand weakness across all regions and limitations in our internal availability.
However, the rate of decline is now smaller compared to the previous quarters. As a reminder, first quarter was down by 17% and second quarter by 8% year-on-year. We still expect a positive low single-digit year-on-year growth in the fourth quarter.
Historically, a volume turnaround has always been followed by an improvement in margins, at least with a certain time lag. Auto remains on a growth path, still benefiting from a healthy order book. After five quarters of declining volumes in furniture, the sector turned around in the third quarter with mid-single-digit growth.
Also, Electronics developed flattish after four quarters of decline. The weakest sector remains construction.
Looking into the different regions, and large showed a return to growth path with increases in three of four industries important to Covestro after we partially solved the limitation on our internal chlorine supply.
As a result of the low comparison base furniture stands out with significant increase, whereas construction and auto showed a slight increase. Electrode was still slightly declining.
Sales volumes in North America also increased slightly across the two industries, electro and auto. Furniture showed a flattish development, but construction witnessed an ongoing significant decline.
After the positive volume development in Asia-Pacific in the second quarter, based on a low comparison basis from the COVID lockdowns last year, growth rates have normalized. Furniture and auto now exhibited slight growth and electrode showed a flattish development. Construction was still affected by a significant decline.
Markus Steilemann
Yes. Thanks Christian. And we are now coming on the next page to the outlook for Covestro’s core industries, and we’re now on Page number 13 of the presentation. The global GDP expectation has been almost flat since our last review and is estimated to be 2.5%.
Sadly, this flattish development does not hold true for most of the industry is important to Covestro. Only automotive is experiencing a positive volume growth, and this trend is continuing with an improved outlook of 7.9% now. The sub-category of EV or battery electric vehicles is against this trend experiencing a slight downgrade of 7.2 percentage points in growth, expecting now 35.3%.
This is still above any other growth rate we currently see in our core industries. The outlook for the construction industry has deteriorated further to minus 2.2% and residential construction has lost more than 4 percentage points in growth down to minus 4.3%. The reason for this trend are well known. High interest rates and high cost of building materials. Also, the furniture industry is seeing a reasonably accelerated negative trend with an expected second year of declining markets between 4% and 5%.
Only the demand outlook for Electro is seeing a flattish development as 0.4% can hardly be counted as growth. Here, the appliance sector is against the trend seeing an upgrade in its growth projections and is expected to show an increase of almost 8%.
Summarizing the data we can see that the development of most of our industries has significant room for improvement. This underlines our own evaluation of the current market conditions that a turn to a positive development is currently still not foreseeable near-term.
With this, let us now turn to the Covestro outlook for the full year 2023. As explained in the outlook for our core industries, there is no substantial indication of a short-term improved — improvement of the economic environment. We expect the ongoing demand weakness to continue at least for the remainder of the year.
Christian Baier
Yes. Thank you, Markus, and Christian, thank you for the welcome. Look forward to our future interactions. With respect to the topic of debt refinancing, we are obviously looking at various products that we’re having. At the moment, there is very significant cash that we have out, especially when we look at the bond maturing in the next year, we are talking about interest rates of below 2%.
In the current market where we are a couple of percentage points higher, we will certainly be very flexible to use available funds but also tap other sources of financing. As just recently, we have tapped the European Investment Bank for a very strong loan facility that we got there. So, we remain active in the capital markets in order to really look at what is the best solution at the time at hand with having a very broad spectrum of tools that are always available to us also in the current markets without the significant increases in the interest rates.
Jaideep Pandya
Yes. hello. I hope you can hear me. My first question really is around — my first question is around the €3 billion investment on the MDI project. I know, Markus, you’ve mentioned about ADNOC. I won’t make you very uncomfortable. But obviously, this is a topic which is very strategic for Covestro.
So, could you just give us some sort of information about how are you tackling this in the light of your discussions with a low in the sense? Is this on the table and being reviewed in totality? Or is this actually off the table because you have taken the project off the table. That’s my first question.
The second question goes back to — it’s sort of tied to the first question. It goes back to your point about €1 billion EBITDA growth even at current margins, 20% volume growth, so how do we get that to the €2.8 billion? Would the €800 million really have to come from improvement in spreads? And what sort of spread improvement that sort of quantifies — if you could just give us some color with regards to that?
And then the final question really is around the competitive landscape. I assume that your availability improves next year and you would like to take back some share presumably in and in MDI from the chlorine issue that you had. Key competitor in China is increasing capacity quite aggressively.
So, could you tell us like in a backdrop of low volume growth next year how do you see the competitive behavior? I mean are you willing to go a bit aggressive on pricing to get back to share? Or are you going to defend pricing as well? Thanks a lot.
Markus Steilemann
Yes, Jaideep. Thank you so much for your questions. Let me start with the first one. And that is totally unrelated to ongoing open-ended discussions with ADNOC. It is just a general explanation of the rationale to invest in MDI.
And maybe one, if you allow minor correction, we’re not talking about a €3 billion investment but the investment costs are rather around €2 billion, depending on where you invest, maybe slightly lower, maybe slightly higher and also depending on how you invest.
That means the way how you construct the plant might also have a significant impact about the total cost of the plant. So, long story short, the number is rather around €2 billion and not in the order of magnitude of €3 billion.
So, having said that, the decision to pause an MDI investment was not driven by financial means. It was driven by the current, let’s say, short-term, at least turbulent market dynamics in the MDI market and also the worries that we already could foresee in the current construction market.
We know that mid to long-term MDI is still in high demand, and it is still the best raw material for insulation panels for commercial as well, sorry, for commercial and residential buildings.
But we also have to very carefully assess when that growth is, let’s say, kicking in. And as we currently see the construction market is under big pressure. The construction market worries us a little bit at current times.
And from that perspective, I think it was a wise decision not to go for the respective MDI construction at the time when we had it on the table because it would have just further increased the price pressure on MDI and in the MDI markets.
So, from that perspective, I would say we are currently once again assessing when is the right moment in time to invest and we will let you know as soon as possible when we have taken the decision.
If you look at the supply/demand balance, last sentence to this, we see that there is actually towards the end of the 2020s, beginning of 30s, no additional supply capacity coming.
And from that perspective, we think at the right moment in time to once again go back to that investment decision is coming soon. Was that in terms of the €1 billion related or, let’s say, with the way to the €2.8 billion, I would actually hand over to Christian. Christian?
Markus Steilemann
Thanks. And Jaideep, to your next question about — yes, you called it market share, you adopt name drop words like price war. I think what is important that this 20% is an average number and an average global number. And that is important. Why? Because it is not only MDI and TDI, where we try to gain market share back it is also other products where we see significant room in increased asset utilization also in the Solutions and Specialty area, not to that same extent. But to, I would say, still reasonably high extent that would also contribute and help us to get back to higher volumes out of existing assets.
Secondly, at least from our perspective, Wanhua has always been a return-driven competitor who behaved very logical.
Thirdly, we believe that there is first signs of growth opportunities, at least from the second half of next year. And we must also not underestimate that, let’s say, if I may say, so the leading docs on the place are not directly getting into an infight, but there’s still a smaller docs, let’s say, in the backyard, which also produced at much higher cost than we do. So, there’s also an opportunity for us to gain market share, whilst at the same time, not getting heads on with one of the largest players in this market.
Fourthly, Wanhua has currently its largest asset base in China. And we know that many customers are looking at us, particularly in Europe and would love to have more material from us. And we have, in Europe, cost competitive assets compared to imports from Asia-Pacific, so landed costs.
And so from that perspective, overall, we believe there is sufficient room to sell out our fully running assets, particularly but not limited to Europe. Particularly in the — but not limited to the MDI as well as TDI space without entering to a price war. I hope that gives you some flavor.
November 1, 2023
Urethane Highlights from BASF Investors Call
BASF SE (BASFY) Q3 2023 Earnings Call Transcript
Oct. 31, 2023 10:56 AM ETBASF SE (BASFY), BFFAF

141.27K Followers
BASF SE (OTCQX:BASFY) Q3 2023 Earnings Conference Call October 31, 2023 6:00 AM ET
Company Participants
Stefanie Wettberg – SVP, Investor Relations
Martin Brudermüller – Chairman
Dirk Elvermann – CFO
Martin Brudermüller
Good morning, ladies and gentlemen. Dirk Elvermann and I would like to welcome you to our analyst conference call on the third quarter of 2023.
Let’s start with the development of global chemical production. Based on currently available data, the chemical industry was under further stress in Q3 as all regions exhibited a decline in production versus the prior year quarter with the exception of China.
The development in China was driven by recovering domestic demand for a broad range of chemical products in association with low sales prices, whereas global chemical production in total grew by 4.8%, including China, it decreased by 4.4% without China.
In Europe, chemical production slowed considerably compared with the prior year quarter. This was due to lower demand resulting from high inflation, increased interest rates, and a renewed rise in natural gas prices as well as front-loading of durable goods consumption during the COVID years.
In Q3 2023, European natural gas prices were still around 40% higher than the average between 2019 and 2021 and four times higher than the Henry Hub quotation for the quarter. Consequently, European chemical production continued to decline in Q3 2023 and shrank by 6.6% compared with the prior year quarter.
In North America, chemical production also declined compared with the prior year quarter in an environment of weak domestic demand from industries and end consumers.
Compared with the prior year quarter, chemical production was also weaker in Asia, excluding China. Subdued consumer spending and a strong import competition from China were the main reasons for this.
Let’s again have a closer look on current and historic levels of indicators for inventory in the manufacturing industry. On the slide, values below 50 indicate declining inventories, values above 50 indicate restocking.
In our Q2 2023 conference call, we mentioned that these indicators were below their long-term averages and in the range of historical inflection points from destocking to inventory buildup for Western Europe and North America.
The figures for Q3 2023 broadly confirm our expectations. The indicator for Western Europe improved marginally, signaling a slightly lower decline in inventories. The indicator for North America has moved further towards neutral. In Asia-Pacific, the inventory indicator is continuing to edge up, pointing to increasing inventories, amid the ongoing slow recovery of industrial production.
Overall, these observations and statistical data remain in line with the current development of order entries in our developing divisions — operating divisions. Particularly in China and India, we see firmer demand, while order entries are stabilizing in the other regions.
We now move on to BASF performance. Overall, BASF Group sales declined by 28% to €15.7 billion in Q3 2023, mainly due to lower prices and volumes. Price fell particularly in the Materials, Chemicals and Surface Technologies segments. But we are able to increase prices in Agricultural Solutions. Sales volumes were considerably lower than in the prior year quarter across all industries with the exception of automotive.
Dirk Elvermann
In the Materials segment, the considerable decline in EBIT before special items was driven by significantly lower earnings in the Monomers division, particularly as a result of lower prices. Earnings in the Performance Materials division fell slightly, mainly due to lower prices and volumes.
In the Materials segment, the considerable decline in EBIT before special items was driven by significantly lower earnings in the Monomers division, particularly as a result of lower prices.
In the light of the current macroeconomic environment, we have significantly trimmed our CapEx for 2023 to €5.3 billion, €1 billion less than the figure of €6.3 billion announced in February 2023. In addition, we will reduce CapEx further by a total of around €3 billion over the next four years.
Thus, for the five years period from 2023 to 2027, planned CapEx will be €24.8 billion, €4 billion lower than our original budget of €28.8 billion. While reducing the overall CapEx, we remain fully committed to our growth projects and our transformation towards climate neutrality.
With the cut in CapEx, we are not only simply postponing projects and investments. We are reducing the number of projects, we’ll implement alternative measures that involve less lower CapEx, and take advantage of the subdued market environment to lower investment costs as our procurement team in China is impressively demonstrating. On February 23, 2024, we will present the new CapEx budget for the planning period from 2024 to 2028.
We are continuing to broaden the foundation for BASF’s future profitable growth. In this context, let me provide you with an update on our Verbund site project in Zhanjiang. The project execution is on time and in budget. Last month, the second downstream plant for thermoplastic polyurethane, in short TPU, successfully started up.
We are stepping up our construction activities according to plan, and there are currently more than 15,000 construction workers on the site every day. The photo of the side shows the impressive progress that our team in China has achieved.
We are taking advantage of the attractive financing conditions in China and are financing the Zhanjiang Verbund site with a combination of 20% equity and 80% debt.
The equity is funded by dividends from the BASF existing group companies in China. The debt financing will be based on the Chinese capital market and local bank financing. We are proud that BASF is able to independently execute such a megaproject in these challenging economic times.
Sam Perry
Hi, thanks for taking my questions. Two, please. Firstly, on inventories. You are around €1 billion lower than at the end of 2022. How much of that is a function of reducing your own volumes of inventory and how much mark-to-market for lower prices? And how much scope do you have to reduce this further by the year end?
Dirk Elvermann
Yes, thanks. Maybe I’ll start with the inventory question. So, we have it both. We have a significant portion in the inventory volume. So, the OIVs. We also have certainly, back wind from FX and prices, but a substantial part of the inventory reduction is coming from the volumes build down.
So, we really started here a structural inventory improvement program, which is a rolling program, this goes further and further and we are intending to continue with that.
Just to give you glimpse of an idea. We were in the years until 2017, running our inventory level of €10 billion and still able to generate EBITDA at a level of €10 billion to €11 billion. And I think this indicates now we’re currently sitting at €15.1 billion, that there is still room for improvement and we will vigorously continue with that. Yes, over to Martin.
October 30, 2023
L&P Results
LEGGETT & PLATT REPORTS 3Q RESULTS
Oct. 30, 2023 4:10 PM ETLeggett & Platt, Incorporated (LEG)
CARTHAGE, Mo., Oct. 30, 2023 /PRNewswire/ —
- 3Q sales of $1.18 billion, a 9% decrease vs 3Q22
- 3Q EPS of $.39, a decrease of $.13 vs 3Q22; 3Q adjusted1 EPS of $.36, down $.16 vs 3Q22
- 3Q cash from operations of $144 million, a $78 million increase vs 3Q22
- 2023 guidance lowered: sales of $4.7–$4.75 billion; EPS of $1.45–$1.55, adjusted1 EPS of $1.35–$1.45
President and CEO Mitch Dolloff commented, “I would like to thank our employees for their tremendous efforts in what was another challenging quarter. Ongoing weak demand impacted our Bedding Products and Furniture, Flooring, & Textile Products segments but was partially offset by continued demand strength in our Specialized Products segment.
“We are lowering our full year guidance to reflect continued volatility in the macroeconomic environment, continued low consumer demand in residential end markets, and the modest impact we have experienced so far from the UAW strike on several North American automakers. The UAW strike had minimal impact on our Automotive business in the third quarter. So far in the fourth quarter, the sales impact has been approximately $5 million, which may not be indicative of future impacts. Due to uncertainties around the duration and severity of the strike, our updated full year guidance does not include impacts beyond what we have experienced so far.
“We are focused on anticipating and adapting to market changes, improving operating efficiency, driving strong cash management, and engaging with our customers on new product opportunities. We are evaluating opportunities across our businesses, including further integration of our specialty foam and innerspring operations, that are expected to support improved profitability, a strong balance sheet, and continued shareholder returns.”
THIRD QUARTER RESULTS
Third quarter sales were $1.18 billion, a 9% decrease versus third quarter last year.
- Organic sales2 were down 11%
- Volume was down 6%, primarily from demand softness in domestic residential end markets, partially offset by growth in our Aerospace and Automotive businesses
- Raw material-related selling price decreases, net of currency benefit, reduced sales 5%
- Acquisitions increased sales 2%
Third quarter EBIT was $91 million, down $22 million or 19% from third quarter 2022 EBIT, and adjusted1 EBIT was $86 million, a $27 million decrease.
- EBIT and adjusted1 EBIT decreased primarily from lower metal margin in our Steel Rod business and lower volume in residential end markets. These decreases were partially offset by lower incentive compensation and lower bad debt expense.
- 3Q 2023 adjustment is for a $5 million gain from a real estate sale within our Bedding segment
- EBIT margin was 7.8% and adjusted1 EBIT margin was 7.3%, down from 8.7% in the third quarter of 2022
Third quarter EPS was $.39, a $.13 decrease versus third quarter 2022 EPS. Third quarter adjusted1 EPS was $.36, down $.16 versus third quarter 2022 EPS.
DEBT, CASH FLOW, AND LIQUIDITY
- Net Debt1 was 3.15x trailing 12-month adjusted EBITDA1
- Debt at September 30
- Total debt of $2.0 billion, including $171 million of commercial paper outstanding
- No significant maturities until November 2024
- Operating cash flow was $144 million in the third quarter, an increase of $78 million versus third quarter 2022, reflecting working capital improvements partially offset by lower earnings
- Capital expenditures were $22 million
- Total liquidity was $595 million at September 30
- $274 million cash on hand
- $321 million in capacity remaining under revolving credit facility
DIVIDEND
- In August, Leggett & Platt’s (LEG) Board of Directors declared a $.46 per share third quarter dividend, two cents higher than last year’s third quarter dividend
STOCK REPURCHASES
- Net issuances of .1 million shares through employee benefit plans
- Shares outstanding at the end of the third quarter were 133.3 million
2023 GUIDANCE
- Full year 2023 sales and EPS guidance lowered. Guidance does not include impacts from the UAW strike beyond what we have experienced so far due to uncertainties around the duration and severity of the strike.
- Sales are expected to be $4.7–$4.75 billion, -8% to -9% versus 2022
- Volume at the midpoint expected to be down mid-single digits:
- Down high single digits in Bedding Products Segment
- Up high single digits in Specialized Products Segment
- Down low double digits in Furniture, Flooring & Textile Products Segment
- Raw material-related price decreases and currency impact combined expected to reduce sales mid-single digits
- Acquisitions completed in 2022 expected to add ~2% to sales
- Volume at the midpoint expected to be down mid-single digits:
- EPS is expected to be $1.45–$1.55
- Decrease is primarily from lower expected volume in our Furniture, Flooring & Textile Products and Bedding Products segments
- Includes anticipated gain from net insurance proceeds from tornado damage of ~$.07 per share and gain on the sale of real estate of $.03 per share
- Adjusted EPS is expected to be $1.35–$1.45
- Based on this framework, EBIT margin should be 7.4%–7.7%; adjusted EBIT margin should be 7.0%–7.3%
- Additional expectations:
- Depreciation and amortization $185 million
- Net interest expense $85 million
- Effective tax rate 24%
- Fully diluted shares 137 million
- Operating cash flow $450–$500 million
- Capital expenditures $110–$130 million
- Dividends $240 million
- Minimal acquisitions and share repurchases
- Implied 4Q Guidance:
- Sales: $1.09–$1.14 billion
- EPS: $.27–$.37
- Adjusted EPS: $.22–$.32
- Prior Full Year Guidance:
- Sales: $4.75–$4.95 billion
- EPS: $1.50–$1.70
- Adjusted EPS: $1.45–$1.65
SEGMENT RESULTS – Third Quarter 2023 (versus 3Q 2022)
Bedding Products –
- Trade sales decreased 17%
- Volume decreased 8%, primarily due to demand softness in domestic markets
- Raw material-related selling price decreases reduced sales 10%
- Currency benefit increased sales 1%
- EBIT decreased $13 million, primarily from lower metal margin and lower volume, partially offset by a $5 million gain from a real estate sale
Specialized Products –
- Trade sales increased 10%
- Volume increased 3% from growth in Aerospace and Automotive
- Raw material-related selling price decreases were offset by currency benefit
- Hydraulic Cylinders acquisition completed in August 2022 added 7%
- EBIT was flat on higher sales primarily offset by consolidation costs at an Automotive facility and the lag associated with passing through raw material-related pricing changes in Hydraulic Cylinders
Furniture, Flooring & Textile Products –
- Trade sales decreased 11%
- Volume decreased 11%, with declines across the segment
- Raw material-related selling price decreases, net of currency benefit, reduced sales 3%
- Textiles acquisitions added 3%
- EBIT decreased $9 million, primarily from lower volume
SLIDES AND CONFERENCE CALL
A set of slides containing summary financial information is available from the Investor Relations section of Leggett’s website at www.leggett.com. Management will host a conference call at 7:30 a.m. Central (8:30 a.m. Eastern) on Tuesday, October 31. The webcast can be accessed from Leggett’s website. The dial-in number is (201) 689-8341; there is no passcode.
October 29, 2023
Klaussner Assets Headed for Liquidation
Klaussner Furniture assets to be liquidated
By Larry Adams
October 26, 2023 | 11:16 am CDT
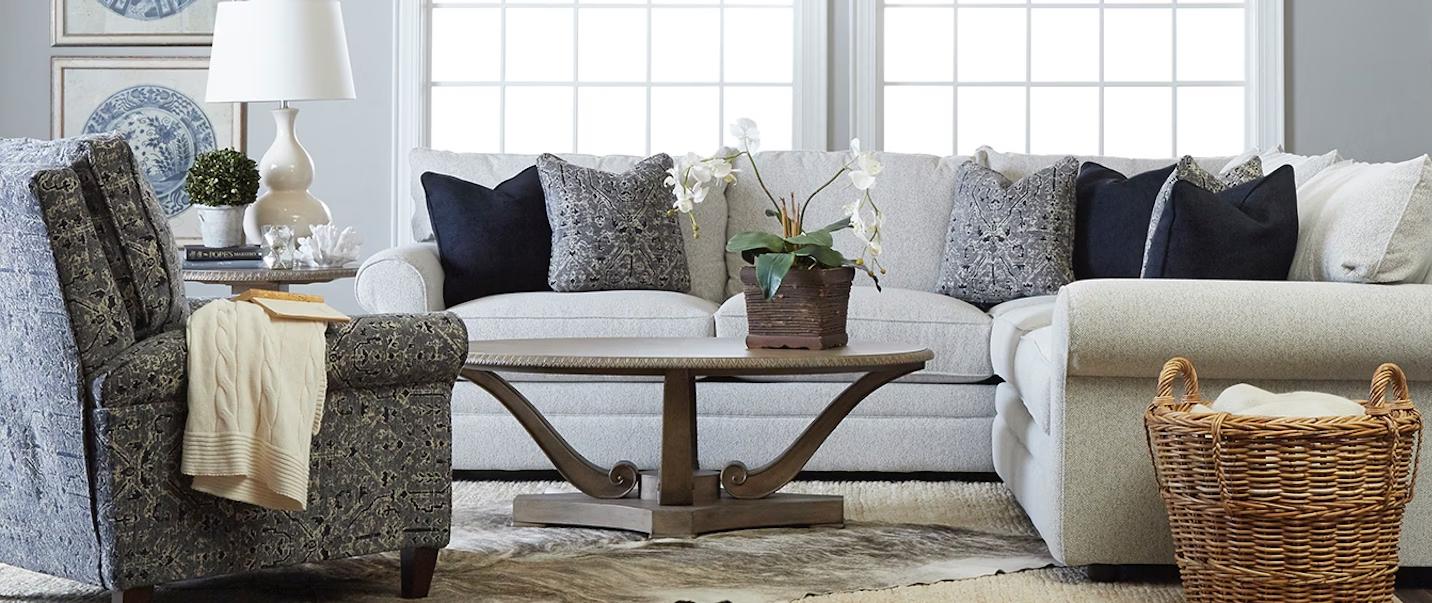
The disposition firm will negotiate sales with Klaussner’s existing customers, who are already familiar with the current models and styles available. In addition, SB360 will expand outreach to other national and regional furniture retailers.
Photo By Klaussner
BOSTON — A leading asset disposition and advisory firm has been selected as the exclusive agent for the disposition of finished goods, work-in-process inventory, and raw materials for Klaussner Furniture Industries, Inc., Asheboro, North Carolina.
The engagement of SB360 Capital Partners will aid the wind-down of operations following the closure of Klaussner’s facilities in August.
Established in 1963, Klaussner Furniture Industries is headquartered in Asheboro and operates multiple manufacturing facilities and distribution centers across the United States. The company offers an expansive assortment of value-driven furniture products, including sofas, recliners, sectionals, bedroom sets, and dining room furniture.
SB360 Capital Partners has a track record of successfully assisting companies in various industries, from retail to manufacturing, with their inventory disposition needs. The firm’s direct furniture affiliations and extensive furniture experience will be pivotal to optimizing the outcome of selling Klaussner’s inventory. SB360 has worked with many well-known furniture retailers and manufacturers, including recent transactions with United Furniture Industries (Lane), Thomasville, Henredon, Drexel, Broyhill, Art Van, and Loves Furniture.
As Klaussner’s products are highly desirable, SB360 will negotiate sales with Klaussner’s existing customers, who are already familiar with the current models and styles available. In addition, SB360 will expand outreach to other national and regional furniture retailers and wholesale distributors. For inventory and merchandise inquiries, please email info@klaussnerliquidation.com.
“Klaussner’s products are sold by major retailers and furniture dealers across the country,” said Aaron Miller, President of SB360 Capital Partners. “This is an opportunity for those retailers to expand their in-stock Klaussner offering and provide customers with a value proposition that will be meaningful as we head into the holiday season.”
Prior to the company’s closure, Klaussner was ranked #36 on the FDMC 300 list of top North American wood products manufacturers with $347 million in 2022 sales.
 Everchem Updates Archive
 Sign Up for Email Updates