
Company News
November 1, 2023
Urethane Highlights from BASF Investors Call
BASF SE (BASFY) Q3 2023 Earnings Call Transcript
Oct. 31, 2023 10:56 AM ETBASF SE (BASFY), BFFAF

141.27K Followers
BASF SE (OTCQX:BASFY) Q3 2023 Earnings Conference Call October 31, 2023 6:00 AM ET
Company Participants
Stefanie Wettberg – SVP, Investor Relations
Martin Brudermüller – Chairman
Dirk Elvermann – CFO
Martin Brudermüller
Good morning, ladies and gentlemen. Dirk Elvermann and I would like to welcome you to our analyst conference call on the third quarter of 2023.
Let’s start with the development of global chemical production. Based on currently available data, the chemical industry was under further stress in Q3 as all regions exhibited a decline in production versus the prior year quarter with the exception of China.
The development in China was driven by recovering domestic demand for a broad range of chemical products in association with low sales prices, whereas global chemical production in total grew by 4.8%, including China, it decreased by 4.4% without China.
In Europe, chemical production slowed considerably compared with the prior year quarter. This was due to lower demand resulting from high inflation, increased interest rates, and a renewed rise in natural gas prices as well as front-loading of durable goods consumption during the COVID years.
In Q3 2023, European natural gas prices were still around 40% higher than the average between 2019 and 2021 and four times higher than the Henry Hub quotation for the quarter. Consequently, European chemical production continued to decline in Q3 2023 and shrank by 6.6% compared with the prior year quarter.
In North America, chemical production also declined compared with the prior year quarter in an environment of weak domestic demand from industries and end consumers.
Compared with the prior year quarter, chemical production was also weaker in Asia, excluding China. Subdued consumer spending and a strong import competition from China were the main reasons for this.
Let’s again have a closer look on current and historic levels of indicators for inventory in the manufacturing industry. On the slide, values below 50 indicate declining inventories, values above 50 indicate restocking.
In our Q2 2023 conference call, we mentioned that these indicators were below their long-term averages and in the range of historical inflection points from destocking to inventory buildup for Western Europe and North America.
The figures for Q3 2023 broadly confirm our expectations. The indicator for Western Europe improved marginally, signaling a slightly lower decline in inventories. The indicator for North America has moved further towards neutral. In Asia-Pacific, the inventory indicator is continuing to edge up, pointing to increasing inventories, amid the ongoing slow recovery of industrial production.
Overall, these observations and statistical data remain in line with the current development of order entries in our developing divisions — operating divisions. Particularly in China and India, we see firmer demand, while order entries are stabilizing in the other regions.
We now move on to BASF performance. Overall, BASF Group sales declined by 28% to €15.7 billion in Q3 2023, mainly due to lower prices and volumes. Price fell particularly in the Materials, Chemicals and Surface Technologies segments. But we are able to increase prices in Agricultural Solutions. Sales volumes were considerably lower than in the prior year quarter across all industries with the exception of automotive.
Dirk Elvermann
In the Materials segment, the considerable decline in EBIT before special items was driven by significantly lower earnings in the Monomers division, particularly as a result of lower prices. Earnings in the Performance Materials division fell slightly, mainly due to lower prices and volumes.
In the Materials segment, the considerable decline in EBIT before special items was driven by significantly lower earnings in the Monomers division, particularly as a result of lower prices.
In the light of the current macroeconomic environment, we have significantly trimmed our CapEx for 2023 to €5.3 billion, €1 billion less than the figure of €6.3 billion announced in February 2023. In addition, we will reduce CapEx further by a total of around €3 billion over the next four years.
Thus, for the five years period from 2023 to 2027, planned CapEx will be €24.8 billion, €4 billion lower than our original budget of €28.8 billion. While reducing the overall CapEx, we remain fully committed to our growth projects and our transformation towards climate neutrality.
With the cut in CapEx, we are not only simply postponing projects and investments. We are reducing the number of projects, we’ll implement alternative measures that involve less lower CapEx, and take advantage of the subdued market environment to lower investment costs as our procurement team in China is impressively demonstrating. On February 23, 2024, we will present the new CapEx budget for the planning period from 2024 to 2028.
We are continuing to broaden the foundation for BASF’s future profitable growth. In this context, let me provide you with an update on our Verbund site project in Zhanjiang. The project execution is on time and in budget. Last month, the second downstream plant for thermoplastic polyurethane, in short TPU, successfully started up.
We are stepping up our construction activities according to plan, and there are currently more than 15,000 construction workers on the site every day. The photo of the side shows the impressive progress that our team in China has achieved.
We are taking advantage of the attractive financing conditions in China and are financing the Zhanjiang Verbund site with a combination of 20% equity and 80% debt.
The equity is funded by dividends from the BASF existing group companies in China. The debt financing will be based on the Chinese capital market and local bank financing. We are proud that BASF is able to independently execute such a megaproject in these challenging economic times.
Sam Perry
Hi, thanks for taking my questions. Two, please. Firstly, on inventories. You are around €1 billion lower than at the end of 2022. How much of that is a function of reducing your own volumes of inventory and how much mark-to-market for lower prices? And how much scope do you have to reduce this further by the year end?
Dirk Elvermann
Yes, thanks. Maybe I’ll start with the inventory question. So, we have it both. We have a significant portion in the inventory volume. So, the OIVs. We also have certainly, back wind from FX and prices, but a substantial part of the inventory reduction is coming from the volumes build down.
So, we really started here a structural inventory improvement program, which is a rolling program, this goes further and further and we are intending to continue with that.
Just to give you glimpse of an idea. We were in the years until 2017, running our inventory level of €10 billion and still able to generate EBITDA at a level of €10 billion to €11 billion. And I think this indicates now we’re currently sitting at €15.1 billion, that there is still room for improvement and we will vigorously continue with that. Yes, over to Martin.
October 30, 2023
L&P Results
LEGGETT & PLATT REPORTS 3Q RESULTS
Oct. 30, 2023 4:10 PM ETLeggett & Platt, Incorporated (LEG)
CARTHAGE, Mo., Oct. 30, 2023 /PRNewswire/ —
- 3Q sales of $1.18 billion, a 9% decrease vs 3Q22
- 3Q EPS of $.39, a decrease of $.13 vs 3Q22; 3Q adjusted1 EPS of $.36, down $.16 vs 3Q22
- 3Q cash from operations of $144 million, a $78 million increase vs 3Q22
- 2023 guidance lowered: sales of $4.7–$4.75 billion; EPS of $1.45–$1.55, adjusted1 EPS of $1.35–$1.45
President and CEO Mitch Dolloff commented, “I would like to thank our employees for their tremendous efforts in what was another challenging quarter. Ongoing weak demand impacted our Bedding Products and Furniture, Flooring, & Textile Products segments but was partially offset by continued demand strength in our Specialized Products segment.
“We are lowering our full year guidance to reflect continued volatility in the macroeconomic environment, continued low consumer demand in residential end markets, and the modest impact we have experienced so far from the UAW strike on several North American automakers. The UAW strike had minimal impact on our Automotive business in the third quarter. So far in the fourth quarter, the sales impact has been approximately $5 million, which may not be indicative of future impacts. Due to uncertainties around the duration and severity of the strike, our updated full year guidance does not include impacts beyond what we have experienced so far.
“We are focused on anticipating and adapting to market changes, improving operating efficiency, driving strong cash management, and engaging with our customers on new product opportunities. We are evaluating opportunities across our businesses, including further integration of our specialty foam and innerspring operations, that are expected to support improved profitability, a strong balance sheet, and continued shareholder returns.”
THIRD QUARTER RESULTS
Third quarter sales were $1.18 billion, a 9% decrease versus third quarter last year.
- Organic sales2 were down 11%
- Volume was down 6%, primarily from demand softness in domestic residential end markets, partially offset by growth in our Aerospace and Automotive businesses
- Raw material-related selling price decreases, net of currency benefit, reduced sales 5%
- Acquisitions increased sales 2%
Third quarter EBIT was $91 million, down $22 million or 19% from third quarter 2022 EBIT, and adjusted1 EBIT was $86 million, a $27 million decrease.
- EBIT and adjusted1 EBIT decreased primarily from lower metal margin in our Steel Rod business and lower volume in residential end markets. These decreases were partially offset by lower incentive compensation and lower bad debt expense.
- 3Q 2023 adjustment is for a $5 million gain from a real estate sale within our Bedding segment
- EBIT margin was 7.8% and adjusted1 EBIT margin was 7.3%, down from 8.7% in the third quarter of 2022
Third quarter EPS was $.39, a $.13 decrease versus third quarter 2022 EPS. Third quarter adjusted1 EPS was $.36, down $.16 versus third quarter 2022 EPS.
DEBT, CASH FLOW, AND LIQUIDITY
- Net Debt1 was 3.15x trailing 12-month adjusted EBITDA1
- Debt at September 30
- Total debt of $2.0 billion, including $171 million of commercial paper outstanding
- No significant maturities until November 2024
- Operating cash flow was $144 million in the third quarter, an increase of $78 million versus third quarter 2022, reflecting working capital improvements partially offset by lower earnings
- Capital expenditures were $22 million
- Total liquidity was $595 million at September 30
- $274 million cash on hand
- $321 million in capacity remaining under revolving credit facility
DIVIDEND
- In August, Leggett & Platt’s (LEG) Board of Directors declared a $.46 per share third quarter dividend, two cents higher than last year’s third quarter dividend
STOCK REPURCHASES
- Net issuances of .1 million shares through employee benefit plans
- Shares outstanding at the end of the third quarter were 133.3 million
2023 GUIDANCE
- Full year 2023 sales and EPS guidance lowered. Guidance does not include impacts from the UAW strike beyond what we have experienced so far due to uncertainties around the duration and severity of the strike.
- Sales are expected to be $4.7–$4.75 billion, -8% to -9% versus 2022
- Volume at the midpoint expected to be down mid-single digits:
- Down high single digits in Bedding Products Segment
- Up high single digits in Specialized Products Segment
- Down low double digits in Furniture, Flooring & Textile Products Segment
- Raw material-related price decreases and currency impact combined expected to reduce sales mid-single digits
- Acquisitions completed in 2022 expected to add ~2% to sales
- Volume at the midpoint expected to be down mid-single digits:
- EPS is expected to be $1.45–$1.55
- Decrease is primarily from lower expected volume in our Furniture, Flooring & Textile Products and Bedding Products segments
- Includes anticipated gain from net insurance proceeds from tornado damage of ~$.07 per share and gain on the sale of real estate of $.03 per share
- Adjusted EPS is expected to be $1.35–$1.45
- Based on this framework, EBIT margin should be 7.4%–7.7%; adjusted EBIT margin should be 7.0%–7.3%
- Additional expectations:
- Depreciation and amortization $185 million
- Net interest expense $85 million
- Effective tax rate 24%
- Fully diluted shares 137 million
- Operating cash flow $450–$500 million
- Capital expenditures $110–$130 million
- Dividends $240 million
- Minimal acquisitions and share repurchases
- Implied 4Q Guidance:
- Sales: $1.09–$1.14 billion
- EPS: $.27–$.37
- Adjusted EPS: $.22–$.32
- Prior Full Year Guidance:
- Sales: $4.75–$4.95 billion
- EPS: $1.50–$1.70
- Adjusted EPS: $1.45–$1.65
SEGMENT RESULTS – Third Quarter 2023 (versus 3Q 2022)
Bedding Products –
- Trade sales decreased 17%
- Volume decreased 8%, primarily due to demand softness in domestic markets
- Raw material-related selling price decreases reduced sales 10%
- Currency benefit increased sales 1%
- EBIT decreased $13 million, primarily from lower metal margin and lower volume, partially offset by a $5 million gain from a real estate sale
Specialized Products –
- Trade sales increased 10%
- Volume increased 3% from growth in Aerospace and Automotive
- Raw material-related selling price decreases were offset by currency benefit
- Hydraulic Cylinders acquisition completed in August 2022 added 7%
- EBIT was flat on higher sales primarily offset by consolidation costs at an Automotive facility and the lag associated with passing through raw material-related pricing changes in Hydraulic Cylinders
Furniture, Flooring & Textile Products –
- Trade sales decreased 11%
- Volume decreased 11%, with declines across the segment
- Raw material-related selling price decreases, net of currency benefit, reduced sales 3%
- Textiles acquisitions added 3%
- EBIT decreased $9 million, primarily from lower volume
SLIDES AND CONFERENCE CALL
A set of slides containing summary financial information is available from the Investor Relations section of Leggett’s website at www.leggett.com. Management will host a conference call at 7:30 a.m. Central (8:30 a.m. Eastern) on Tuesday, October 31. The webcast can be accessed from Leggett’s website. The dial-in number is (201) 689-8341; there is no passcode.
October 29, 2023
Klaussner Assets Headed for Liquidation
Klaussner Furniture assets to be liquidated
By Larry Adams
October 26, 2023 | 11:16 am CDT
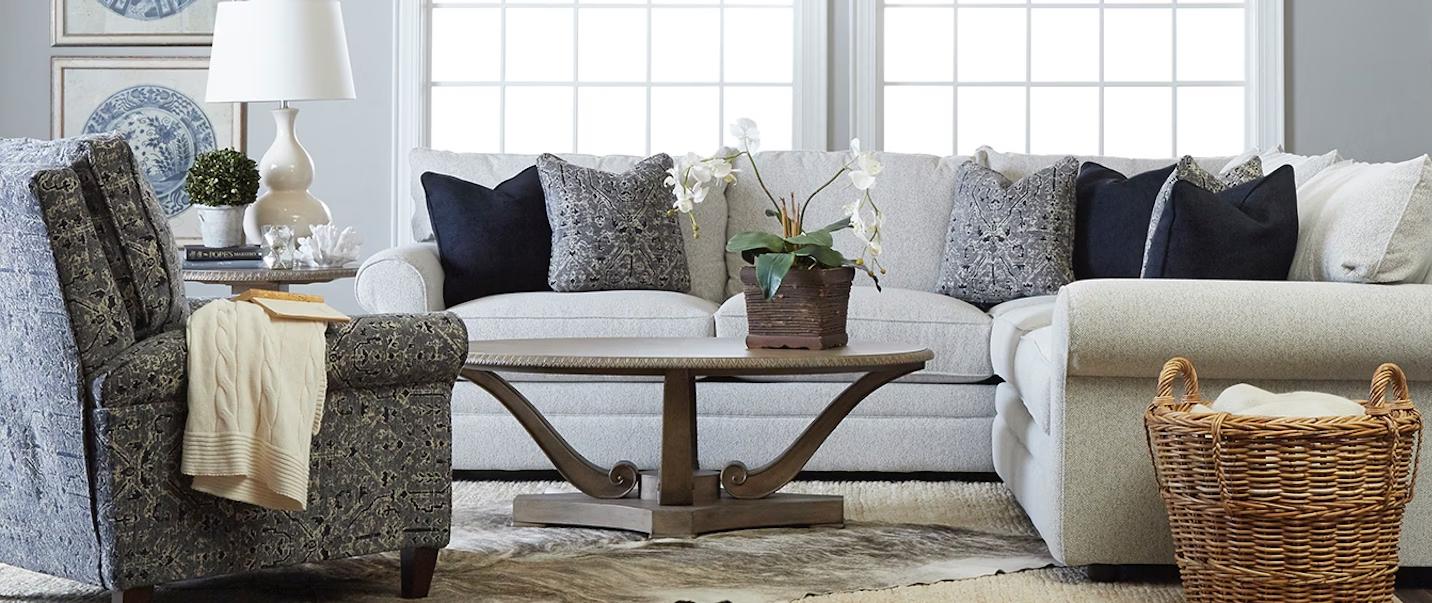
The disposition firm will negotiate sales with Klaussner’s existing customers, who are already familiar with the current models and styles available. In addition, SB360 will expand outreach to other national and regional furniture retailers.
Photo By Klaussner
BOSTON — A leading asset disposition and advisory firm has been selected as the exclusive agent for the disposition of finished goods, work-in-process inventory, and raw materials for Klaussner Furniture Industries, Inc., Asheboro, North Carolina.
The engagement of SB360 Capital Partners will aid the wind-down of operations following the closure of Klaussner’s facilities in August.
Established in 1963, Klaussner Furniture Industries is headquartered in Asheboro and operates multiple manufacturing facilities and distribution centers across the United States. The company offers an expansive assortment of value-driven furniture products, including sofas, recliners, sectionals, bedroom sets, and dining room furniture.
SB360 Capital Partners has a track record of successfully assisting companies in various industries, from retail to manufacturing, with their inventory disposition needs. The firm’s direct furniture affiliations and extensive furniture experience will be pivotal to optimizing the outcome of selling Klaussner’s inventory. SB360 has worked with many well-known furniture retailers and manufacturers, including recent transactions with United Furniture Industries (Lane), Thomasville, Henredon, Drexel, Broyhill, Art Van, and Loves Furniture.
As Klaussner’s products are highly desirable, SB360 will negotiate sales with Klaussner’s existing customers, who are already familiar with the current models and styles available. In addition, SB360 will expand outreach to other national and regional furniture retailers and wholesale distributors. For inventory and merchandise inquiries, please email info@klaussnerliquidation.com.
“Klaussner’s products are sold by major retailers and furniture dealers across the country,” said Aaron Miller, President of SB360 Capital Partners. “This is an opportunity for those retailers to expand their in-stock Klaussner offering and provide customers with a value proposition that will be meaningful as we head into the holiday season.”
Prior to the company’s closure, Klaussner was ranked #36 on the FDMC 300 list of top North American wood products manufacturers with $347 million in 2022 sales.
October 29, 2023
Recticel Results
Recticel Trading update third quarter 2023

Regulated information, Brussels, 27/10/2023 — 06:55 CET, 27.10.2023
- Third quarter net sales decrease from € 160.2 million in 2022 to € 132.3 million (-17.5%) in 2023
- Year-to-date September net sales decrease from € 447.5 million in 2022 to € 398.4 million (-11.0%) in 2023
- Net cash position: € 155.6 million (30 June 2023: net cash position € 142.3 million ; 31 December 2022: net financial debt of € 250.0 million)
- Divestment of the 33% share in Orsa Foam completed on 11 October 2023 and first instalment received
Jan Vergote (CEO Recticel): “European construction markets have further contracted throughout the third quarter of 2023.
Compared to the first half of 2023, our Insulated Panels activity has increased volumes and profitability generally in line with our previous outlook and will also enter 2024 with a stronger order book then at the start of 2023.
On the contrary, our Insulation Boards activity has been confronted with additional margin pressure, severely impacting profitability.
These market trends have been observed now in all European countries and our teams are working on several projects to compensate for these shortfalls going into 2024, as no material improvement in market conditions is expected.
Our net cash position has further improved to € 155.6 million since June 2023, linked to disciplined working capital management, some M&A related incoming payments and positive interest income. We continue to further explore several acquisition opportunities to enhance our market and segment positions in Europe.”
OUTLOOK
While Insulated Panels has improved its performance compared to the first half of 2023, Insulation Boards’ profitability has further deteriorated due to increased competition in depressed markets.
In this context, we have to adjust our guidance downwards and expect our full year 2023 Adjusted EBITDA to come out between € 35-40 million.
https://www.recticel.com/recticel-trading-update-third-quarter-2023.html
October 25, 2023
Invista to Close HMDA Plant in Texas

INVISTA decision to close Orange facility catches many by surprise Published 3:09 pm Thursday, October 5, 2023 By Staff Reports (invista.com) INVISTA’s announcement that it is shutting down production at its Orange facility was unexpected news to many.
Orange County Judge John Gothia said he was informed of the news Thursday. “Anytime we have a shut down or loss of jobs in the community, it’s never a good day,” Gothia said.
Gothia said the county has a number of programs to entice businesses to the area and stay competitive, but there’s not a lot to offer to keep an existing business. Looking toward the positive, Gothia noted there are a lot of growth and job opportunities on the horizon in Orange County coming in the next year, in addition to Lamar State College Orange offering a number of training programs to aid job seekers.
INVISTA operates its facility at 3055 FM 1006 in Orange. Francis Murphy, INVISTA president and CEO, said they appreciate the diligent and innovative work of employees at the Orange site over the years. “Unfortunately, lower than anticipated growth and an increase in global supply led to this difficult decision,” a company statement read. The site will begin the safe shutdown of the adiponitrile production unit right away and expects to cease production of hexamethylene diamine in mid-2024, according to information from INVISTA.
HMDA is the precursor for HDI.
Approximately 240 of the site’s 300 roles will be eliminated by the end of 2024. All impacted employees will be eligible for severance benefits. Throughout this transition, the company is committed to treating every employee with dignity and respect, leaders said. INVISTA’s top priority now and always is the safety of employees, contractors and the surrounding community.
“Ultimately, this decision was made to position our business to more competitively serve the long-term needs of our customers,” Murphy said.
Read more at: https://www.orangeleader.com/2023/10/05/invista-decision-to-close-orange-facility-catches-many-by-surprise/
 Everchem Updates Archive
 Sign Up for Email Updates