Company News
August 8, 2023
Klaussner to Close
Klaussner Home Furnishings closes
August 7, 2023 | 5:17 pm CDT
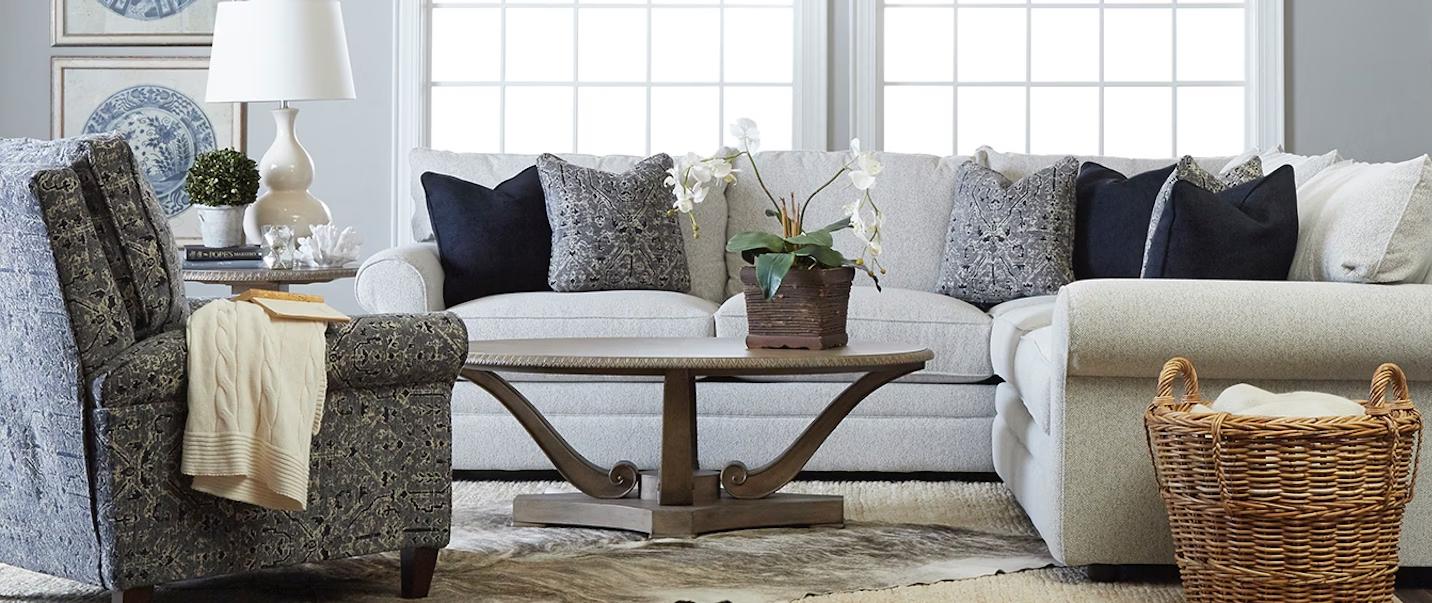
Photo By Klaussner Furniture website
ASHEBORO, N.C. – Klaussner Home Furnishings is shuttering its operations effective immediately.
The residential furniture company manufactured more than 70 percent of its products domestically through its five manufacturing campuses in North Carolina, including at its Asheboro headquarters. Klaussner was ranked #36 on the FDMC 300, a listing of the largest North American wood products producers, with estimated sales of more than $300 million in 2022.
A statement posted on Klaussner’s website reads in part:
“As the result of challenging and unexpected business circumstances impacting our operations, Klaussner Furniture Industries, Inc. and its direct and indirect subsidiaries (“Klaussner” or the “Company”) must unexpectedly wind down the operations.
“Klaussner’s lending source has unexpectedly refused to continue to fund the Company’s operations. This outcome was not reasonably foreseeable, but due to these unexpected circumstances, Klaussner can no longer sustain its operations. As a result, Klaussner has made the difficult decision to permanently cease operations and is providing as much notice as possible.
“Klaussner anticipates closing all of its facilities entirely, and that process is underway as of today, August 7, 2023.
Klaussner is working to provide information and resources to assist with next steps for displaced employees as it becomes available. This information will be communicated directly to employees via the contact information we have on file.”
Founded in 1963, Klaussner Home Furnishings has been a leading provider of residential furniture, including upholstery, motion, sleepers, bedroom, dining occasional and accent furniture. Its licensed lifestyle collections included Trisha Yearwood Home Collection and Stacey Garcia Home. It is also affiliated with Prestige Fabricators Inc., a foam manufacturing company based in Asheboro.
https://www.woodworkingnetwork.com/management/fdmc-300/klaussner-home-furnishings-closes
August 7, 2023
The Fine Print
Privacy Storm Brewing As Zoom’s Updated Terms Greenlight AI Model Training With User Data
by Tyler Durden
Monday, Aug 07, 2023 – 12:25 PM
Zoom has added a clause to its Terms-of-Service (TOS) which allows the video conferencing company to use customer-generated content for any purpose they see fit, including to train artificial intelligence (AI) models, with no opt-out.
Zoom’s TOS, last revised on July 26th, conceals a concerning caveat. Nestled within section 10.4, for those brave enough to venture, is language that confers upon Zoom a carte blanche right to exploit what it coins as “Service Generated Data” (SGD). This expansive designation encompasses a cornucopia of user-generated information – from innocuous telemetry data to incisive diagnostic insights – all grist for the AI mill.
Section 10.4 also describes the company’s use of Customer Content (defined as “data, content, files, documents, or other materials”), not just telemetry data and the like, which it can use “for the purpose of product and service development, marketing, analytics, quality assurance, machine learning, artificial intelligence, training, testing, improvement of the Services, Software, or Zoom’s other products, services, and software, or any combination thereof.”
The company makes clear that it will be using data for, among other things, fine-tuning AI models and algorithms. The potential consequences are manifold, raising red flags for privacy pundits and sparking debates over the boundaries of user consent.
Zoom’s data net is cast even wider with a perpetual, worldwide, non-exclusive, royalty-free, sublicensable, and transferable license. This legal carte blanche emboldens Zoom to undertake a multitude of actions that span the entire data lifecycle. From reconstituting, republishing, and accessing user content to the deep recesses of data modification, redistribution, and algorithmic processing, the breadth of Zoom’s dominion over user-generated data now defies conventional comprehension.
Zoom contends that these data maneuvers are vital to service provision, bolstering software quality, and enhancing the broader Zoom ecosystem. The augmentation of AI capabilities, epitomized by Zoom IQ, has been touted as a beacon of collaboration, promising efficient meeting summaries, task automation, and optimized follow-ups, all enabled by the seamless integration of user data.
“With the introduction of these new capabilities in Zoom IQ, an incredible generative AI assistant, teams can further enhance their productivity for everyday tasks, freeing up more time for creative work and expanding collaboration,” said Zoom chief product officer, Smita Hashim. “There is no one-size-fits-all approach to large language models, and with Zoom’s federated approach to AI, we are able to bring powerful capabilities to our customers and users through Zoom’s own models as well as our partners’ models.”
In 2021, Zoom agreed to settle a class-action privacy lawsuit for $86 million, after plaintiffs accused the company of violating the privacy of millions of users by sharing personal data with Facebook, LinkedIn and Google.
The controversial section of the TOS reads (emphasis ours):
Customer License Grant. You agree to grant and hereby grant Zoom a perpetual, worldwide, non-exclusive, royalty-free, sublicensable, and transferable license and all other rights required or necessary to redistribute, publish, import, access, use, store, transmit, review, disclose, preserve, extract, modify, reproduce, share, use, display, copy, distribute, translate, transcribe, create derivative works, and process Customer Content and to perform all acts with respect to the Customer Content: (i) as may be necessary for Zoom to provide the Services to you, including to support the Services; (ii) for the purpose of product and service development, marketing, analytics, quality assurance, machine learning, artificial intelligence, training, testing, improvement of the Services, Software, or Zoom’s other products, services, and software, or any combination thereof; and (iii) for any other purpose relating to any use or other act permitted in accordance with Section 10.3. If you have any Proprietary Rights in or to Service Generated Data or Aggregated Anonymous Data, you hereby grant Zoom a perpetual, irrevocable, worldwide, non-exclusive, royalty-free, sublicensable, and transferable license and all other rights required or necessary to enable Zoom to exercise its rights pertaining to Service Generated Data and Aggregated Anonymous Data, as the case
August 6, 2023
LTL Price Hikes Ahead
Yellow shutdown likely means LTL price increases, analysts say
The low-cost carrier’s rivals see an opportunity to bring in loads at higher rates as bankruptcy looms.
Published Aug. 4, 2023
David TaubeAssociate Editor

Yellow Corp.’s shutdown has left shippers without a major player in the less-than-truckload space — a development that means higher costs are likely in store, according to trucking industry analysts.
“There’s probably going to be an increase in the pricing charged to the shipper,” said Craig Decker, who leads investment banking activities across supply chain, logistics and transportation areas at Brown Gibbons Lang & Co.
The price difference could be a 20% to 25% price per pound increase depending on the circumstances, DAT Chief of Analytics Ken Adamo suggested on a weekly market update show. All together, he said the price increases could be 7% to 10% higher.
“[If] you decided late last week to send ArcBest, Old Dominion, XPO and FedEx Freight your data to get some rates back, probably by late this week you’re going to be fully processing the sticker shock of how much of a price increase you’re going to have to take over what Yellow was charging you,” Adamo said.
XPO executives noted Friday on a Q2 earnings call that Yellow’s shuttering is disrupting the market and accelerating their pricing. ““Our customers understand: When you take 10% of capacity out of the market, it’s going to cost more to move freight,” incoming CFO Kyle Wismans said.
The increase to rates comes as a result of Yellow’s role in the trucking market: Shippers who relied on the low-cost carrier are likely left with higher-priced alternatives, analysts said.
“As one of the US’ most cost-effective LTL transport companies, businesses switching from Yellow to a more expensive rival carrier will experience a twofold cost increase,” Charles Haverfield, CEO of U.S. Packaging & Wrapping, said in emailed comments.
Haverfield said this is particularly true if shippers have not built relationships with other carriers to secure discounted prices or if they switch to smaller trucking companies that cannot leverage Yellow’s economies of scale to lower prices for their services.
“The best approach is for businesses to adopt a comprehensive approach, encompassing both major carriers and smaller freight companies,” Haverfield said.
Shippers had been diverting freight to other carriers, brokers and the spot market even before Yellow confirmed it was shutting down terminal operations and laying off workers.
August 3, 2023
Foamation Has Been Sold
Green Bay Packers Acquires Foamation, Maker of PU foam Cheesehead Hats

The Green Bay Packers announced today the organization has acquired Foamation Inc., the company responsible for creating the original Cheesehead® hat, along with a wide variety of specialty foam products.
Foamation, based in Milwaukee, was founded by Ralph Bruno in 1987. Bruno first wore the Cheesehead hat to a Brewers game, after having the idea for the unique headwear while reupholstering his mother’s couch and seeking an opportunity to poke fun at the sports fans south of Wisconsin. He burned holes in the foam to give it a Swiss cheese-like appearance and painted it yellow to look like cheddar.
The one-of-a-kind hat turned out to be big hit while Bruno was tailgating before the game, and a new tradition began; the Cheesehead has since become a universally recognized symbol for Wisconsinites and Packers fans.
After more than 30 years of growing Foamation, which offered the hats and a variety of other specialty cheese-like foam products, the Brunos were ready to shift gears. Since the Packers were already the largest purchaser of their products – in order to keep them stocked in the Packers Pro Shop – the couple approached the team to determine the next steps for Foamation.
With an already beloved, iconic brand like the Cheesehead, the Packers were excited about the opportunity to continue growing the brand.
“The popular Cheesehead hats have come to represent Packers fans all over the world and we’re excited to officially welcome this special brand to the Packers organization,” said Packers vice president of marketing and fan engagement Gabrielle Dow. “We’re looking forward to building upon the legacy the Bruno family has created over the years and offering our fans even more Cheesehead items to love.”
The Packers have sold Foamation’s products in the Packers Pro Shop for several years. All Cheesehead hats and related foam products will continue to be manufactured in Wisconsin.
“After many years of working with family and friends to build the Cheesehead brand, we are pleased to pass it on to the Green Bay Packers,” said Ralph Bruno. “We have had a very special relationship with the Packers over the years, and my wife, Sue, and I are both very excited about what the Packers can do with the Cheesehead going forward.”
A variety of Cheesehead products are currently available in the Packers Pro Shop in-store and online at packersproshop.com, and the team is exploring several opportunities to grow the brand and create new products for fans to enjoy this coming season.
https://www.bizjournals.com/milwaukee/news/2023/07/24/green-bay-packers-acquire-cheesehead-maker.html
August 3, 2023
Urethane Highlights from Covestro Investors Call
Covestro AG (CVVTF) Q2 2023 Earnings Call Transcript
Aug. 01, 2023 3:32 PM ETCovestro AG (CVVTF), COVTY

139.22K Followers
Covestro AG (OTCPK:CVVTF) Q2 2023 Earnings Conference Call August 1, 2023 9:00 AM ET
Company Participants
Ronald Koehler – Head of IR
Markus Steilemann – CEO
Thomas Toepfer – CFO
Markus Steilemann
Hello and a warm welcome also from my side to the results of our second quarter call. We are still operating in a challenging environment characterized by weak demand, de-stocking and industry wide price pressure. Consequently, our sales were significantly down year-on-year to €3.7 billion. In line with our guidance we achieved a second quarter EBITDA of €385 million. Free operating cash flows strongly improved year-on-year and was minus €10 million only slightly negative in a seasonal weak quarter. This was supported by a rigorous working capital management.
For full year 2023 we confirmed our guidance for all KPIs, however, we now expect to be rather at the lower half of the guidance ranges. Finally, we continued our 500 million share buyback program and brought back 1.2 million shares during the quarter.
On the next page, we’re coming now to the business and the volume development in the second quarter of 2023. Year-on-year, the global sales volumes decreased by 8%. This was caused by on-going demand weakness across all regions and limitations in our internal availability. Looking across the industries, we see quite a mixed development with auto and electro on a growth path, but furniture and construction with declining volumes.
Europe is continuing to be the weakest region with significant decreases in almost all industries important to Covestro, except automotive, where we had a slight increase. Part of the volume weakness was still caused by the known production limitations and chlorine in Germany. The gradual ramp-up of the production during the second quarter has been on schedule and we expect this to continue throughout the third quarter, resulting in a return to full output in the fourth quarter of 2023.
Sales volumes in North America also declined across most industries. Construction witnessed a significant decline, whereas electro and furniture were only slightly down. And in line with the global trend, auto transportation improved slightly. Against the overall declining trend in the other regions, Asia-Pacific showed a positive volume development. This was driven by a low comparison basis as we suffered from the COVID lockdowns last year. Compared to this low basis, electro, automotive and furniture achieved significant growth. However, despite the weak basis, construction still slightly declined.
With that summary of the demand development, I’m now handing over to Thomas, who will guide you through the financials.
Markus Steilemann
Thank you, Thomas. Now we’re coming on the next page to the outlook for Covestro’s core industries. Since beginning of the year, the outlook of the global GDP has slightly improved from 1.5% to now 2.4%. Although the message sent from this is positive, our core industries are not the beneficiary of this development.
After the end of the COVID pandemic, the service sector is more than proportionately benefiting from the regained freedom of travel and socializing, thus driving this GDP growth. Most of the producing sector remains stuck in the on-going demand weakness and destocking trend. It’s important to Covestro, we see that only automotive is expecting a further improved demand raised to 6% now.
The expectation for the construction industry has deteriorated and even turned negative. The reason for these trends are the high interest rates, higher cost for building materials and on-going destocking. The furniture industry is seeing a very similar trend with now an expected second year of declining markets. The demand expectations for electro were also adjusted downwards to almost no growth.
With this disappointing development of our core industries, let us now turn to the Covestro outlook for the third quarter and the full year 2023. On Page 15, you see as explained in the outlook for our core industries that we currently see the potential risk of a further deteriorating economic environment and on-going demand weakness for the remainder of the year.
Therefore, we currently expect our EBITDA to come out at the lower half of our guidance of €1.1 billion to €1.6 billion for the full year 2023. We expect now volumes to decrease mid-single digit percent year-on-year for the full year 2023. However, the second half of 2023 will result in higher available capacities from resolving our production limitations towards the first quarter 2023.
This should allow us to continue a slight quarter-over-quarter volume growth in 2023. The current mark-to-market calculation comes out at about €1.2 billion based on July margins flat forward. This is in line with the midpoint of the lower half of our EBITDA guidance. We are confirming the mid-cycle EBITDA level of €2.8 billion in 2024.
We are confident that we can achieve such an EBITDA level in a normal economic environment. The most important element of bridging the gap would be a high utilization rate of our plants.
Without further investments, we could grow our volumes by more than 20%. Even on today’s depressed product margins, this would translate into an additional EBITDA contribution of more than €1 billion.
Thomas Swoboda
Yes, good afternoon everybody. I will risk two questions, please. Firstly, on your guidance for Q3, it seems that you were pointing to a more negative pricing delta in Q3. Could you discuss where you see pricing pressure in particular on product, product and regional level, if possible.
My second question is — and I will risk asking on the current situation, but I will ask it indirectly. In terms of your of your long — mid to long-term growth ambitions do you currently face any limitations in terms of backward integration financing capabilities? Or how can I put it, being very being very exposed to the capital market that are limiting your growth vice versa, if you would have limited resources and would be shaded from the public a little bit more, would you be able to grow much, much faster than you would be — then you are able to grow currently in the mid to long-term. Thank you.
Thomas Toepfer
So Thomas, let me maybe take the first question with respect to the guidance in Q3 and also what that means with respect to the pricing delta. So first of all, I would confirm that for Q3, we’re expecting a negative pricing delta. If you look at it from a quarter-over-quarter perspective, so that could be somewhere in the region between €150 million to €200 million negative. If you look at it from a year-over-year perspective, I’d say it’s almost neutral.
So what is it that we’re seeing quarter-over-quarter is mainly a weakness in TDI, mainly in Europe, but also to some extent in other regions. The polio weakness will continue and there might be a little bit more downside in PCS commodities, while MDI, we rather would assume that it is flattish. So it’s a mix mainly coming from our quality businesses where as I said sequentially, we would see that there is a negative pricing delta, as you correctly said. However, again, year-over-year, it’s almost neutral.
Markus Steilemann
Thomas, this is Markus speaking. Thanks for your question and coming to the second question that you have asked. Covestro has a very clear strategy. It’s well positioned in the key regions. That means North America, Europe as well as Asia Pacific. And we have access to very competitive and sufficient and reliable raw materials, be it on smaller raw materials or strategic raw materials for our business.
And in that context, with regard to the limitations that you indicated also on growth, we do not see neither by the way how we are financed or let’s say, well, by the respective resources limitations on our growth opportunities.
Jaideep Pandya
And then the third question, I’m sorry to ask you this very directly now. But I mean what is your different strategy given that finally, somebody is knocking on your door little loudly. So if this is real, how are you defending this? Or are you just using the famous words, no comment and not talking. So can you please confirm what is official version from Covestro on ADNOC? And how are you defending it if it is real? Thanks.
Markus Steilemann
So that’s for your second question. And on the third question, I have to say that Covestro does not comment on rumors and that this is a general policy. And so I also, in this case, please bear with me if I say that Covestro does not comment on respective market rules.
Jaideep Pandya
Sorry to just – apologies for this but. So you’re basically saying you can even say, if you’ve got an offer or not, this is all market rumor. Is that how we should understand this comment?
Markus Steilemann
You should understand the comment as it says, Covestro does not comment on rumors.
Geoffery Haire
Hi, thank you for letting me ask a question. So I apologize in advance for the question. Leaving aside any potential bidder for Covestro and price. What does the Supervisory Board and the Management Board look for when it comes to a potential suitor?
Markus Steilemann
Well let me be very clear on that point. We are at any given time committed to all stakeholders. So we are at any given point in time looking at all options that make sense. And therefore, let me also hear rest assured the Board of management is fully aware of its fiduciary duties. And in this context, aligns any of its decision solidly with the interest of its shareholders and the shareholders. So this principle is embedded in and also secured by a regular exchange with the Supervisory Board. I hope that gives you some clarity around your questions.
Geoffery Haire
Okay, thank you. And thanks Thomas for all your help over the years.
Jaideep Pandya
Yes, thanks a lot. The question really is just around your asset network, specifically in Europe. I mean Markus, you mentioned about the 20% volume uplift, but it sort of looks like we might be in a cycle where that is a bit far away. So — and then if I look at the Chinese plants that are coming up, the nameplate capacity is at par with yours or even higher than yours.
So in that context, does Europe need to shut down maybe 15%, 20% of polyurethane capacity to actually balance and have a situation where you just don’t get swamped from imports? Or can you actually survive a benign demand environment in Europe and still maintain profitability or breakeven or above breakeven? Just want to understand what is your European profitability today? And if volumes don’t improve, where do we go? Thanks.
Markus Steilemann
Yes. Jaideep, thanks for your follow-up question. And on spot so to say, I would say, because for sure, we also having all those questions in mind. But let me elaborate a little bit of that. I don’t know whether you call — recall the year 2015. In 2015, we had also quite significantly underutilized European assets, and we made it in about a year. Those assets were filled. Then if you look at today’s situation and the industry cost curves, we are in almost every product, in every let’s say, plant that — where we produce that the cost leader and where we haven’t been the cost leader, we invested in the plants, for example, Tarragona, Spain into chlorine production, which now puts this asset from our perspective into the cost-leading position in Europe. Then it also has been mentioned, I think by Thomas a little bit earlier, the closure of the TDI/BSF plant held, as already said. And in that context the imports that we are currently seeing is mainly coming from high-cost producers, which have assets outside of Europe and try to import Asia Pacific to supply their customers with their own demand.
So in general terms, I see that MDI demand should accelerate because the MDI demand is driven by energy-efficient buildings, as you know. And we think next to the fact that there is a construction industry decline refurbishment of existing buildings will get more and more important to get to the carbon dioxide emission reduction targets that the European Union has. And that’s why there will be sufficient and additional demand for MDI returning plus that assets are the ones that are leased underutilized. That means the assets that should be first, if I may say so, back into the positives is definitely MDI then followed by TDI, once again, BSF closure helps and then the polycarbonates, but here only the standard polycarbonates, whereas we have more or less now 4/5 of our external sales in the non-standard polycarbonates, so they’re highly blended grades for special applications.
So long story short, it’s about cost leadership in Europe. It is about that we see opportunities that demand will come back in industries where it counts and that at current energy price levels with a leading cost position, we also feel comfortable and competitive against attempts to import material from outside Europe. So all in all, you could only look at the negative side. But as an individual company, we feel very well positioned to also master this challenge and also return back may I call it to enjoyable margin levels. Currently, we deliver positive results, but they’re definitely not at an enjoyable level. Let me put it that way.
Thomas Toepfer
Well, thank you very much, Carston [Ph]. I just wanted to steal two minutes of your time for thanking, first of all, Markus, thank you very much for your kind words. I can only say it was always a pleasure and a real privilege to be part of the Covestro team. I think it’s an absolutely fascinating and great company, and I really felt privileged to be part of it over the last 5 years.
And secondly, I would like to thank everybody on the call for – for the many discussions that we had over the last 5 years for following Covestro through some ups and downs and for challenging us with your questions. It was also always a real pleasure to be in touch with you.
And I’m really looking forward to at least meet some of you again in the future. Again, let me conclude by saying I’m really very attached to Covestro and it’s also, to some degree, with a heavy heart that I’m leaving. But of course, it’s a little bit of a personal decision because it will be — because it will bring me back to Hamburg, which is my home city. And therefore, it’s kind of a homecoming for the family. So with that, Carston, back to you and — or back to Ronald, I think to conclude the call, and I wish everybody a nice summer holiday.
 Everchem Updates Archive
 Sign Up for Email Updates