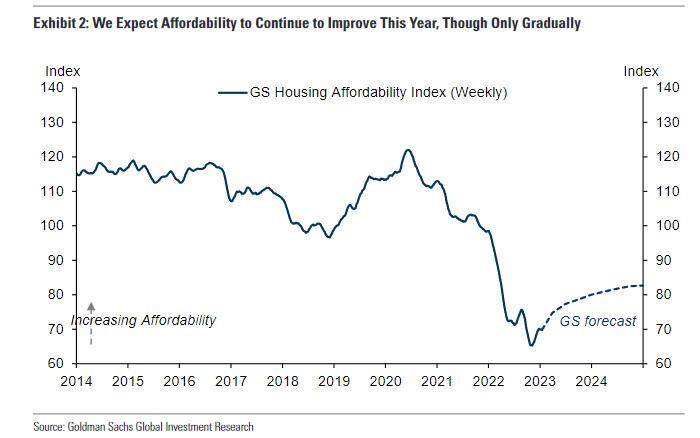
Has The Housing Market Bottomed? The Surprising Result From A Little-Known Market Indicator
by Tyler Durden
Monday, Jan 30, 2023 – 03:20 PM
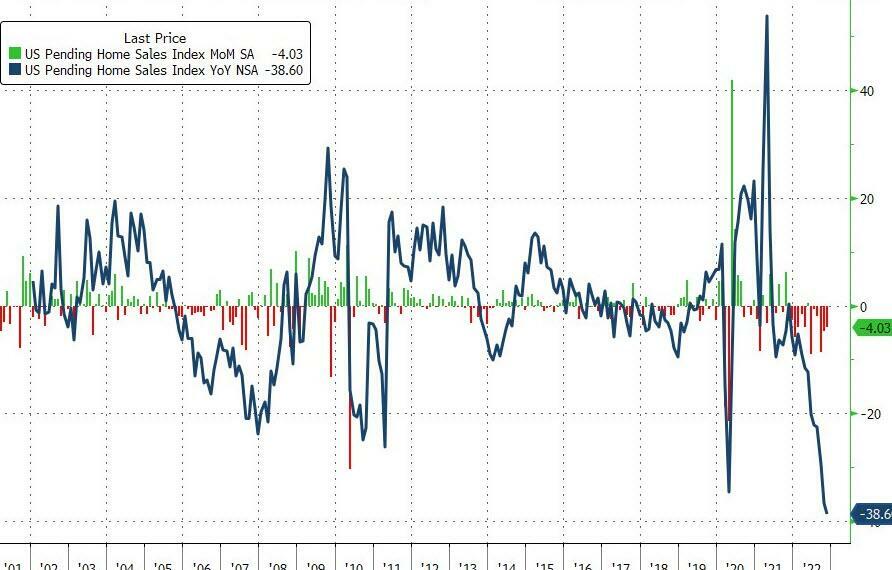
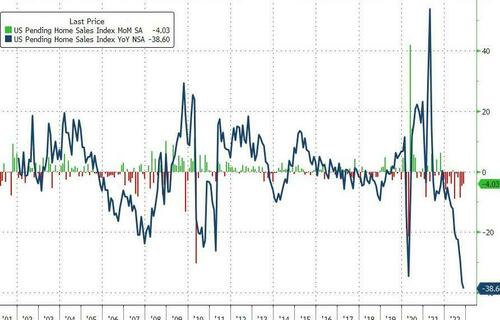
It may come as a bit of a shock to those who have been following the creeping freeze in housing transactions as the bid-ask spread grows to monstrous proportions, leading to a record crash in pending home sales…
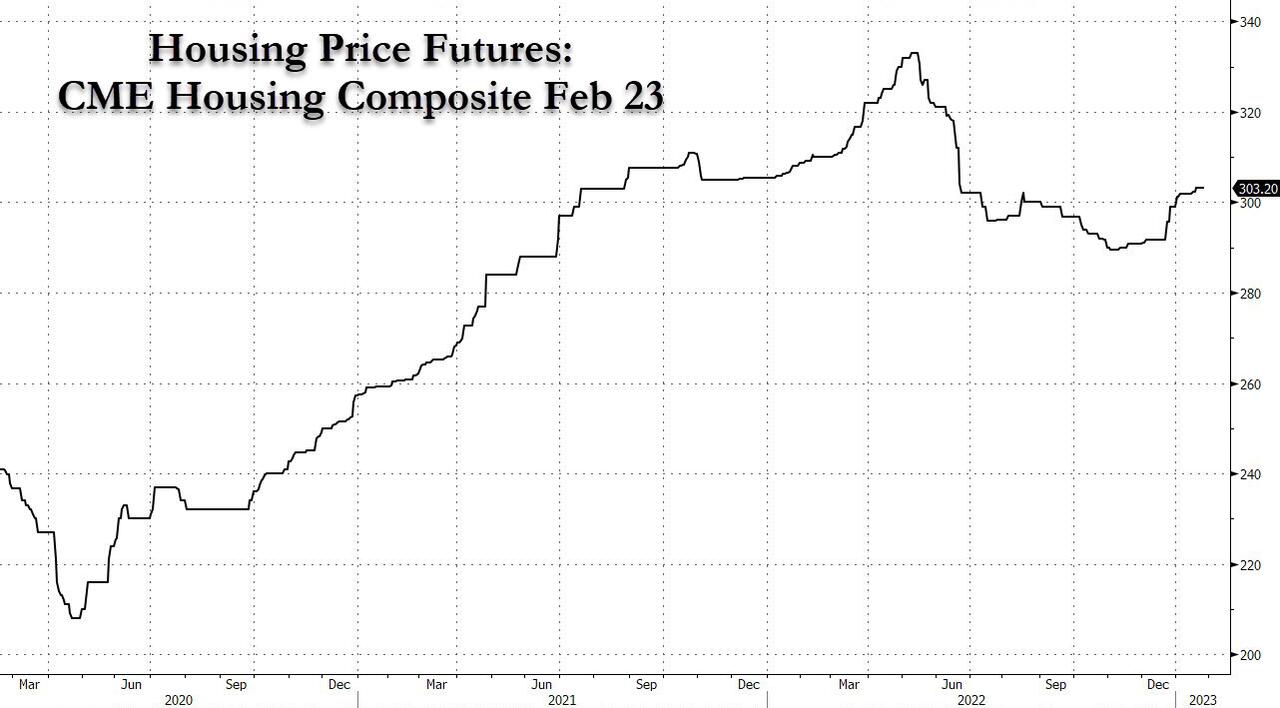
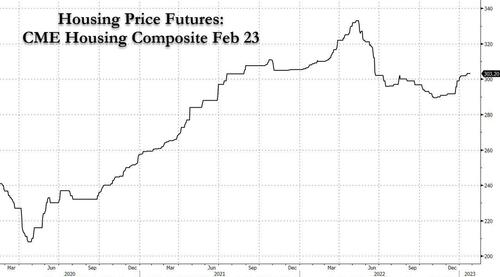
… but even though mortgage rates ticked higher back to 6% in January, there is growing speculation that the housing market has bottomed. Why? Because as Goldman’s Rich Provorotsky notes, “bet you didn’t know there were housing price futures…they bottomed in Q4 and have been rallying.” Indeed, the Housing Composite Index traded on the CME is up decidedly in the past month after hitting a 16 month low in November.
Why this surprising bounce? A big reason for the unexpected rebound may be a recent report from real estate company Redfin which last Wednesday reported that “the housing market has begun to recover from a trough in the second week of November with buyers returning at a faster pace than sellers. The number of Redfin customers asking for first tours has improved by 17 percentage points from the November low, and the number of clients contacting.”
Furthermore, according to the report, Redfin agents to begin the home-buying process has improved by 13 points: “I’ve seen more homes go under contract this month than in the entire fourth quarter,” Angela Langone, a San Jose, California, agent, said in the report.
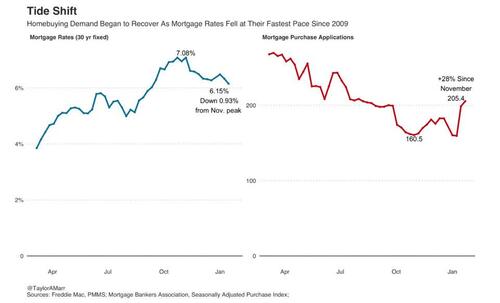
Among notable market moves, Redfin points to mortgage applications which are up 28% from early November as the average 30-year-fixed mortgage rate has dropped to 6.15% from its peak of 7.08% in November, the biggest decline since 2009. Pending home sales rose 3% in December from November.
Preliminary data on the share of Redfin agents’ offers facing bidding wars points to small upticks in the Seattle and Tampa markets this month (however, since this is an uneven trend, expect it to take some time before bidding wars nationally show an upward trend).
“Bidding wars are back in Seattle,” said local Redfin real estate agent Shoshana Godwin. “One of our Issaquah listings got 12 offers and is under contract for $155,000 over the $1.4 million list price. The buyer waived every contingency, handed over $300,000 of earnest money and is letting the seller stay for free for two months after closing. Another home in Seattle’s popular Ballard neighborhood was recently delisted after sitting on the market for over three months. The seller relisted it last week and it went pending in under a day.”
Eric Auciello, Redfin’s team manager in Tampa, has seen three modest single-family homes priced around $300,000 wind up in bidding wars in central Florida this month, with 16, 17 and 23 competing offers, respectively.
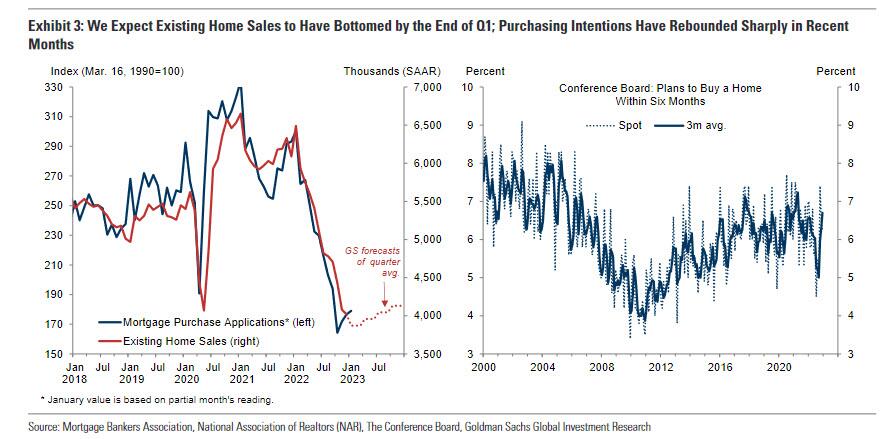
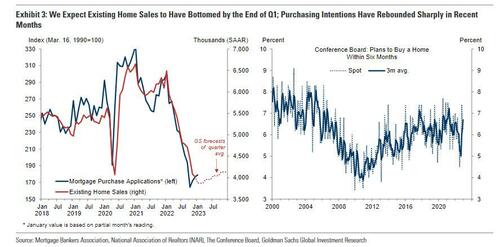
But while one can accuse Redfin of bias – after all the company recently laid off some 13% of its employees due to the housing market collapse so it is certainly interested in sparking some animal spirits in the sector – it is not alone in predicting a housing recovery. One week ago, Goldman’s Jan Hatzius published the bank’s Housing Outlook for 2023 in which he predicted that “home sales appear set to turn higher.” That’s because “mortgage purchase applications have averaged 9% above their October trough so far in January and survey-based measures of purchasing intentions have rebounded sharply” and while Goldman expects that existing home sales could decline slightly further “but will likely bottom in Q1 (GS forecast: Q1 average of 3.85mn saar vs. 4.02mn in December) before rebounding modestly by year-end (GS forecast: Q4 average of 4.1mn).”
Here are some more observations from the Goldman note (full report available to pro subs):
We forecast that housing starts will take longer to stabilize, declining to a trough pace of 1¼mn in 2023Q4 (vs. 1.4mn in 2022Q4) before recovering next year. We expect completions to total 1½mn this year, the most since 2007, which will help to clear the backlog of homes under construction and contribute to a modest increase in the homeowner vacancy rate (GS forecast of 1.2% in 2023Q4 vs. 0.9% now and 1.4% in 2019Q4).
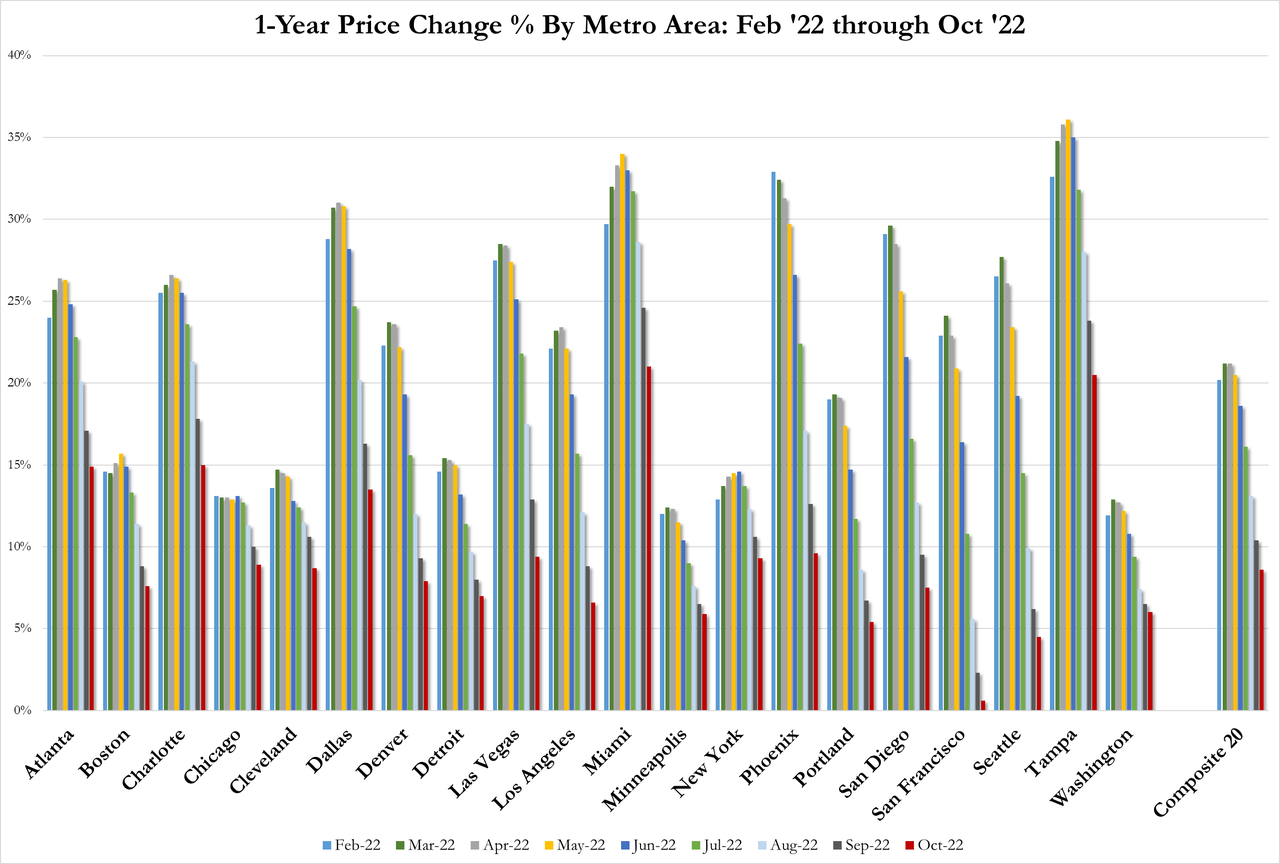
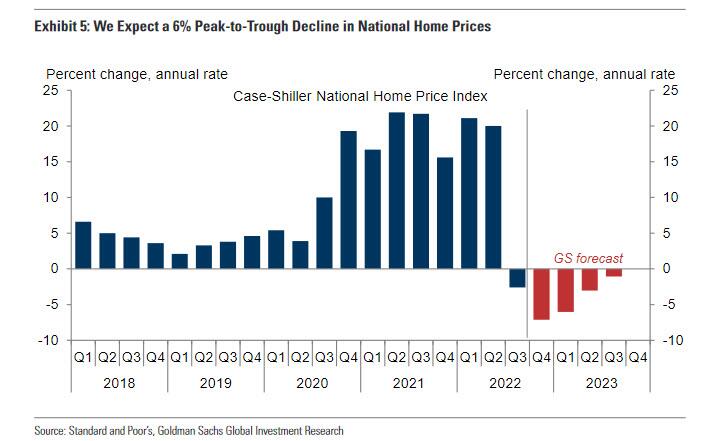
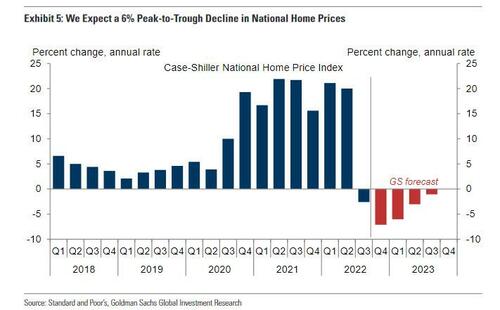
We expect a peak-to-trough decline in national home prices of roughly 6% and for prices to stop declining around mid-year.
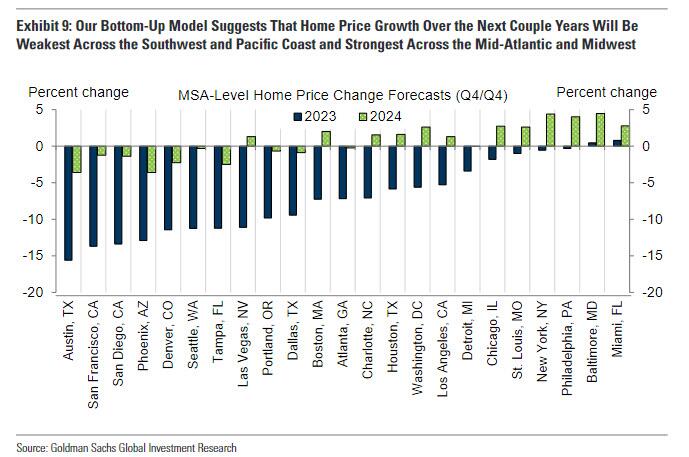
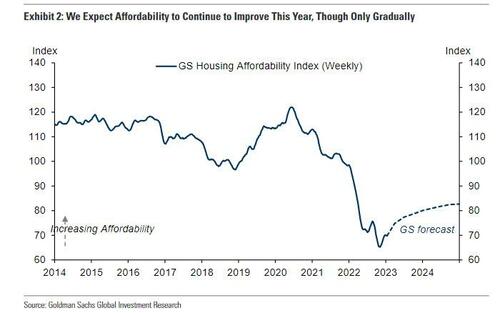
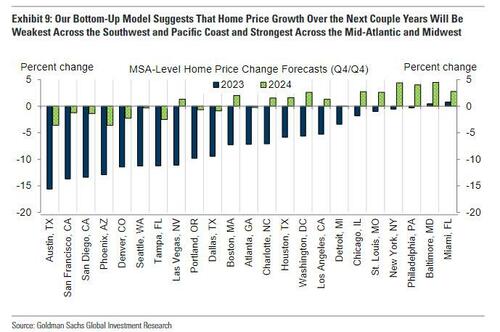
On a regional basis, we project larger declines across the Pacific Coast and Southwest regions—which have seen the largest increases in inventory on average—and more modest declines across the Mid-Atlantic and Midwest—which have maintained greater affordability over the past couple years.
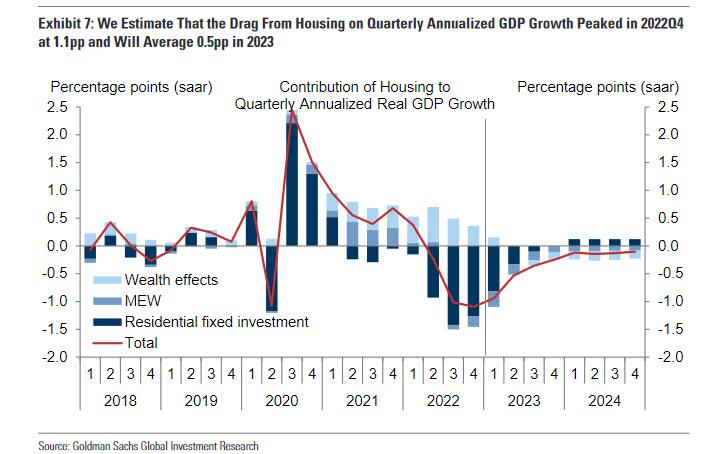
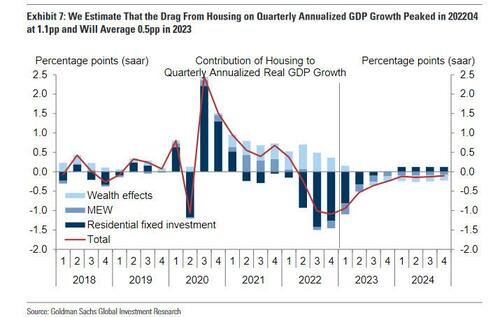
Higher rates and lower home prices will increase the drag on GDP growth from negative wealth effects and declining mortgage equity withdrawal, but we believe that the aggregate drag on GDP growth from the housing sector peaked in 2022Q4 at 1.1pp and will moderate to just 0.25pp by 2023Q4.
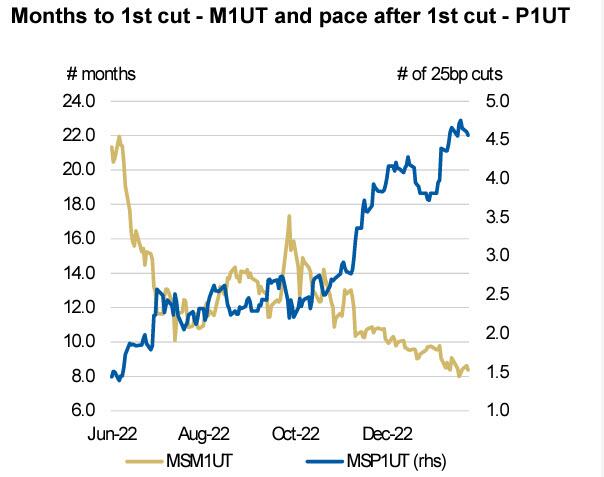
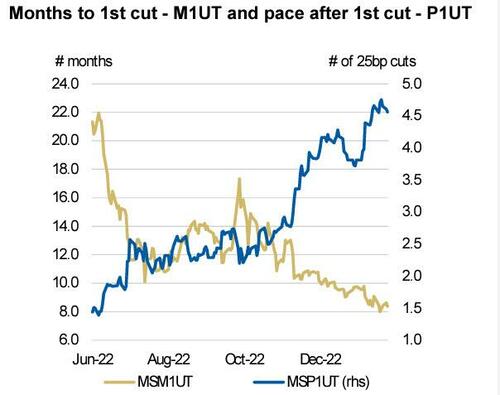
If the housing price futures market – and Goldman – is right in pricing in a housing trough than the consequences could confound markets: on one hand, a stabilization in housing will likely make any coming recession less severe; on the other, since housing is the primary channel by which the Fed can slowdown the economy, any failure to cripple this key US asset, could mean that Powell will be stuck in a “higher for longer” mode for, well, longer than the market expects. As a reminder, as the following Morgan Stanley chart shows, consensus is that the Fed is about 8 months away from its first rate cut, which will be promptly followed by ~4.5 25bps rate cuts.
Manufacturers accepted 57,300 trailer orders in December, the second-highest monthly total since tracking began in 1996. (Photo: Jim Allen/FreightWaves)
Trailer manufacturers posted 57,300 orders in December, the second-highest monthly intake since ACT Research began tracking in 1996. The volume appeared to be a catch-up after OEMs blocked many orders from April to August because they lacked pricing visibility.
“I cannot speak for other OEMs. However, our higher booking in December was driven by the later opening of the order books as we awaited required quoting information from the supply base,” Sean Kenney, chief sales officer for Hyundai Translead, told FreightWaves.
“Hyundai Translead is anticipating continued higher-than-normal orders for the next few months as we work through the impact of this.”
Trailer orders in December 2022 came in at the second-highest volume since ACT Research began tracking in 1996. (Chart: ACT Research)
December net U.S. trailer orders came in 46% higher compared to November and 115% above December 2021, ACT Research reported. The highest month on record was September 2018, with 57,800 net orders.
Some manufacturers report that the supply of parts has deteriorated despite their acceptance of the huge number of December orders.
Lingering supply chain concerns for future trailer orders
“Supply-chain concerns still linger,” with no short-term improvement in sight, Jennifer McNealy, ACT director of commercial vehicle market research and publications, said in a news release. “Regarding demand, most trailer makers continue to see demand exceeding capacity through the end of 2023.”
One major OEM, Wabash, announced a long-term supply agreement Jan. 10 with J.B. Hunt Transport covering up to 15,000 trailers over the next few years.
Some OEMs mentioned an erosion in confidence to ACT, but so far it is not showing up in order cancellations.
Mike Baudendistel, a FreightWaves market expert, expressed surprise at the order volume in December.
“It could be some makeup orders to compensate for the supply constraints the past couple years,” he said. “I would think the orders were even more heavily weighted toward the large enterprise carriers than they usually are since they are well capitalized and their business holds up better in a weakening market.”
Total net orders placed in 2022 were 361,500 compared to 249,400 in 2021. The industry produced approximately 306,000 trailers in 2022.
“Our projections point to a continuation of that upward trend into 2023,” McNealy said.
Did the first quarter lull come early, in November and December of 2022?
For carriers, the first quarter is always the most difficult period in the annual freight calendar, when retailers clear their excess holiday inventory, construction takes a pause for the frigid weather and everything is gloomy and cold. The soft first quarter often follows a robust fourth quarter, in which freight companies enjoy the annual peak season and make an outsized portion of their profits. Carriers look forward to spring for some market stability and potential market accelerations.
Is it possible that winter came early this year? Did the freight winter start in November and now we are experiencing an early thaw?
Early freight data and channel checks would suggest the freight market could be stabilizing and clearer skies are ahead.
Over the past week, we’ve spoken with numerous freight executives who have mentioned that the first two weeks of the first quarter are shaping up better than expected, granted, expectations were incredibly low after such a weak peak. Going into the quarter, executives we spoke with predicted a significant collapse in freight for the first quarter, with a seasoned veteran executive of a large trucking technology firm predicting that the first quarter would be the worst in his four-decade career. It was a fair bet considering how challenging the second half of the 2022 was for most in the freight market.
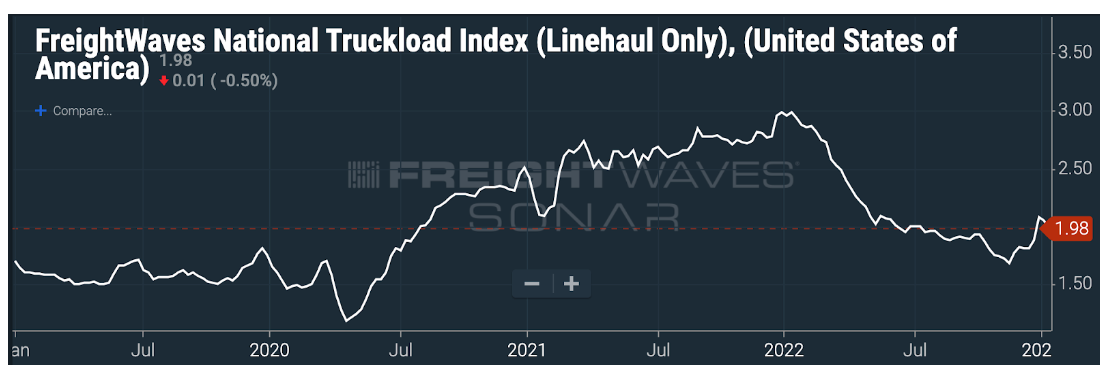
Truckload spot rates, according to the FreightWaves National Truckload Index, hit a low of $1.67 on Nov. 17, 2022, and have since bounced back to $1.98 per mile.
FreightWaves SONAR: National Truckload Index. To learn more about SONAR, click here.
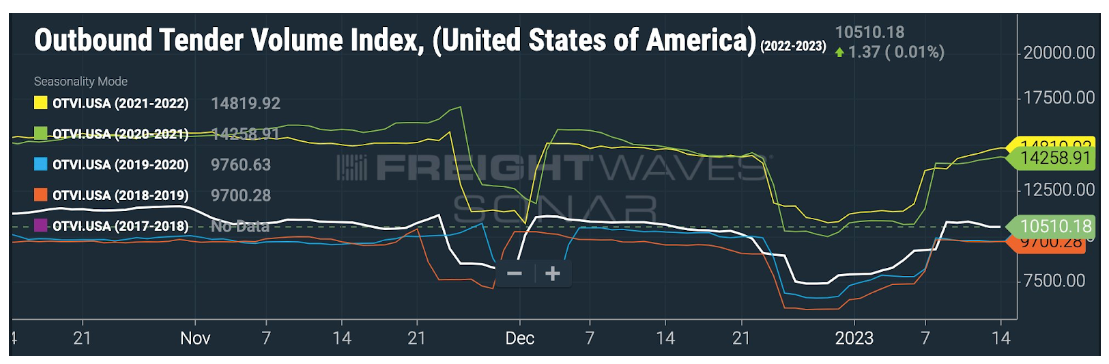
Trucking tender volumes also suggest that the direst of predictions have not played out. Tender volumes on the Outbound Tender Volume Index (OTVI), an index that tracks the volumes of load requests from shippers to carriers, show that volumes briefly dipped below 2019 and 2020 levels, but they have since broken away from this baseline.
The seasonal OTVI chart inside of SONAR tracks multiple years of truckload volume data. The white line is the current market, with previous years representing the colors in the chart key.
If the first few weeks of the new year are an early omen, then the freight market may have bottomed in the fourth quarter and carriers can look forward to a far less volatile market in 2023.
Interested in being the first to know about the changes in the global freight market so that you can prepare your business for market changes before your competitors? All of the data in this article is available via subscription to SONAR, the world’s leading high-frequency data platform.
These Are North America’s Biggest Sources Of Electricity By State And Province
by Tyler Durden
Friday, Jan 13, 2023 – 08:40 PM
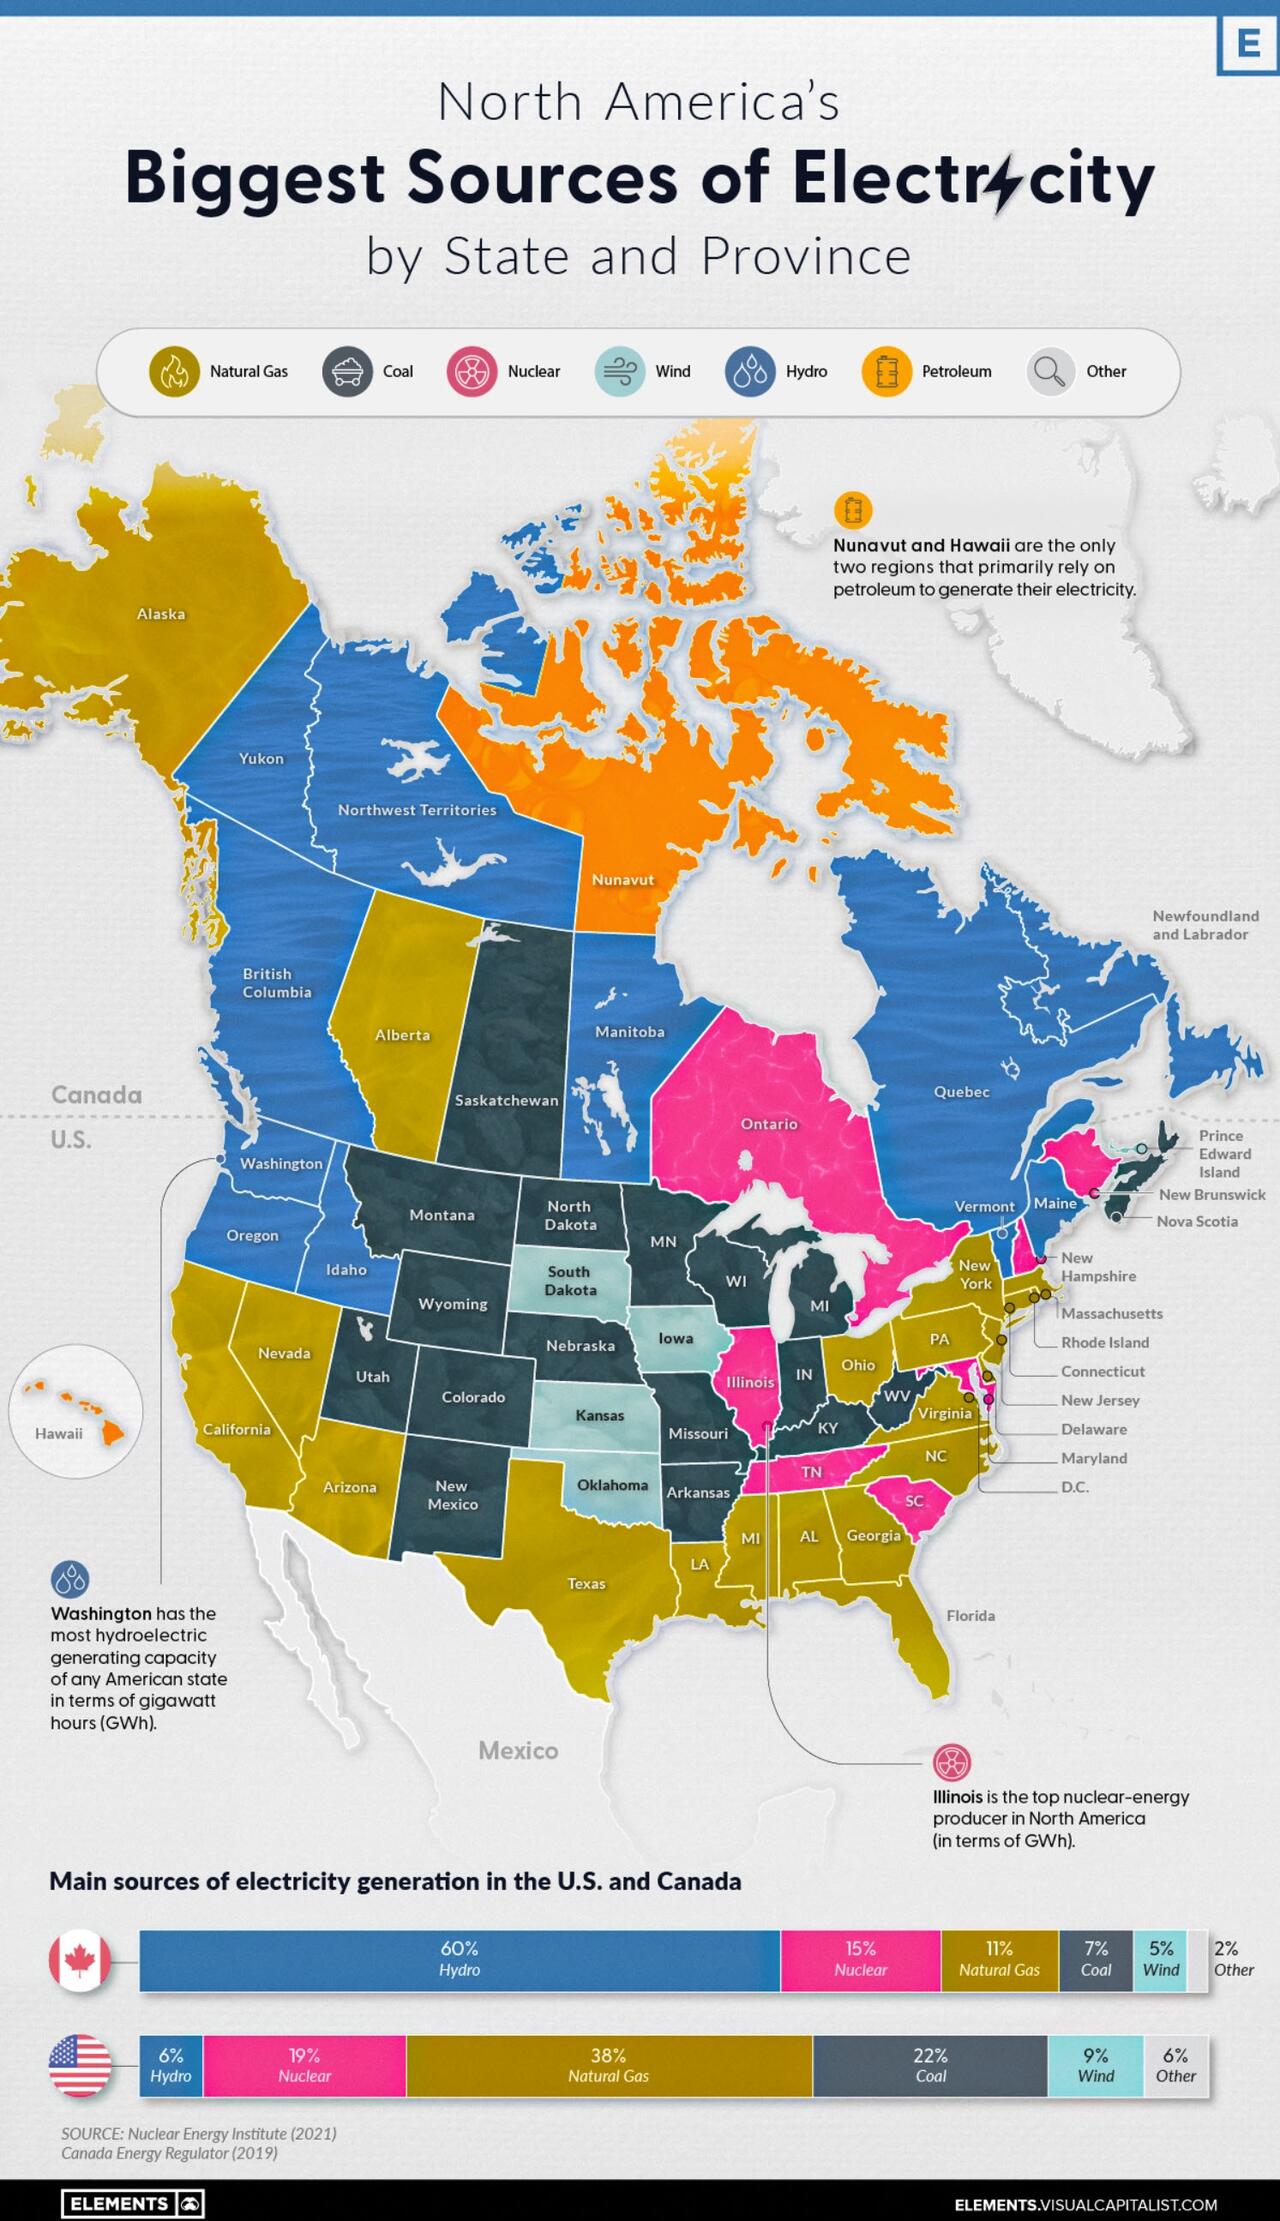
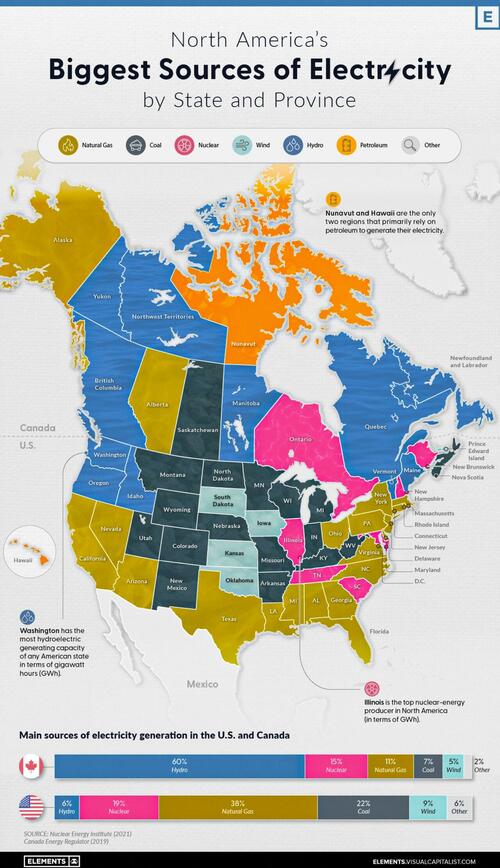
On a national scale, the United States and Canada rely on a very different makeup of sources to generate their electricity.
The U.S. primarily uses natural gas, coal, and nuclear power, while Canada relies on both hydro and nuclear. That said, when zooming in on the province or state level, individual primary electricity sources can differ greatly.
Natural gas is widely used for electricity generation in the United States. Known as a “cleaner” fossil fuel, its abundance, coupled with an established national distribution network and relatively low cost, makes it the leading electricity source in the country.
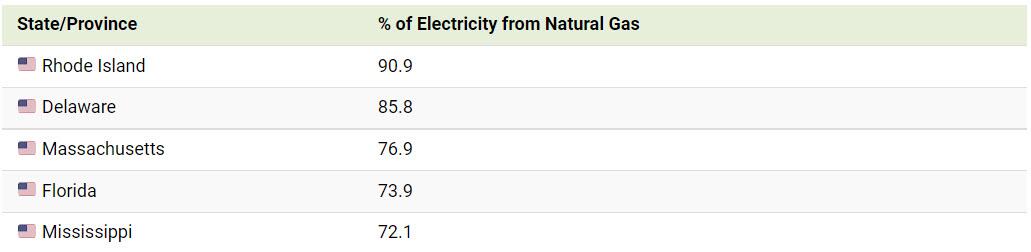
In 2021, 38% of the 4120 terawatt-hours (TWh) of electricity generated in the U.S. came from natural gas. Not surprisingly, more than 40% of American states have natural gas as their biggest electricity source.
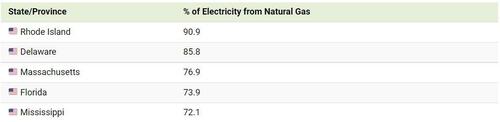
Here are some states that have the largest shares of natural gas-sourced electricity.
In Canada, natural gas is only the third-biggest electricity source (behind hydro and nuclear), accounting for 11% of the 632 TWh of electricity produced in 2019. Alberta is the only province with natural gas as its main source of electricity.
Nuclear
Nuclear power is a carbon-free energy source that makes up a considerable share of the energy generated in both the U.S. and Canada.
19% of America’s and 15% of Canada’s electricity comes from nuclear power. While the percentages are close to one another, it’s good to note that the United States generates 6 to 7 times more electricity than Canada each year, yielding a lot more nuclear power than Canada in terms of gigawatt hours (GWh) per year.
As seen in the map, many states and provinces with nuclear as their main source of electricity are concentrated in the eastern half of the two countries.
In the U.S., Illinois, Pennsylvania, and South Carolina are top producers in terms of GWh/year. Illinois and South Carolina also have nuclear as their primary electricity source, whereas Pennsylvania’s electricity production from natural gas exceeds that from nuclear.
The vast majority of Canada’s nuclear reactors (18 of 19) are in Ontario, with the 19th in New Brunswick. Both of these provinces rely on nuclear as their biggest source of electricity.
Renewables: Hydro, Wind and Solar
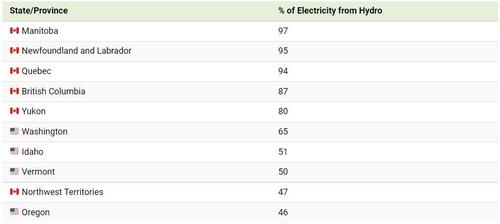
Out of the different types of renewable electricity sources, hydro is the most prevalent in North America. For example, 60% of Canada’s and 6% of the U.S.’s electricity comes from hydropower.
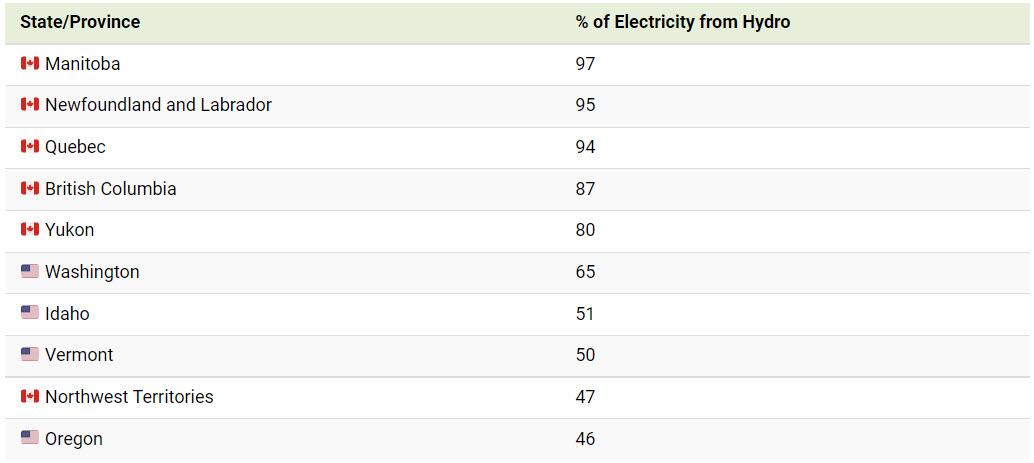
Here are the states and provinces that have hydro as their biggest source of electricity.
Wind and solar power collectively comprise a small percentage of total electricity generated in both countries. While no state or province relies on solar as its biggest source of electricity, Iowa, Kansas, Oklahoma, and South Dakota rely primarily on wind for their electricity, along with Canada’s Prince Edward Island (PEI).
Coal and Oil
Coal and oil are emission-heavy electricity sources still prevalent in North America.
Currently, 22% of America’s and 7% of Canada’s electricity comes from coal, with places such as Kentucky, Missouri, West Virginia, Saskatchewan, and Nova Scotia still relying on coal as their biggest sources of electricity.
Certain regions also use petroleum to generate their electricity. Although its use for this purpose is declining, it is still the biggest source of electricity in both Hawaii and Nunavut.
Over the next few years, it will be interesting to observe the use of these fossil fuels for electricity generation in the U.S. and Canada. Despite the differences in climate commitments between the two countries, lowering coal and oil-related emissions may be a critical part of hitting decarbonization targets in a timely manner.



 Everchem Updates Archive
 Sign Up for Email Updates