
Epoxy
April 27, 2021
Container Update
“It’s About To Get Much Worse”: Supply Chains Implode As “Price Doesn’t Even Matter Anymore”
by Tyler DurdenTuesday, Apr 27, 2021 – 02:15 PM
By Greg Miller, of FreightWaves,
The number of container ships stuck at anchor off Los Angeles and Long Beach is down to around 20 per day, from 30 a few months ago. Does this mean the capacity crunch in the trans-Pacific market is finally easing? Absolutely not, warned Nerijus Poskus, vice president of global ocean at freight forwarder Flexport. “It’s not getting better. It’s getting worse,” he told American Shipper in an interview on Monday.
“What I’m seeing is unprecedented. We are seeing a tsunami of freight,” he reported.
“For the month of May, everything on the trans-Pacific is basically sold out. We had one client who needed something loaded in May that was extremely urgent and who was ready to pay $15,000 per container. I couldn’t get it loaded — and we are a growing company that ships a lot of TEUs [twenty-foot equivalent units]. Price doesn’t always even matter anymore.”
Restocking driving volumes higher
Poskus said that trans-Pacific import volumes are still rising. He noted that January trans-Pacific imports were up 10% versus 2019 (comparisons to 2020 numbers are skewed by COVID) and 13.5% in February, then jumped 51% in March. “So, we’re now at 1.5 times pre-pandemic levels.”
With imports far outpacing retail sales growth, he attributed volumes to inventory restocking. “The restocking is actually affecting the trade even more than growth in demand. That tells me that this will last even longer. Let’s say U.S. consumer demand slows down in Q3 and Q4. That’s not expected, but even if it does, [capacity availability and rates] shouldn’t improve quickly, simply because of the huge restocking demand.”
Poskus also believes there is a growing export backlog piling up each day in Asia, awaiting available ship slots. If that backlog grows too big, he said, “I honestly don’t know what’s going to happen.” As a result of the backlog and restocking demand, he thinks “prices will remain high and shipping will probably remain difficult for the rest of this year. And then after that, you have the peak for Chinese New Year in 2022.”
About to get even worse
He said that the situation today is the worst he’s witnessed — and he believes it’s about to get even more severe.
“Buckle up. The month of May will be the worst people have ever seen,” he predicted. Because some shippers will have to wait in line behind the growing backlog in Asia, he expects “what’s going to happen soon is that some importers won’t even be able to get on the boat. For them, it will almost feel like trade is coming to a halt.”
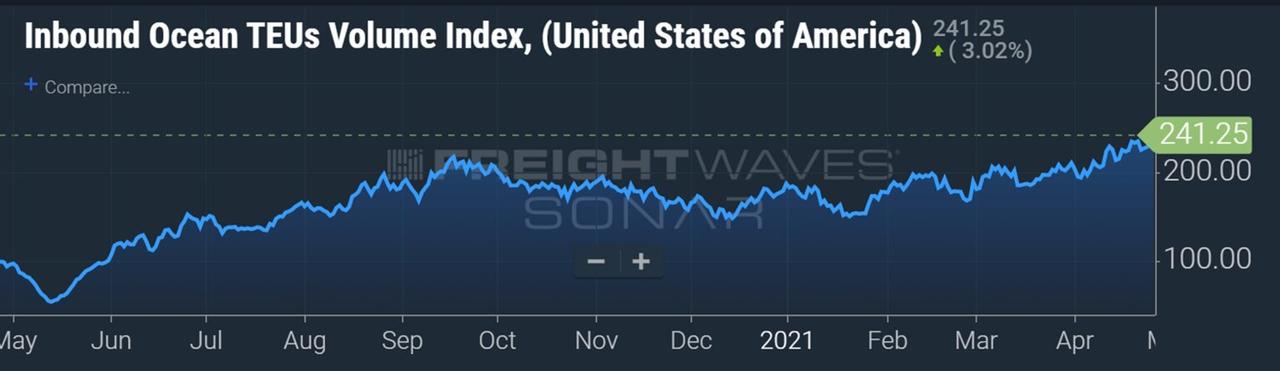
Poskus’ comments mirror cargo bookings data. FreightWaves’ SONAR platform features a proprietary index of shippers’ ocean bookings (SONAR: IOTI.USA). Bookings to the U.S. are measured in TEUs on a 10-day-moving-average basis as of the scheduled date of overseas departure. As of Monday, the index was at a new all-time high and forward bookings data showed a continued rise ahead.
Spot premiums back with vengeance
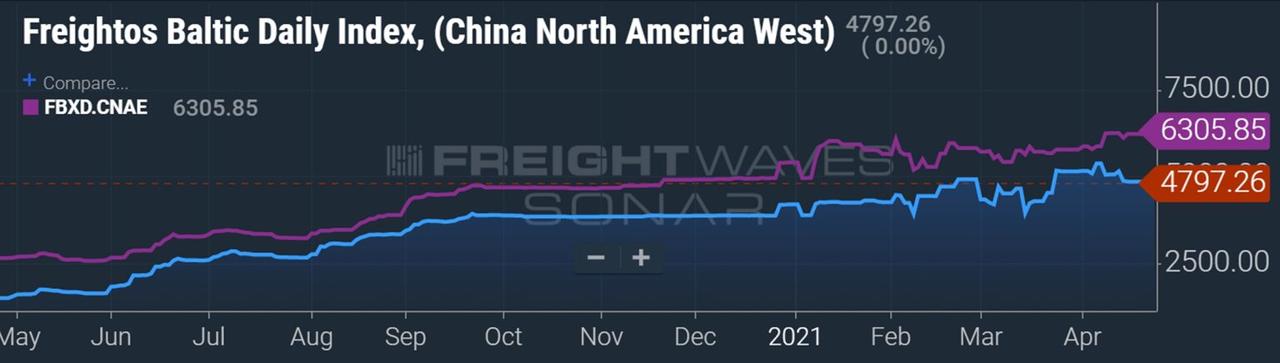
As of Friday, the Freightos Baltic Daily Index assessed the Asia-West Coast spot rate (SONAR: FBXD.CNAW) at $4,797 per forty-foot equivalent unit (FEU) and the Asia-East Coast rate (SONAR: FBXD.CNAE) at $6,306 per FEU — both near all-time highs.
But that’s only part of the rate story. “Indexes are not bills. Premiums are not reflected in the indexes,” said Poskus. Earlier this year, some of the premium charges came down as container availability in Asia improved. That’s reversed, said Poskus, who noted that the Ever Given incident in the Suez Canal pulled container equipment from the market. “Container shortages in Asia are again very bad because of the Ever Given, and it will take another four to six weeks to come back to normal.”
The added premiums to get spot cargo loaded “are back and they’re higher than before,” he said. “They are $2,000-$3,000 above FAK [spot price] and that’s the best case.”
Spot cargo that was booked 21 days prior and was forecast within the shipper’s allocation is still getting FAK pricing on spot, he noted. However, “everything last minute is basically a free-for-all auction. You are basically offering as much money as you can and hoping somebody will take it. Many importers are now struggling. We’re seeing so many new customers approaching us asking for help because they can’t get loaded.”
Contract rates up sharply
A recent presentation by Xeneta, a company that collects contract data, showed Asia-West Coast contracts being negotiated this year at around 30%-50% higher levels than last year.
Poskus’ numbers are around double Xeneta’s. “We are seeing fixed-price increases of slightly over 100% on Asia-West Coast and about 75% on Asia-East Coast,” he said. “Also, almost every single contract rate is subject to peak season surcharges [PSSs], so the prices aren’t exactly fixed. I think the PSSs will reduce the gap between the spot and fixed market.”
Asked about shippers who have yet to conclude their annual contracts, he said, “If you want a fixed price in today’s market, the answer you’ll get from the carriers is that it’s too late. We advised many importers to sign early because the trans-Pacific contract season would close [early] because there’s more demand than supply. And that’s exactly what happened.”
There are exceptions, such as larger shippers with June-to-June contracts who began discussions with carriers earlier this year. “But if you are just a simple importer and you are yet to sign your fixed contract, you will be in the spot market,” said the Flexport vice president.
Advice to importers
Poskus offered several pieces of advice to importers scrambling to get container loads to the U.S.
He noted that carriers need reefers in the U.S. market for refrigerated exports to Asia. On the way back from Asia, these reefers are powered down and can be used as non-operating reefers (NORs) to transport dry cargo. “Believe it or not, carriers are still moving some NORs empty because importers don’t like them. This is a missed opportunity to move cargo in NORs. My advice is: Take that option. If you’re searching for the best solution in this market, you’re going to see even more delays.”
He also suggested moving cargo via less-than-container-load (LCL) shipments. “LCL is still moving. Of course, you cannot move thousands of containers LCL, but if you have something urgent, you can still get space for LCL on May sailings. Instead of waiting, break your some of your shipments down into LCL shipments and at least get some inventory,” he said.
Yet another option: Be creative with routings. For example, direct China-West Coast sailings may be sold out, but cargo can be routed from China through the Panama Canal to Cartagena, Colombia, then back through the canal to the West Coast. “It has a longer transit time but it can be loaded in the same week and it’s an option versus waiting a month and a half to get loaded [for the direct route],” he said.
“Just get your cargo to the continent of North America and from there you can get it to where it needs to go, whether it’s with NORs or LCL or transshipping [through hubs like Cartagena] or shipping it to Canada and then putting it on rail to Chicago and trucking it to New York. It will be expensive, but at least it will get there.
“You have to be flexible. Look for any routing and be creative. It’s a moving target. And don’t wait. If something opens up, act fast.”
April 27, 2021
Feedstock Pricing Outlook
Americas petrochemicals outlook, w/c April 26
- Author
- Mary Hogan Staff
- Editor
- Manish Parashar
US polypropylene
US polypropylene exports are expected to continue to trend downward in the short term amid improved availability, sources said.
The homopolymer assessment fell 13.5 cents/lb in the week ended April 24 amid talks of railcars available much lower for the period. S&P Global Platts assessed the homopolymer injection at $2,249-$2,271/mt April 23 on a FAS Houston basis. Ramp-ups by suppliers recovering from the February cold weather disruptions that hit the US Gulf Coast were expected to continue through the end of the month. Talks of normal production were expected to resume in June, sources said. Many buyers were still buying on allocations by producers. Despite the drop, participants deemed pricing too high to export to traditional import markets like Latin America amid competitive pricing from key global sellers. Still, there was talk that pricing would continue to dip on expected decreases in feedstock propylene contract price. Domestic market participants were eying a potential decrease as downstream contract settlements typically follow a monomer plus formula.
US olefins
US spot polymer-grade propylene is expected to continue rising in the week started April 25 on strong downstream polypropylene demand, sources said. April domestic PGP contracts are expected to settle in the week started April 25 between 10 and 16 cents lower.
US spot ethylene is expected to fall amid steam cracker restarts.
US vinyls
US spot export polyvinyl chloride prices were expected to remain at an all-time high of $1,800/mt FAS Houston in the week started April 25 as producers assess whether they will be able to offer volumes for May export. While all plants that shut amid sustained subfreezing temperatures in mid February have since restarted, turnarounds that were slightly delayed by the freeze shutdowns and more slated for May has kept output tight. Market participants do not expect output to resume normal levels until June. Upstream, caustic soda prices could inch up on growing demand in the pulp and paper industry as offices slowly reopen to workers, particularly in the US, with COVID-19 vaccinations becoming more available.
US aromatics
Benzene prices are expected to continue falling from the almost seven-year high of 503 cents/gal DDP USG reached April 20. While some sources said the decline in prices in the latter half of the week ended April 24 was simply a correction, the week of April 25 started with even lower spot ranges, including May benzene bid and offered at 410-485 cents/gal DDP HTC. May benzene had closed April 23 at 460 cents/gal DDP USG, up 35 cents on the week. Price movements through April 28 may prove influential in the settlement of the May CP, expected by the end of the week. May spot prices in recent weeks show the settlement should be sharply higher than the April CP of 301 cents/gal. Downstream, US styrene prices may see support from producers raising offers to account for higher feedstock prices as CP estimates clarify margins, as well as demand from Europe amid skyrocketing benzene costs in that region. May styrene closed April 23 at $1,520/mt FOB USG, up $50/mt on the week.
Stability is expected in the lower liquidity US aromatics markets of toluene and xylenes. While no spot trading was reported in the week of April 19-23, one market participant said the final days of April could usher in offers from producers who have otherwise been uncharacteristically quiet in the spot market since the mid-February Texas freeze derailed refining operations and supply chains. Sharp increases in benzene prices have improved economics for toluene disproportionation, allowing operators to increase STDP unit run rates, one trader said. Prompt nitration-grade toluene closed April 23 at 273 cents/gal FOB USG, up 3 cents week on week, while mixed xylenes gained 1 cent on the week at 249 cents/gal FOB USG.
April 25, 2021
Housing Gone Crazy
Home Prices Soar 18% To An All Time High; A Record 58% Of Houses Sell Within Two Weeks Of Listing
by Tyler DurdenSunday, Apr 25, 2021 – 05:25 PM
As if the official government data on soaring home prices wasn’t crazy enough, the latest monthly data from RedFin shows that in April, homes sold at their fastest pace on record with nearly half off-market within one week.
“There has been an ongoing debate at Redfin about whether fear of coronavirus infection was keeping homeowners from selling. With a third of American adults now fully vaccinated and still hardly any homes being listed for sale, we’re close to settling that debate,” said Redfin Chief Economist Daryl Fairweather.
(A quick note on the base effect in the housing market: at this time last year, pandemic stay-at-home orders halted homebuying and selling, which makes year-over-year comparisons unreliable for select housing metrics. As such, this report has been broken into two sections: metrics that are OK to compare to the same period in 2020, and metrics for which it makes more sense to compare to the same period in 2019.)
Metrics to compare to 2020:
- The median home-sale price increased 18% year over year to $344,625, an all-time high. Asking prices reached an all-time high of $356,175.
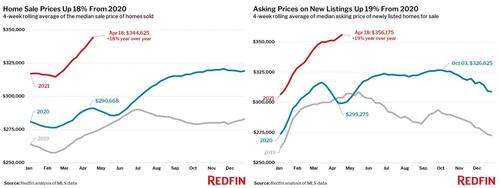
- Homes that sold during the period were on the market for a median of 21 days, the shortest time on market since 2012. This was 16 days fewer than the same period in 2020.
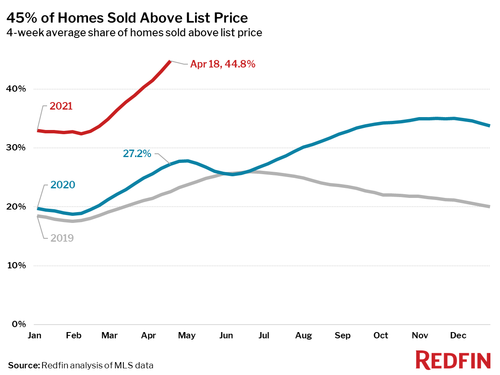
- 45% of homes sold for more than their list price, an all-time high. This was 18 percentage points higher than the same period a year earlier.
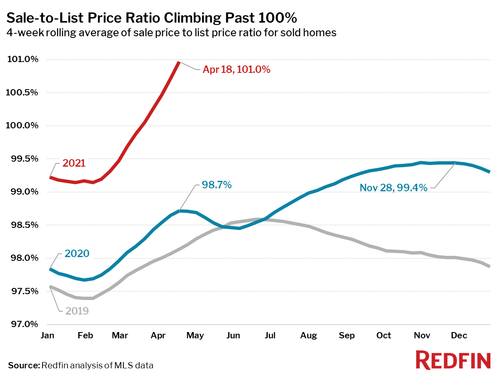
- The average sale-to-list price ratio, which measures how close homes are selling to their asking prices, increased 2.3 percentage points year over year to an all-time high of 101.0%, meaning the average home sold for 1% more than its asking price.
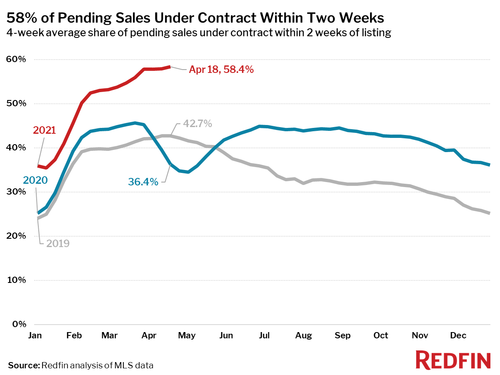
- 58% of homes that went under contract had an accepted offer within the first two weeks on the market. This was a new all-time high (Redfin’s data for this measure goes back to 2012).
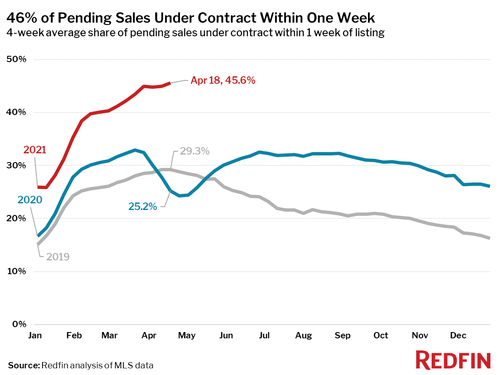
- 46% of homes that went under contract had an accepted offer within one week of hitting the market, an all-time high.
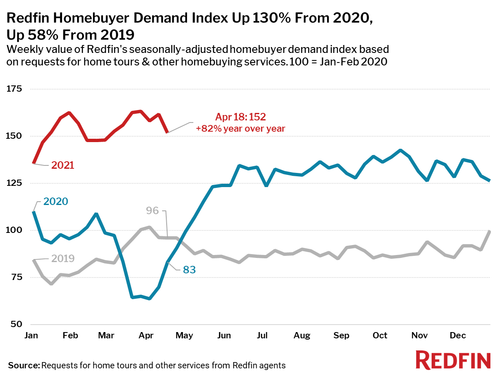
- Meanwhile, with supply at record lows, demand remains near record highs thanks to fiscal stimulus, an exodus from rental units and near-record low mortgage rates.
Metrics to compare to 2019:
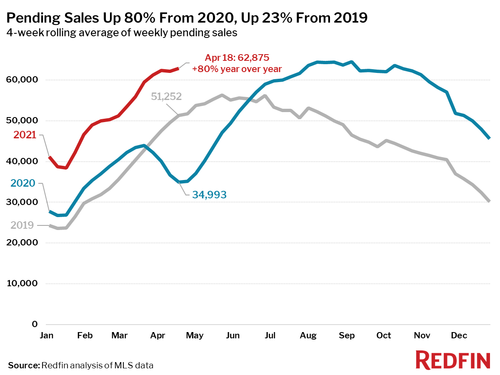
- Pending home sales were up 23% from the same period in 2019.
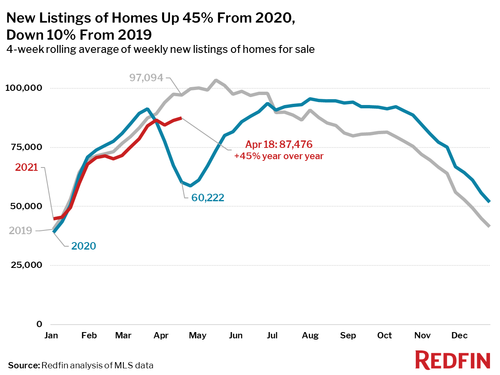
- New listings of homes for sale were down 10% from the same period in 2019.
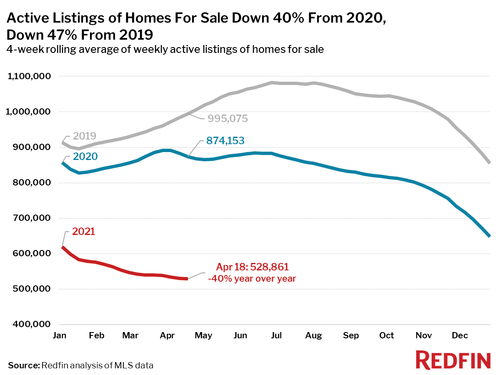
- Active listings (the number of homes listed for sale at any point during the period) fell 47% from the same period in 2019 to a new all-time low.
Fairweather’s conclusion: “Homeowners are staying put because if they move and buy another home they will face a very competitive housing market as buyers, and they don’t need to sell to take advantage of record low mortgage rates. They can just refinance their current home. On top of that, builders are struggling to construct new homes given an ongoing lumber shortage. Without more homeowners listing, buyers are scrambling to compete for the limited number of homes on the market, which continues to drive prices up to new heights.”
April 25, 2021
Housing Gone Crazy
Home Prices Soar 18% To An All Time High; A Record 58% Of Houses Sell Within Two Weeks Of Listing
by Tyler DurdenSunday, Apr 25, 2021 – 05:25 PM
As if the official government data on soaring home prices wasn’t crazy enough, the latest monthly data from RedFin shows that in April, homes sold at their fastest pace on record with nearly half off-market within one week.
“There has been an ongoing debate at Redfin about whether fear of coronavirus infection was keeping homeowners from selling. With a third of American adults now fully vaccinated and still hardly any homes being listed for sale, we’re close to settling that debate,” said Redfin Chief Economist Daryl Fairweather.
(A quick note on the base effect in the housing market: at this time last year, pandemic stay-at-home orders halted homebuying and selling, which makes year-over-year comparisons unreliable for select housing metrics. As such, this report has been broken into two sections: metrics that are OK to compare to the same period in 2020, and metrics for which it makes more sense to compare to the same period in 2019.)
Metrics to compare to 2020:
- The median home-sale price increased 18% year over year to $344,625, an all-time high. Asking prices reached an all-time high of $356,175.
- Homes that sold during the period were on the market for a median of 21 days, the shortest time on market since 2012. This was 16 days fewer than the same period in 2020.
- 45% of homes sold for more than their list price, an all-time high. This was 18 percentage points higher than the same period a year earlier.
- The average sale-to-list price ratio, which measures how close homes are selling to their asking prices, increased 2.3 percentage points year over year to an all-time high of 101.0%, meaning the average home sold for 1% more than its asking price.
- 58% of homes that went under contract had an accepted offer within the first two weeks on the market. This was a new all-time high (Redfin’s data for this measure goes back to 2012).
- 46% of homes that went under contract had an accepted offer within one week of hitting the market, an all-time high.
- Meanwhile, with supply at record lows, demand remains near record highs thanks to fiscal stimulus, an exodus from rental units and near-record low mortgage rates.
Metrics to compare to 2019:
- Pending home sales were up 23% from the same period in 2019.
- New listings of homes for sale were down 10% from the same period in 2019.
- Active listings (the number of homes listed for sale at any point during the period) fell 47% from the same period in 2019 to a new all-time low.
Fairweather’s conclusion: “Homeowners are staying put because if they move and buy another home they will face a very competitive housing market as buyers, and they don’t need to sell to take advantage of record low mortgage rates. They can just refinance their current home. On top of that, builders are struggling to construct new homes given an ongoing lumber shortage. Without more homeowners listing, buyers are scrambling to compete for the limited number of homes on the market, which continues to drive prices up to new heights.”
 Everchem Updates Archive
 Sign Up for Email Updates