
Epoxy
February 25, 2021
Spot Propylene Drops 23c/lb Today With Restarts
FACTBOX: US spot propylene prices plunge from freeze-fueled record high
- Author
- Kristen Hays Astrid Torres Sarah Schneider
- Editor
- Richard Rubin
- Commodity
- Petrochemicals
Houston — US spot polymer-grade propylene prices fell sharply from all-time highs Feb. 24 as two of the three propane dehydrogenation plants in the US began restarting after coming offline during the deep freeze that hit the US Gulf Coast the week of Feb. 15.
Spot propylene prices already had reached their highest level in a decade before the freeze on tight supply, which grew tighter when sustained sub-freezing temperatures forced Dow Chemical’s 750,000 mt/year unit in Freeport, Texas, and Flint Hills Resources’ 658,000 mt/year unit in Houston offline. Enterprise Products Partners had already shut its 750,000 mt/year PDH unit pre-freeze on Feb. 1 for maintenance, the company confirmed.
Spot polymer-grade propylene prices plunged 23 cents on Feb. 24 to 102 cents/lb from an all-time high of 125 cents/lb on news that Dow and Flint Hills were restarting their units, market sources said.
However, downstream polymer prices were expected to rise sharply in the coming weeks as volumes are offered after plants restart, sources said.
Those restarts were expected to be gradual, as producers had to ensure downstream units could operate before restarting upstream olefins units, sources noted.
In addition, supply chains had to recover as well. The freeze affected much of the US in addition to the US Gulf Coast, and trucking services and railroads moving domestic volumes inland from the region.
“Domestically, it’s horrendous going north,” a source said. Shipments of volumes already bought could take several weeks to reach their destinations, he added. Market participants also were concerned about whether enough rail cars would return to move out more product once production ramps back up.
Indorama Ventures in March will impose a 4.5 cents/lb surcharge on shipments of all grades of polyethylene terephthalate, the resin used to make plastic bottles, on all supplies in the US, Mexico and Canada, to cover higher feedstock and logistics cost not included in formula-based resin pricing, according to a customer letter dated Feb. 23.
Here is a rundown of confirmed fallout from the freeze:
FORCE MAJEURES
**Dow Chemical: Declared Feb. 19, on 2-ethylhexanol and butanol products from its Texas City, Texas complex
**Formosa Plastics USA: Declared Feb. 19 on US polyethylene
**BASF: Declared Feb. 19 on dioctyl terephthalate (DOTP), a plasticizer, at its Pasadena, Texas, site
**Westlake Chemical: Declared Feb. 19 on US caustic soda, chlorine, PVC and VCM; company has 2.9 million mt/year of US caustic soda capacity, more than 2 million mt/year of PVC capacity, 2.6 million mt/year of VCM; more than 2.26 million mt/year of chlorine capacity at five affected sites
**Formosa Plastics USA: Declared Feb. 18 on US PVC, 1.3 million mt/year of capacity at Point Comfort, Texas, and Baton Rouge, Louisiana, complexes.
**Dow Chemical: Declared Feb. 18 on multiple intermediate chemicals produced at plants in Deer Park, Freeport, Texas City and Bayport Texas, Hahnville, Louisiana, and Louisville, Kentucky; declaration includes vinyl acetate monomer (VAM), methyl methacrylate (MMA), glacial methacrylic acid (GMAA), butyl methacrylate (BMA), glycidyl methacrylate (GMA), 2-ethylhexyl Acrylate (2EHA), butyl acrylate (BA), and others; Dow informed South American customers
**Celanese: Declared force majeure Feb. 18 on multiple intermediate chemicals normally sold to customers in the US, Europe and the Middle East, including acetic acid, VAM, ethyl acetate and ethylene vinyl acetate (EVA)
**Total: Declared Feb. 17 on polypropylene produced at its 1.15 million mt/year La Porte, Texas, facility
**Formosa Plastics USA: Declared Feb. 17 on all chlor-alkali products
**LyondellBasell: Declared Feb. 16 on styrene monomer
**Vestolit: Declared Feb. 16 on PVC produced at its Colombia and Mexico plants on lack of upstream vinyl chloride monomer feedstock from US suppliers; plants have a combined 1.8 million mt/year of capacity
**Olin: Declared Feb. 16 on US chlorine, caustic soda, ethylene dichloride, epoxy, hydrochloric acid and other products produced at its Freeport, Texas, complex; ; on Feb. 18 Olin expanded the declaration in a separate letter to customers to include products made system-wide
**MEGlobal: Declared Feb. 15 on MEG produced at its Freeport, Texas, site
**LyondellBasell: Declared Feb. 15 on US polyethylene
**Flint Hills Resources: Declared Feb. 15 on polypropylene produced at Longview, Texas
**OxyChem: Declared Feb. 15 on US chlorine, caustic soda, EDC, vinyl chloride monomer and polyvinyl chloride.
**LyondellBasell: Declared Feb. 15 on US polypropylene
**INEOS Olefins and Polymers USA: Declared Feb. 15 on polypropylene
**OQ Chemicals: Declared Feb. 15 on US oxo-alcohols, aldehydes, acids and esters produced at its Bat City, Texas, operations
SHUTDOWNS
**Westlake Chemical: 331,763 mt/year cracker, 249,475 mt/year chlorine, 274,423 mt/year caustic soda, 680,388 mt/year vinyl chloride monomer, 680,388 mt/year polyvinyl chloride, Calvert City, Kentucky
**Eastman Chemical: 7.33 million mt/year ethylene capacity, Longview, Texas
**INEOS: 1.89 million mt/year of ethylene capacity, Chocolate Bayou, Texas
**LyondellBasell: 3.26 million mt/year of ethylene capacity in Channelview, La Porte and Corpus Christi, Texas
**MEGlobal: 750,000 mt/year monoethylene glycol (MEG) plant, Freeport, Texas
**Total: 1.15 million mt/year PP, La Porte, Texas
**Lotte Chemical: 700,000 mt/year MEG, Lake Charles, Louisiana; 1 million mt/year joint-venture cracker
**Braskem: 360,000 mt/year PP Freeport, Texas; 400,000 mt/year PP La Porte, Texas; 225,000 mt/year PP Seadrift, Texas
**ExxonMobil: Cumulative 1.53 million mt/year from three units, HDPE and LLDPE capacity, Mont Belvieu, Texas
**Indorama Ventures: Port Neches, Texas, 235,867 mt/year cracker, 1 million mt/year ethylene oxide/MEG unit, 238,135 mt/year propylene oxide unit, and 988,000 mt/year of MTBE capacity; Clear Lake, Texas, 435,000 mt/year EO, 358,000 mt/year MEG.
**Olin: Freeport, Texas complex, with 3 million mt/year of caustic soda and 2.73 million mt/year of chlorine capacity; 748,000 mt/year of EDC
**OxyChem: Ingleside, Texas, 544,000 mt/year cracker; 248,000 mt/year chlor-alkali; 680,000 mt/year EDC; Deer Park and Pasadena, Texas, 1.27 million mt in PVC capacity; 1.79 million mt/year of VCM capacity; 580,000 mt/year chlor-alkali
**Shintech: Freeport, Texas: 1.45 million mt/year PVC
**Formosa Plastics USA: Entire Point Comfort, Texas, complex, including three crackers with a cumulative capacity of 2.76 million mt/year; 875,000 mt/year of high density polyethylene; 400,000 mt/year of low density PE; 465,000 mt/year of linear low density PE; two PP units with combined capacity of 1.7 million mt/year; 798,000 mt/year of PVC; 1 million mt/year of caustic soda and 910,000 mt/year of chlorine; 753,000 mt/year of VCM; 1.478 million mt/year of EDC; and a cumulative 1.17 million mt/year of monoethylene glycol operated by sister company Nan Ya Plastics.
**Dow Chemical: Certain units offline within Dow sites along the US Gulf Coast, but the company did not specify. Dow’s Gulf Coast operations include a complex at Freeport, Texas, with three crackers able to produce a combined 3.2 million mt/year, two LDPE units with 552,000 mt/year and 186,000 mt/year HDPE; Dow’s Seadrift, Texas, complex includes 490,000 mt/year LLDPE and 390,000 mt/year HDPE; Dow told South American customers in a letter dated Feb. 16 that the company was assessing impact on PE production capacity “and we know that our ability to supply various products could be affected.”
**TPC Group: Houston site shut down, including 544,310 mt/year butadiene unit, when boilers lost steam
**Motiva Chemicals: Port Arthur, 635,000 mt/year mixed-feed cracker
**Shell: Deer Park, Texas, refining and chemical complex, including two crackers with a combined 961,000 mt/year of capacity
**Shell: Norco, Louisiana, refining and chemical complex, including two crackers with a combined capacity of 1.42 million mt/year
**Chevron Phillips Chemical: Pasadena, Texas, 998,000 mt/year HDPE; also has cumulative 5.35 million mt/year in capacity of six crackers in Port Arthur, Baytown and Sweeny, Texas
RESTARTS
**Flint Hills Resources: 658,000 mt/year PDH unit, Houston
**Dow Chemical: 750,000 PDH, Freeport, Texas
**Braskem: Restarting 450,000 mt/year PP, La Porte, Texas
**Dow Chemical: restarting 680,000 mt/year cracker in Orange, Texas
**ExxonMobil: Beaumont, Texas, restart activity begun; 826,000 mt/year cracker; 225,000 mt/year HDPE; 240,000 mt/year LDPE; 1.19 million mt/year LLDPE with some HDPE capacity
**ExxonMobil: Baytown, Texas, restart activity begun; three crackers with a combined capacity of 3.8 million mt/year; 800,000 mt/year PP
**Sasol: Restarts for 380,000 mt/year EO/MEG, Lake Charles, Louisiana
**Formosa Plastics USA: 513,000 mt/year PVC, 653,000 mt/year VCM, Baton Rouge, Louisiana
**LyondellBasell: Lake Charles, Louisiana, joint-venture 470,000 mt/year LLDPE; 420,000 mt/year LDPE
PRICES
**US February spot ethylene prices rose 1.75 cents/lb to 50 cents/lb FD Mont Belvieu and were up 3.25 cents to 47 cents/lg FD Choctaw; for March, the FD Mont Belvieu marker rose 1.75 cents to 47.75 cents/lb and the FD Choctaw marker climbed 3.25 cents to 46.25 cents/lb
**US spot polymer-grade propylene prices fell 23 cents Feb. 24 to 102 cents/lb FD USG, retreating from a fresh all-time high of $1.25/lb FD USG reached Feb. 23, on news of two US PDH unit restarts
**US export homopolymer injection-grade polypropylene assessed $88 higher on the week Feb. 24 at $2,568-$2,590/mt FAS Houston
**US export polyvinyl chloride prices were assessed flat on the week at $1,400/mt FAS Houston, but market participants talked of pricing levels as high as $1,600/mt FAS once producers are able to make volumes available
https://www.spglobal.com/platts/en/products-services/electric-power/gas-and-power
February 24, 2021
Restart Updates
Polar storm paralyses US Gulf Coast petrochemical sector
By Rebecca Trager24 February 2021
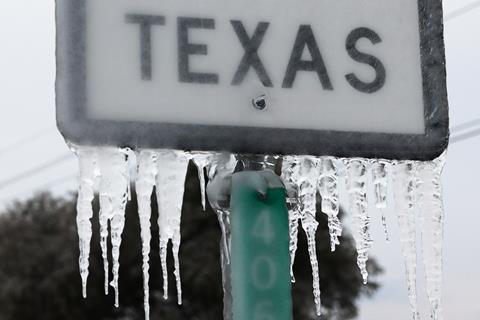
The polar storm that descended into the US Gulf Coast on 14 February, bringing unprecedented prolonged freezing temperatures to many parts of Texas, dramatically disrupted petrochemical supplies. Approximately 75% of total US ethylene capacity remained offline as of 23 February, according to analysis by Kevin McCarthy, who covers the global chemicals industry for the Connecticut-based equity research firm Vertical Research Partners, and colleagues.
Source: © Joe Raedle/Getty Images
The situation in the aftermath of what’s been dubbed the ‘icepocalypse’ of 2021 is very fluid, with the status of plant operations being updated continually, but the data coming in reveals how badly Texas-based chemicals capacity has been impacted by the record-breaking cold weather. Texas is the petrochemical hub of America.
As of 23 February, 100% of epichlorohydrin production was offline, as was about 90% of ethylene glycol production, more than 70% of polypropylene production, over 60% of epoxy resins production, and about 40% of propylene production, Vertical Research Partners finds.
Shutdowns include one or more crackers operated by Chevron Phillips Chemical, Dow, ExxonMobil, Formosa Plastics, Lyondell and Motiva, according to McCarthy’s research note. In addition, Sasol has also reportedly reduced rates at Lake Charles, Louisiana and Indorama appears to have throttled back or shut down ethylene and ethylene oxide at Port Neches, Texas. Likewise, Lyondell’s ethylene oxide is down at Bayport, Texas.
Most of the 150-plus petrochemical facilities in the Houston area are expecting to come back online sometime this week, according to Chad Burke, president and chief executive of the Economic Alliance Houston Port Region. Some are working through repairs while others are waiting on utilities and feedstock supplies to be restored, he says.
Waiting on utilities
An anonymous representative of one of the largest integrated refining and chemical companies in the Houston port area reports being in ‘various stages of startup’ across its different facilities in the area. Meanwhile, a plant manager at another chemical company in the region says the majority of the roughly 75 sites in the vicinity, including their own, are down waiting to receive utilities like natural gas, steam, nitrogen and water. ‘At this stage it looks like another week before utilities return,’ the plant manager, who also preferred not to be identified, said on 22 February.
Although it is difficult to estimate the impact of these facilities being down for the better part of two weeks, it’s bound to be significant since Houston is the largest petrochemical complex in the world, producing more than 40% of America’s chemicals and about 25% of its fuels.
‘The vast majority of petrochemical plants and refineries in the state ceased all production manufacturing and were idling, except for those that were generating power to help provide added support to the state’s electric grid,’ Hector Rivero, president and chief executive of the Texas Chemical Council and the Association of Chemical Industry of Texas, tells Chemistry World.
At this stage it looks like another week before utilities return
Because Texas doesn’t normally have such extreme weather, the state is not prepared and resourced to handle such conditions. There have been ice storms in Texas over the years, but they are generally brief events. This most recent storm was a multi-day hard freeze.
Many chemical plants in the state and nearby Louisiana are not designed to operate in such extreme conditions, so equipment failures and frozen process lines can decrease operational reliability, explained McCarthy and colleagues in their recent research note. They also cautioned that ‘unfavourable network effects’ can exacerbate the situation because many assets are dependent upon neighbouring plants for utilities, like electric power, and the supply of feedstock or intermediates required to operate.
A ‘mad scramble’
In fact, the storm’s extended freeze caused downed power lines and power loss across Texas, and the state had to initiate rolling blackouts to try to ensure that power demand did not exceed supply. These forced outages will certainly impact global supply and demand for chemicals, Rivero says. Indeed, he points out that the price of gas has already soared in parts of Texas and across the US.
‘With all of these facilities being shut down, a lot of the supply chain was also impacted,’ Rivero adds. ‘It is kind of a mad scramble to secure the resources needed to be able to come back online, and that is starting to happen now.’
A key lesson learned is the need to improve the security of the electricity supply regionally, experts suggest. Aside from the temporary challenges posed by the ice storm, which were severe, the scarcity of electric power also created significant consequences for chemical companies. Manufacturing plants had to shut down because of the need to divert and conserve electric power so that it could be preserved for residential and emergency needs. That is a weakness in the system that had remained under-appreciated prior to this severe weather event.
But there is perhaps some good news to be found in a surprising place. The ongoing pandemic has significantly changed the supply chain, and that could help with the recovery of Texas’ petrochemical industry from this natural disaster.
The interruptions caused by the Covid-19 shutdowns actually deepened the inventories of feedstocks, intermediate products like chemicals and resins, and finished products, according to Burke. ‘Both manufacturers and customers recognised the importance of increasing inventories to insulate against supply chain interruptions,’ he explains. ‘Those lessons learned should actually serve to decrease the time it takes now to get back into production.’
February 24, 2021
Restart Updates
Polar storm paralyses US Gulf Coast petrochemical sector
By Rebecca Trager24 February 2021
The polar storm that descended into the US Gulf Coast on 14 February, bringing unprecedented prolonged freezing temperatures to many parts of Texas, dramatically disrupted petrochemical supplies. Approximately 75% of total US ethylene capacity remained offline as of 23 February, according to analysis by Kevin McCarthy, who covers the global chemicals industry for the Connecticut-based equity research firm Vertical Research Partners, and colleagues.
Source: © Joe Raedle/Getty Images
The situation in the aftermath of what’s been dubbed the ‘icepocalypse’ of 2021 is very fluid, with the status of plant operations being updated continually, but the data coming in reveals how badly Texas-based chemicals capacity has been impacted by the record-breaking cold weather. Texas is the petrochemical hub of America.
As of 23 February, 100% of epichlorohydrin production was offline, as was about 90% of ethylene glycol production, more than 70% of polypropylene production, over 60% of epoxy resins production, and about 40% of propylene production, Vertical Research Partners finds.
Shutdowns include one or more crackers operated by Chevron Phillips Chemical, Dow, ExxonMobil, Formosa Plastics, Lyondell and Motiva, according to McCarthy’s research note. In addition, Sasol has also reportedly reduced rates at Lake Charles, Louisiana and Indorama appears to have throttled back or shut down ethylene and ethylene oxide at Port Neches, Texas. Likewise, Lyondell’s ethylene oxide is down at Bayport, Texas.
Most of the 150-plus petrochemical facilities in the Houston area are expecting to come back online sometime this week, according to Chad Burke, president and chief executive of the Economic Alliance Houston Port Region. Some are working through repairs while others are waiting on utilities and feedstock supplies to be restored, he says.
Waiting on utilities
An anonymous representative of one of the largest integrated refining and chemical companies in the Houston port area reports being in ‘various stages of startup’ across its different facilities in the area. Meanwhile, a plant manager at another chemical company in the region says the majority of the roughly 75 sites in the vicinity, including their own, are down waiting to receive utilities like natural gas, steam, nitrogen and water. ‘At this stage it looks like another week before utilities return,’ the plant manager, who also preferred not to be identified, said on 22 February.
Although it is difficult to estimate the impact of these facilities being down for the better part of two weeks, it’s bound to be significant since Houston is the largest petrochemical complex in the world, producing more than 40% of America’s chemicals and about 25% of its fuels.
‘The vast majority of petrochemical plants and refineries in the state ceased all production manufacturing and were idling, except for those that were generating power to help provide added support to the state’s electric grid,’ Hector Rivero, president and chief executive of the Texas Chemical Council and the Association of Chemical Industry of Texas, tells Chemistry World.
At this stage it looks like another week before utilities return
Because Texas doesn’t normally have such extreme weather, the state is not prepared and resourced to handle such conditions. There have been ice storms in Texas over the years, but they are generally brief events. This most recent storm was a multi-day hard freeze.
Many chemical plants in the state and nearby Louisiana are not designed to operate in such extreme conditions, so equipment failures and frozen process lines can decrease operational reliability, explained McCarthy and colleagues in their recent research note. They also cautioned that ‘unfavourable network effects’ can exacerbate the situation because many assets are dependent upon neighbouring plants for utilities, like electric power, and the supply of feedstock or intermediates required to operate.
A ‘mad scramble’
In fact, the storm’s extended freeze caused downed power lines and power loss across Texas, and the state had to initiate rolling blackouts to try to ensure that power demand did not exceed supply. These forced outages will certainly impact global supply and demand for chemicals, Rivero says. Indeed, he points out that the price of gas has already soared in parts of Texas and across the US.
‘With all of these facilities being shut down, a lot of the supply chain was also impacted,’ Rivero adds. ‘It is kind of a mad scramble to secure the resources needed to be able to come back online, and that is starting to happen now.’
A key lesson learned is the need to improve the security of the electricity supply regionally, experts suggest. Aside from the temporary challenges posed by the ice storm, which were severe, the scarcity of electric power also created significant consequences for chemical companies. Manufacturing plants had to shut down because of the need to divert and conserve electric power so that it could be preserved for residential and emergency needs. That is a weakness in the system that had remained under-appreciated prior to this severe weather event.
But there is perhaps some good news to be found in a surprising place. The ongoing pandemic has significantly changed the supply chain, and that could help with the recovery of Texas’ petrochemical industry from this natural disaster.
The interruptions caused by the Covid-19 shutdowns actually deepened the inventories of feedstocks, intermediate products like chemicals and resins, and finished products, according to Burke. ‘Both manufacturers and customers recognised the importance of increasing inventories to insulate against supply chain interruptions,’ he explains. ‘Those lessons learned should actually serve to decrease the time it takes now to get back into production.’
February 24, 2021
West Coast Ports
Shippers Need Alternatives to West Coast Port Congestion
February 22, 2021 Robert J. Bowman, SupplyChainBrain
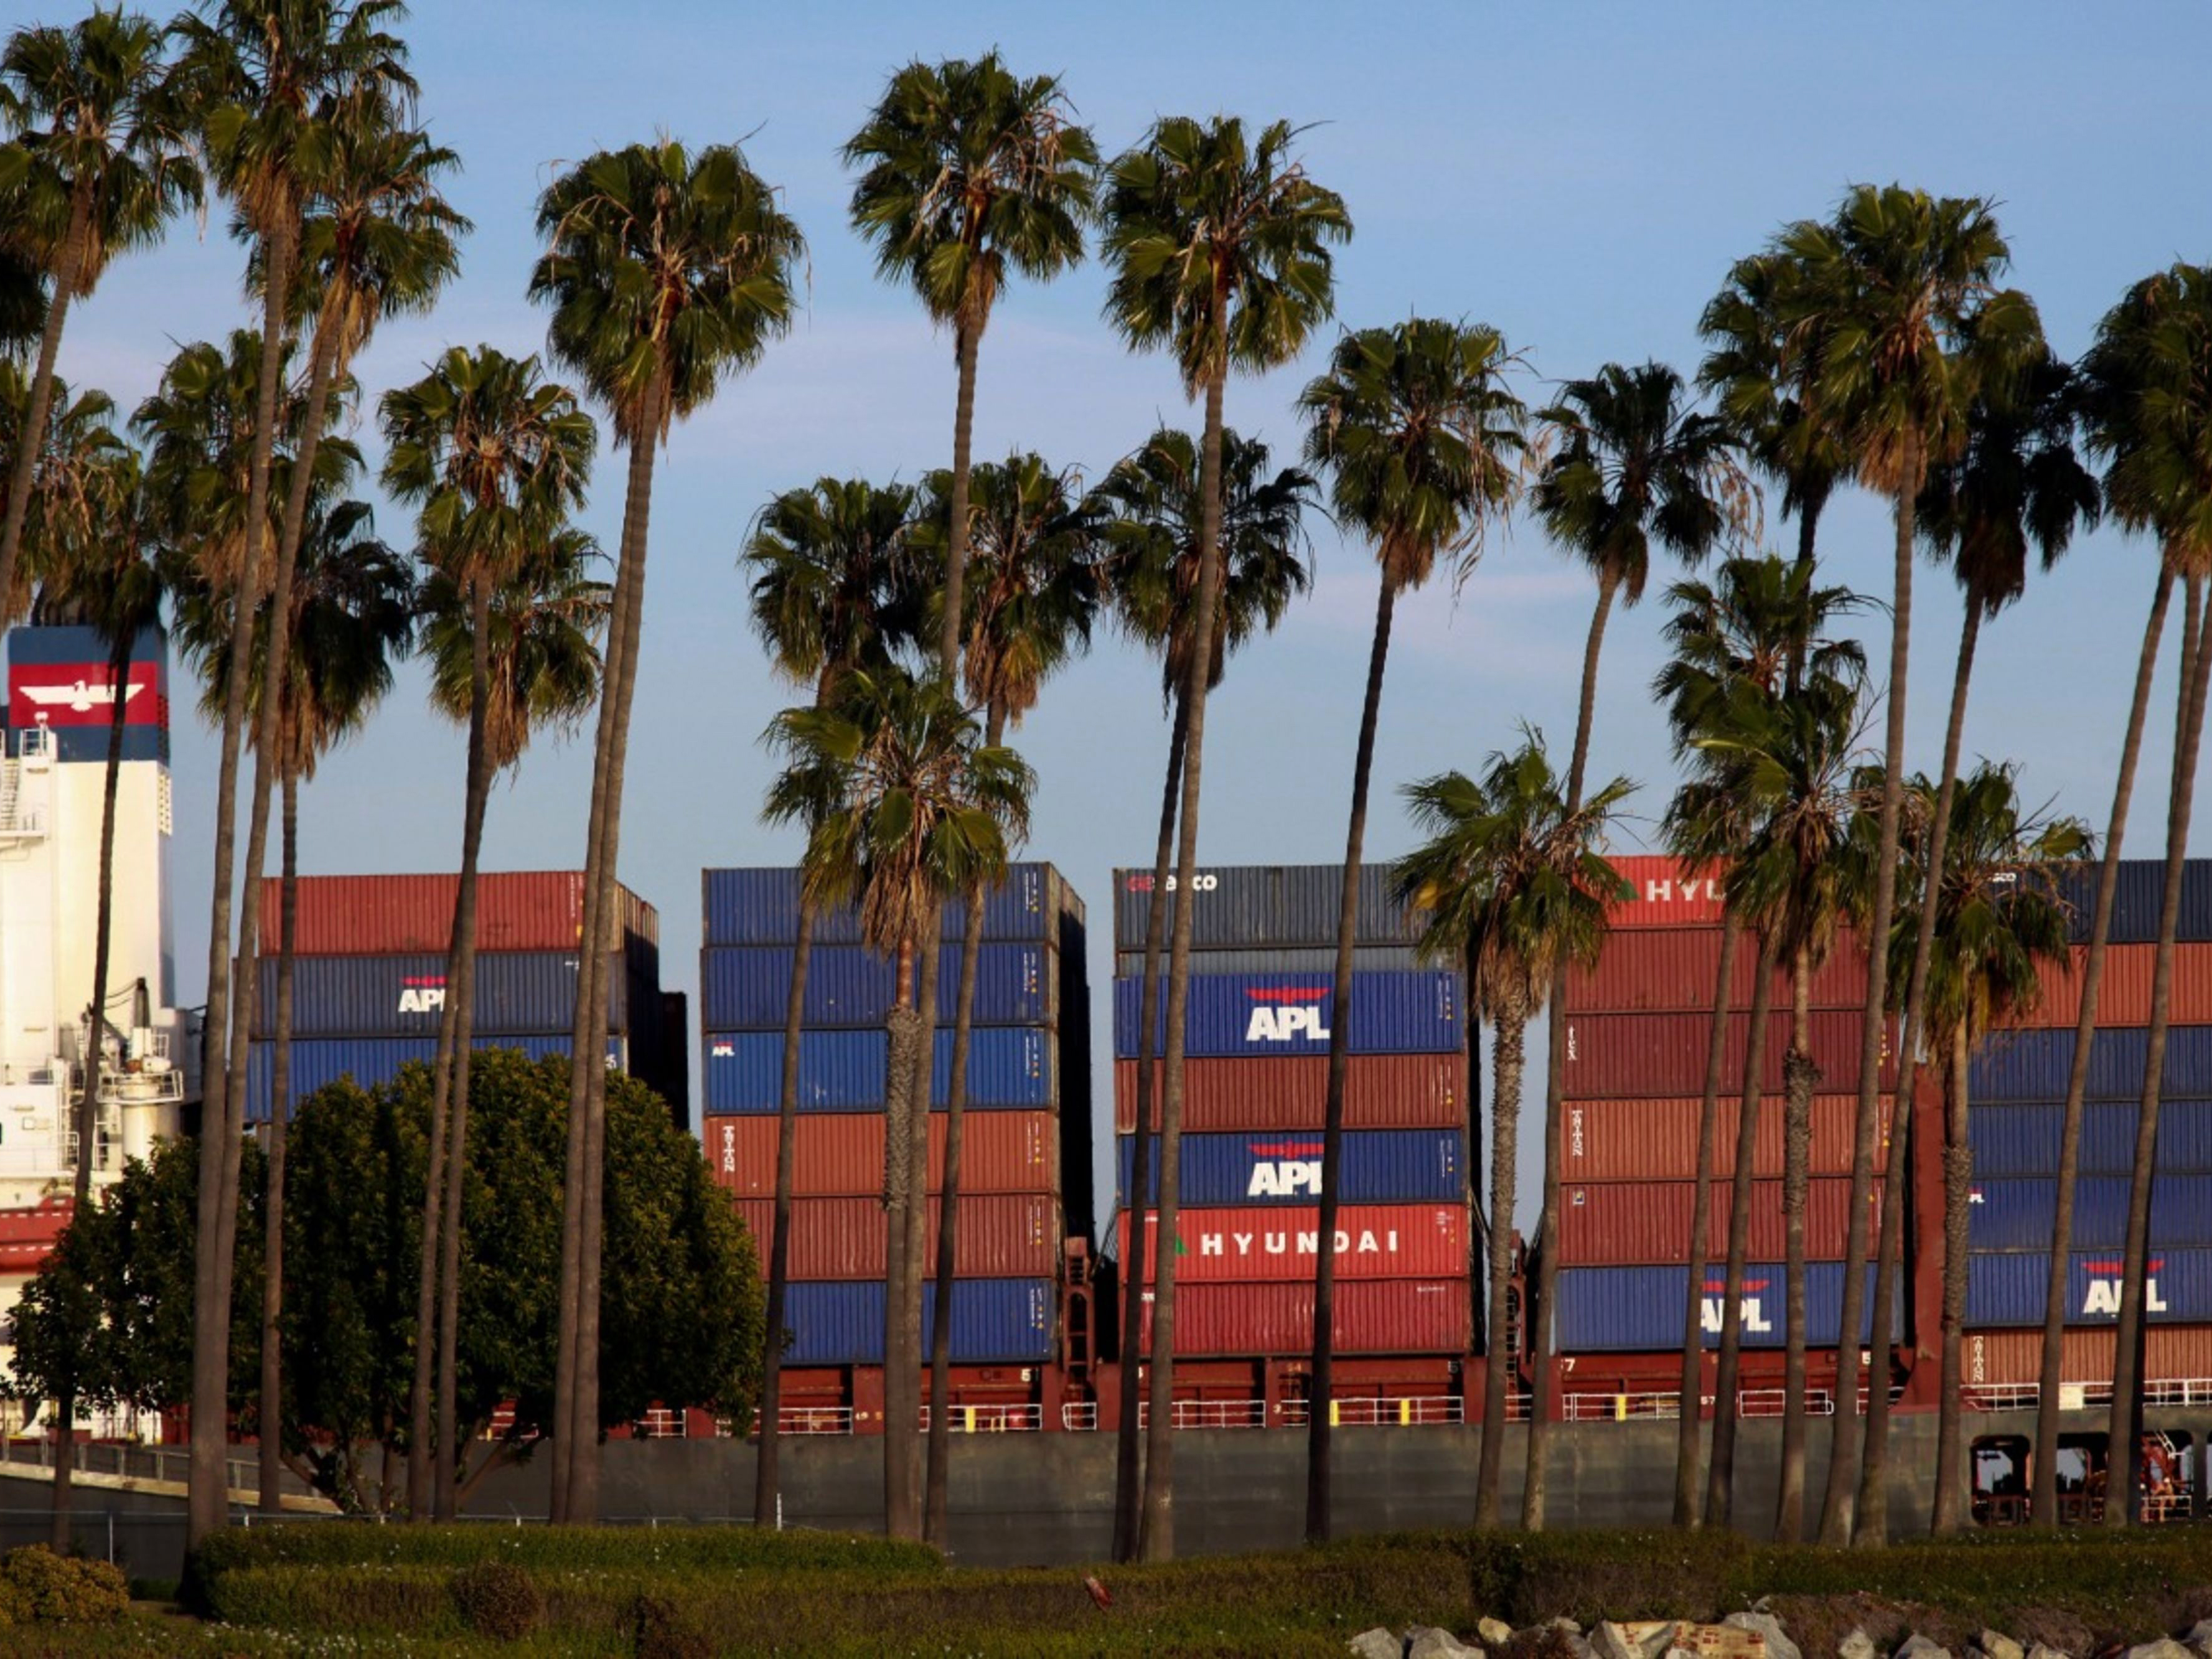
The ports of Los Angeles and Long Beach are currently experiencing severe congestion, with a heavy backup of containers waiting to unload import cargo from Asia. In this conversation with SupplyChainBrain Editor-in-Chief Bob Bowman, Jason Totah, president of Odyssey International Services Inc., discusses alternatives to bringing cargo through overtaxed West Coast ports.
SCB: What’s the situation at the ports of Los Angeles and Long Beach right now?
Totah: It’s quite a logjam, from unloading ships to making containers and chassis available at the port, and appointments to pick up containers. It’s a pretty desperate situation.
SCB: What’s the cause of this congestion?
Totah: Just a lack of planning across the board. This season in particular has been more severe than others because of the pandemic, extra volume, and the vessel alliances omitting and consolidating ports. For various reasons, it’s creating this huge logjam.
SCB: Shouldn’t volumes be slacking off after the holiday peak season, and into Chinese New Year?
Totah: We’ve always had a peak past December, ahead of Chinese New Year. People are uncertain about when factories are going to come back online after Chinese New Year, and the possibility of labor in China being quarantined when they do come back. So everybody’s trying to buy a lot sooner. The anticipation of delays is what’s causing these problems.
SCB: What are you proposing as an alternative for shippers who don’t want to deal with congestion at Long Beach and Los Angeles?
Totah: Our advice has been to have a lot more elasticity in their supply chain, look at different options, and not put all their eggs in one basket. Alternatives would be to use the ports of Seattle or Tacoma as a gateway. Or maybe Oakland, even though there’s not a lot of direct sailings or vessels calling there direct.
SCB: Are Seattle and Tacoma first ports of call inbound from Asia, and last ports of call outbound? Are there a sufficient number of sailings like that in order to take the overflow from L.A./Long Beach?
Totah: Yes. Seattle-Tacoma is either the fourth- or fifth-largest containerport complex in the United States, combining in the Northwest Seaport Alliance. They have quite a lot of sailings coming in. They’re not the super-max vessels, but there are direct sailings from major ports in Asia.
SCB: What about infrastructure beyond the piers in Seattle and Tacoma, such as on-dock or near-dock rail transfer yards, and the ability to transload into trucks as well? Is there adequate capacity for that up there?
Totah: It’s adequate today for the volume they have, but with proper planning it can be scaled. There are a few terminals that have on-dock rail. There’s a similar lack of trucks and chassis, but at smaller scale, than in L.A. and Long Beach.
SCB: How about coming into the Port of Vancouver, British Columbia, then transiting by rail across Canada and down into the U.S. Midwest? Is that an option?
Totah: That has always been an option. Many importers have used it in the past, and it has a customs advantage on valuation because importers don’t pay a harbor maintenance fee when goods arrive at ports in Canada. But the Canadian rails are also congested. You’ll have some people using them, but if you don’t do it regularly, you’re not going to have access to those routings because steamship lines have dedicated space for the people who do.
SCB: Are the lines intent on keeping incoming international containers at the port, so that they can expedite their return to Asia? And does that necessitate transloading inbound cargo into domestic equipment to go inland?
Totah: Yes. Carriers are very reluctant to accept bookings beyond the West Coast. They can give you containers to load your product in, but they don’t want to give you containers to go inland.
SCB: So you have to transload. Is that a good idea anyway? Or does it slow things down?
Totah: Transloading has been a good idea in our view, especially at Seattle/Tacoma, to certain parts of the United States. I’m not proposing that transloading from there into the Southeast is a good option, because the connectivity on the rail isn’t that great. But there are direct points from Seattle/Tacoma to Chicago, Minneapolis, and the Ohio Valley that can offer faster transit time, because international containers don’t move regularly. Domestic trailers move on a daily basis, versus maybe weekly for ocean containers. And congestion at inland rail hubs isn’t as bad for domestic containers. So in terms of transit time and price from port to door, we find that transloading is very competitive.
SCB: When we talk about onward transportation of cargo offloaded on the West Coast and moving into the Midwest, is that mostly by rail? Or does long-haul truck offer an alternative?
Totah: Long-haul over-the-road capacity has been declining for the last several years. There’s a big migration to intermodal. I think that domestic intermodal services are a lot more effective than over-the-road because there’s no limitation on hours of service, or the need for team drivers to deliver the cargo.
SCB: What about bypassing the West Coast altogether, through the Panama Canal and up the East Coast? Is that a viable option today for shippers?
Totah: I think it is. A lot of shippers are based on the East Coast and use all-water services to get there. The demand for it is great, and similar to what I mentioned about going through Vancouver, B.C. Shippers who use the service regularly are committed to it, and give steamship lines the base loads to go in there. It’s not easy for you just to flip-flop to the East Coast based on your needs, because you may not get the space. Up until the last couple of years, there was more demand on the all-water service than via the West Coast. So that’s already at capacity, too.
SCB: What about going in the other direction — from East Asian ports through the Suez Canal, then via transatlantic service to the East Coast?
Totah: It does work from the subcontinent — India, Pakistan, Bangladesh, Sri Lanka, and maybe Singapore, but not from Northeast Asian ports such as Hong Kong. It just adds way too much time. Plus congestion and capacity constraints aren’t limited to the North America trade. It’s also to Europe and other areas. The longer the transit on the water, the more capacity just gets sucked out of the system.
SCB: Do you believe this situation is going to persist throughout 2021?
Totah: I don’t see how it wouldn’t. What we need is a true investment in our industry — for stakeholders to buy more equipment, including containers and chassis, and add vessels. For international trade worldwide, I can’t see it slowing down.
 Everchem Updates Archive
 Sign Up for Email Updates