The Urethane Blog
January 24, 2024
BASF Hauling More Product by Road as German Train Strike Starts — OPIS

Provided by Dow Jones
Jan 24, 2024 1:26 PM EST
German chemicals major BASF expects a six-day nationwide rail strike in Germany starting Wednesday will have more of an adverse impact on hauling the company’s products than previous strikes and necessitate a greater use of road transport.
“In normal circumstances, we handle about 30% of our transports by rail. Due to the rail strike, we are now forced to shift railway transports on a large scale to trucks,” said Uwe Liebelt, President of European Verbund Sites at BASF, in a statement shared with OPIS on Wednesday. “This will increase logistics costs and CO2 emissions.”
BASF said that it had taken measures to cushion the effects of the upcoming strike on production sites and customers, but added that its operations were still recovering from adverse weather and a previous rail strike earlier in January.
“The fact that the strikes are occurring very close together, giving BASF very little preparation time, and the existing backlog due to last week’s snowfall that has not yet been cleared, significantly complicates the situation,” the company’s statement said.
The international competitiveness of Germany, “which is already under considerable pressure due to high energy and raw material costs, will be further damaged,” said Liebelt, who is in charge of BASF’s chemical production sites that have highly interlinked product flows.
BASF’s Ludwigshafen site is one of the world’s largest integrated chemical complexes. The site is home to a dense network of 200 plants that create a variety of products and petrochemicals for diverse industries, according to the company’s website.
The company declined to say whether run rates at any of its sites have been impacted by the strike.
German train drivers began the record six-day strike starting January 24 after their union rejected state-owned rail operator Deutsche Bahn’s latest wage offer. The country’s cargo train drivers began their strike on the evening of January 23.
GDL, the trade union representing Germany’s train drivers, said the fourth round of strikes in the ongoing wage dispute will last until January 29, 6pm Central European Time.
Later on Wednesday, Germany-based chemicals producer Covestro told OPIS that there were no “restrictions” on production at its sites due to the strikes.
“We have made the best possible preparations for the strike and, wherever possible, switched to road and inland waterway transportation at an early stage,” said a spokesperson for the company. “We currently see only limited effects on Covestro and can continue production without restrictions. At the same time, the changeover is naturally accompanied by increased operating expenses.”
January 22, 2024
The Reality of American “Deindustrialization”
Manufacturing in the United States has not disappeared but has been transformed and very much remains a vital part of the country’s economic fabric.
October 24, 2023 • Publications
- Despite rhetoric from some politicians that decades of unfettered globalization have hollowed out the U.S. industrial base, the United States remains a manufacturing powerhouse, accounting for a larger share of global output than Japan, Germany, and South Korea combined. In key industries such as autos and aerospace, the United States ranks among the global leaders and is the second‐largest manufacturing economy overall.
- That manufacturing employs fewer Americans and accounts for a lower percentage of gross domestic product than in decades past is not cause for serious concern, unique to the United States, or primarily owed to globalization. These trends have instead been largely driven by productivity gains and shifting consumer preferences in favor of services.
- The premium placed by policymakers on manufacturing employment is misplaced. Unlike most of the post–World War II era, jobs in this sector now provide lower compensation than similar roles elsewhere in the economy, while the diversified nature of the U.S. economy is a source of economic resiliency, not weakness.
An unfortunate perception among many commentators and political leaders is that the United States “doesn’t make anything anymore.” According to this narrative, the country is a former manufacturing titan brought low by the forces of globalization that have left the rusting hulks of once‐humming factories in its wake. Instead of producing their wares in locations such as Pittsburgh and Peoria, some globalization critics claim U.S. corporations have shifted their operations to take advantage of vastly lower wages in China, Mexico, and elsewhere. Factory closures, these critics insist, have forced American workers to trade well‐paid work on the assembly line for less financially rewarding jobs in the service sector. In this telling, trade liberalization’s legacy is one of industrial decline, wrecked lives, and ruined communities.
Reports of American manufacturing’s death, however, are greatly exaggerated. While it is undeniably true that certain manufacturing industries—particularly labor‐intensive, low‐tech ones—are no longer primarily located in the United States, many other, more advanced ones have flourished. Thus, factories producing consumer staples such as textiles and furniture, for example, have made way for facilities that produce products less often found in retail stores, such as chemicals and machinery. At the same time, productivity gains unleashed by automation and other technologies have enabled manufacturing output to remain near record highs even as direct manufacturing employment has declined. Many other Americans, meanwhile, still work in manufacturing or are involved in the manufacturing process through the design of new products, even if their employers don’t operate actual factories.
In short, manufacturing in the United States has not disappeared but has been transformed and very much remains a vital part of the country’s economic fabric.
Deindustrialization Worries Are Nothing New
Politicians have sought to advance and capitalize on worries of industrial decline for decades. During his 1984 presidential campaign, Walter Mondale told steelworkers in Cleveland that President Ronald Reagan’s policies were “turning our industrial Midwest into a “rust bowl”—a turn of phrase soon modified and popularized by the media as “Rust Belt.” This region’s misfortunes—and the broader alleged plight of American manufacturing—have been an enduring feature of the political discourse ever since.
Some of this focus is the natural result of politicians’ and the media’s long‐standing attraction to bad news and nostalgia: Factory closures make news (or even movies); factory expansions don’t. And the industrial Midwest’s long‐standing importance to the U.S. presidential election means that the region will always receive outsized political attention, regardless of economic realities elsewhere in the country.
Yet certain statistics also lend a superficial plausibility to claims of domestic manufacturing’s dire state. U.S. manufacturing employment peaked in 1979 at 19.5 million employees, stood at just over 17 million in 2000, and has since dropped to approximately 13 million as of January 2023. In relative terms, the percentage of workers employed in manufacturing has more than halved since 1980 as did its share of gross domestic product (GDP) from 1978 to 2018.
Such declines also correlate with a growing embrace of trade liberalization over this period via such initiatives as the North American Free Trade Agreement, conclusion of the Uruguay Round of trade negotiations and agreement to establish the World Trade Organization (WTO), and China’s accession to the WTO (although the decline was already underway when each of these took place).
No great effort is therefore required to grasp why many Americans believe that the country’s industrial sector—and the well‐paying jobs that go with it—has received a hammer blow at the hand of globalized commerce more generally and China in particular. But that doesn’t mean it’s true. A fuller and more accurate picture reveals a sector in remarkably good health whose indications of decline are far less worrisome when placed in proper context.
What Is Manufacturing?
Before delving into the state of U.S. manufacturing, it is worth examining what the industry entails. Although the term may conjure images of glowing hot steel or new automobiles rolling off the assembly line, manufacturing runs a wide gamut of activities. According to the Bureau of Labor Statistics, manufacturers are “… establishments engaged in the mechanical, physical, or chemical transformation of materials, substances, or components into new products.” These include not only the production of heavy machinery and sophisticated devices but also other items, such as fruit and vegetable preserves, stationary, and beverages. By this definition, Coca‐Cola is every bit the manufacturer as Boeing, General Motors, or U.S. Steel.
But the dividing line can sometimes be ambiguous. U.S.-headquartered Nike, for example, engages in the design and marketing—key parts of the manufacturing process—of footwear, apparel, and sports equipment. The actual production of these items, however, is outsourced to independent contractors. Global semiconductor leader Nvidia follows much the same approach. Should these “factoryless goods producers” be considered manufacturers? So far, the government’s answer is no. Nevertheless, such firms are key contributors to the manufacturing process and generate considerable value, jobs, and innovations.
The United States Remains a Manufacturing Powerhouse
Regardless of how one defines manufacturing, the United States is clearly one of its heavy hitters. In 2021, it ranked second in the share of global manufacturing output at 15.92 percent—greater than Japan, Germany, and South Korea combined—and the sector by itself would constitute the world’s eighth‐largest economy. The United States was the world’s fourth‐largest steel producer in 2020, second‐largest automaker in 2021, and largest aerospace exporter in 2021.
That the United States has achieved these rankings with a relatively small industrial workforce is a testament to its world‐beating productivity: the country ranks number one in real manufacturing value‐added per worker by a large margin. With value‐added of over $141,000 per worker in 2019, the United States bested second‐ranked South Korea by over $44,000. The gap with China was over $120,000 per worker (Figure 1).
Manufacturing output has also remained strong in historical terms, at only 5 percent lower than its all‐time high achieved in the final quarter of 2007 (Figure 2). Measured by real value‐added, the sector reached its highest level in 2022 (Figure 3).
Read more here: https://www.cato.org/publications/reality-american-deindustrialization#united-states-remains-manufacturing-powerhouse
January 21, 2024
2023 Was The Worst Year On Record For Existing Home Sales
by Tyler Durden
Friday, Jan 19, 2024 – 10:35 AM
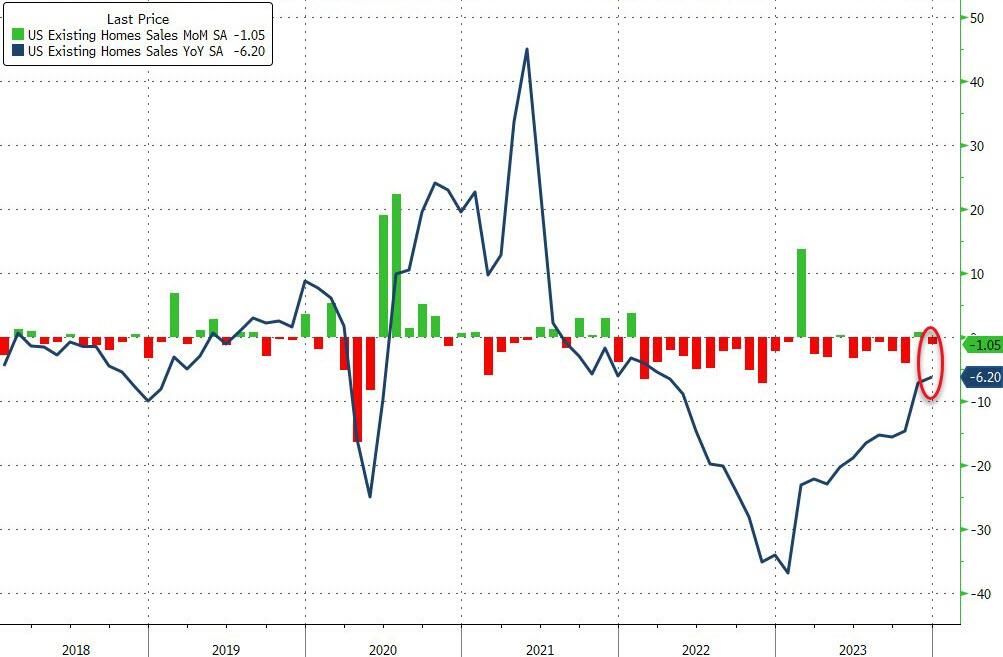
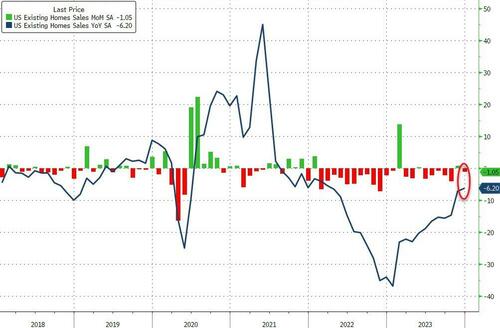
Existing Home Sales fell 1.0% MoM in December, worse than the +0.3% expected, leaving sales down
Source: Bloomberg
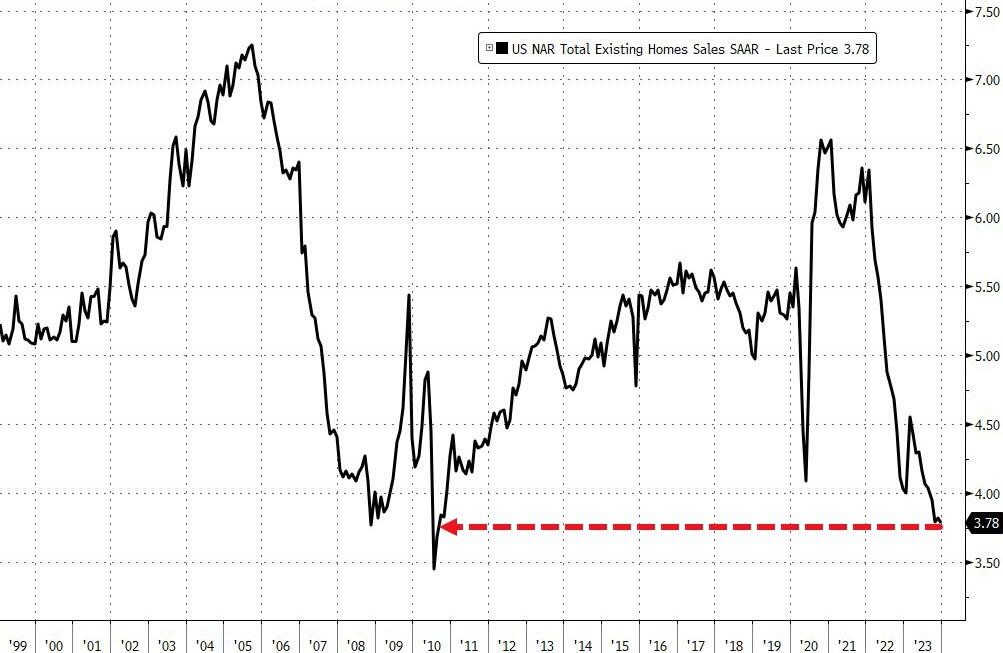
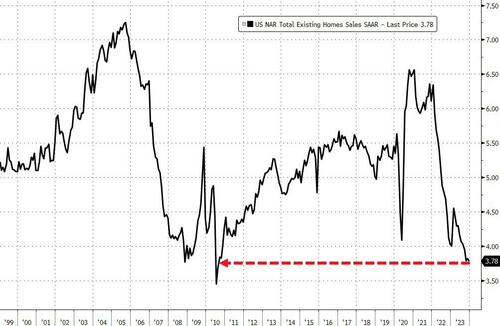
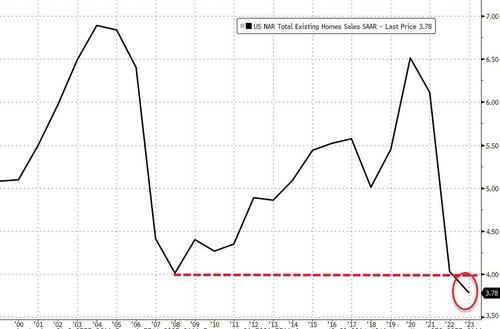
Total Existing Home Sales in December 2023 were 3.78mm – the lowest SAAR since 2010…
Source: Bloomberg
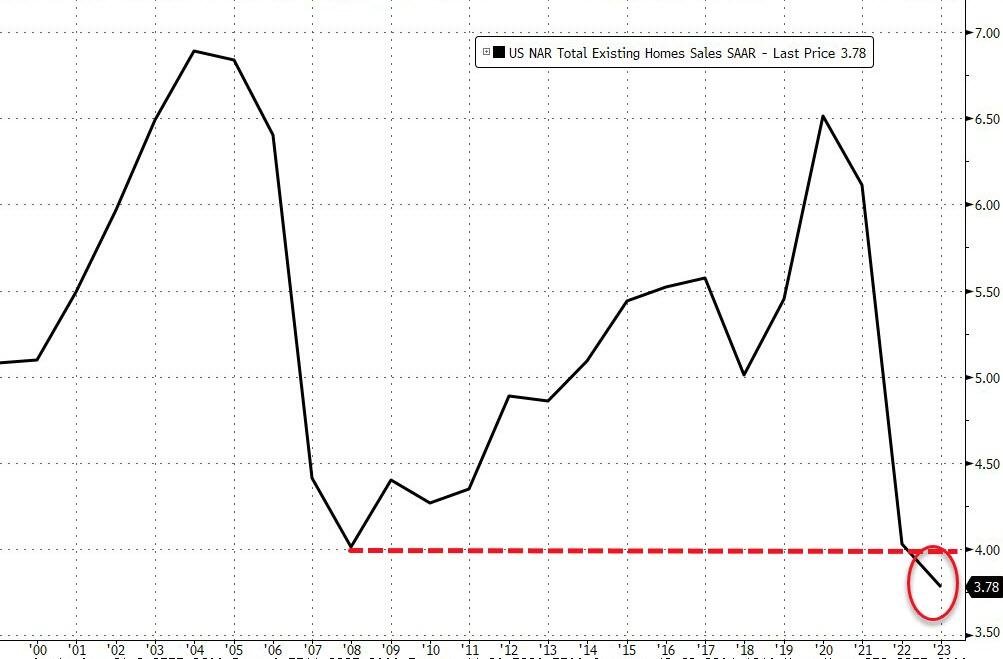
But, on an annual basis, this is the worst year on record (back to at least 1995)..
Source: Bloomberg
“The latest month’s sales look to be the bottom before inevitably turning higher in the new year,” said NAR Chief Economist Lawrence Yun. “Mortgage rates are meaningfully lower compared to just two months ago, and more inventory is expected to appear on the market in upcoming months.”
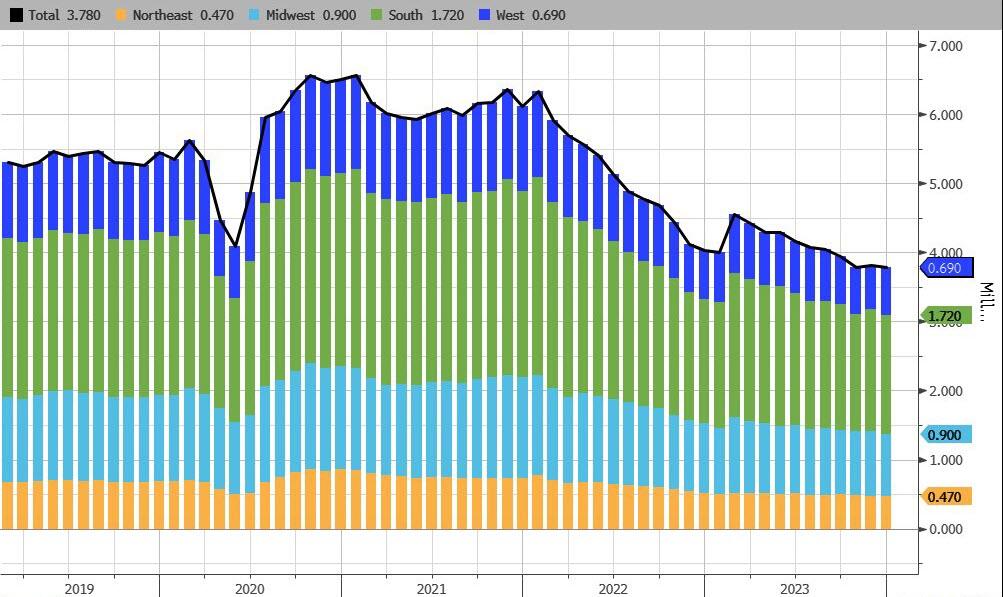
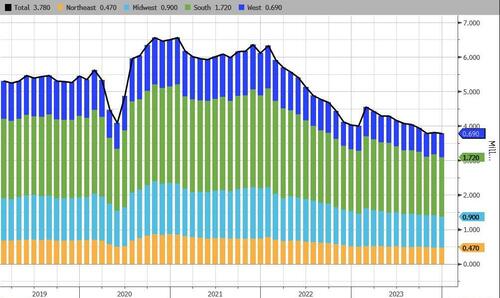
Existing Home Sales were flat in the Northeast, lower in the MidWest and the South, and up marginally in the West (driven by single-family-home sales as condo sales declined)…
Source: Bloomberg
Last month, the number of previously owned homes for sale dropped to 1 million, the lowest since March.
At the current sales pace, selling all the properties on the market would take 3.2 months.
Realtors see anything below five months of supply as indicative of a tight resale market.
That lack of inventory is helping to keep prices elevated.
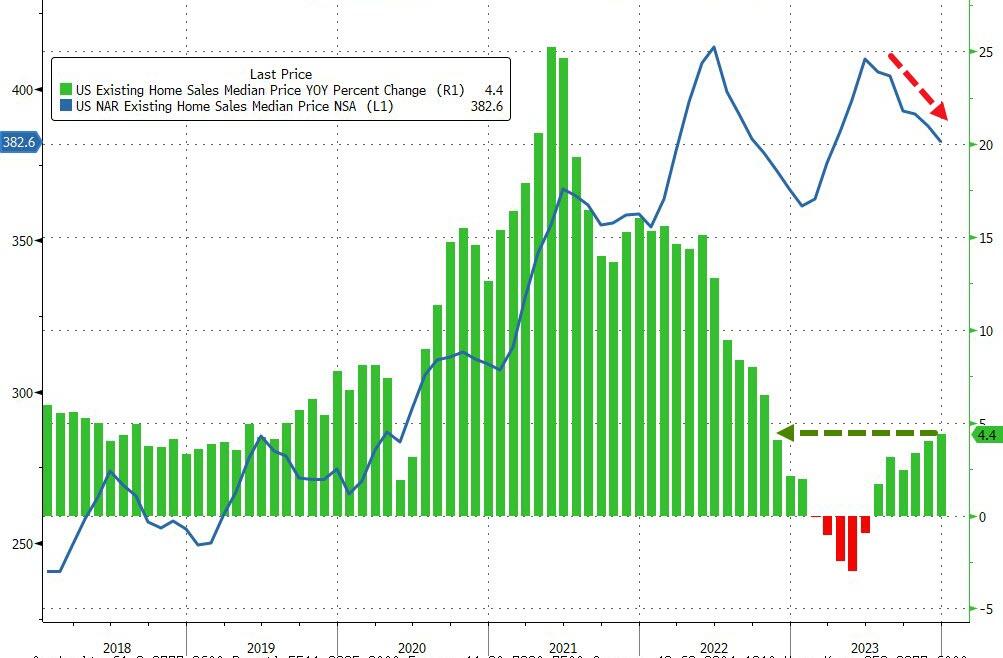
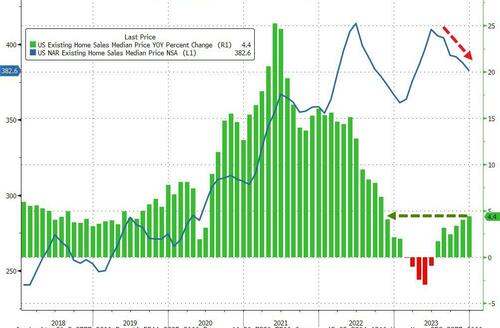
The median selling price climbed 4.4% to $382,600 in December from a year ago, reflecting increases in all four regions. Prices hit a record of $389,800 in 2023.
Source: Bloomberg
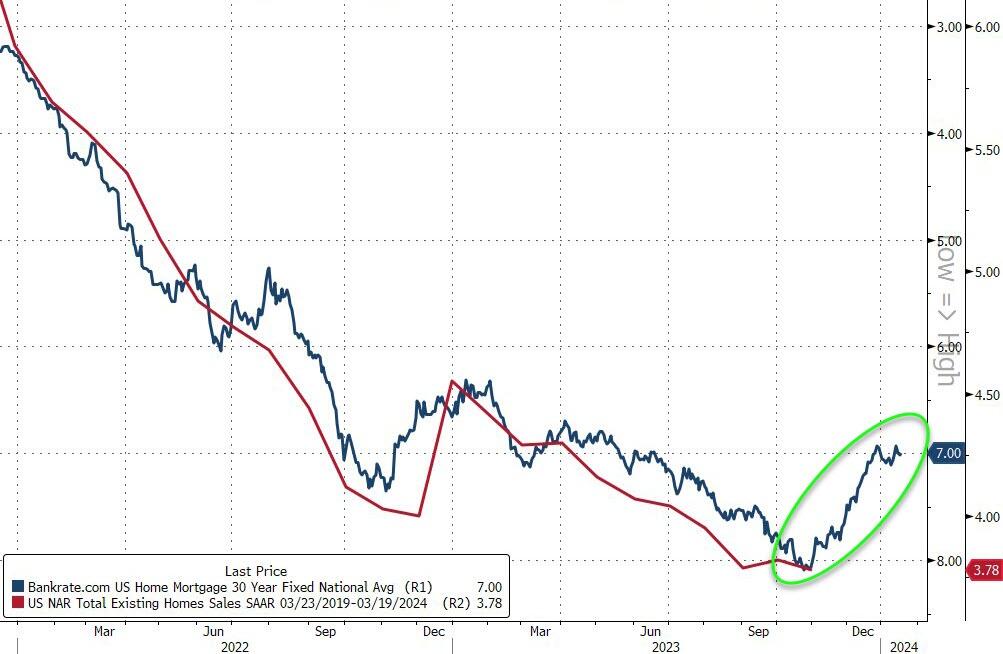
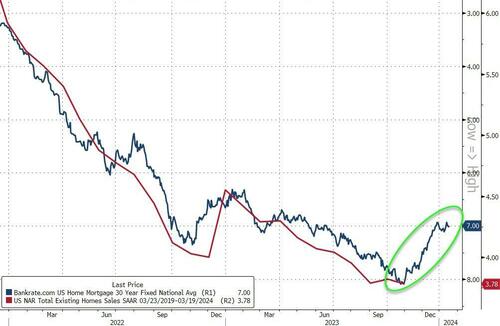
But, with mortgage rates having tumbled (and given the lagged responses), are sales about to start rising again?
Source: Bloomberg
https://www.zerohedge.com/markets/2023-was-worst-year-record-existing-home-sales
January 19, 2024
BASF Group releases preliminary figures for full year 2023
- Sales and EBIT before special items below the ranges forecasted by BASF and slightly below the respective analyst consensus
- EBIT and net income considerably below the respective analyst consensus due to non-cash-effective impairments
- Cash flows from operating activities above prior year
Ludwigshafen – January 19, 2024 – Expected BASF Group sales for the full year 2023 of €68,902 million are below the range of €73 billion to €76 billion forecasted by BASF and below average analyst estimates for 2023 (Vara: €70,579 million). Sales in 2022 amounted to €87,327 million.
Expected income from operations (EBIT) before special items of €3,806 million in 2023 is below the range of €4.0 billion to €4.4 billion forecasted by BASF and below the level of average analyst estimates for 2023 (Vara: €3,934 million). EBIT before special items in 2022 amounted to €6,878 million. The decrease compared with the prior year is due to sales-related lower margins, which could not be offset by the achieved fixed cost reduction.
The average analyst estimates for EBIT before special items of the segments are slightly exceeded in 2023 by Industrial Solutions, Materials and Agricultural Solutions. In the Chemicals segment, EBIT before special items in 2023 falls considerably short of average analyst estimates, among other things due to unplanned plant shutdowns. In the Surface Technologies and Nutrition & Care segments, EBIT before special items in 2023 remains slightly below the respective analyst consensus. In Other, EBIT before special items in 2023 is slightly weaker than expected by analysts on average.
The BASF Group’s expected EBIT in 2023 amounts to €2,240 million; this is below analyst consensus for 2023 (Vara: €3,691 million) and below the figure for the prior year (2022: €6,548 million). This is primarily attributable to non-cash-effective impairments in the amount of €1.1 billion. These mainly relate to the Surface Technologies, Agricultural Solutions and Materials segments.
Net income of BASF Group is expected to amount to €225 million in 2023. This is an improvement of €852 million compared with the prior-year figure (2022: minus €627 million), which included non-cash-effective impairments on Russia-related assets of Wintershall Dea in the amount of €6.5 billion. Analyst consensus for net income in 2023 (Vara: €2,247 million) is, however, not achieved.
Cash flows from operating activities are expected to reach €8.1 billion in 2023 and are thus above the prior-year figure of €7,709 million. Free cash flow is expected to amount to €2.7 billion (2022: €3,333 million).
January 19, 2024
Huntsman Updates Fourth Quarter 2023 Outlook; To Discuss Fourth Quarter 2023 Results on February 22, 2024; Results to be Released After Market Close on February 21, 2024
Download as PDFJanuary 19, 2024 7:00am EST

THE WOODLANDS, Texas, Jan. 19, 2024 /PRNewswire/ — Huntsman Corporation (NYSE: HUN) now expects fourth quarter 2023 adjusted EBITDA to be in the range of $40 million to $45 million compared to our original guidance range of $65 million to $90 million as communicated on October 31, 2023. The lower range compared to prior guidance is primarily due to continued pressure in our Polyurethanes segment, including lower equity earnings and the negative impact of an unplanned outage during the quarter at the Rotterdam, Netherlands facility, which has now been resolved. These are preliminary results and are subject to completion of the corporation’s annual audit process.
Huntsman Corporation will hold a conference call on Thursday, February 22, 2024, at 10:00 a.m. ET to discuss its fourth quarter 2023 financial results. Following some opening remarks, the call will move into a question and answer session.
The earnings press release, including financial statements and segment information, will be distributed after the market closes on Wednesday, February 21, 2024. The earnings slide presentation and prepared remarks will be available at www.huntsman.com/investors after the market closes on Wednesday, February 21, 2024.
Webcast link:
https://event.choruscall.com/mediaframe/webcast.html?webcastid=4YckWj4j
| Participant dial-in numbers: | |
| Domestic callers: | (877) 402-8037 |
| International callers: | (201) 378-4913 |
The conference call will be accessible via the webcast link and Huntsman’s investor relations website, www.huntsman.com/investors. Upon conclusion of the call, the webcast replay will be accessible via Huntsman’s website.
 Everchem Updates Archive
 Sign Up for Email Updates