
The Urethane Blog

Carpenter Co., one of the world’s largest producers of comfort products, is pleased to announce that it has completed the acquisition of Recticel N.V.’s Engineered Foams Division, which includes the former Foam Partner and Otto Bock operations. The acquisition creates the world’s largest vertically integrated manufacturer of polyurethane foams and specialty polymer products.
Recticel, a Belgian company with origins tracing back to 1778, comprises people, offices and production facilities in Europe, Asia, Africa and North America. The transaction allows Carpenter to expand its geographic footprint, explore new product lines and add new capabilities to the industry leader.
Brad Beauchamp, CEO of Carpenter Co., expressed, “We are very excited to welcome the employees of Recticel, Foam Partner and Otto Bock into Carpenter. We believe that combining these great businesses with ours will result in the best flexible foam company throughout all market segments and geographic locations. We believe that this acquisition will bring additional innovations in polyurethane foam beyond our industry leading materials like Serene® foam, Hybrid TheraGel™ memory foam and others. Recticel is also known for their leadership in sustainability and recycling of foam materials and we expect that to pair very well with our own developments on those issues that are facing the industry.”
Both Carpenter and Recticel have demonstrated a commitment to innovation, sustainability and continuous improvement. United together, the combined organization will work towards a shared purpose: to enhance the quality of life for everyone through its products and services.
June 14, 2023
PPI Plunges More Than Expected – Lowest Since Dec 2020
by Tyler Durden
Wednesday, Jun 14, 2023 – 08:36 AM
After a mixed picture from CPI data yesterday (headline down big, core still sticky, supercore rising), PPI was expected to continue to decline in data this morning for May, and it did bigly… Headline PPI fell 0.3% MoM in May (way more than the 0.1% drop expected), which dragged the YoY PPI to just 1.1%. That is the lowest since Dec 2020…
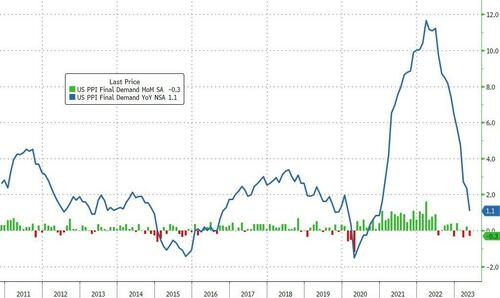
Source: Bloomberg
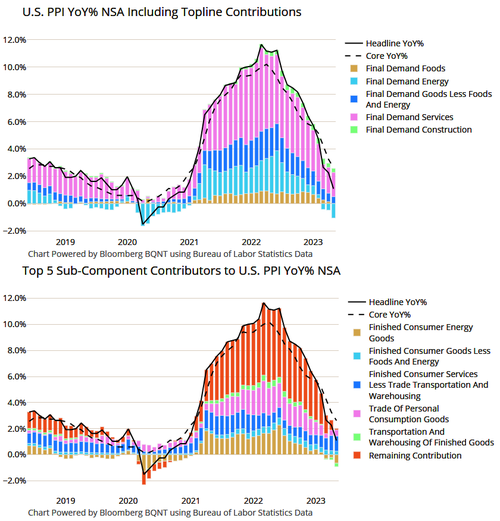
Under the hood, Goods PPI tumbled 1.6% while Services rose just 0.2%…
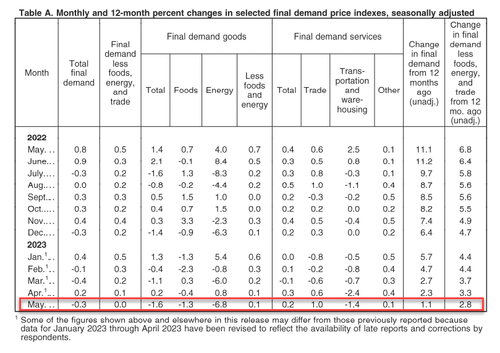
Sixty percent of the May decline in the index for final demand goods can be traced to a 13.8-percent drop in prices for gasoline.
The indexes for diesel fuel, chicken eggs, jet fuel, fresh and dry vegetables, and iron and steel scrap also fell. Conversely, prices for tobacco products advanced 1.7 percent. The indexes for electric power and for beverages and beverage materials also increased.
Over 40 percent of the May increase in prices for final demand services can be attributed to margins for automobiles and automobile parts retailing, which rose 4.2 percent.
The indexes for fuels and lubricants retailing; apparel, footwear, and accessories retailing; securities brokerage, dealing, investment advice, and related services; machinery and vehicle wholesaling; and food wholesaling also advanced. Conversely, prices for truck transportation of freight fell 2.1 percent. The indexes for portfolio management and for health, beauty, and optical goods retailing also decreased.
Core PPI was unchanged MoM, dragging the YoY change to +2.8% – the lowest since Feb 2021…
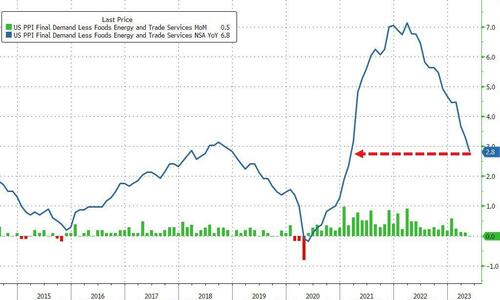
Source: Bloomberg
The pipeline for PPI is also increasingly deflationary as prices for intermediate demand goods plunge…
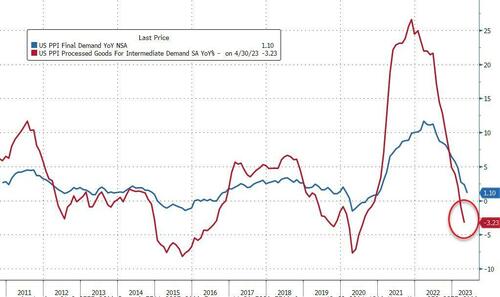
Source: Bloomberg
Finally, M2 suggests this re-acceleration of the deflationary impulse in PPI is set to continue aggressively…
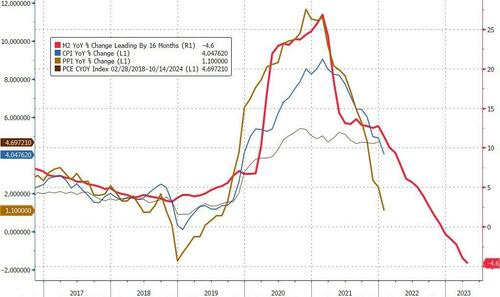
Source: Bloomberg
The question is – does The Fed care about PPI? Or just its latest SuperCore CPI as an inflation ‘signal’?
Finally, we note the following trend – is this the new economy?
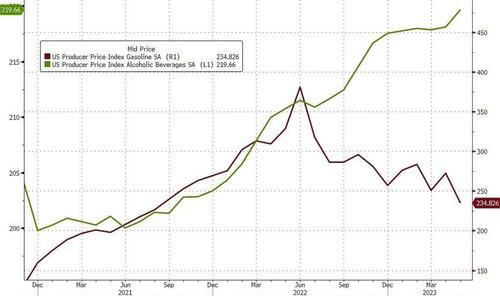
Drink more, drive less?
https://www.zerohedge.com/personal-finance/ppi-plunges-more-expected-lowest-dec-2020
June 14, 2023
Recticel becomes a pure insulation player after completing the divestment of its Engineered Foams activities on 12 and 13 June 2023

Regulated information, Brussels, 14/06/2023 — 06:59 CET, 14.06.2023
- Changes in transaction perimeter: Recticel keeps The Soundcoat Company Inc. (USA – acoustic and thermal insulation) and its 33% participation in Orsa Foam S.p.A. (Italy)
- Recticel Ltd. (UK Comfort Foams) sold to GIL Investments Ltd.
- Revised Enterprise Value of EUR 454.1 million
- Cash proceeds of EUR 427.0 million
- Reduction of IFRS16 lease debt by EUR 23.9 million, and reduction of other provisions and liabilities by EUR 30.6 million
- The transaction represents a 7.5 x multiple on the average 2021 and 2022 Adjusted EBITDA pertaining to the divested perimeter
Recticel signed a binding agreement (see press release dd. 07 December 2021) to sell its Engineered Foams activities to US-based Carpenter Co., subject to customary closing conditions, including anti-trust clearance. Carpenter and Recticel received such clearance from the UK Competition & Markets Authority (CMA) on 12 April 2023, and have subsequently signed the divestment of the two UK Comfort foam facilities (remedies meeting CMA requirements) to GIL Investments Ltd. on 17 April 2023 (see press release dd. 28 April 2023). All conditions precedent being met, Carpenter Co. and Recticel could progress to closing the main transaction.
June 13, 2023
BDO Market Booms with Growing Demand in Traditional and Emerging Industries
ECHEMI2023-06-12
1,4-butanediol (BDO) is an influential organic and fine chemical raw material, widely used in textile, chemical and other fields. Demand for BDO has formed a significant driving force in recent years with the expansion of applications in emerging fields such as biodegradable plastics and lithium batteries, as well as the recovery of traditional downstream industries such as spandex and PBT plastics.
According to SteelHome, the BDO market is currently extremely hot, with prices rising sharply. The benchmark price of BDO in the East China market has exceeded 11000-11100 yuan/ton, with a growth to the past week. According to research by Shenwan Hongyuan Securities, China’s apparent BDO consumption is expected to reach about 4.47 million tons per year by 2025, and the compound annual growth rate of BDO demand from 2020 to 2025 will be 26.5 percent.
BDO’s traditional application areas are primarily spandex and PBT engineered plastics, with BDO’s downstream applications in the spandex industry chain and PBT engineered plastics reaching 51% and 26% respectively. The spandex market is extremely hot, with product prices up nearly 200 percent, as demand for textiles and clothing recovers and export orders rise. The PBT plastics sector is also showing a clear trend of growth, with increasing applications in new energy vehicles and charging devices.
In addition to traditional application areas, BDO is rapidly expanding its applications in emerging areas such as biodegradable plastics and lithium batteries. With the frequent introduction of domestic plastic reduction policies, the demand for biodegradable plastics is about to enter a period of explosive growth, and PBAT is expected to lead the way in the agricultural plastic film and packaging materials and other biodegradable plastic markets with well-established production technologies and high cost-effectiveness. As a major feedstock for PBAT, PBAT is expected to generate approximately 2.5 million tonnes/year of new demand for BDO by 2025. At the same time, BDO is an essential raw material in the hottest lithium battery industry chain, and its downstream NMP is an important solvent in the production process of lithium battery cathodes, as well as a cleaning agent for semiconductors and integrated circuits.
Due to the long-term low BDO product prices, companies can only barely maintain a break-even point, and the industry’s sluggish business environment severely hinders new capital expenditures. Currently, the d Chinese annual production capacity of BDO is about 1.45 million tons, and the demand gap exceeds 200,000 tons. Only two A-share listed companies, Zhongtai Chemical and Shaanxi Black Cat, have BDO production capacity, with a combined annual capacity of only 330,000 tons. The huge gap between supply and demand has attracted a group of domestic companies to ramp up production on a regular basis. More than 1.5 million tons of new BDO capacity are currently planned in China, but the construction of BDO capacity usually takes about two years and there is a certain commissioning period after completion to achieve stable production. The fastest new capacity will gradually enter the production release period in the second half of 2022. Many industry insiders believe that the mismatch between new capacity and downstream demand growth will keep this cycle of BDO shortages going for more than two years, and that the BDO business environment will continue to improve as a result.
Recently, the world’s largest BDO project with an annual production capacity of 900,000 tons was settled in Fujian. The project will help boost China’s new energy and environmental protection industries by using the large amount of hydrogen produced as a by-product of propane dehydrogenation to produce BDO, a new chemical material that can be used to produce lithium batteries, high-end spandex, fully biodegradable plastics and other products. The move is an important boost for China’s plasticization industry and will help promote the transformation and upgrading of the country’s chemical industry, as well as the development of new energy and environmental protection industries.
https://www.echemi.com/cms/1416474.html
Polybutylene adipate terephthalate
From Wikipedia, the free encyclopedia
PBAT (short for polybutylene adipate terephthalate) is a biodegradable random copolymer, specifically a copolyester of adipic acid, 1,4-butanediol and terephthalic acid (from dimethyl terephthalate). PBAT is produced by many different manufacturers and may be known by the brand names ecoflex, Wango, Ecoworld, Eastar Bio, and Origo-Bi. It is also called poly(butylene adipate-co-terephthalate) and sometimes polybutyrate-adipate-terephthalate[1] (a misnomer) or even just “polybutyrate”.[2] It is generally marketed as a fully biodegradable alternative to low-density polyethylene, having many similar properties including flexibility and resilience, allowing it to be used for many similar uses such as plastic bags and wraps.[3] It is depicted as a block co-polymer here due to the common synthetic method of first synthesizing two copolymer blocks and then combining them. However, it is important to note that the actual structure of the polymer is a random co-polymer of the blocks shown.
Read more here: https://en.wikipedia.org/wiki/Polybutylene_adipate_terephthalate
June 13, 2023
Furniture industry moves forward
June 5, 2023 | 10:37 am CDT
Photo courtesy of Groupe Lacasse.
The economy, along with material costs and labor concerns continues to temper the sales outlook of many residential and contract furniture manufacturers.
According to Allied Market Research, North American demand for furniture — residential and commercial — will hit $400.1 billion by 2030, at a CAGR of 4.9% (2021-2030). The residential segment is forecast to have a greater market share due to ongoing home renovations, plus the growing infrastructure and real estate market. Commercial furniture growth continues to be driven by companies investing in furnishing offices for social distancing and flexible or hybrid workplaces. Smart furniture is also gaining popularity.
Preliminary figures by S&P Global Market Intelligence, published on BIFMA’s website, show the North American office and institutional furniture market size reached an estimated $24.7 billion in 2022, up 18.4 percent from 2021. The United States accounted for $16.2 billion, with Canada at $4.2 billion and Mexico at $4.3 billion.
Based on comments by manufacturers, 2023 is also projected to be relatively positive by many in the contract furniture market.
Steelcase (#5), for example, has seen 17 percent revenue growth for fiscal 2023, despite a challenging environment.
“In the Americas, our fourth quarter orders were stronger than we anticipated and drove revenue and earnings above our expectations,” said Sara Armbruster, president and CEO. “Although our fourth quarter orders were below the prior year, project business from large corporate customers improved sequentially from the third quarter. We’ve seen opportunity creation in the Americas grow on a year-over-year basis for eight of the last nine months, and in recent months, a notable number of larger companies in the United States have announced workplace strategies that emphasize the importance of an in-office presence.”
With the supply chain stabilizing in most cases, allowing for shorter lead times and steady supply, 2023 sales for Groupe Lacasse (#96) are projected to rise compared to 2022, said Sylvain Garneau, president and CEO. “Overall, it might be above 2019 (pre-COVID).”
Projections for 2024, however, are too early to tell.
“When your lead times are two to eight weeks, it is too early to say,” Garneau said. “There is still quite a bit of unknown for 2024: Recession or not? Will there be more returning to work in downtown or not? Will employers invest more in their workplaces to make them more attractive or not? It’s too far out at this time.”
See sidebars below: Changes in the FDMC 300, Outlook for outdoor furniture
On the residential side, new furniture orders dropped 17 percent in February compared to 2022, although up slightly from January 2023 figures, according to the latest issue of Furniture Insights produced by analyst and consulting firm Smith Leonard.
Yet a number of manufacturers remain bullish on projections for 2023 and beyond.
“I am pleased with our third quarter results and the progress the organization has made, especially as we consider the many consumer and macroeconomic headwinds we continue to face,” said Jerry Dittmer, president, and CEO of Flexsteel Industries (#28). “Despite the market challenges…. Our growth initiatives are working and gaining momentum, and we anticipate continuing that drive to deliver even higher sales in the fourth quarter compared to the third quarter results.”
La-Z-Boy (#13) and Ethan Allen (#32) also recorded strong third quarters for fiscal 2023. “We are pleased with our third quarter operating performance,” stated Farooq Kathwari, Ethan Allen chairman, president and CEO. “We are confident in the investments that we are making for the future, but recognize the need to remain cognizant of the slower economic environment in which we are currently operating in. We remain cautiously optimistic,” he added.
Gat Caperton, CEO of Gat Creek (#211), is also cautiously optimistic on 2023 sales growth. “Sales will be up slightly,” he noted. “We’ll do well in the first half of the year, but the second half is shaping up to be a bit soft.”
Projections for 2024, he added, are “good.”
We asked Caperton and Garneau to share some of their tips for success. “Stay focused and resilient!” Garneau said. “Leverage our strengths.”
Caperton added, “Adapt quickly to changes in demand. It’s too hard to predict accurately so you have to adapt quickly.”
He continued, “The past two years were amazingly consistent, given a large bubble of pandemic orders that needed to be worked off.”
Meeting the challenges
Optimism is tempered by concerns. For 2023, it comes down to the “steady ability to produce what is sold, with no major changes in the marketplace,” Garneau noted. 2024’s top concern: “Economic conditions overall.”
Caperton also cited concerns over a possible economic slowdown. “Capital is tight, and spending is down.” That said, “I think both will open up more by the end of 2023,” he added.
https://www.woodworkingnetwork.com/management/fdmc-300/furniture-industry-moves-forward
 Everchem Updates Archive
 Sign Up for Email Updates


