The Urethane Blog
February 28, 2023
Evonik is moving its North America headquarters to Piscataway, New Jersey

MOSCOW (MRC) — Evonik, one of the world’s leading specialty chemicals companies, is moving its North America headquarters from Parsippany, N.J., to Piscataway, N.J., said the company.
The official address change took effect on January 1, 2023. The Parsippany location will be closed with the end of its lease later this year.
The relocation is part of Evonik’s larger site rationalization plan to ensure efficient operations and future growth in North America. Evonik has embraced a hybrid work model in the region to consolidate office space, enhance employee engagement, and increase employer attractiveness.
“For Evonik, moving towards a hybrid workplace is a strategic opportunity to attract and retain diverse talent and to enable an efficient real estate footprint,” says Bonnie Tully, president North America region. “We want to foster conditions for growth, creativity, and innovation.”
The new Piscataway headquarters, located approximately 35 miles southwest of New York City, consists of administrative offices, laboratories for Research & Development, and the largest Collaboration Hub in the North America region – designed to support a hybrid and creative work environment for more than 160 employees. Evonik has recently opened similar hubs at its sites in Richmond, Va., and Mobile, Ala., and will eventually feature them at six locations in North America.
The uniquely designed spaces offer open areas and meeting rooms for employees to work onsite without needing individual offices. Employees have access to collaboration technology like digital whiteboards and tools for video conferencing. “The Collaboration Hubs promote interactions across our business lines and functions,” says Tully. “It will shape the future of work at Evonik and contribute to our culture of innovation.”
North America is an essential growth market for Evonik. The region contributed roughly a quarter (23%) to Evonik’s annual sales in 2021, making it the second-largest revenue source after Europe (EMEA). By 2030, Evonik aims to invest more than USD3 billion in Next Generation Solutions — products with superior sustainability benefits. Evonik will invest an additional USD700 million in Next Generation Technologies to optimize production processes and infrastructure and avoid CO2 emissions.
We remind, Evonik is pooling its expertise and integrating its alkoxides business into the Catalysts Business Line. The extensive portfolio of heterogeneous catalysts is thus now complemented by homogeneous catalysts. An international network of production sites and the highly experienced alkoxides team will additionally strengthen the Catalysts Business Line, one of Evonik’s growth areas, from January 2023.
February 28, 2023
Lithium Industry Reeling After China Shutters 10% Of Global Supply
by Tyler Durden
Monday, Feb 27, 2023 – 06:00 PM
That’s a nice little EV industry you got over there in the US, it’s be a shame if suddenly it found itself without the most important commodity.
That’s one way to interpret what just happened in China; another – a less cynical – is the way Bloomberg described it, namely that China’s lithium industry itself is reeling as its top production hub – responsible for around a 10th of the world’s supply – faces sweeping closures amid a government probe of environmental infringements.
The crackdown in Yichun, Jiangxi province, also known as the country’s “Lithium capital” follows a local lithium frenzy over the past year as miners raced to feed rampant demand for the battery material — and to benefit from record global prices. Now, they’re grappling with a close-up inspection by environment officials sent from Beijing.
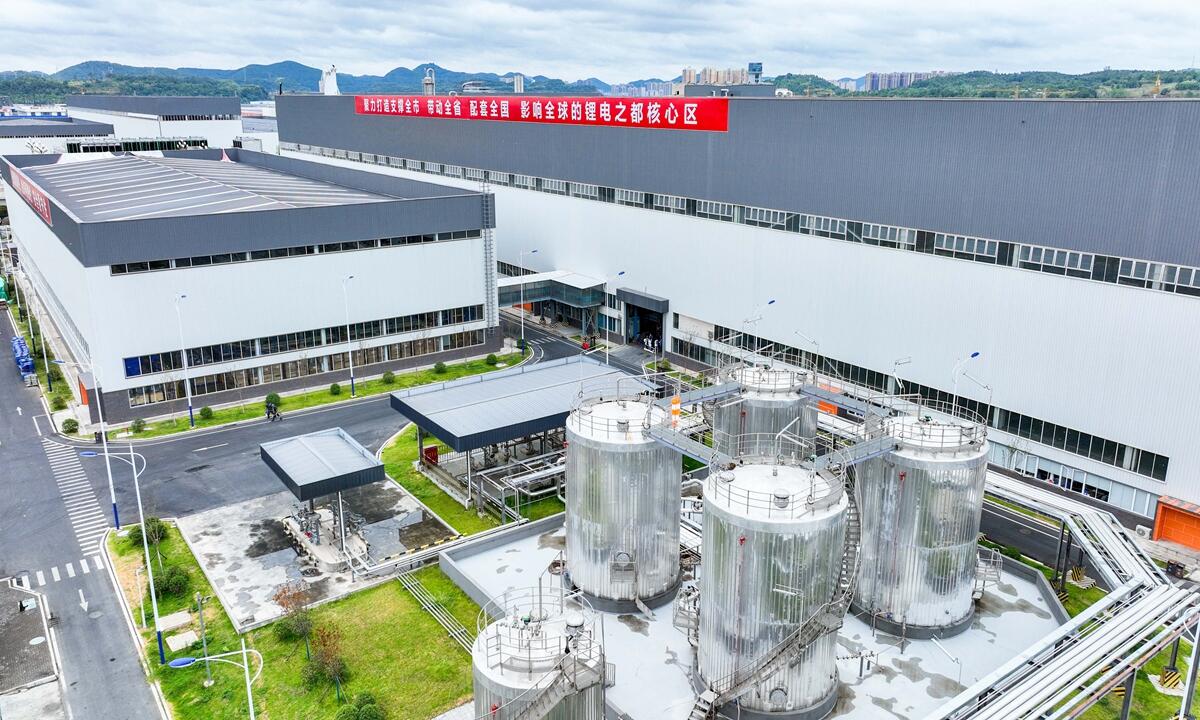
According to Yicai newspaper, ore-processing operations in Yichun have been ordered to stop as investigators probe alleged violations at lithium mines. That, Bloomberg notes, threatens somewhere between 8% and 13% of global supply, according to various analyst estimates, although it’s unclear for how long the immediate shutdowns will last.
The sudden probe injects a big dose of uncertainty into a lithium market that has seen prices drop, bringing some relief to EV manufacturers, as more global output emerges. Jiangxi province was expected to be a big source of extra supply, from a lithium-bearing mineral known as lepidolite.
“This supervision may mean that the inspection and control over lepidolite mining in China will be more stringent in the future,” said Susan Zou, analyst at Rystad Energy. Companies with operations in Yichun include major battery manufacturers Contemporary Amperex Technology Co. and Gotion High-Tech Co., whose shares both fell more than 1% on Monday.
Due to the ongoing probe, all lepidolite mining in Yichun aside from those by a state-owned company have been suspended, but refineries are still operational, Daiwa analysts Dennis Ip and Leo Ho said.
Global lithium prices soared to a record high last year as demand from China’s booming electric-vehicle industry outstripped production. And, as so often happens in commodities, where the cure to high prices is more supply, leading to lower prices, this high-profit, high-demand environment has encouraged miners to skirt regulations.
Some companies had already been targeted for infringements, including incidents of pollution, over the past year. This is a much wider crackdown, and involves officials from central government departments including the Ministry of Natural Resources.
Yucai added that Beijing will mainly look at violations at lithium mines and seek to guide the “healthy development” of the industry; they will largely target those mining without permits or with expired licenses.
Curiously, a recent Goldman report found that the Chinese car industry’s demand for lithium has fallen by more than half in recent months, a dramatic reversal that will drive a further slump in the market. Meanwhile, Chinese prices have dropped more than 30% from last year’s peak.
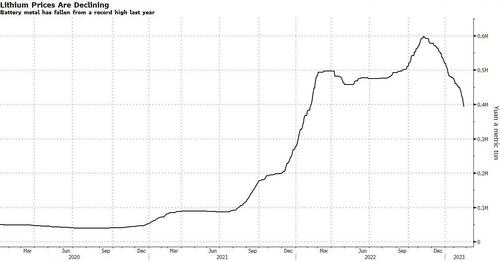
According to calculations form Citic Securities analyst Bai Junfei, a month-long mining halt in Yichun would reduce lithium output by an amount equivalent to around 13% of the world’s total. Rystad Energy, a consultancy, estimated the amount at 8%.
“At present, the market speculation is that the probe may stop after the two sessions in China next month,” Rystad’s Zou said, referring to the annual parliamentary meetings due early March.
https://www.zerohedge.com/markets/lithium-industry-reeling-after-china-shutters-10-global-supply
February 27, 2023
US Pending Home Sales Explode Higher In January
by Tyler Durden
Monday, Feb 27, 2023 – 10:07 AM
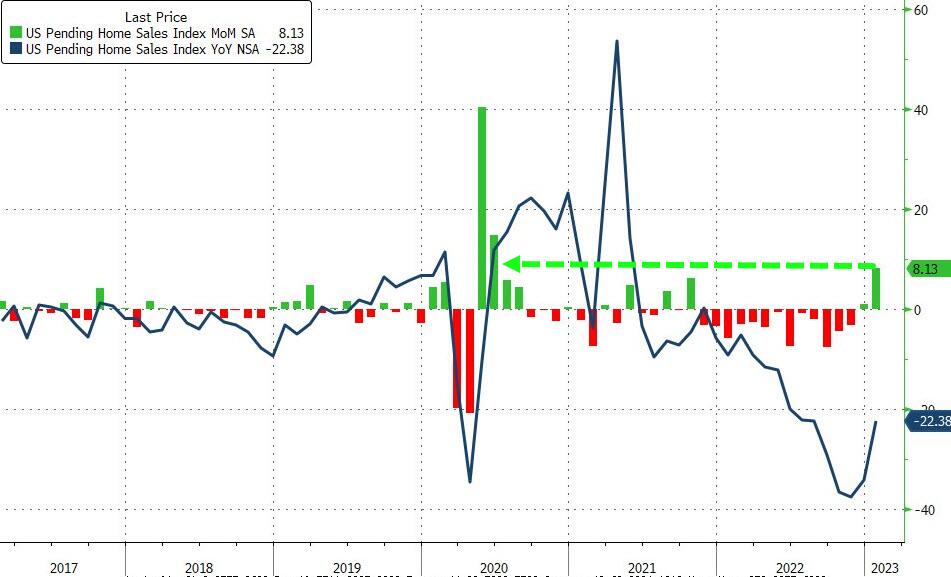
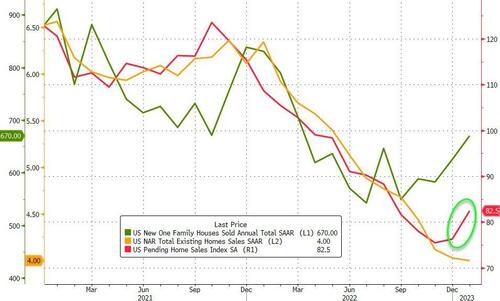
Existing home sales plunged, new home sales surged… so today’s pending home sales print will be the decider over what level of bloodbathery is really occurring in the US housing market. After a surprise jump in December (after 6 straight declining months), analysts expected a modest 1.0% MoM jump in pending home sales in January but were blown away by an 8.1% MoM explosion in sales (though Dec was revised down from +2.5% to +1.1%)….

Source: Bloomberg
“Home sales activity looks to be bottoming out in the first quarter of this year, before incremental improvements will occur,” Lawrence Yun, NAR’s chief economist, said in a statement.
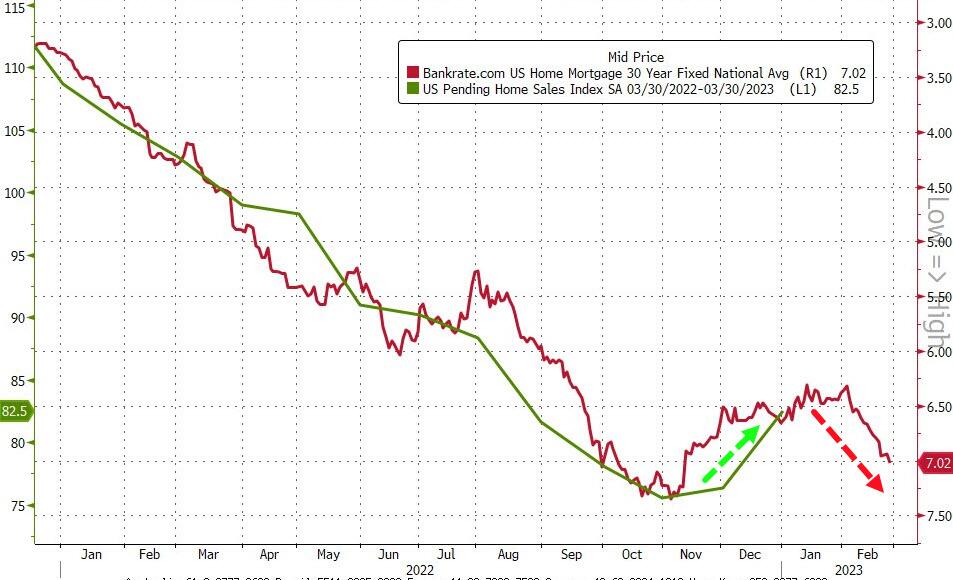
That is the biggest MoM jump since June 2020, pushing the index to its highest since August 2022…
Source: Bloomberg
“Buyers responded to better affordability from falling mortgage rates in December and January,” said NAR Chief Economist Lawrence Yun.
Sorry Larry… that’s history!
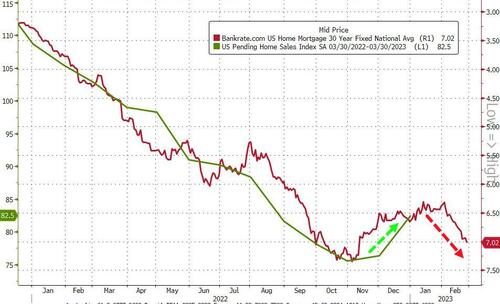
This surge in pending sales is unlikely to continue since mortgage rates have surged since the period these sales were ‘pending’ for.
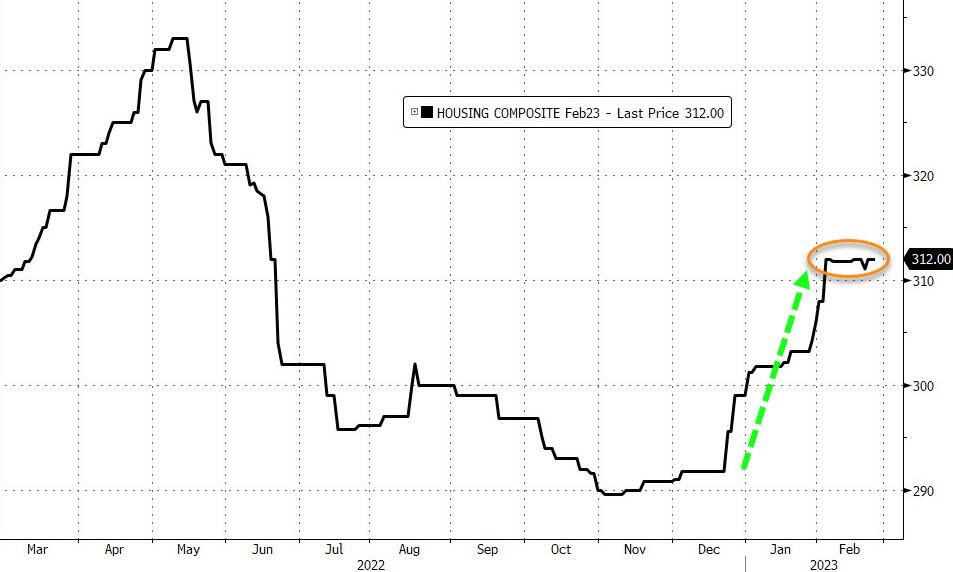
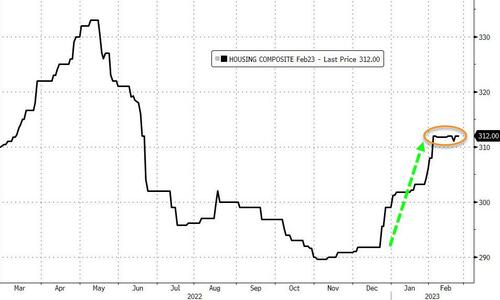
We also note that while housing futures have surged in recent months, the last week or two have seen them stagnate as mortgage rates soared…
Signings rose in all four regions in the month, led by a more than 10% gain in the West.
“An extra bump occurred in the West region because of lower home prices, while gains in the South were due to stronger job growth in that region,” Yun said.
Even with the surge at the start of the year, contract signings were still down 22.4% from January 2022 on an unadjusted basis.
https://www.zerohedge.com/markets/us-pending-home-sales-explode-higher-january
February 27, 2023
BASF SE (BASFY) Q4 2022 Earnings Call Transcript
Feb. 24, 2023 11:26 AM ETBASF SE (BASFY), BFFAF

BASF SE (OTCQX:BASFY) Q4 2022 Earnings Conference Call February 23, 2023 2:00 AM ET
Company Participants
Stefanie Wettberg – SVP, IR
Martin Brudermuller – Chairman & CEO
Hans-Ulrich Engel – Supervisory Board Member
Martin Brudermuller
Good morning, ladies and gentlemen. Hans Engel and I would like to welcome you to our virtual conference for analysts and investors. Exactly 1 year ago, Russia invaded Ukraine. Since then, war has been raging in the middle of Europe. We condemn Russia’s attack. For the Ukrainian people, it is a catastrophe. And the past year has taught us all a harsh lesson. Peace and economic stability must never be taken for granted.
The consequences for the global economy have been tremendous. 2022 was marked by great uncertainties, rising energy prices, inflation and concerns about the widespread economic distortions. On January 17, BASF released preliminary figures for the full year 2022. Today, Hans and I will first provide you with further details regarding our business development in Q4 and the full year 2022. Subsequently, I will present the decisive actions we are taking to strengthen our competitiveness in Europe and particularly in Germany.
Let’s start with the challenging macroeconomic environment. Over the course of 2022, the global macroeconomic environment has deteriorated significantly. There are currently no signals of substantial improvement in the short term. Russia’s war against Ukraine, high inflation and the sharp increase in energy prices led to a slowdown in consumer demand, particularly in Europe. To combat inflation, Central Banks raised interest rates considerably, which further dampened consumer spending. Demand in our consumer industries softened in the course of 2022, with 2 exceptions.
According to the current data, global automotive production reached 82 million units in 2022 and thus increased by 6% compared with the very low level of previous year. Supply shortages, particularly for the semiconductors have gradually eased. For 2023, we expect a slight increase to around 84 million units. Global agriculture production also continued to grow moderately in the course of 2022. However, overall production growth was lower than in 2021, partially due to the normalization of growth rates after higher-than-average growth in 2021. In addition, production growth was impacted by longer spells of trough in several regions as well as production disruptions in Ukraine as a result of the war.
Let’s now look at chemical production by region. Full year growth is shown on the middle bar. Based on currently available data, global chemical production grew by only 2.2% in 2022. While the markets in China and North America grew, chemical production declined massively in Europe, and also fell in Asia, excluding China. Chemical production growth in China slowed slightly in 2022 compared with a strong baseline in 2021. This was mainly due to lower demand as a result of COVID-related lockdowns. In North America, chemical production growth increased compared with the previous year. In 2021, growth had been negatively impacted by the freeze in the first quarter and the hurricanes in summer and autumn. Chemical production in Europe declined substantially. Lower demand and higher energy prices led to shutdowns of selected production capacities, especially in the second half of 2022. This was particularly apparent in Germany, where chemical production declined by around 12% in 2022.
Lower demand and higher energy prices were also the main reasons for the decline in chemical production in Asia, excluding China. As the following slides, we’ll mainly focus on BASF’s business performance in Q4 2022, I will also briefly comment on chemical production in the last quarter of the year.
In Q4 2022, global chemical production increased by only 1%, a considerable increase, which was surprising in the overall weak environment was only seen in China. This was particularly driven by a base effect as chemical production in China had been negatively impacted by electricity cuts in the fourth quarter of 2021. All other regions recorded a decline in chemical production, which was most pronounced in Europe.
Moving on to BASF. In Q4 2022, our sales decreased by 2% to €19.3 billion, mainly on account of lower volumes. Sales volumes declined by 15%, with the exception of Agricultural Solutions, all segments recorded lower volumes. Sales prices increased by 9%. All segments were able to increase prices, except for chemicals, where prices declined on account of weak demand. Portfolio effects of minus 1% were mainly caused by the sale of the Kaolin Minerals business, which had been part of the Performance Chemicals division until the divesture. Currency effects of plus 4.5% had a positive impact on sales and were primarily related to the U.S. dollar.
Let’s now move on to our earnings development by segment in Q4 2022 compared with the strong prior year quarter. The overall decline in EBIT before special items resulted largely from considerably lower contributions from the Chemicals and Materials segments. In Q4 2022, these 2 segments contributed only €65 million to BASF’s group EBIT before special items compared with €933 million in the prior year quarter. This was mainly due to lower volumes and margins on the back of low demand in high energy and raw material prices. In total, earnings in BASF’s for downstream segments improved by €229 million and amounted to €393 million.
Hans-Ulrich Engel
Thank you, Martin. Good morning, ladies and gentlemen. In the following, I will provide you with further details of BASF Group’s financial figures in the fourth quarter of 2022 compared with the prior year quarter. I will start with EBITDA before special items, which decreased by 36% and amounted to €1.4 billion. EBITDA amounted to around €1.4 billion to a decrease of €862 million. At €373 million, EBIT before special items declined by 70%. Special items in EBIT amounted to minus €254 million compared with plus €1 million in the fourth quarter of 2021. The special items were mainly related to noncash effective impairments on plans in Ludwigshafen.
EBIT decreased by 90% to €119 million in Q4 2022. Income from nonintegral companies accounted for using the equity method amounted to minus €4.7 billion compared with plus €112 million in Q4 2021. The strong decline was driven by noncash effective impairments on the shareholdings in Wintershall Dea AG in the amount of about €4.7 billion in Q4 2022. These impairments resulted in particular from the deconsolidation of the Russian exploration and production activities of Wintershall Dea due to the loss of actual influence and economic expropriation. The remaining value of the Russian participations of Wintershall Dea declined significantly and further write-downs were made on the European gas transportation business.
Let’s now look at BASF’s operational earnings development from a regional perspective. Our competitiveness in Europe and particularly in Germany, has declined. In 2015, Germany, Europe, excluding Germany and the other regions each contributed around 1/3 to BASF Group’s EBIT before special items. In the strong business year 2021, Europe, including Germany, contributed only 1/3, while the other regions contributed 2/3. After the strongest ever first half, earnings softened in the further course of 2022 and we saw a particular deterioration in our German operations. In the second half of 2022, the contribution of Germany was even negative and we ended the year with an overall year before special items contribution of minus €126 million. This shows how important a balanced regional footprint is for our risk management. We will, therefore, continue to strengthen our business growth outside of Europe while adapting our business in our home region to reflect the changed framework conditions.
One explanation for the earnings decline in Europe are the elevated energy costs in the region. In 2022, our operational earnings were burdened by additional energy cost of €3.2 billion globally. Europe accounted for around 84% or €2.7 billion of this increase which mostly impacted our Verbund site and Ludwigshafen. Higher natural gas costs accounted for 69% or €2.2 billion of the overall increase in energy costs. And again, the main impact was on Europe and on Ludwigshafen. In 2022, we reduced our natural gas consumption by around 1/3 in Europe. This was primarily due to lower production volumes. Nevertheless, as mentioned before, we incurred €2 billion in additional cost for natural gas in Europe alone compared with 2021.
Martin Brudermuller
We anticipate only moderate growth in the majority of our customer industries in 2023. Our forecast assumes that the war in Ukraine will continue but not escalate further. Even so, the further developments of the war and its effects on economic growth are still subject to a high degree of uncertainty. In addition, we are assuming that an acute gas shortage with regulatory cuts to energy-intensive industries in Europe will not materialize. We expect that China’s departure from its Zero COVID strategy will have a positive impact on demand and will stimulate growth globally.
Based on these assumptions, we expect the global economy to grow by only 1.6% in 2023. We forecast growth of 1.8% for global industrial production, while global chemical production is likely to expand by 2% in 2023. Our planning assumes an average exchange ratio of USD 1.05 per euro and an average oil price of USD 90 for a barrel of Brent crude. We anticipate elevated and very volatile gas prices in Europe. In few of these factors, we forecast BASF Group to generate sales of between €84 billion and €87 billion in 2023. EBIT before special items is expected to decline to between €4.8 billion and €5.4 billion.
We expect a weak first half of 2023, followed by an improved earnings environment in the second half of the year due to recovery effects, especially in China. Based on the weaker earnings performance and slightly higher cost of capital base is forecast for BASF Group in 2023, we anticipate a ROCE of between 7.2% and 8%. We expect CO2 emissions of between 18.1 million metric tons and 19.1 million metric tons as a result of moderate growth in production and slightly higher capacity utilization at emission-intensive plants.
We will now move on to the measures to increase the competitiveness and profitability of BASF Group. I will focus on 2 areas in the second part of today’s presentation. We will begin with the cost savings program focusing on Europe that we announced in October. This will be followed by a longer section on the adaption of our Verbund structures in Ludwigshafen. Europe’s competitiveness is increasingly suffering from overregulation, slow and bureaucratic permitting processes and high costs for most of the production input factors. This has resulted in many years of low market growth. High energy prices are putting an additional burden on our profitability and competitiveness in Europe. Our cost savings program, therefore, focuses on rightsizing our cost structures in Europe and particularly in Germany to reflect these circumstances.
We will implement the program from 2023 to 2024. On completion, the program is expected to generate annual savings of more than €500 million in non-production areas. What do we mean with non-production areas? These include service, operating and research and development divisions as well as the corporate center. Roughly half of the cost savings are expected to be realized at the Ludwigshafen site. The measure under the program include the consistent bundling of services and hubs, simplifying structures in divisional management, the rightsizing of business services as well as increasing the efficiency in R&D activities. Globally, the measures are estimated to have a net effect on around 2,600 positions. This includes the creation of new positions, in particular in the hubs and program costs are expected to amount to around €400 million. This will cover training and qualification measures, relocation costs and severance packages. Employee representatives in the relevant bodies have been and will continue to be involved regarding the various measures.
Let’s now move from the non-production areas to production at our largest site worldwide in Ludwigshafen. This is a schematic picture of the Ludwigshafen and Verbund site today in terms of inputs and outputs. We require vast amounts of natural gas as an energy source to power our plants and as a feedstock for our products. Today, renewable energy and renewable feedstocks still play a relatively small role. As outputs, we currently sell significant volumes of several base chemicals to the market. However, we mainly use base chemicals within the Verbund to produce a vast range of around 8,000 downstream products for European and global customers. And as a collateral output, this site emits about 7 million metric tons of carbon dioxide per year. Based on 2021 figures, the Ludwigshafen site accounts for about 4% of Germany’s natural gas consumption. In few of the large amount of gas we consume, it comes as no surprise that our competitiveness in Ludwigshafen suffers in times of elevated energy prices.
European gas prices skyrocketed to unseen levels in August. Since then, prices have declined, but we expect them to stay considerably higher in the long run compared to what they were over the past several years. Furthermore, lower market growth in Europe has negatively impacted supply and demand dynamics in several value chains. We are, therefore, undertaking structural measures to improve our competitiveness over the long term in addition to the cost savings program we have initiated. During the past months, we have carried out a thorough analysis of our Verbund structures in Ludwigshafen. By assessing our asset base in detail, we reached a deep understanding of how to ensure the continuity of profitable business while making necessary adoptions.
Let me now highlight the major changes we will be implementing. Let’s start by looking at the ammonia value chain. Ammonia is the largest consumer of natural gas as a raw material in Ludwigshafen. Currently, we operate 2 ammonia plants at the site, which you see in a simplified diagram on the left side of the slide. Ammonia is an important input factor for caprolactam and with that for polyamide-6, adipic acid as well as nitrogen fertilizers. Caprolactam, in particular, has seen tremendous buildup of capacities in recent years, especially in China. As a result, European exports to Asia were already under pressure before the sharp increase in Europe’s energy prices. To reduce our exposure to the market, we intend to close our caprolactam production in Ludwigshafen. BASF caprolactam in [indiscernible] is sufficient to serve captive and merchant market demand in Europe going forward.
By closing the caprolactam plant in Ludwigshafen, we will significantly reduce captive demand for the precursor ammonia. And in turn, this allows us to close 1 of the 2 ammonia plants as well as associated fertilizer facilities. At the same time, we will use the changes as an opportunity to optimize our polyamide 6 production network and further strengthen this important business for BASF Group. High value-added products such as standard and specialty amines and the AdBlue business, for example, will be unaffected and will remain competitive. They will be supplied via the second ammonia plant at the Ludwigshafen site.
Let us now move on to the next value chain, adipic acid. As 1 of the main precursors of polyamide 6.6, adipic acid is an essential part of our Engineering Plastics business. In addition, to serving captive demand, we sell production volumes to the merchant market. Over recent years, however, margins in this part of the business have been steadily eroded due to overcapacities in Asia and lower-than-anticipated domestic market growth. This situation became even worse with the sharp increase in European energy prices. In response to this changed market environment, we will reduce our adipic acid production capacity in Ludwigshafen and will close the precursor plant for cyclohexanol and cyclohexanone as well as the production of soda ash. With these measures, we will reduce our merchant market exposure while improving our overall earnings. Adipic acid production at our joint venture with Domo in Chalampe in France will remain unchanged and has sufficient capacity to supply our business in Europe. We will also continue to operate our polyamide 6.6 production plants in Ludwigshafen.
The certain value chain I want to address is the TDI production complex in Ludwigshafen. Over the past years, both MDI and TDI have gone through significant demand and profitability cycles. Overall, market demand for MDI is healthy as expected and continues to grow. Demand for TDI for however, did not grow as expected and has been especially weak in Europe, Middle East and Africa. We do not expect this to change. As a result, our TDI complex in Ludwigshafen has been underutilized and has not met our expectations in terms of economic performance. This situation has further worsened with sharply increasing energy and utility costs. We have, therefore, decided to close our TDI plant and the precursor plants for DNT and TDA. We remain fully committed to our European customers, and we’ll continue to serve them via our global production network with our existing TDI plants in Geismar, Louisiana, Yeosu, South Korea and Shanghai, China.
As I mentioned earlier, we thoroughly analyzed our asset base in Ludwigshafen. This included the gas intensive acetylene value chain as well as olefins from our 2 steam crackers in Ludwigshafen. While we identified some optimization potential in these value chains, our analysis shows that these assets will remain competitive in the long term, even under the changed framework conditions. In total, 10% the replacement — asset replacement value at the site will be affected by the measures. This will likely affect around 700 positions in production. However, we are very confident that we will find suitable positions for most of the affected employees since there are vacancies in production and many colleagues will retire in the next few years.
The measures will be implemented stepwise by the end of 2026 and are expected to reduce fixed costs by more than €200 million per year. These structural changes will also lead to a significant reduction in power and natural gas demand at the Ludwigshafen site. Consequently, CO2 emissions in Ludwigshafen will be reduced by around 0.9 million metric tons per year. This corresponds to a reduction of around 4% in our global CO2 emissions.
Since the start of the Russian war against Ukraine, we had analyzed in depth what factors influence the gas consumption of our Verbund, both positively and negatively. When uncertainties regarding gas supply first arose, we mentioned 50% at a minimum for operating the Ludwigshafen for Verbund site. Now we are able to continue operations even if the gas supply were to drop as far as 30% of our average consumption in 2021. This is thanks to optimization measures that including using the byproduct ethane from our steam crackers to feed our acetylene plant and the recommissioning of sections in the synthesis gas plant that is independent from natural gas.
We are now executing further projects that will reduce gas consumption in Ludwigshafen even further. By the end of this year, we will convert 2 of our 4 natural gas turbines in our combined heat and power plants to allow operation with either natural gas or fuel oil. Gas allocation would nevertheless force us to shut down many production plants at the site, but under optimal conditions and this natural gas consumers taken offline, we would, however, still be able to run the Ludwigshafen site at a supply rate of around 10% of our average gas consumption in 2021. Thanks to a possible partial conversion to fuel oil, we will thus be able to avoid a complete shutdown.
I congratulate the BASF team for its creativity and dedication in developing the required solutions during the last 12 months. Reducing the demand for natural gas is 1 of the elements in the transformation of the Ludwigshafen site. We want to develop Ludwigshafen into the leading low-emission chemical production site in Europe and are initiating further changes needed to achieve this. The green arrows indicate the time lines for preparations and investments while the extended arrows indicate better transformation along the particular levers has more or less ended steady state. We are exploring how we can best accelerate the transformation and how we can move forward most efficiently with regard to abatement costs.
We are making good progress. As part of the gray to green lever, we will secure further supplies of renewable energy in line with our Make & Buy strategy. With regard to the electrification of the Ludwigshafen site, we are taking steps to establish the platforms and infrastructure that we need to supply the site with renewable electricity and hydrogen. We are planning the use of heat pumps and cleaner ways of generating steam. In a transition phase, we are also looking into possibilities for using carbon capture and storage for hard-to-abate CO2 streams before moving to carbon capture and utilization. In addition, we will employ new CO2-free technologies such as water electrolysis to produce hydrogen. And finally, we plan to use the flexible entry options offered by our Verbund to switch from fossil to circular and renewable raw materials.
I’m concluding my remarks, and I want to reemphasize what BASF stands for. You can rely on BASF to continue to deliver what is known and where we are — what is known from us and what we are respected for. Connectedness lies at the core of BASF and is exemplified by our Verbund. The flexibility of our Verbund clearly demonstrated by the measures we have taken, and we will continue to take to reduce our natural gas demand. We will build on the benefit it offers both in Ludwigshafen and at other Verbund sites worldwide. Our global footprint with production assets close to our customers in all regions, proves to be the right setup particularly in a world that is becoming increasingly multipolar.
With our ongoing investments in China and the United States, we continue to improve our regional footprint. We are expanding our global presence in growing market segments, for example, in the battery materials value chain. Our transformation towards Net Zero will enable us to provide our customers with a complete portfolio of products that have reduced or even net zero carbon footprint. This will differentiate us from our competitors. Here, too, the Verbund plays an important role, and we will be — and will be supported by our powerful global R&D teams. All of these things would not be possible without our employees. And I’m therefore proud that we can count on such a great team at BASF, and I thank the team for its commitment in these challenging times. Thus, our shareholders can rely on BASF for value generation over the long term. Thank you.
Stefanie Wettberg
There’s a bit more specific questions on the closures in Ludwigshafen. It’s from Markus Mayer, Baader-Helvea. Why does the closure of plants in Ludwigshafen not trigger further impairments? Do you not need to write down the TDI plant? Is the TDI pant closure more linked to the energy situation or to production issues the plant had?
Martin Brudermuller
I mean, first of all, let me say some of the plants I have mentioned, adipic acid, caprolactam are part of BASF’s structure for a long time. These are rather old plants that have been totally depreciated. So from that point of you don’t see any write-downs or impairments coming with that. I think I mentioned also that they have been under pressure also from market points in terms of utilization. And now really, they get another hit by the energy prices. And this is, I think, while we also have a good opportunity to now, let’s say, restructure 1 of the oldest parts, I think, in the Ludwigshafen part.
The TDI plant is certainly a more new one. And I think I mentioned that also here, I think — the most disappointing part is actually the market development in Europe, which is significantly below what we have expected. It grows below 1%, most probably going forward in the next 10 years. If you look on to the supply balance — supply-demand balance on a global point of view, we have a very low utilization on the global level for all the plants. It is also a product which is not so difficult to transport much easier than actually MDI. So that is — you can run that as a global business. And this is why actually all the assets all over the world can participate in regional markets. And I think this is one of the major aspects also where we see not the scenario that we can really fully load these plants economically in terms of a market development.
When it comes to the depreciation part, I quickly hand over to Hans because that is the only plant that has a little bit less history in BASF and the other ones.
Hans-Ulrich Engel
Yes. And Markus, when you look closely at the Q4 P&L, you see that there is a €0.25 billion in special items there. The vast majority of that are write-down/impairments on plants in Ludwigshafen resulting from the high gas and energy cost or in other words, part of the closures that we are now announcing. And I’d say digesting that in the quarter is a significant number.
Stefanie Wettberg
Okay. So we continue another question related to that topic area. Mubasher Chaudhry from Citi. With regard to the various shutdowns announced, is there any option to bring any of these plants back online? Should the demand picture improve in the medium term?
Martin Brudermuller
No. I think this is more or less excluded because, first of all, when you start to shut down these plants and you really want to reduce the fixed cost. You have also to solve the teams and have really to get the fixed cost off and also not stay with remnant costs or holding a team for such a moment, then you don’t gain anything. We will then clean up the plants, and we will really shut them down. We will not demolish everything on the right on the spot. We don’t need the space in Ludwigshafen. We will then do that or use it or demolish it when we need a certain phases also for growth again. But I think in order to really tap into this roughly €200 million of fixed cost reduction, you really also have to eliminate the structures.
I would also say, once we have started to then bring down an ammonia plant, which is branching out is a very important raw material also, you adapt a lot of service, utility in precursor plants than to the new scenario, you certainly also reduce costs in these plants if they have lower capacities. So if you do that in a way that you actually say, more and a most appalling thing than you do not get the cost reduction. So for that reason, we decided to do that for good.
Stefanie Wettberg
Now there’s a question from Georgina Fraser, Goldman Sachs. It’s a combination of outlook and the measures announced for Ludwigshafen. What are your midterm energy cost assumptions for Europe? What was the scenario under which the site closure decisions have or the plant closure decisions have been taken?
Hans-Ulrich Engel
Georgina, what we’ve done is we worked with the overall assumption that the very competitive, not to say price advantaged gas deliveries from Russia will not play a role in Europe, and in particular, in Northwestern Europe going forward. What does that lead to? That leads to the question, what will be price setting for Northwestern Europe going forward? We think that there is a high likelihood that the price for Northwestern Europe for natural gas and then resulting from that to a certain extent also for power will be set on the basis of LNG imports. What are the key sources for LNG imports, as we all know, that is the U.S. and also Qatar.
We think there is a high likelihood that the base for price will be Henry Hub price plus then the cost of the LNG supply chain. In other words, from the liquefaction transportation to gasification. That cost is somewhere in the order of magnitude of $5 to $6 per million BTU. So Henry Hub plus supply chain costs for LNG is what we think will form the basis for prices going forward. We also think it will take probably about 2 years to get to this situation. This is with all the problems in the entire system currently, probably the time to establish a full LNG supply chain, the situation in Germany, where thankfully, the first FSRUs. So the floating terminals are now up and running, but to create and establish an LNG import structure will take a bit of time. But in the end, these are the assumptions that we used. In other words, with respect to natural gas and also power situation where prices should be higher in Europe than they were in the past.
Martin Brudermuller
And maybe to add 1 part on that because, I mean, competitiveness is a relative thing and not an absolute thing. And if you now hear politicians talking, okay, energy price is getting low now. So — or the danger, everything is off that of the political agenda or the society feel safe. But I think if you actually take the current prices of roughly €50 per megawatt hour you have today and you compare it with the low number you have in the annually up in the moment, you have actually a factor of 6 in between Europe and the U.S. and that is quite significant if you are in the energy-intensive business.
So we have — and that’s what I said this earlier when I got the question of Tim whether there’s more to come. I think we have a robust scenario with different scenarios where we actually back tested that situation. And I can only warn that this is not a topic that is quickly off. I mean we have really to look into the whole value chains in Europe. It’s not only about ours that we have to bring the material still competitively to our customers. But also our customers throughout the value chain, they have to take care about their competitiveness that they keep their market share that they keep their export businesses. If they would actually also fail, then you will see a further softening of the demand in the long run, which makes it difficult to keep the whole ecosystem of Europe, which is 1 of the very last remaining or the only ones where you have full value chains and interlinked value chain.
So I would say we will do our share, but I hope also our customers are bold enough to restructure and take the right steps to ensure that the whole value chain stays competitive. We have talked to a lot of customers about that. but that is also what we cannot totally factor in on our own exercise. We have to do our step and the others have to do their share.
Stefanie Wettberg
Charlie Webb from Morgan Stanley has a related question, but it’s a bit broader, not only focused on BASF, is your TDI production of the cost curve at current energy prices and no longer competitive domestically? It’s hard to talk for others, but — I mean.
Martin Brudermuller
I mean, I think I mentioned it already. I mean I said that competitiveness is a relative term. And I mean if you look into the energy situation in some of the countries where other production positions are, depreciated plants, very well established plants also in their local and regional markets where the base load is then they have also a good — a better, let’s say, competitive position gain now over the recent times since Europe got in this difficult situation. So that also import material is coming into Europe. So for that reason, yes, that’s a good example where Europe, as such, I would say, has lost competitiveness.
Stefanie Wettberg
This related question to, in this case, Region North America. It’s from Sebastian Satz, Barclays. Can you elaborate to what extent BASF may be able to benefit from various government support packages for the energy transition? And specifically thinking about the U.S. Inflation Reduction Act, for example, blue ammonia, or the discussions of an industry power price in Germany?
Hans-Ulrich Engel
Yes. Thank you, Sebastian, for your question. Of course, we are looking into the incentives that come with the Inflation Reduction Act, which, by the way, is the misnomer of the year 2022, but that’s different. That is a different story. As you know, what we do as BASF, we invest in the markets where our customers are. So we are investing in North America for our North American customers. We’re investing in Europe for our European and in Asia for our Asian customers. That’s our basic philosophy. And this basic philosophy will not be changed as a result of support schemes such as, for example, the IRA. Nevertheless, we are looking into it.
There can be certain activities that clearly benefit. As you know, we have big activities in the U.S. Gulf Coast. We have a major investment in our site at Geismar, Louisiana, the new MDI plant there. You look at what we’ve just announced with respect to the 5-year CapEx plan were around about €4 billion to €4.5 billion is earmarked for North America for the next 5 years. So you see this is a significant investment that we intend to do there. And in a scenario such as, for example, carbon capture and storage, the IRA provides, I would say, highly attractive incentives and we’ll certainly look into that. But again, basic philosophy is we produce where our customers are.
Stefanie Wettberg
I think with that, you answered, there were a few more questions from Laurent Favre, Sebastian Bray on Wintershall Dea, but that is covered. So I switch back to TDI and a question from Sebastian Bray, Berenberg. There’s quite a lot of TDI capacity exiting the market as a result of changes announced, will BASF need to spend on expanding assets elsewhere to compensate for this. Will you need additional shipping capacity for TDI? Also how much soda ash capacity is being shut?
Martin Brudermuller
I mean, first of all, a clear no. No, we don’t need additional CapEx to expand capacities in other sites. So we really can use existing capacities for covering our European market position. Certainly, we have to increase logistics. This is clear, you have to organize this. You have then to establish the supply chain that you also ensure that you have enough volumes here then in Europe from the imports to be on the safe side for your customers. This is all very clear. Please understand for the competitive reasons that I’m not going to talk about capacities now also for soda ash.
Interesting to note that all questions went through Stefanie. I’ll have to research if this is standard procedure for BASF or a one time thing, but it isn’t for other companies. Editor Comments
February 24, 2023
Hong Kong Exchanges and Clearing Limited and The Stock Exchange of Hong Kong Limited
take no responsibility for the contents of this announcement, make no representation as to
its accuracy or completeness and expressly disclaim any liability whatsoever for any loss
howsoever arising from or in reliance upon the whole or any part of the contents of this
announcement.
Sinomax Group Limited
盛諾集團有限公司
(Incorporated under the laws of the Cayman Islands with limited liability)
(Stock Code: 1418)
PROFIT WARNING
This announcement is made by Sinomax Group Limited (the “Company”, together with its
subsidiaries, collectively the “Group”) pursuant to Rule 13.09(2)(a) of the Rules Governing
the Listing of Securities on The Stock Exchange of Hong Kong Limited (the “Listing Rules”)
and the Inside Information Provisions (as defined in the Listing Rules) under Part XIVA of the
Securities and Futures Ordinance (Chapter 571 of the Laws of Hong Kong).
The board of directors of the Company (the “Board”) wishes to inform the shareholders of
the Company and potential investors that, based on a preliminary review of the unaudited
consolidated management accounts of the Group for the year ended 31 December 2022
(“FY2022”) and other information currently available to the Board, the Group is expected to
record a loss after taxation for FY2022 of not less than HK$35 million as compared to a profit
after taxation for the year ended 31 December 2021 of approximately HK$31 million. This
was primarily attributable to the continual outbreak of the COVID-19 which had critically
weakened both local and global consumption market and also the sales of the Group, and the
impact of the above also resulted in higher supply chain and logistic costs of the Group.
The Company is in the process of finalising the Group’s audited consolidated financial results
for FY2022. This announcement is made based on a preliminary review of the unaudited
consolidated management accounts of the Group for FY2022 and other financial information
currently available, which are subject to finalisation and possible adjustments upon review and
audit by the Company’s auditors or audit committee. Further details of the Group’s financial
results for FY2022 will be disclosed in the annual results announcement of the Company,
which is expected to be published on 28 March 2023.
Shareholders and potential investors of the Company are advised to exercise caution
when dealing in the shares of the Company.
By order of the Board
Sinomax Group Limited
Lam Chi Fan
Chairman
Hong Kong, 10 February 2023
As at the date of this announcement, the executive Directors are Mr. Lam Chi Fan (Chairman
of the Board), Mr. Cheung Tung (President), Mr. Chen Feng, Mr. Lam Kam Cheung
(Chief Financial Officer and Company Secretary) and Ms. Lam Fei Man; and the independent
non-executive Directors are Mr. Wong Chi Keung, Professor Lam Sing Kwong Simon,
Mr. Zhang Hwo Jie and Mr. Wu Tak Lung.
https://www1.hkexnews.hk/listedco/listconews/sehk/2023/0210/2023021000667.pdf
 Everchem Updates Archive
 Sign Up for Email Updates