
The Urethane Blog
April 6, 2026
Foam prices are on the rise. What does that mean for mattresses, upholstery?
Sheila Long O’Mara //Executive Editor, Furniture Today//April 3, 2026

At A Glance
- Carpenter Co reports double-digit foam price increases and allocations
- FXI and Future Foam announce 12% to 18% price increases with supply cuts
- Manufacturers weigh surcharges amid foam cost increases
HIGH POINT – A fast-moving disruption in the global chemical supply chain is triggering sharp increases in foam costs and tightening allocations across the bedding and upholstery categories, setting the stage for higher retail prices and added pressure on an already strained home furnishings market.
Suppliers are implementing double-digit price increases – in some cases exceeding 20% – while limiting order volumes, creating a dual challenge of rising costs and constrained supply that executives say is unlike recent disruptions.
“It’s not just a North America issue; it’s a global problem,” said Michael Faus, senior vice president of Carpenter Co., the industry’s largest foam producer, noting that unlike prior disruptions such as the 2021 Texas freeze, suppliers today cannot simply source materials from other regions. “Back then, you could go outside the U.S. and bring in a spot buy. In this case, Asia, Europe and Mexico are all dealing with the same issues.”
At the center of the disruption is a shortage of propylene oxide, a critical feedstock used to produce polyols, which in turn are essential to polyurethane foam. Faus said a recent fire at a major Texas chemical plant significantly curtailed supply, creating a bottleneck that is rippling across the entire value chain.
Beyond the plant outages, executives point to geopolitical instability – including the ongoing war with Iran and tensions in the Middle East – as a key driver of rising input costs, which also impact textiles, yarn, steel and other components. Because foam chemicals are petroleum derivatives, increases in crude oil and fuel prices are directly impacting the cost of producing key chemicals like propylene oxide, polyols and isocyanates.
The impact is being felt across the entire cost structure, from raw materials to freight to plastic packaging to polyester thread. Rising fuel prices are increasing transportation costs, while higher energy prices are adding pressure at every stage of chemical production, further tightening an already constrained global supply chain.
“You can have all the TDI you need, but about 60% of the chemistry behind polyurethane depends on propylene oxide,” Faus said. “When that gets disrupted, it impacts everything.”
That constraint – combined with outages at major global chemical producers and rising input costs for energy, freight and raw materials such as benzene and natural gas – is driving multiple rounds of price increases. Carpenter implemented increases in early April and is preparing another round for May, which Faus expects to be in the double digits.
“The reality is, pricing is going up, and there’s another increase coming,” he said.
At the same time, supply remains constrained. Carpenter has implemented allocations and is working hard to manage them across its customer base. “We’re trying to keep allocations steady and consistent,” Faus said.
Carpenter isn’t alone in the price hikes or the allocations, limits on historical purchasing levels.
Suppliers have responded with multiple rounds of increases and allocation policies. FXI notified customers via letters received by Furniture Today of an 18% price increase effective mid-April alongside supply reductions, while Future Foam announced – also via emailed letters received by Furniture Today – a 12% increase with another, larger adjustment expected in early May. Vertically integrated 3Z Brands sent a similar notice to foam customers that conventional polyurethane foam would increase 22% and specialty foam products would jump 8% as of April 15.
Effects are being felt
Manufacturing executives across the industry, including a handful who would only speak on background, say the ripple effects are being felt immediately, with foam producers moving quickly to adjust pricing and control supply.
Increases, manufacturers say, are moving through the system at an unprecedented pace. Those constraints are being reinforced by force majeure declarations tied to shortages of key inputs, as chemical suppliers struggle to meet demand following the disruption in propylene oxide production.
The result is a supply chain shock that is cascading downstream – and one that manufacturers say cannot be absorbed.
For mattress and upholstery manufacturers, foam represents one of the largest component costs, leaving little room to offset increases. Several executives said retail prices on mattresses could rise by $100 or more in the near term, with overall product costs climbing meaningfully across categories.
Nick Bates, president and CEO of Spring Air International, said his company is already preparing to implement surcharges on orders to manage the volatility. “We’re looking at 12% to 18% increases now, and potentially 30% in May,” he said. “We’ll track it with a surcharge because of how fluid this is. No manufacturer is going to eat that; it’s going to show up at retail.”
At the same time, allocations are limiting manufacturers’ ability to grow production or support new business, creating additional friction at a time when demand remains soft.
While demand has softened compared with the pandemic-era surge – a factor Faus described as a “bit of a silver lining” – he emphasized that the current environment remains highly challenging, particularly as rising costs flow downstream to manufacturers and retailers already contending with weak consumer demand.
“This impacts everybody,” he said. “Most retail is struggling, and even some of the luxury segment is being affected. Now you layer on higher costs, and it puts even more pressure on the finished goods.”
Bob Naboicheck, CEO of Gold Bond, said the increases are coming at a particularly difficult moment for both manufacturers and retailers already contending with higher energy and freight costs.
“It’s a horrible time because the cost of energy is so high and chemicals are so high,” he said. “We’ll have to raise prices – probably around 8% on average – because we just can’t absorb it.”
While many executives view the increases as a necessary response to real cost pressures, others expressed skepticism about how quickly and how broadly pricing is moving higher.
“It feels opportunistic,” Bates said. “Every time something like this happens, prices go up quickly, but I’ve never seen a letter saying they’re coming back down.” He said suppliers are saying once the shortages clear pricing will stabilize.
“I’ll believe it when I see it, and I hope they remain true to their word,” he said.
Past comparisons, future expectations
Not all suppliers are reacting in the same way. Vertically integrated manufacturers with internal foam production capabilities say they are working to manage costs more deliberately.
“I believe the cost pressures are real,” said Kyle Robertson, chief operating officer of Mlily USA. “But our goal is to approach any changes thoughtfully. Because we control our foam pouring, we can take a more intentional approach rather than reacting too quickly.”
The current situation has drawn comparisons to past supply shocks, including Hurricane Katrina and the 2021 winter freeze in Texas. But executives say this disruption is more complex because it is global in scope and tied to multiple factors, including geopolitical instability, chemical plant outages and rising energy costs.
“This is about as close as it gets to Katrina, but it’s different,” Faus said. “This is more of a macro challenge.”
Looking ahead, industry leaders expect supply conditions to remain volatile in the near term. If domestic propylene oxide production resumes by early summer, Faus said conditions could begin to ease within 60 to 90 days. However, pricing pressure is expected to linger longer as elevated input costs work their way through the system.
“From a supply standpoint, we’re probably looking at 60 to 90 days of choppy waters,” Faus said. “But from a cost perspective, this will last longer than that.”
March 31, 2026
Saudi Aramco-Dow JV suspends chemical output amid regional disruptions
Mar 31, 2026, 3:45 PM ETDow Inc. (DOW) Stock, ARMCO StockBy: Rob Williams, SA News Editor
A major petrochemical facility in Saudi Arabia operated by a partnership between Saudi Aramco (ARMCO) and Dow (DOW) temporarily stopped production, underscoring how escalating tensions in the Middle East are straining industrial activity and supply chains.
Sadara Chemical Co. confirmed that operations at the complex have been paused, though it didn’t provide a timeline for restarting production, Bloomberg News reported Tuesday. The company said any resumption will depend on both domestic conditions and broader international developments.
The shutdown highlights the growing impact of the Iran conflict on energy infrastructure across the region. The Strait of Hormuz, a critical artery for global energy trade that typically carries roughly 20% of the world’s oil and liquefied natural gas, remains largely obstructed, complicating exports.
Saudi Arabia has already reduced crude output, and alternative logistics are being stretched. A pipeline network connecting eastern production hubs to ports on the Red Sea is reportedly operating at maximum capacity, providing a partial workaround for shipments.
The Sadara complex, a roughly $20 billion investment, is designed to produce about 3 million metric tons of plastics and specialty chemicals annually. Saudi Aramco has previously positioned the facility as a cornerstone of its strategy to diversify revenue by converting crude oil into higher-value products.
March 31, 2026
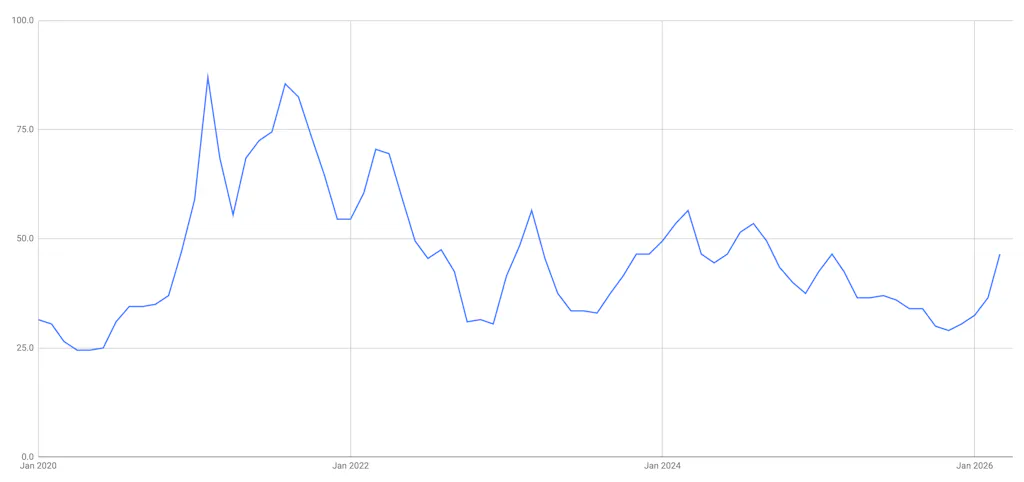
Chemical Grade Propylene is $0.465/lb in March 2026. Up 10cpp from February.
March 24, 2026
Stepan Announces Increases

https://www.stepan.com/content/stepan-dot-com/en/news-events/pricing-announcements.html
March 23, 2026
National trucking capacity is about to tighten significantly
· Sunday, March 22, 2026

The freight market momentum is building at a rapid clip. National dry van spot rates — tracked via the SONAR National Truckload Index (NTI.USA), the 7-day moving average of booked rates including fuel — have broken out to a new cycle high of $2.89 per mile. This represents the strongest level since 2022 and confirms the market’s shift toward carriers is gaining real traction.

Chart: SONAR National Truckload Rate Index (NTI.USA) GoSONAR.com
Even more telling: rates jumped $0.12 per mile in the past week alone. That’s a sharp weekly gain that underscores accelerating tightness and carrier pricing power. Spot rates have now recaptured roughly $0.50–$0.60 per mile net of fuel over recent months, climbing from the low $2.00s that defined much of 2023–2024. We’re witnessing 20–25% year-over-year recovery in key lanes and metrics, with volumes holding at multi-year highs reminiscent of late 2022.
This isn’t isolated noise — it’s driven by fundamentals. The return of industrial demand remains the core engine, with stronger manufacturing signals, flatbed activity, and overall domestic freight resilience putting sustained pressure on a shrunken truckload supply. Multi-year carrier attrition (exits, driver regulations, and structural challenges) has left capacity thin, making the market highly responsive to any demand pickup. National tender rejection rates sit stubbornly in the low-to-mid teens (around 13–14% recently), with the Midwest still leading above 18% and tightness now spreading more broadly.
Seasonal layers are piling on:
- Produce season is ramping in major growing regions.
- Construction is accelerating as weather improves.
- Gardening and home improvement demand is building.
- Beverage season is gearing up for warmer months.
These verticals compound the industrial rebound, further squeezing available trucks.
The West Coast awakening adds a powerful pull. Chinese New Year landed later this year (February 17, 2026, vs. earlier in prior cycles), prolonging the post-CNY slowdown and keeping Southern California unusually loose into early March (outbound rejections below 5%). But the rebound is hitting hard now: inbound containers are surging, outbound tenders are recovering, and rejections are set to rise meaningfully.

This creates a classic “magnet” for capacity. Long-haul carriers chase West-to-East port loads for their superior length of haul (1,500–2,000+ miles per move) versus shorter eastern runs that demand multiple loads for equivalent paid miles. As trucks reposition westward from Midwest/Southeast corridors (along I-35 and parallels) to capture higher-paying outbound freight via I-20 and I-40, interior markets face no relief — expect even tighter conditions back east. The Midwest’s industrial strength and elevated rejections mean any capacity drain will intensify pressure, not ease it.
Broader indicators align:
- Tender rejection rates remain high nationally, with seasonal builds accelerating the spread.
- Dry van spot rates continue rising on resilient volumes and persistent constraints.
- Ocean bookings are starting to recover sharply from Chinese New Year
The bottom line: Spring 2026 is igniting hotter and earlier than recent years. The $2.89 cycle high — fueled by a $0.12 weekly jump — reflects tightening capacity, resurgent industrial demand, seasonal verticals firing up, and the delayed-but-powerful post-CNY import surge creating synchronized tightness. Shippers unprepared for higher costs are under immediate strain, with routing guides tested early. Carriers positioned for West Coast outbound, industrial, and seasonal lanes are capturing the gains as capacity reallocates — but back east, conditions are set to tighten further as carriers shift their focus towards the West to East longhaul.
Monitor SONAR outbound rejections and spot rates from Southern California over the next 2–4 weeks, alongside Midwest/Southeast trends. The speed of this spread will show how broad and sustained the impact becomes.
The spring shipping season is just getting started — and it’s going to be a hot one.
 Everchem Updates Archive
 Sign Up for Email Updates