The Urethane Blog
June 14, 2021
Top 10 Liners Control 85% Of The Container-Ship Market… And They’re Not Done Yet
by Tyler DurdenMonday, Jun 14, 2021 – 02:06 PM
By Greg Miller of FreightWaves,
The extreme consolidation within the container liner sector is the kind of thing owners of tankers and bulk carriers can only dream of. The latest data from Alphaliner highlights the extent of liner consolidation, how soon the rankings will change, and how newbuilding orders will render the carrier arena even more concentrated than it already is.
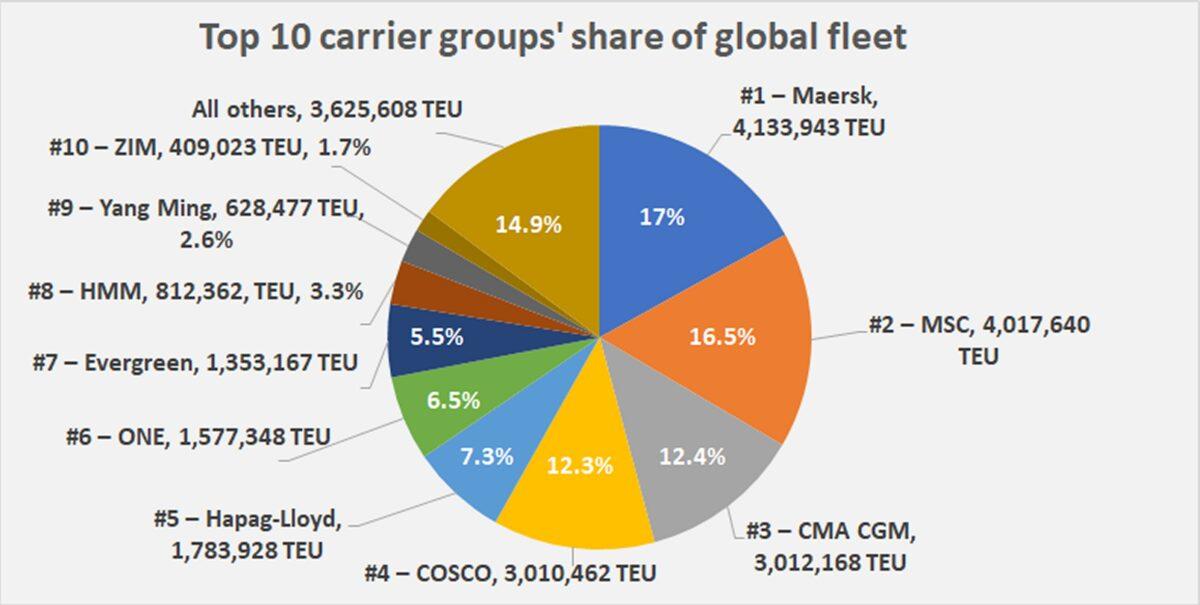
The top 10 carriers now operate 85% of global shipping capacity. Four groups — Maersk, MSC, CMA CGM and COSCO — control more than half of capacity (58%). The top seven, including Hapag-Lloyd, ONE and Evergreen, control 78%.TEU = twenty-foot equivalent unit (Chart: American Shipper based on data from Alphaliner)
This base level of fleet concentration is then greatly enhanced by the existence of three vessel-sharing alliances on the mainline East-West trades — 2M, the Ocean Alliance and THE Alliance — which count nine of the top 10 liner groups as members.
Big moves by MSC
The big mover at the top end of the liner rankings is MSC. The Switzerland-based carrier has been extremely active in the secondhand market, purchasing 49 vessels since August. It has also been busy in the charter market and very active in the newbuild market.
Including three secondhand ships it recently acquired, MSC just passed the 4 million-TEU (twenty-foot-equivalent unit) fleet milestone. Alphaliner noted that MSC’s fleet has increased 4% from the beginning of this year alone.
Including newbuilds on order, MSC effectively surpassed Maersk months ago to become the world’s largest carrier. Even in terms of ships on the water, it will take the crown soon. “The takeover could even happen before the end of the year, as MSC is to take delivery of four more 23,656-TEU ‘megamax’ newbuildings in the coming months,” said Alphaliner.
Newbuildings to hike carriers’ shares
When all newbuildings on order are delivered, MSC will pull far ahead of the pack. Although the sum of on-the-water tonnage and newbuild tonnage is not equivalent to future capacity (because there can be more orders in the interim, and ships can go on and off charter, be bought, sold, or scrapped), it does provide an indicator of future rankings.
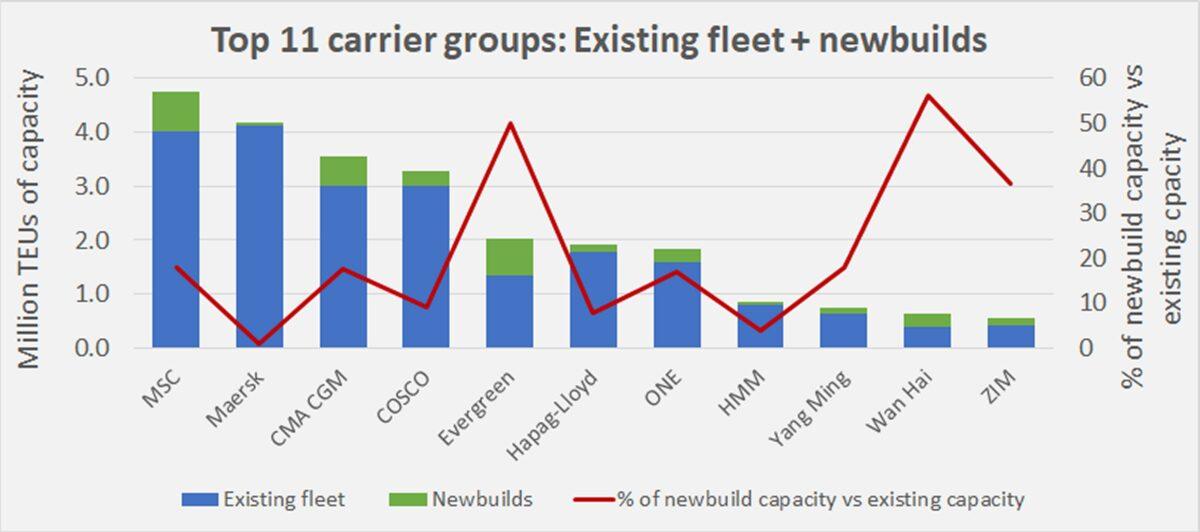
Maersk has the least on order of all the larger liner companies, with newbuild capacity of just 0.9% of on-the-water capacity. In sharp contrast, MSC’s orderbook is 18% of its operating fleet, according to Alphaliner data. The combined tonnage of existing ships and newbuilds for MSC is 4,742,400 TEUs, 14% and 34% above the same calculation for Maersk and CMA CGM, respectively.(Chart: American Shipper based on data from Alphaliner)
Beyond the “who has the biggest fleet” contest between Maersk and MSC, the broader and more important story is that the world’s top few carriers will be the overwhelming recipients of the new tonnage arriving in 2023-24 that was ordered starting in Q4 2020.
Among the other top players, the orderbook-to-fleet ratio of Wan Hai is 56%, Evergreen 50%, ZIM 37%, CMA CGM and Yang Ming 18%, ONE 17%, and COSCO 9%. These percentages will increase further as newbuilds ordered by non-operating owners are identified with their charterers over time.
A portion of this new capacity is replacement tonnage for older vessels, yet the newbuilding data implies that the top 10 liners’ capacity control will climb from its current 85% level in the direction of the 90s.
June 14, 2021
Top 10 Liners Control 85% Of The Container-Ship Market… And They’re Not Done Yet
by Tyler DurdenMonday, Jun 14, 2021 – 02:06 PM
By Greg Miller of FreightWaves,
The extreme consolidation within the container liner sector is the kind of thing owners of tankers and bulk carriers can only dream of. The latest data from Alphaliner highlights the extent of liner consolidation, how soon the rankings will change, and how newbuilding orders will render the carrier arena even more concentrated than it already is.
The top 10 carriers now operate 85% of global shipping capacity. Four groups — Maersk, MSC, CMA CGM and COSCO — control more than half of capacity (58%). The top seven, including Hapag-Lloyd, ONE and Evergreen, control 78%.TEU = twenty-foot equivalent unit (Chart: American Shipper based on data from Alphaliner)
This base level of fleet concentration is then greatly enhanced by the existence of three vessel-sharing alliances on the mainline East-West trades — 2M, the Ocean Alliance and THE Alliance — which count nine of the top 10 liner groups as members.
Big moves by MSC
The big mover at the top end of the liner rankings is MSC. The Switzerland-based carrier has been extremely active in the secondhand market, purchasing 49 vessels since August. It has also been busy in the charter market and very active in the newbuild market.
Including three secondhand ships it recently acquired, MSC just passed the 4 million-TEU (twenty-foot-equivalent unit) fleet milestone. Alphaliner noted that MSC’s fleet has increased 4% from the beginning of this year alone.
Including newbuilds on order, MSC effectively surpassed Maersk months ago to become the world’s largest carrier. Even in terms of ships on the water, it will take the crown soon. “The takeover could even happen before the end of the year, as MSC is to take delivery of four more 23,656-TEU ‘megamax’ newbuildings in the coming months,” said Alphaliner.
Newbuildings to hike carriers’ shares
When all newbuildings on order are delivered, MSC will pull far ahead of the pack. Although the sum of on-the-water tonnage and newbuild tonnage is not equivalent to future capacity (because there can be more orders in the interim, and ships can go on and off charter, be bought, sold, or scrapped), it does provide an indicator of future rankings.
Maersk has the least on order of all the larger liner companies, with newbuild capacity of just 0.9% of on-the-water capacity. In sharp contrast, MSC’s orderbook is 18% of its operating fleet, according to Alphaliner data. The combined tonnage of existing ships and newbuilds for MSC is 4,742,400 TEUs, 14% and 34% above the same calculation for Maersk and CMA CGM, respectively.(Chart: American Shipper based on data from Alphaliner)
Beyond the “who has the biggest fleet” contest between Maersk and MSC, the broader and more important story is that the world’s top few carriers will be the overwhelming recipients of the new tonnage arriving in 2023-24 that was ordered starting in Q4 2020.
Among the other top players, the orderbook-to-fleet ratio of Wan Hai is 56%, Evergreen 50%, ZIM 37%, CMA CGM and Yang Ming 18%, ONE 17%, and COSCO 9%. These percentages will increase further as newbuilds ordered by non-operating owners are identified with their charterers over time.
A portion of this new capacity is replacement tonnage for older vessels, yet the newbuilding data implies that the top 10 liners’ capacity control will climb from its current 85% level in the direction of the 90s.
June 14, 2021
Era Polymers: 35th anniversary
The Australian independent polyurethane systems house Era Polymers Pty Ltd with head office in Sydney announced that it is celebrating its 35th anniversary in 2021. According to the company, in 1986 George Papamanuel had the dream of owning his own polyurethane business. With the support of his wife Tina Papamanuel, hard work and determination, he realised that dream. George’s business started off small in his garage and he was always pinching Tina’s cooking utensils and crockery to test product.
 Tina and George Papamanuel (Source: Era Polymers)
Today, 35 years later, Era Polymers is one of the largest suppliers of prepolymers in Asia, operates six state-of-the-art manufacturing facilities (Australia, New Zealand, South Africa, and United States) and exports to over 86 countries. However, the company is still very much a family affair with Alex, Francene, Nicole and Shannon all working in the business, said Era Polymers. The company’s polyurethane solutions comprise, amongst others, one of the most diverse ranges of cast elastomer prepolymers, spray polyurethane and polyurea’s, rigid and flexible foam systems, rubber binders and timber floor coatings.
Despite this growth and achievement George Papamanuel has always remained true to the business philosophy: “Business is people doing business with people”.While Era Polymers offers a global reach, the company said it remains important that its customers get great service locally.
https://www.gupta-verlag.com/news/industry/25291/era-polymers-35th-anniversary
June 14, 2021
Era Polymers: 35th anniversary
The Australian independent polyurethane systems house Era Polymers Pty Ltd with head office in Sydney announced that it is celebrating its 35th anniversary in 2021. According to the company, in 1986 George Papamanuel had the dream of owning his own polyurethane business. With the support of his wife Tina Papamanuel, hard work and determination, he realised that dream. George’s business started off small in his garage and he was always pinching Tina’s cooking utensils and crockery to test product.
Tina and George Papamanuel (Source: Era Polymers)
Today, 35 years later, Era Polymers is one of the largest suppliers of prepolymers in Asia, operates six state-of-the-art manufacturing facilities (Australia, New Zealand, South Africa, and United States) and exports to over 86 countries. However, the company is still very much a family affair with Alex, Francene, Nicole and Shannon all working in the business, said Era Polymers. The company’s polyurethane solutions comprise, amongst others, one of the most diverse ranges of cast elastomer prepolymers, spray polyurethane and polyurea’s, rigid and flexible foam systems, rubber binders and timber floor coatings.
Despite this growth and achievement George Papamanuel has always remained true to the business philosophy: “Business is people doing business with people”.While Era Polymers offers a global reach, the company said it remains important that its customers get great service locally.
https://www.gupta-verlag.com/news/industry/25291/era-polymers-35th-anniversary
 Everchem Updates Archive
 Sign Up for Email Updates