
The Urethane Blog
August 21, 2025
Overall housing starts gain in July, affordability crisis persists
By Dakota Smith
August 20, 2025 | 9:41 am CDT

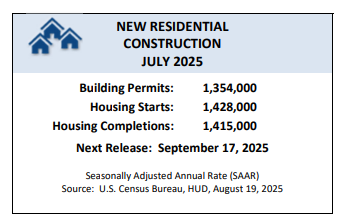
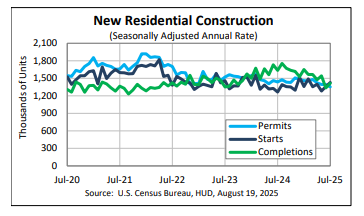
WASHINGTON, D.C. — Led by solid multifamily production, overall housing starts increased 5.2% in July to a seasonally adjusted annual rate of 1.43 million units, according to a report from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau.
Single-family housing starts posted a modest gain in July as builders continue to contend with challenging housing affordability conditions and a host of supply-side headwinds, including labor shortages, elevated construction costs and inefficient regulatory costs.
The July reading of 1.43 million starts is the number of housing units builders would begin if development kept this pace for the next 12 months. Within this overall number, single-family starts increased 2.8% to a 939,000 seasonally adjusted annual rate and are down 4.2% on a year-to-date basis. The multifamily sector, which includes apartment buildings and condos, increased 9.9% to an annualized 489,000 pace.
“Single-family production continues to operate at reduced levels due to ongoing housing affordability challenges, including persistently high mortgage rates, the skilled labor shortage and excessive regulatory costs,” said Buddy Hughes, chairman of the National Association of Home Builders (NAHB) and a home builder and developer from Lexington, N.C. “These headwinds were reflected in our latest builder survey, which indicates that affordability is the top challenge to the housing market.”
“The slowdown in single-family home building has narrowed the home building pipeline,” said NAHB Chief Economist Robert Dietz. “There are currently 621,000 single-family homes under construction, down 1% in July and 3.7% lower than a year ago. This is the lowest level since early 2021 as builders pull back on supply.”
On a regional and year-to-date basis, combined single-family and multifamily starts were 10.2% higher in the Northeast, 17.7% higher in the Midwest, 2.4% lower in the South and 0.5% lower in the West.
Overall permits decreased 2.8% to a 1.35-million-unit annualized rate in July. Single-family permits increased 0.5% to an 870,000-unit rate and are down 5.8% on a year-to-date basis. Multifamily permits decreased 8.2% to a 484,000 pace.
Looking at regional permit data on a year-to-date basis, permits were 16.6% lower in the Northeast, 9.1% higher in the Midwest, 3.4% lower in the South and 5.1% lower in the West.
August 19, 2025
Wanhua Chemical TDI plant maintenance and Fujian Phase II production announcement
PUdaily | Updated: August 18, 2025

According to Wanhua Chemical’s announcement: The company’s subsidiary, BorsodChem zrt. MDI (400,000 tonnes/year), TDI (250,000 tonnes/year) and other integrated devices and related supporting devices will be shut down for maintenance from July 23, 2025. As of August 18, the shutdown and maintenance of the above-mentioned TDI devices has been completed and normal production has resumed; The MDI device will be announced separately after the resumption of production.
According to the annual maintenance plan, the company’s TDI plant (300,000 tonnes/year) and related supporting devices in Yantai Industrial Park will be suspended for maintenance starting from August 19, 2025, and the maintenance is expected to last for about 40 days.
The company’s new TDI phase II plant (360,000 tonnes/year) in Fujian Industrial Park has recently been completed and put into operation, and has produced qualified products.
August 17, 2025
Somnigroup International Inc. (SGI) Q2 2025 Earnings Call Transcript
Aug. 07, 2025 11:31 PM ETSomnigroup International Inc. (SGI) StockSGI

Q2: 2025-08-07 Earnings Summary
EPS of $0.53 beats by $0.02
| Revenue of $1.88B (52.46% Y/Y) misses by $19.59M
Somnigroup International Inc. (NYSE:SGI) Q2 2025 Earnings Conference Call August 7, 2025 8:00 AM ET
Company Participants
Bhaskar Rao – Executive Vice President and Chief Financial Officer
Lauren Avritt – Corporate Participant
Investor Relations – Corporate Participant
Scott L. Thompson – Chairman of the Board, CEO, President & Interim CEO of Mattress Firm
Scott L. Thompson
Good morning, and thank you for joining us on our second quarter 2025 earnings call. I’m pleased to report that Somnigroup delivered another quarter of solid performance, driven by disciplined execution and progress in our combination with Mattress Firm. We continue to outperform the market, strengthen our competitive position and deliver value to all of our stakeholders.
I will now begin with some highlights from the second quarter, then turn the call over to Bhaskar to review the financial performance in more detail and discuss our 2025 guidance. After that, we’ll open the call up for Q&A.
In the second quarter of 2025, we are pleased to achieve record net sales and adjusted EBITDA. Net sales were up approximately 53% to $1.9 billion, and adjusted EBITDA was also up approximately 26% to $291 million. Adjusted EPS for the quarter was $0.53. We believe the North American bedding market was down high single digits in the quarter and the international markets in aggregate were down mid-single digits.
The quarter started soft but strengthened as we moved throughout the period. Early third quarter like-for-like trends are encouraging with indication of potential solid growth. It’s too soon to call a turn in the market we serve, but we are encouraged with what we are experiencing. We’ll know more after the third quarter.
Our first highlight of the quarter was the market outperformance of Mattress Firm. Mattress Firm reported like-for-like sales down just 1% from prior period. The team continues to operate with relentless focus on in-store execution to drive performance against a muted U.S. bedding industry. We’re executing our new merchandising plan and advertising campaign, leveraging the strength of Mattress Firm’s talented people to support our long-term growth. We are thrilled with how Mattress Firm and Tempur Sealy teams are implementing our shared vision, which I will discuss in just a moment. This has been the smoothest combination I’ve ever experienced in my 40-year career, which only seems fair as it was the longest regulatory approval process imaginable.
The second highlight is the progress we’ve made on our synergy initiatives following the acquisition of Mattress Firm. We’re now approximately 6 months post closing and have made meaningful progress in driving both sales and cost synergies. Starting with
sales. We have refined Mattress Firm’s multi-branded merchandising strategy by taking a more holistic approach to product selection and partnering with multiple suppliers who offer high-quality products at competitive price points, and who support Mattress Firm’s success with their own traffic-driving advertising and differentiated product. We’re also pleased with the progress we’ve made on normalizing our brand’s balance of share at Mattress Firm.
For 2025, we now expect Tempur Sealy to represent approximately low 50% of Mattress Firm’s total sales, up from our initial expectations of high 40%. In total, we expect the balance of share shift from mid-40s in 2024 to low 50s in 2025 to result in $40 million benefit to 2025 adjusted EBITDA. As we look forward to 2026, we’re on track to realize the full benefit of the merchandising changes, which we estimate to be approximately $100 million EBITDA opportunity, phased as an incremental $40 million adjusted EBITDA in 2025 and then another $60 million of adjusted EBITDA in 2026.
For estimating purposes, Mattress Firm sales were held flat over the period. The opportunity is expected to grow as the U.S. bedding industry recovery and U.S. Mattress Firm sales increase. The incremental adjusted EBITDA is derived from enhanced economics from third-party suppliers and normalizing our brand’s balance of share.
Now turning to cost synergies. We’re leveraging our expanded scale and vertical integration to drive efficiencies across manufacturing, logistics and sourcing operations. Enhanced visibility into end consumer demand is also enabling us to refine our future product launches and end-of-life planning. We’re on track to realize at least $100 million in annual run rate net cost synergies with $15 million expected in 2025 and an additional $50 million in 2026. And finally, an additional $35 million in 2027 with opportunities thereafter.
One of the many projects underway is streamlining order fulfillment by utilizing Mattress Firm’s robust home delivery network for Tempur Sealy’s retail sales. In addition to driving cost efficiencies, we expect this initiative to add value by shortening order to delivery time, enhancing oversight of delivery process, in turn, improving customer outcomes and satisfaction. We’ve made significant strides on this initiative to date, and we are on track to begin ramping this program in the fourth quarter. We’re also optimizing our combined marketing spend to drive growth. On a consolidated basis, Somnigroup is now the largest advertiser in the bedding industry by a factor of 2, and we believe we can leverage the combined advertising power to drive demand, benefiting everyone in the bedding industry.
There are a couple of ways we’re operationalizing this opportunity. We’ve identified approximately $20 million of marketing efficiencies that we are considered in our cost target. The savings results from leveraging our combined scale to drive sourcing favorability and improving the efficiency of Mattress Firm’s advertising spend by cutting spend in areas of very low returns, such as sports sponsorships and nonworking agency fees. The $20 million of identified marketing synergies does not include the benefit of any enhanced advertising creative, though we continue to believe it’s a compelling opportunity.
Additionally, Tempur Sealy and Mattress Firm have historically employed different marketing strategies at times, resulting in mixed messages to the consumer. As the 2 largest advertisers in the industry, this was suboptimal. We can now deliver high-quality messaging that benefits everyone, the combined Somnigroup businesses and the broader U.S. bedding industry.
A significant enabler of this higher-quality messaging will be Mattress Firm’s launch of its all-new advertising campaign in the third quarter. The campaign called Sleep Easy is designed to help consumers understand the importance of the right mattress for achieving quality sleep and persuading the consumer to take the next step on their purchase journey. It showcases several of the most widely experienced and acutely felt sleep disruptors and then demonstrates how Mattress Firm and specific mattress solutions it offers can help. Testing show this is the highest performing campaign in Mattress Firm’s recent history across all metrics. We expect synergies to represent a significant enhancement to Somnigroup’s financial and competitive position.
Now that we have more in-depth perspective, let’s look back at the Mattress Firm transaction’s pricing. Mattress Firm’s stand-alone adjusted EBITDA has ranged from approximately $400 million to $700 million over the last 4 years, averaging approximately $530 million. Using the average adjusted EBITDA and taking into account known synergies just discussed, the purchase price at signing of the definitive agreement was about 6x adjusted EBITDA. If you look at the purchase price at closing date, 2 years later and accounting for the impact of Somnigroup’s shares appreciation during the period, it was 7x adjusted EBITDA. We believe this transaction is a great example of creating value through M&A. High return on investment, derisking of the business model of significant distribution risk has been mitigated and clearly enhancing our competitive position.
Our third highlight for the quarter is that our international business continues to perform very well, reporting robust double-digit sales growth and solid margin expansion. This marks 9 consecutive quarters of meaningful sales expansion on a constant currency basis for our legacy international business against the backdrop of industry pressure. Our latest collection of Tempur products continue to be the primary driver of growth with expanded price points broadening our total addressable market. Further, our improved late-stage
customization manufacturing process has allowed us to seamlessly tailor products to individual markets, channels and customers. We’re supporting the new international collection with expanded distribution with broad-based investments in advertising aimed at building brand awareness and driving conversion.
To date, these investments have increased our share of voice in targeted international markets, and we’re winning share of consumer mattress searches versus key competitors in our top 5 markets. Our U.K.-based bedding retailer Dreams, also delivered a strong quarter. They continue to execute on initiatives to provide superior product quality and consistency of service, resulting in continued market outperformance and record customer satisfaction.
Our fourth highlight was Tempur Sealy North America’s market performance. Like-for-like net sales for our Tempur Sealy North American business unit were down 2% in the quarter, excluding mid-single-digit headwind from foreclosed distribution discussed last quarter. Although the North American business was down slightly, we believe it continued to outperform the market, which we believe was down high single digits. Our North American performance was driven by the successful launch of our all-new Sealy Posturepedic collection, the largest bedding launch in industry history.
Remember, Sealy is the #1 brand in the U.S. and the world. The team, our suppliers, our third-party retailers did a great job on a very heavy lift. While the launch did take a bit longer to execute than planned, which impacted the first part of the quarter, we exited the second quarter with solid momentum. The launch targets the mid-entry-level segment. This updated collection is the culmination of a multiyear research and development effort. At the core of our innovation is a new patent-pending coil system engineered to deliver enhanced support. In addition to technology advances, we designed the collection with streamlined merchandising, a clear value proposition and a more compelling step-up story to better guide consumers through the product lineup.
Retailer feedback on the new product is highly positive and consumers’ initial reviews are strong with an average of 4.9 out of 5 stars across the assortment. We’re supporting the launch with a new advertising campaign that began over the Memorial Day holiday. This top-of-funnel initiative is crafted to reinforce the unique value of Sealy Posturepedic and generate excitement around the Sealy brand.
The campaign is complemented by enhanced in-store experience, featuring updated retail displays and new sales streaming. Preliminary results of the campaign are strong. as we believe Sealy has more than doubled its share of voice in the market since the launch. In addition to our increased investment, this expansion is also supported by our retailers redirecting dollars from nonbranded advertising to Sealy, underscoring the trust retailers have in the new product.
Our final highlight is the expanded relationship with Fullpower announced this morning. Fullpower’s Sleeptracker-AI technology powers the successful TEMPUR-Ergo Smart Base, which provides personalized sleep analytics and coaching. As part of the expanded collaboration, Tempur Sealy is making a $25 million equity investment in Fullpower to acquire approximately 15.6% ownership stake.
In addition, Tempur Sealy and Fullpower have signed a multiyear extension through 2036 with Tempur Sealy’s exclusive rights to embed Sleeptracker technology in our products. This strategic investment reflects our deep commitment to innovation and the future of bedding consumer experience. Extending our relationship with Fullpower, we are not only enhancing our ability to serve consumers through smarter, more tailored solutions. We’re reinforcing our position at the forefront of bedding innovation.
Susan Marie Maklari
My question is on the demand side. In your prepared remarks, you said that the quarter started soft and improved as we moved through the last couple of months, and you’re feeling more encouraged going into the third quarter. Can you talk about what has changed in the last couple of months that you think is making the consumer feel a bit better? And what you’re watching for from here out to determine how we — how the industry and your sales come together? And perhaps, is there any upside to your expectations that the industry will be down mid-single digits this year?
Scott L. Thompson
Thank you, Susan. First of all, I think you can go to consumer confidence. If you remember, in the first quarter conference call, we pointed and talked quite a bit about the weakness in consumer confidence and the correlation to consumer confidence in our business as we think about it. And consumer confidence has stabilized, and we’ll call it upticked some. So I think the first thing I’d point out is the lack of new surprises or something unusual coming out of Washington. So consumers are kind of stabilized and slightly better.
I think the next thing I would probably lean on, and I can’t be precise because I don’t have — I don’t know exactly the mix of it, would be the Sealy Posturepedic launch. I mean we’ve called it out for quite a while in the size of this launch, the largest launch in bedding history. It was a huge undertaking, both by the company, by retailers, by some great suppliers. It took a little bit longer to get through the system as retailers had to sell off their floor models and their back stock, as we don’t sweep the floor. So that’s a difficult lift for the retailers, and they did a great job.
And then we launched for the first time, national advertising on Sealy during the quarter. And you could see it in the Sealy numbers. It started a little slower in the quarter than we expected as it took a little while again to get the product placed. But boy, where it was placed, strong velocity in the SKUs and then that momentum continued to run into the third quarter, as we talked about in our prepared remarks. So I guess, in short, just general, no surprises, nothing weird from a consumer confidence standpoint, a little bit of a recovery, then good product innovation and advertising.
Bhaskar Rao
Just to add on to that is at the midpoint, what we’re assuming is that, call it, low or mid-single digit from an industry decline standpoint. When you translate that into what it means for Tempur Sealy, the way I think about it is EPS, nice growth in the back half, call it, mid- to high single digits. And what I would expect is more of that growth from an EPS coming in the fourth quarter versus the third quarter. And that’s nothing more than the historic seasonality of Mattress Firm, a little bit more advertising in the third versus the fourth. So what does all that mean? Think about EPS in the third quarter in the mid-80s with the balance coming in the fourth quarter to get to that midpoint of $2.55.
Bradley Bingham Thomas
Congrats on the good start here with Mattress Firm. My question was around your relationship with non-Mattress Firm retailers. And Scott, I was hoping you could just talk a little bit more about what you’re seeing in terms of sales trends within your different brands, how slot count is holding up? And just more broadly, that relationship with the non-Mattress Firm retailers as you all now own this #1 retailer in the segment?
Scott L. Thompson
Sure. Our net slot in the second quarter with third-party retailers is net up from the same period last year. If I look at the top 5 retailers and I look at our business with the top 5 retailers, it has grown and has increased quicker or yes, I guess, quicker is a good word than the market share. So I would say that those 2 stats would be the first things that I would lean into. I would say that the Sealy
product has done very, very well with third-party retailers and it continues to be business as normal. And normal is with great product, advertising, sales support to logistics, where we help third-party retailers drive their business, which is our business plan, we’re getting great reception.
Peter Jacob Keith
Thinking about the sales mix between Tempur and Sealy, I’m wondering if you are experiencing or could start to experience some mix pressure on your gross margin, if the strength in Sealy would push Sealy sales growth ahead of Tempur-Pedic growth. And on a related note, one thing we are hearing in the retail channel is that the high end of the Sealy line is so good that it’s actually cannibalizing the low end of the Tempur line. So maybe you could comment on that potential as well.
Scott L. Thompson
Sure. I mean, first of all, the Tempur brand was the strongest brand in the second quarter, just to kind of put a base. On a go-forward basis, which is what your question is, I think it is possible that the Sealy brand will grow faster than the Tempur brand for a couple of quarters. And it would be a slight headwind to the gross margin.
Bradley Bingham Thomas
Scott, I wanted to ask about product innovation and particularly with the news of the partnership and investments in full power and again, now being even more vertically integrated in the U.S. How should we think about the pace of innovation and how you all may innovate differently, if at all, from a product standpoint?
Scott L. Thompson
Thanks for the question. You’re right. One of the advantages of combining with Mattress Firm is to align on technology for future innovation. Mattress Firm was going down a different path from a technology standpoint and had a different technology strategy. And then, of course, we have our technology strategy leveraging full power. And quite frankly, the thought of one day in the future going to Mattress Firm or any other retailer and the RSA explaining to you, here’s one app if you buy this bed, here’s another app if you buy that bed and trying to explain multiple technologies. To me, it sounded like a disaster on the floor.
And so the combination allows us to streamline under one technology platform. That will accelerate innovation and also it derisk the innovation because we have known distribution that — so when we develop something, we know we have a home for it, and it’s a home that’s large enough to drive that technology to make the economics work. So I do think the combination of Mattress Firm was an unlock on what I’ll call future innovation that will be more complex and change your sleeping experience.
August 12, 2025
Wanhua Chemical Released 1H 2025 Financial Report
PUdaily | Updated: August 12, 2025
On August 11, Wanhua Chemical released its 1H 2025 financial report. The company posted revenue of CNY 90.90 billion, down 6.4 % year-on-year; net profit attributable to shareholders was CNY 6.12 billion, down 25.1 %; recurring net profit was CNY 6.24 billion, down 22.9 %; and net cash from operating activities was CNY 10.53 billion, up 2.3 %.
In the second quarter, revenue reached CNY 47.83 billion (-6.0 % YoY); net profit attributable to shareholders was CNY 3.04 billion (-24.3 % YoY); and recurring net profit was CNY 3.20 billion (-19.3 % YoY).
In the report, the company noted that despite weak global demand and geopolitical tensions, the chemical industry remained stable overall. Wanhua continued to optimize the structure of its polyurethane, petrochemicals, specialty chemicals and advanced materials businesses. Within polyurethane, demand from new-energy and high-end manufacturing segments was robust, while overseas energy-efficient construction markets underperformed.
In petrochemicals, concentrated capacity additions created supply-demand imbalances, pushing prices lower and compressing margins. Specialty chemicals and advanced materials benefited from supportive national policies and achieved steady growth with promising prospects. Under the management theme of “Year of Transformation,” the company reorganized structures and mindsets, strengthened cost control and resource-allocation efficiency, and responded actively to market shifts to sustain optimization.
Wanhua remains innovation-driven to upgrade its portfolio. It is advancing next-generation MDI technology, expanding capacity and implementing energy-saving projects to achieve best-in-class cost competitiveness. In-house technologies are being commercialized rapidly: the MS unit started up successfully on the first attempt, enriching the optical product line; tert-butylamine reached industrial scale, extending the specialty amine chain; sulfone polymers have produced on-spec material, rounding out Wanhua’s engineering-plastics solutions; bio-based 1,3-butanediol has been qualified by cosmetics customers. Battery-material R&D continues to accelerate: fourth-generation lithium iron phosphate is already in mass production, and the fifth generation has completed its initial release. A differentiation strategy yielded multiple high-value-added POE, polyolefin, nylon 12 and modified-material grades, penetrating niche markets and boosting new-business capabilities. AI-enabled research projects are progressing in an orderly manner; the National Key Laboratory for High-Performance Organic Optical Polymers and Advanced Manufacturing Technologies remains focused on strategic needs, deepening external collaboration and building mutually beneficial ecosystems with industry partners. In 2025, the company filed 469 domestic and international invention patents and was granted 269, accelerating overseas patent deployment to support global expansion of new businesses.
August 10, 2025
Tosoh Corporation Announced its First-quarter Consolidated Results for 2026 Fiscal Year
PUdaily | Updated: August 8, 2025

August 05, 2025, Tokyo, Japan—Tosoh Corporation is pleased to announce its first-quarter consolidated results for its 2026 fiscal year, from April 1, 2025, to June 30, 2025.
The Company’s net sales decreased ¥7.7 billion (3.1%) year-on-year to ¥245.1 billion (US$1.7 billion), during the first quarter the first three months of the Company’s 2026 fiscal year which extends from April 1, 2025, to March 31, 2026. This decrease was attributable to lower naphtha prices and the progressively stronger yen, as well as a decrease in shipment volume resulting from reduced production volume during scheduled maintenance at the Nanyo Complex.
The Company’s consolidated operating income decreased ¥3.7 billion (18.9%) year-on-year to ¥16.1 billion (US$111.2 million), due to unfavorable inventory fluctuations and increased fixed costs, despite sales growth in the Engineering Group and improved terms of trade backed by lower prices in raw materials and fuels, including naphtha and coal. Non-operating income decreased ¥9.5 billion year-on-year due to deterioration in foreign exchange gains and losses.
Ordinary income decreased ¥13.3 billion (48.5%) year-on-year to ¥14.1 billion (US$97.4 million).
Quarterly net income attributable to owners of parent decreased ¥9.7 billion (59.8%) year-on-year to ¥6.5 billion (US$45.2 million).
During the period under review, the United States saw steady growth where the labor market remained firm. In Europe, the economy recovered moderately as inflation eased, while in China, there were signs of improvement supported by policy measures. Due to the impact of the United States’ uncertain tariff policies, the ongoing real estate recession and deflation in China, both the Japanese and overseas economies faced an uncertain outlook and continued to experience challenging conditions.
Chlor-alkali
Chlor-alkali Group net sales decreased ¥9.7 billion (10.5%) year-on-year to ¥82.1 billion (US$567.7 million). Operating income decreased ¥3.2 billion year-on-year, resulting in an operating loss of ¥1.9 billion (US$13.0 million). This was due to unfavorable inventory fluctuations and a decrease in shipments, despite improved terms of trade for caustic soda and MDI backed by lower prices in raw materials and fuels.
Caustic soda shipments decreased due to lower production volume from scheduled maintenance at the Nanyo Complex, but export prices increased as overseas market conditions improved. Vinyl chloride monomer shipments also decreased due to lower production volume from scheduled maintenance at the Nanyo Complex. Polyvinyl chloride (PVC) resin shipments were unchanged year-on-year. Moreover, selling prices of PVC products for overseas markets declined due to weaker overseas market conditions.
Cement shipments decreased due to weak demand, despite an increase in domestic selling prices.
Methylene diphenyl diisocyanate (MDI) shipments decreased due to lower production volume during scheduled maintenance at the Nanyo Complex. Market conditions for hexamethylene diisocyanate (HDI) hardeners declined and shipments decreased, reflecting sluggish global demand.
 Everchem Updates Archive
 Sign Up for Email Updates