
The Urethane Blog
October 29, 2024
Increased profits in challenging market environment
- Group sales remain stable at EUR 3.6 billion (+1.0%)
- EBITDA increases to EUR 287 million (+3.6%)
- Net income reaches EUR 33 million
- Free Operating Cash Flow is at EUR 112 million (–63.6%)
- Investment Agreement with ADNOC signed
- Guidance for 2024 fiscal year narrowed within given ranges
In the third quarter of 2024, Covestro continued to increase its volumes sold, particularly in the EMLA and APAC regions. Compared to the same quarter of the previous year, Group sales remained stable at around EUR 3.6 billion, as lower raw material prices led to lower selling price levels (previous year: EUR 3.57 billion). Compared to the third quarter of 2023, the Group’s EBITDA increased by 3.6 percent to EUR 287 million (previous year: €277 million), thus falling within the expected range of EUR 250 million to EUR 350 million. Net income reached EUR 33 million (previous year: EUR –31 million). Free operating cash flow decreased to EUR 112 million (previous year: EUR 308 million), primarily due to lower operating cash flows.
“We concluded the third quarter of the year with higher sales volumes and improved earnings,” said Dr Markus Steilemann, CEO of Covestro. “Nevertheless, the current market environment remains challenging. Our focus is therefore clear: We continue to do our homework, focus on the levers we can control and consistently implement our ‘Sustainable Future’ strategy. In doing so, we not only lay the foundation for future success and sustainable growth, but also make steady progress towards becoming fully circular.”

Guidance for 2024 further narrowed within given ranges
In light of the continued challenging economic environment, Covestro has narrowed its guidance for the 2024 fiscal year regarding expectations for EBITDA and ROCE above WACC.
The Group now anticipates EBITDA between EUR 1.0 billion and EUR 1.25 billion (previously: between EUR 1.0 billion and EUR 1.4 billion). For ROCE above WACC, Covestro now expects a range between –7.0 and –5.0 percentage points (previously: between –7.0 and –4.0 percentage points) for the financial year 2024. Regarding GHG emissions (measured as CO2 equivalents), Covestro continues to expect a figure between 4.4 and 5.0 million metric tons. Covestro also continues to expect a Free Operating Cash Flow between EUR –100 and EUR 100 million.
“Overall, global demand is intact but remains at a low level. We continue to face challenges in various industries and regions,” says Christian Baier, CFO of Covestro. “Nonetheless, we were able to slightly increase our EBITDA, indicating that our measures for efficiency and plant reliability are working. However, the economic environment remains challenging, and we have therefore narrowed our guidance for the full year accordingly.”
Investment Agreement with ADNOC supports execution of “Sustainable Future” strategy
As announced in an ad-hoc release on October 1, 2024, Covestro has on that day signed an Investment Agreement with entities of the ADNOC Group, including ADNOC International Limited (“ADNOC International”) and its indirect subsidiary ADNOC International Germany Holding AG (“Bidder”). The agreement stipulates, among other items, that the Bidder will make a public takeover offer for all outstanding shares of Covestro at a price of €62.00 per share. In addition, ADNOC International is committing itself to fully supporting the Company’s “Sustainable Future” strategy and intends to fully support Covestro in further executing on this strategy. To this end, the Bidder shall subscribe to new Covestro shares at the offer price via an increase of the Company’s share capital by 10% under simplified exclusion of subscription upon the completion of the transaction. This will result in an amount of €1.17 billion proceeds at an offer price of €62.00 which Covestro will use to foster the further implementation of its growth strategy.
On October 25, 2024, the Bidder, following approval by BaFin, has published the corresponding offer document in relation to all outstanding Covestro shares at an offer price EUR 62.00 per Covestro share. The Board of Management and the Supervisory Board of Covestro will now carefully review the offer document and issue a reasoned statement pursuant to Section 27 WpÜG in due course. Subject to the review of the offer document, the Board of Management and the Supervisory Board assume that they will recommend the acceptance of the offer to the Company’s shareholders.
Further milestones on the road to climate neutrality achieved
In the third quarter of 2024, Covestro further increased the share of renewable energies in its energy mix, thereby achieving another important milestone on the road to operational climate neutrality by 2035. In July 2024, Covestro signed a long-term power purchase agreement (PPA) with bp to supply its sites in Spain with solar energy. The contract has a term of ten years and increases the share of renewable energy from less than ten percent to around 30 percent. As a result, a significant share of the electricity consumption of Covestro’s main production site in Tarragona, Spain, is now also covered by renewable sources.

EBITDA in the Performance Materials segment significantly increased
In the Performance Materials segment, Covestro increased its sales by 4.1 percent to EUR 1.78 billion (previous year: EUR 1.71 billion) in the third quarter of 2024. This was primarily driven by higher volumes, especially in the EMLA region. These higher volumes contributed to a significant increase in EBITDA of 47.1 percent to EUR 125 million (previous year: EUR 85 million). Free Operating Cash Flow amounted to EUR 111 million (previous year: EUR 317 million) due to a significantly lower release of funds from working capital compared to the same quarter of the previous year.
In the Solutions & Specialties segment, sales in the third quarter of 2024 decreased by 2.0 percent to EUR 1.77 billion (previous year: EUR 1.81 billion). This was primarily due to a demand-related decline in average selling prices, which higher volumes were unable to offset fully. As a result, the segment’s EBITDA fell 15.4 percent to EUR 208 million (previous year: EUR 246 million). Free Operating Cash Flow was EUR 101 million (previous year: EUR 185 million), primarily due to cash being tied up in working capital, as opposed to a release of funds in the same quarter last year, and lower EBITDA.
Challenging environment weighs on results in the first nine months of 2024
In the first nine months of 2024, Covestro’s sales remained largely stable at EUR 10.8 billion compared to the same period of the previous year (previous year: EUR 11.0 billion). The increase in volumes across the Group did not offset the demand-related decline in average selling prices in the first nine months. That is also reflected in the EBITDA for the first nine months of 2024, which fell by 7.2 percent to EUR 880 million (previous year: EUR 948 million). Net income fell to –€74 million (previous year: –€11 million). Free Operating Cash Flow for the nine-month period amounted to –€164 million (previous year: €159 million).
https://www.covestro.com/press/increased-profits-in-challenging-market-environment
October 24, 2024
Dow Inc. (DOW) Q3 2024 Earnings Call Transcript
Oct. 24, 2024 11:16 AM ETDow Inc. (DOW) Stock
Q3: 2024-10-24 Earnings Summary
EPS of $0.47 misses by $0.00 | Revenue of $10.88B (1.39% Y/Y) beats by $200.05M
Dow Inc. (NYSE:DOW) Q3 2024 Earnings Conference Call October 24, 2024 8:00 AM ET
Company Participants
Andrew Riker – IR, VP
Jim Fitterling – Chair and CEO
Jeff Tate – CFO
Conference Call Participants
Vincent Andrews – Morgan Stanley
Hassan Ahmed – Alembic Global
Richard Garchitorena – Wells Fargo Securities
Jeff Zekauskas – JPMorgan
Bhavesh Lodaya – BMO Capital Markets
David Begleiter – Deutsche Bank
Steve Byrne – Bank of America
Josh Spector – UBS
Chris Parkinson – Wolfe Research
Patrick Cunningham – Citi
Kevin McCarthy – Vertical Research Partners
Frank Mitsch – Fermium Research
John Roberts – Mizuho
Mike Leithead – Barclays
Duffy Fischer – Goldman Sachs
Matthew Blair – TPF
Aleksey Yefremov – KeyBanc
Laurence Alexander – Jefferies
Arun Viswanathan – RBC Capital Markets
Jim Fitterling
Thank you, Andrew. Beginning on Slide 3, our cost advantage footprint in the Americas continues to provide strong competitive edge capturing demand growth in attractive markets and regions. In the third quarter, Team Dow delivered our fourth consecutive quarter of year-over-year volume growth. We delivered this despite a soft macroeconomic environment, primarily in Europe and China, as well as an unplanned cracker outage in Texas, which has been successfully restarted and is running well.
Net sales in the Q3 were $10.9 billion, this is up 1% versus the year ago period led by higher demand and local prices in the United States and Canada. Volume increased 1% versus the year ago period and prior periods. Sequentially, we saw gains in Packaging and Specialty Plastics and Industrial Intermediates and Infrastructure.
Local price was flat year-over-year as gains in Packaging and Specialty Plastics were offset by decreases in Performance Materials and Coatings. Sequentially, local price was down 1% due to minor declines across all segments. Operating EBIT was $641 million, up $15 million year-over-year, reflecting higher integrated margins in Packaging and Specialty Plastics, which were partly offset by the impact of the unplanned cracker outage in Texas and higher planned maintenance activity. Cash flow from continuing operations was $800 million down year-over-year, primarily due to higher inventories to support both sales growth and labor related supply chain disruptions.
Shareholder remuneration for the quarter was $584 million including dividends and share repurchases. In addition, we progressed our long-term growth strategy including signing a long-term agreement with Linde for the supply of clean hydrogen for our Path2Zero project in Fort Saskatchewan. We also completed the acquisition of US based polyethylene recycler Circulus. This will add capacity of 50,000 metric tons of recycled materials annually to Dow’s portfolio.
Now turning to our operating segment performance on Slide 4. In the Packaging and Specialty Plastics segment, local price increased year-over-year led by higher polyethylene prices in all regions except Latin America, which was flat. Volume was flat year-over-year as higher demand for functional polymers in all regions was offset by lower polyethylene volumes. Operating EBIT was $618 million an increase of $142 million year-over-year. This was primarily driven by higher integrated margins, which were partly offset by the impact of the unplanned cracker outage I mentioned earlier.
Moving to the Industrial Intermediates and Infrastructure segment, local price was flat year-over-year. In addition, volume was down 2%. This was driven by lower volumes in Polyurethanes and Construction chemicals, which were primarily due to a force majeure in MDI following a third-party supplier outage.
Operating EBIT decreased $74 million versus the year ago period. Results were driven by higher planned maintenance activity and lower integrated margins, which were partly offset by improved equity earnings. And in the Performance Materials and Coatings segment, local price declined year-over-year, while volume was up 5% with gains in both businesses and across all geographic regions. Operating EBIT was $140 million down $39 million compared to the year ago period, driven by higher raw material costs, which were partly offset by higher volumes.
Moving to Slide 5. The strength of Dow’s differentiated portfolio is defined by our strategic and purpose built asset footprint which leverages low cost feedstock positions, primarily in the Americas. Our growth investments are concentrated in higher value businesses and regions, particularly where demand is resilient and we have a competitive cost advantage. Over the past few years, we’ve demonstrated our commitment to operating with the best owner mindset by taking proactive actions with select higher cost assets aligned with the evolving market dynamics.
Since 2023, we have undertaken more than 20 asset actions. These include targeted rationalization of our global polyols capacity, shutting down our propylene oxide unit in Freeport, Texas in 2025 to reduce lower value merchant PO exposure, strengthening our coatings footprint with select asset closures and announcing the sale of our laminating adhesives business for $150 million including two manufacturing sites in Italy, which we expect to finalize in the fourth quarter of this year.
Overall, these actions have been primarily focused on our industrial, intermediates and infrastructure segment and in the EMEA region. On Slide 6, current market dynamics are impacting Europe, including continued soft demand, coupled with a persistent lack of long-term regulatory policy. This ongoing absence of clear, consistent, and competitive regulatory policy in Europe has resulted in many challenges for our industry.
These challenges have been acknowledged in statements by EU government leaders, top economists, and our peers. And while a demand recovery in other parts of the world was expected to provide swift upside across the markets we serve, this alone is unlikely to be enough in Europe. Given these dynamics, we’ve begun a strategic review of select European assets, primarily those in our polyurethane business. This review includes all value-creating options for these assets and currently consists of approximately 20% of our sales in the EMEA region.
We expect to complete this review by mid-2025. We continue to engage with governments both directly as well as through our leadership in trade associations to improve the industry’s overall competitiveness in the region. Decisions regarding the strategic review, similar to our prior actions, will focus on strengthening Dow’s global portfolio. This enables us to invest in the most attractive opportunities and create long-term value growth for our shareholders.
Hassan Ahmed
Good morning Jim. Just a question around some of the sort of review work that you guys are doing in Europe. You guys specifically talked about polyurethanes. I’m just trying to sort of get a better sense of all the moving parts with regards to how you see the polyurethane cycle sort of panning out. Obviously, we’ve seen or about to see some assets change hands within the global polyurethane market. The destocking was particularly severe in polyurethanes, but the supply side seems a bit tepid. So as sort of you sift through all of these moving parts, how do you see the polyurethane market sort of coming out on the other side?
Jim Fitterling
Good morning Hassan. Actually, we’re still poised for a very good recovery in construction and durables markets, which really drive a lot of what’s going on in polyurethanes. I’d add automotive on top of that because I think automotive has been under some pressure in Europe. So I agree with you, there is no signs that there’s any stocking and destocking has run its course. But I think we are waiting for that obvious turn in the economy that gets people moving into those segments.
And those assets in Europe is really a portfolio shift move. It really has nothing to do with the business. Polyurethanes is a good business, a pretty diverse downstream markets. We’ve got good positions there. And as I mentioned, we’re thinking about 20 asset actions so far across the globe, mostly in II&I, which is really to tighten up the footprint and get our capacity focused on our lowest cost assets there. So I think it is strengthened, both polyurethane business and also the coatings business as well.
Thank you, good morning. Jim, on the European assets under review, are they EBITDA positive? And if so, how much? And if you do close both of your MDI plants in Europe, would you still look to supply Europe MDI from your plants in Saudi and Texas? Thank you.
Jim Fitterling
Yes, good morning David. I don’t have a specific number to give you on the European assets right now, but they are EBITDA positive. They are good cost positions in the European market. Again, we are looking at all value-creating opportunities. I don’t believe – I don’t want to preclude anything, but I don’t believe shutting down MDIS, that is going to be a value-creating opportunity, but we’re going to look at everything.
John Roberts
Thank you. Jim, you’ve got chlorine integration in Europe. So how separable are the decisions you’re looking at in Europe for polyurethanes versus the [cab] (ph) assets?
Jim Fitterling
They’re not, John. Obviously, we’re not going to do anything without close contact with our own chlorine assets but also with our partners in Europe. And so we’ll keep a close eye on that. Chlorine PO integration is critical for us, and so we will make sure we’re eyes wide open to that.
Aleksey Yefremov
Thanks good morning everyone. Jim, I was quite surprised to see about $100 million in EBITDA for II&I into this quarter. The segment started the year pretty strongly with $234 million, and then EBITDA continued to soften. Could you give us, just to reflect on this year, what product specifically or regions maybe did not perform as well? And what do you expect next year here?
Jim Fitterling
Yes. So obviously, we had Glycol-2 up and running, so that was to a positive. We had price pressure on PO Polyols and we had lower volumes in MDI. I mentioned in the opening that we had a third-party outage in North America, which supplied industrial gas to our MDI process there, the plants back up but still running at lower rates. And then look, the other thing that happened when Texas-8 was out, Texas-8 produces propylene for us as well. And so when we had Texas-8 out, we had to go into the market to get some of that propylene so that was a higher cost.
So I think it was on to one-time, the MDI issue is a one-time, which will correct itself. The PO polyols that was a big driving force around the decision to tighten up the footprint in Freeport. So as we go forward, we don’t have as much length in PO, which brings the North American market more in the balance. So I think, as we move forward, it is polyurethanes in North America, that was the bigger slowdown and drag in the quarter.
Arun Viswanathan
Hi, guys great. Thanks for taking my question. So I guess I just wanted to ask about — there’s been a lot of portfolio reviews, especially of European assets at this point. So just wondering if you’ve gone through some kind of analysis here, assuming any of those shutdowns happen or potentially portfolio reviews result in shutdowns. How much maybe capacity could be coming out of the industry and P&SP in — as you look into ’25.
And maybe if you can give us your thoughts as well on PMC kind of global supply demand as well, just because we’ve been mired in weakness on the coating side for a while, from a demand standpoint, but maybe there is some green shoots with rates coming down. So do you see any improvement in operating rates on the PMC side as well. So just maybe you could get your comments on both P&SP and PMC utilization as you look into ’25? Thanks.
Jim Fitterling
Yes good morning Arun. Look, I think, again, our portfolio work in Europe is around polyurethanes. And as I mentioned before, it really isn’t driven primarily by shutdowns, we’ll look at that. But I think we’ve done a lot to bring smaller assets down and bring that capacity into our low-cost locations. It’s really looking at what is there a better owner for the portfolio? Does that allow us to continue to focus on our Invest for Growth businesses, which went from Investor Day, you’ll remember we’re P&SP our silicones business and also our Industrial Solutions business.
October 24, 2024
Dow’s stock rises as Q3 sales beat estimates
Oct. 24, 2024 9:20 AM ETDow Inc. (DOW) StockBy: Rob Williams, SA News Editor
Dow’s (NYSE:DOW) stock rose 1.5% on Thursday morning after the chemical maker reported third-quarter results.
Adjusted earnings were $0.47 a share, in line with the consensus estimate.
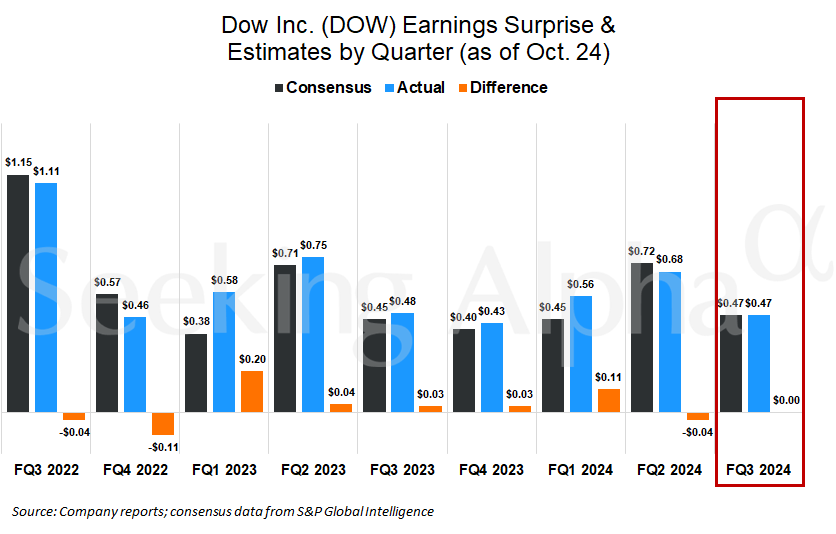
Net sales rose 1% from a year earlier to $10.88 billion in the third quarter, led by higher sales in the United States and Canada. Analysts on average forecast sales of $10.68 billion.
The company last month had warned third-quarter sales would be less than previously forecast.
“Our cost-advantaged footprint in the Americas continues to provide a strong competitive edge, enabling Dow (DOW) to capture demand growth in attractive markets,” Jim Fitterling, chair and chief executive of Dow (DOW), said in a statement. “However, a meaningful recovery has yet to materialize in Europe and China.”
Sales grew 1.1% from the prior year in its packaging and specialty plastics business, and by 3.9% for its performance materials and coatings unit. However, sales fell 2.4% in its industrial and infrastructure unit.
October 23, 2024
October 18, 2024

Update: Compliance with Antidumping Duties and Tariffs for Spray Foam Products
U.S. International Trade Commission (USITC) into imports of alkyl phosphate esters (TCPP fire retardants) from China for price dumping (701-TA-721 and 731-TA-1689).
To all Quadrant Performance Materials Customers,
On September 30, 2024, the Department of Commerce International Trade Administration announced their preliminary determination, concluding that countervailable subsidies—financial assistance and other unfair trade practices—have been provided by the Chinese government to its domestic producers of alkyl phosphate esters (TCPP), thus distorting international trade. These subsidies have given unfair advantages to Chinese manufactures, enabling them to sell goods at lower prices. For more details, please see the Federal Register notice: Federal Register Document C-570-169.
Countervailing duties (additional tariffs) have been imposed on the importation of Chinese manufactured TCPP, with tariffs ranging from 50% to 564%, depending on the company.
A variety of US Industries, including spray foam, use imported TCPP as the US domestic production capacity is insufficient to meet Industry demands. Consequently, the raw material costs for spray foam are expected to increase.
Furthermore, the investigation is still ongoing, to further assess additional antidumping tariff and or penalties; with a final determination expected in late November and or before February 9, 2025.
We strongly recommend that you obtain documentation from your spray foam suppliers to ensure that the products you have purchased since 2018, as well as those you are currently buying, comply with all applicable duty and tariff regulations.
Quadrant’s Commitment to Compliance
Quadrant Performance Materials has and will continue to adhere to all relevant duties and tariffs for any imported materials used in our spray foam systems and other products. We verify and ensure the payment of these duties and tariffs, to maintain transparency and compliance.
If you have any questions or need further clarification on this issue, please do not hesitate to contact us.
Quadrant Performance Materials
200 Industrial Blvd, McKinney, TX 75069
(972)542-0072
October 22, 2024
A turn to growth expected for residential remodeling
By Dakota Smith
October 17, 2024 | 10:09 am CDT

CAMBRIDGE, Ma. — After a mild pullback over the previous year, spending for improvements and repairs on owner-occupied homes is set to expand once again by the middle of next year, according to the Leading Indicator of Remodeling Activity (LIRA) released by the Remodeling Futures Program at the Joint Center for Housing Studies of Harvard University. The LIRA projects that annual expenditures for home renovation and maintenance will grow by 1.2 percent through the third quarter of 2025.
“A continued thaw in new home construction and sales of existing homes bodes well for an uptick in residential improvement and repairs next year,” says Carlos Martín, Director of the Remodeling Futures Program at the Center. “Additionally, stronger gains in home values and thus home equity levels should boost both discretionary and ‘need-to-do’ replacement projects for owners staying in place.”
“Annual spending for home improvements and maintenance is projected to grow from $472 billion today to $477 billion through the third quarter of 2025,” says Abbe Will, Associate Director of the Remodeling Futures Program. “A quick return to growth after a fairly modest downturn ultimately means that residential remodeling and repair expenditures are expected to approach past peak levels moving forward.”
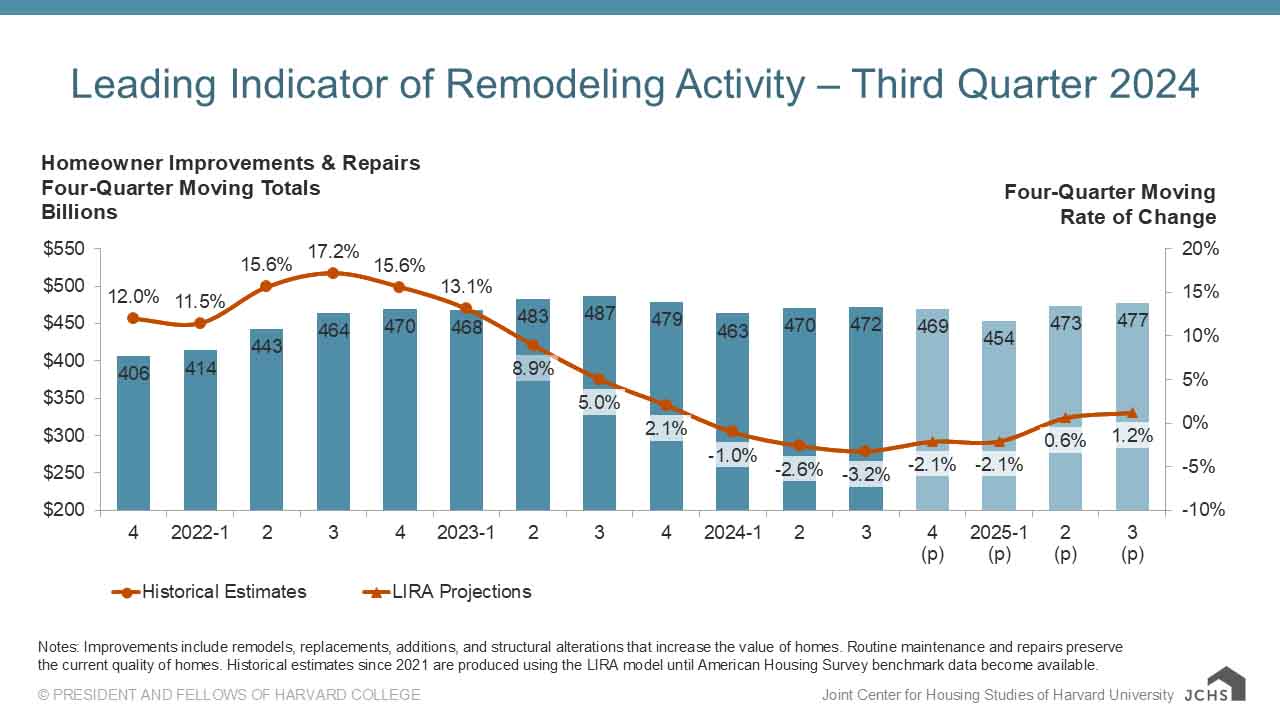
The Leading Indicator of Remodeling Activity (LIRA) provides a short-term outlook of national home improvement and repair spending to owner-occupied homes. The indicator, measured as an annual rate-of-change of its components, is designed to project the annual rate of change in spending for the current quarter and subsequent four quarters, and is intended to help identify future turning points in the business cycle of the home improvement and repair industry. Originally developed in 2007, the LIRA was re-benchmarked in April 2016 to a broader market measure based on the biennial American Housing Survey.
The LIRA is released by the Remodeling Futures Program at the Joint Center for Housing Studies of Harvard University in the third week after each quarter’s closing. The next LIRA release date is January 16, 2025.
 Everchem Updates Archive
 Sign Up for Email Updates