
The Urethane Blog
October 30, 2024
Casper Sleep Inc. To Operate As Subsidiary Of Carpenter Co.
Posted on October 29, 2024

RICHMOND, VA – Casper Sleep Inc., which has one of the best-known brands in the bedding category and is recognized as the leader in the bed-in-a-box e-commerce category, has become a subsidiary of Carpenter Co. Carpenter will assist Casper on a comprehensive growth and profitability strategy, as well as the appropriate future channels to market.
For more information, please contact Mike McQuiston, Senior Vice President of Consumer Products for Carpenter Co.
About Carpenter Co.
Founded in 1950, Carpenter Co. is the world’s largest vertically integrated manufacturer of polyurethane foams. Carpenter also serves a diversified global marketplace with polyurethane chemical solutions, polyester fibers, and insulation materials through a network of more than 70 production locations. Our 6,500+ employees across the globe seek to provide the most innovative products and solutions with a focus on enhancing the quality of people’s lives while being a good steward of our resources.
https://carpenter.com/en/casper-sleep-inc-to-operate-as-subsidiary-of-carpenter-co/
October 30, 2024
MDF recycling set to launch on an industrial scale
By Larry Adams
October 29, 2024 | 11:39 am CDT

MDF recycling was technically impossible, but now a new process is set to launch on an industrial scale.
Photo By Unilin Technologies
WIELSBEKE, Belgium — Backed by a €20 million investment, Unilin is set to start recycling MDF on an industrial scale at its site in Bazeilles, France. Unilin plans to make this innovative service available to the entire sector via Unilin Technologies.
For the production of its MDF and HDF boards, Unilin Group, a global supplier of panels and building supplies, uses recovered and recycled wood. Until 2021, it was technically impossible to recycle the 100 million cubic feet of medium density fiberboard (MDF) and high density fiberboard (HDF) boards manufactured worldwide each year, but Unilin has developed a steam explosion technology to reclaim the wood fiber from these boards in an economically viable manner and reuse them for the production of high-quality fiberboards on an industrial scale.
According to Geert Coudenys, R&D Director, Unilin Panels, the steam explosion is a process in which biomass is treated with hot steam (180 to 240 °C) under pressure (1 to 3.5 MPa) followed by an explosive decompression of the biomass that results in a rupture of the biomass fibers’ rigid structure. “It sounds quite complicated,” Coudenys told Woodworking Network, “but you can compare the process of recycling MDF to the operation of a pressure cooker. First, we moisten the MDF boards with steam. Then the boards are heated and put under very high pressure. Finally, the pressure is reduced, releasing the fibers.
MDF and HDF containing products, such as laminate flooring, are considered difficult to recycle because of the specific way they are made, Coudenys said. These boards are composed of very fine wood fibers bonded with a urea-formaldehyde adhesive, which makes mechanical recycling methods unsuitable. When mechanical recycling methods (like those used for chipboard) are applied to MDF/HDF, the fibers in these boards are destroyed, preventing them from being reused to create new MDF or HDF products. Instead, these materials have traditionally been incinerated or sent to landfills at the end of their life. To recycle MDF/HDF, a chemical recycling process is needed to preserve the integrity of the wood fibers. However, this process is complex and has been challenging to develop on an industrial scale, requiring significant time and resources to create an efficient and high-quality technology.
“As a result, recycling these materials has been considered almost impossible for a long time. Until now. Unilin is the first company in the world to develop a technology to recycle MDF/HDF on an industrial scale,” he said. “Until now, MDF items such as decorative panels, laminate flooring, and production waste products were simply incinerated at the end of their life cycle. What previously made recycling such products impossible was the glue used to bond the wood fibers. The key to making it possible was therefore to find a way to break down the glue molecules.”
Unilin Panels’ CEO Veronique Hoflack took to the kitchen for the first round of testing, using her pressure cooker. “What we’re actually doing is using steam to break apart the glue molecules in cooking vessels,” explains project engineer Stéphane Marthy. “Ultimately, these are agro-industrial machines. To make them suitable for MDF recycling, we put them through a rigorous experimentation process to determine the optimal process parameters.”
From prototype to industrial production
After several years of prototype production, the testing phase finally successfully concluded and the industrial production phase could commence: “We’re going to be working with the same kind of machines, but this time they are custom-built for our needs, to handle far higher volumes,” explains Yoann Raucourt, production manager for the Bazeilles site. Currently, Unilin’s Bazeilles plant is already recycling 1500 kilos of MDF an hour, to exponentially increase this rate from September 2025. This is the date the first MDF recycling line should go live.
“MDF recycling enables us to reuse the wood fibers in the product, storing the CO2 in the wood for longer, rather than being incinerated. The aim for the first phase of operation is to store 380,000 tons of additional CO2 per year, equivalent to the annual emissions of 211,000 cars,” explains Julien Boucher, site manager at Bazeilles.
The €20 million investment will fund new industrial plants and equipment, as well as implementing new processes. Subsequently, Unilin will be able to offer MDF panels made from 30% recycled materials, with that proportion undoubtedly set to rise in the future. To achieve this, two recycling lines will have to be created and integrated: the pre-consumer lines, handling waste generated by industrial customers (manufacturers of laminated products, etc.), and the post-consumer lines, processing consumer waste materials recovered at the end of their first life.
Boucher added, “Innovation is in Unilin’s DNA and we are convinced that this MDF recycling technology represents a considerable leap forward for our industry. This is why we are keen to make this technology more widely available, through Unilin Technologies licensing. This will help develop and boost the circular economy of the panels and flooring industry.”
October 30, 2024
BASF Group in third quarter 2024:
EBITDA before special items increased compared with Q3 2023 due to considerably higher earnings of core businesses
- Sales in third quarter 2024: €15.7 billion (prior-year quarter: €15.7 billion)
- EBITDA before special items in third quarter 2024: €1.6 billion (prior-year quarter: €1.5 billion)
Thanks to significantly higher contributions from the core businesses, BASF Group’s EBITDA before special items (income from operations before depreciation, amortization and special items) increased in the third quarter by €77 million to €1.6 billion. “The positive earnings momentum in our core businesses was already visible in the first half of 2024 and continued in the third quarter, driven by higher volumes and margins,” said Dr. Markus Kamieth, Chairman of the Board of Executive Directors of BASF SE. This increase was partially offset by a considerable earnings decline in the standalone businesses as well as in Other.
Under its new strategy announced in late September 2024, BASF differentiates between its core businesses (Chemicals, Materials, Industrial Solutions and Nutrition & Care) and the standalone businesses that serve distinct industries. The standalone businesses are reported in the Surface Technologies and Agricultural Solutions segments.
At €15.7 billion, sales were on a level with the prior-year period. Volume growth in almost all segments compared with the third quarter of 2023 had a positive impact on sales performance. Volumes increased in the core businesses as well as in Agricultural Solutions. Only the Surface Technologies segment recorded a decline in volumes in the Catalysts division due to weak demand in the automotive market. Negative currency effects, mainly relating to the Argentine peso and Brazilian real, burdened sales. Lower prices in nearly all segments, particularly for precious and base metals in the Surface Technologies segment, also hindered sales performance.
The EBITDA margin before special items was 10.3 percent, following 9.8 percent in the prior-year quarter. In the core businesses, the EBITDA margin before special items improved by 3.6 percentage points to 13.4 percent in the third quarter of 2024 versus 9.8 percent in the prior-year quarter.
EBITDA amounted to €1.3 billion, following €1.4 billion in the prior-year period. EBITDA included special items in the amount of minus €345 million. Special charges resulted in particular in the Agricultural Solutions division from provisions in connection with the closure of the production plants for glufosinate-ammonium and the associated site closures that were announced in July 2024.
At €250 million, EBIT was €144 million below the figure of the prior-year quarter. Depreciation and amortization amounted to €1 billion, compared with €969 million in the prior-year period.
Net income was €287 million (prior-year quarter: minus €249 million). This significant increase resulted mainly from higher net income from shareholdings, primarily due to special income of €398 million in connection with the transfer of Wintershall Dea assets to Harbour Energy plc. In the prior-year quarter, special items in the amount of minus €291 million arose at Wintershall Dea.
Cash flows from operating activities amounted to €2.1 billion in the third quarter of 2024, €633 million below the figure of the prior-year period. The €674 million higher reduction in trade accounts payable was the primary reason for this decrease. At the same time, cash released from inventories decreased by €339 million compared with the third quarter of 2023. Free cash flow amounted to €569 million in the third quarter of 2024, compared with €1.5 billion in the prior-year period.
Cost savings programs on track
Chief Financial Officer Dr. Dirk Elvermann provided an update on the cost savings programs currently underway: “We are on track to achieve the targeted €2.1 billion annual cost savings by the end of 2026. The implementation of the cost savings programs announced in February 2023 is in full swing.” As of the end of September 2024, BASF has already achieved a cost reduction run rate of around €800 million. The associated one-time costs were around €500 million. By the end of this year, the company expects to achieve a cost reduction run rate of more than €800 million, with associated one-time costs of around €550 million.
BASF is also moving forward as planned with the additional cost savings program launched in 2024 that focuses on improving the competitiveness of the Ludwigshafen site. The units at the site have recently been informed about the contributions they are expected to deliver by the end of 2026.
Changes in BASF reporting
In 2022, the European Union adopted the Corporate Sustainability Reporting Directive (CSRD). Due to the extended sustainability reporting requirements under this Directive, BASF will have two publication dates going forward.
On February 28, 2025, BASF will initially publish the results for the 2024 business year as an online report in unaudited form. This will contain all important financial and non-financial figures for 2024 as well as the outlook for 2025.
The audited BASF Report 2024 will be published on March 21, 2025. It will contain all legally required financial and ESG information and will be provided in the form of an online report and as a clickable PDF. A print version will no longer be provided.
BASF Group’s outlook for 2024 unchanged
BASF’s assumptions for the full year 2024 remain unchanged:
- Growth in gross domestic product: +2.3 percent
- Growth in industrial production: +2.2 percent
- Growth in chemical production: +2.7 percent
- Average euro/dollar exchange rate of $1.10 per euro
- Average annual oil price (Brent crude) of $80 per barrel
The BASF Group’s forecast for the 2024 business year published in the BASF Report 2023 also remains unchanged:
- EBITDA before special items of between €8.0 billion and €8.6 billion
- Free cash flow of between €0.1 billion and €0.6 billion
- CO2 emissions of between 16.7 million metric tons and 17.7 million metric tons
Based on current information, BASF expects to reach the low end of the EBITDA before special items forecast range for the full year 2024. For the fourth quarter of 2024, there are risks from potential declines in prices and lower volume growth than expected. Opportunities may arise from a positive development in demand and margins.
https://www.basf.com/global/en/media/news-releases/2024/10/p-24-308
October 29, 2024
Covestro AG (CVVTF) Q3 2024 Earnings Call Transcript
Oct. 29, 2024 3:00 PM ETCovestro AG (CVVTF) Stock, COVTY Stock
Covestro AG (OTCPK:CVVTF) Q3 2024 Results Conference Call October 29, 2024 9:00 AM ET
Company Participants
Ronald Koehler – Head of Investor Relations
Christian Baier – CFO & Member of Management Board
Carsten Intveen – Investor Relations Director
Conference Call Participants
Christian Faitz – Kepler Cheuvreux
Geoff Haire – UBS
Chetan Udeshi – JPMorgan
Christian Baier
Thank you, Ronald, and hello, and a warm welcome to our third quarter call. Before coming to the business of the last quarter, let me update you on the status of the announced transaction with ADNOC. The signing of the investment agreement on 1st of October marked the beginning of a multistep takeover process, which we believe is in the best interest of our shareholders, the company and all stakeholders.
Last Friday, ADNOC published the offer document. The publication of the offer document marked the start of the initial acceptance period, which will last until November 27, 2024. A potential additional acceptance period might last from December 3 until December 16, 2024. The Board of Management, together with the Supervisory Board, will issue their recent statement in due course.
But now let us focus on the highlights of the third quarter. We delivered a continued strong volume growth of 6.1% year-on-year. However, lower prices are still affecting sales, which came in at €3.6 billion. In line with our guidance, we achieved an EBITDA of €287 million. Free operating cash flow turned positive with €112 million and was in line with our expectations. As usual, with the Q3 call, we are narrowing our EBITDA guidance range.
Turning back to the business and the volume development in the third quarter of 2024. Year-on-year, the global sales volume continued to increase by 6.1%. This is driven by an improving demand but also constantly delivering on our reliability ambition after the issues in Europe in 2022 and 2023. The volume growth rate has slowed slightly compared to H1 2024 due to a baseline effect as we were able to ramp up production already during H2 2023.
Going through different industries. Construction showed the highest growth rate, with a low teens percent increase and Furniture with a mid-single-digit percent volume increase. Electro developed flattish and Auto exhibited a low single-digit volume reduction.
Let’s now look into the different regions. In EMLA, Construction and Furniture are showing continued strong growth based on improved availability of MDI and TDI since the resolved internal availability issues. However, Auto is on a slight decline and Electro on a significant decline. And almost comparable industry picture can be observed in North America. Construction developed positively with a significant increase. Furniture is flat, but like in EMLA, Electro and Auto are showing a slight decline. APAC again, continues with stable to positive growth across all industries, important to Covestro. Construction exhibited significant growth, Furniture and Electro slight growth and Auto was flattish.
Chetan Udeshi
Okay. This is always very complicated, I have to say. Maybe you should probably think about a better way of doing it. Can I ask one thing? I saw Dow mentioned last week that they are doing a strategic review of their polyurethanes assets. And I was just curious from Covestro’s perspective, is that something that Covestro can look at? Is it even practically possible from antitrust point of view? I’m just trying to explore what possibilities we might have for a possible consolidation, if any, in the European polyurethanes market, especially after what Dow said.
The second question, I was just curious and maybe this is just following up on the previous question. You said based on historical cycles, et cetera, you think next year could also be weak for Construction and Auto. And I’m just curious if you can point me to what exactly — or which historical cycles are you referring to?
Christian Baier
Chetan, I’m very happy to comment on maybe just on the last one with respect to Construction and Auto, we said that we have seen on the side of Furniture and Electro which have now stabilized. We have seen slightly longer periods of weakness from that overall perspective. And while this is not an academic read across into Construction and Auto, and there is a little bit of a perspective that this could be somewhat ongoing. That’s what we are properly preparing for, there is no better crystal ball that we have on those.
And certainly, when we look into Construction, especially from a seasonal perspective, we’d rather see that developing from Q2 next year onwards rather than from the beginning of the year. But that’s as far as it goes with respect to our expectations on that.
With respect to the topic of Dow, they have put their European pure assets into a strategic review. We are talking here about 3 MDI assets that they have spread across Europe. We are talking about polyol assets on that perspective. Let’s see what the outcome will be of the review that they are going forward. We certainly, in any of the movements in the overall industry would be open-minded on the various pieces that would be developing and watching that situation closely.
October 29, 2024
The Potential Ban of PO Chlorohydrin and its Impact in China
By Tobias Spyra
6 min read | Jul 03, 2024
The potential ban of PO chlorohydrin and its impact on China’s polyether polyol production
By Tobias Spyra, Director, Research and Analysis
Propylene oxide (PO) is a key ingredient in producing polyether polyols and propylene glycols and is a key component of many surfactants and detergents. The Chinese ‘National Development and Reform Commission’ has recently made headlines by amending its ‘National Restructuring Guidance Catalogue’ to gather industry and university feedback on the potential ban of certain chemicals or production routes. The 2023 edition called for PO production using the “first generation” technology of chlorohydrination to be banned going forward in China. It is not the first time this move has been raised, and it indicates that PO chlorohydrin in China has been shrinking in production and nameplate capacity.
Transition from Peak Production to Advanced Technologies in Propylene Oxide Manufacturing
Despite these regulations being discussed since 2011, PO production via chlorohydrination peaked in 2017 at over 2 million metric tons in China. This proves that the guidance distributed by these journals takes time to digest and still takes longer to be acted upon by industrial participants. The other main contributor was that the peak of chlorohydrination production resulted from prior large investments in this sector, with the inauguration of projects coinciding at a time when the industry was supposed to move away from this production route.
Moving on from this peak in production, the rationalization of older and smaller assets paved the way for investment in new technologies, particularly the Propylene Oxide-Styrene Monomer (POSM) process—where both PO and styrene monomer are produced—and the Hydrogen Peroxide to Propylene Oxide (HPPO) process.
Process of Chlorohydrination
The process of chlorohydrination is three steps. Chlorination forms intermediate propylene chlorohydrin and hydrochloric acid by-products; this is followed by rectification or distillation, which allows the mixture to be purified and by-products separated using their various boiling points. The final step, saponification, involves caustic soda or lime milk treatment to generate the final PO product and a salt by-product.
One advantage of the PO chlorohydrin process is that PO is derived without any major co-product compared to the POSM or Propylene Oxide-Tertiary Butyl Alcohol processes (PO TBA), with the latter generating tertiary butyl alcohol (TBA) as a by-product. These production methods have been the subject of major investments in China and the United States. Another advantage that chlorohydrination has over more modern technologies is that it can use lower-purity propylene.
Even with these potential advantages, the process is much more complex due to the large amounts of chlorine, wastewater and base (caustic or lime) required. Over time, the nature of these components also leads to extensive equipment corrosion, requiring regular replacement and, hence, cost.
While attempts have been made to alter the reactants used, such as replacing lime milk with sodium hydroxide (NaOH) to reduce waste liquid through recycling steps, alterations have been too time/energy-intensive to warrant mass adoption. Dow Chemicals and Lummus are just two companies that tried to optimize this process to contain contaminated water, off-gases, and residues and curtail energy consumption. Yet the capital expenditure (CAPEX) of these adjustments is simply too high for many participants who might already be at their marginal limit.
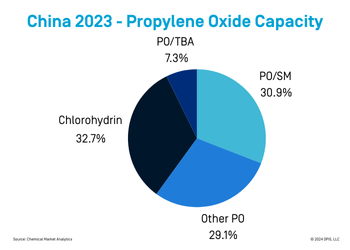
With the Chinese government encouraging environmentally friendly production, closing older, smaller chlorohydrination assets has been considered ahead of rationalization waves that come through the market. However, this movement towards environmentally friendly routes could be overestimated, as production capacity via this route has decreased to 1.6 million metric tons in 2023. Although this accounts for 26% of Chinese production, with Chinese operating rates dropping to 50 % in recent years, the continuation of chlorohydrination as a prominent pathway is in doubt.
Shift in PO Production Methods
Companies are increasingly adopting new methods and phasing out the chlorohydrination process, with many licensing technologies such as POSM from firms like Repsol. In other cases, joint ventures have been formed, such as Shell and CNOOC’s partnership at the petrochemical complex in Huizhou, Guangdong Province, China, another POSM asset.
Hence, PO production is expected to decline further in China. Rationalization could possibly extend to other regions, as evidenced by Dow closing capacities in Freeport in 2022 and 2025. This will increase the market share for different methods of PO production. Despite the downtrend in capacity, the PO market remains oversupplied, affecting the polyurethane industry and upstream chlorine and caustic soda (chlor-alkai) sectors.
Gain comprehensive analysis into long-term outlooks:
Of the global polyether polyols markets
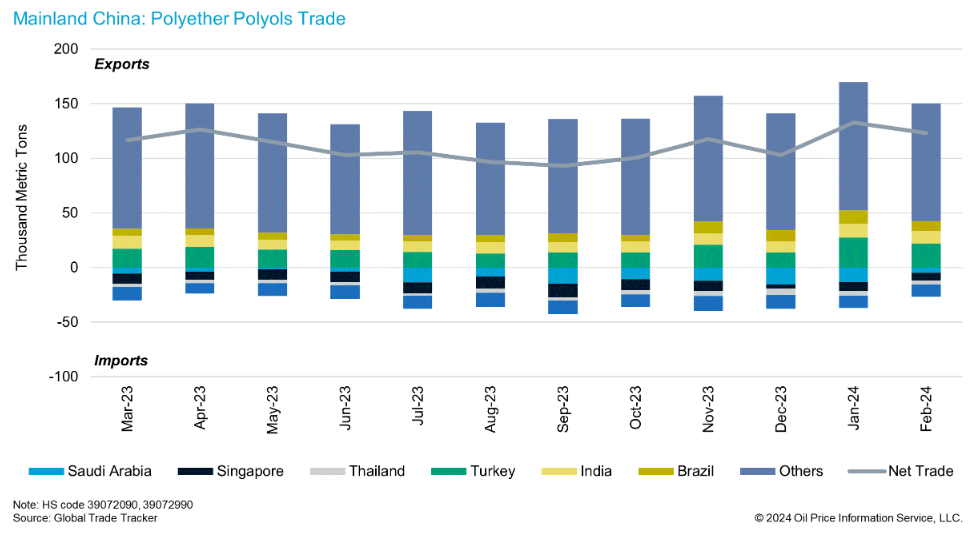
Another indicator of the declining interest in chlorohydrination is the derivative exports from China, primarily polyether polyols and propylene glycol. For polyether polyols production, the impact is minimal since the chlorohydrin route mainly serves propylene glycol production or PO itself. Larger companies and state-owned manufacturers have transitioned away from chlorohydrination for polyether polyols, reducing the impact on overall production, regional consumption, and global trade. Additionally, investments in polyether polyols and expansions in China occurred after the PO overbuild, leading to polyols capacity being built without upstream integration due to the existing feedstock abundance. Thus, the impact of the supply chain is minimal.
Technological Shifts and Global Implications
It is important to note that beyond advancements in PO technology or upstream integration, Chinese and Asian producers have increasingly focused on exporting their excess capacity. Adopting more environmentally friendly production methods—including reducing wastewater and CO2 emissions—has become a significant advantage for marketing their products globally. This trend is expected to continue and strengthen with compounding economies of scale.
China maintained a balanced import and export market before the COVID-19 pandemic, with net trade at 500 kilotons on each side. Since 2019, exports have nearly tripled to 1.5 million metric tons, turning all eyes to the country as the world’s preeminent production source moving into the future.
Larger companies and state-owned PO manufacturers have switched technologies or built new complexes while closing chlorohydrin routes. This is expected to have a limited impact on polyether polyols production, regional consumption, or global trade. The path forward for Chinese and Asian players is to export excess capacity to the rest of the world. Offering an environmentally friendlier route, with lower water and CO2 emissions, will help promote these products in the global market. This trend is expected to strengthen due to economies of scale.
The impact of such technological shifts on PO and polyol production in other regions should also be considered. Dow has closed PO chlorohydrin capacity in the United States and will do so again in 2025, affecting the local market. LyondellBasell, a major PO producer integrated into propylene glycols, has published a strategic review of its European assets, which may suggest further divestments or idling of capacity linked to the PO chain.
 Everchem Updates Archive
 Sign Up for Email Updates