
The Urethane Blog
September 9, 2024
Oil Rises As Major US Refineries In Path Of Strengthening Gulf Storm
by Tyler Durden
Monday, Sep 09, 2024 – 08:45 AM
Oil and gasoline futures moved higher early Monday as the National Hurricane Center tracked a potential tropical system that threatened parts of the US Gulf Coast later this week. The storm could slam into the upper Texas and Louisiana coasts, accounting for about 60% of US refining capacity.
Potential Tropical Cyclone Six, or Invest 91L, churns in the southwestern Gulf of Mexico early Monday and is forecasted to become a hurricane before it reaches the northwestern US Gulf Coast late Wednesday. The storm emerges right on time, at the peak of the Atlantic hurricane season. It is interesting to note that this hurricane season has been very quiet.
“While it is too soon to pinpoint the exact location and magnitude of impacts, the potential for life-threatening storm surge and damage winds are increasing for portions of the Upper Texas and Louisiana coastlines beginning Tuesday night,” the NHC wrote in its latest update.
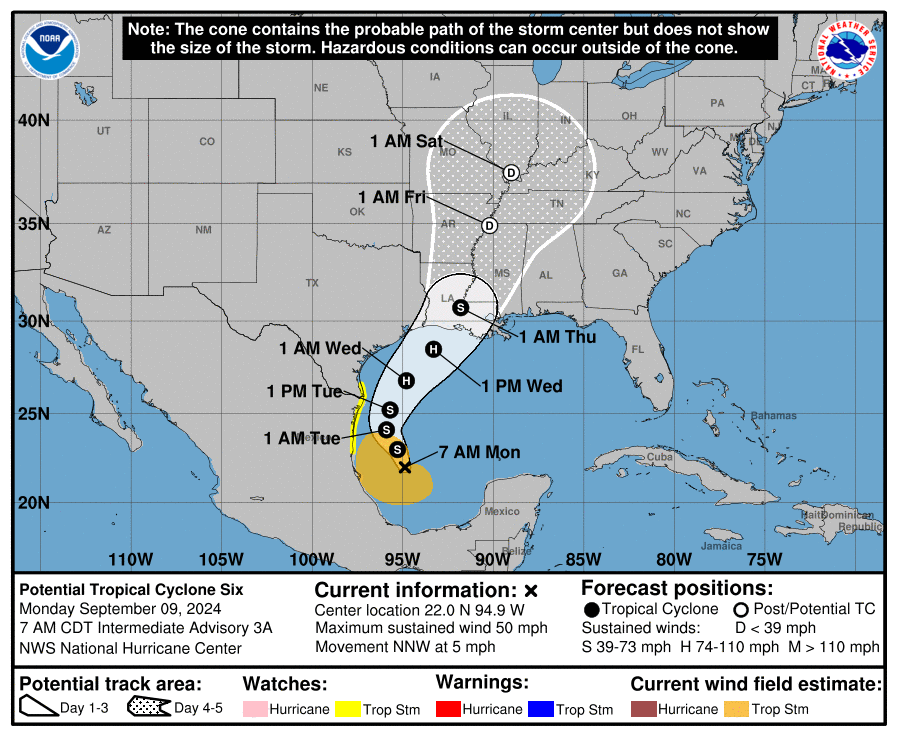
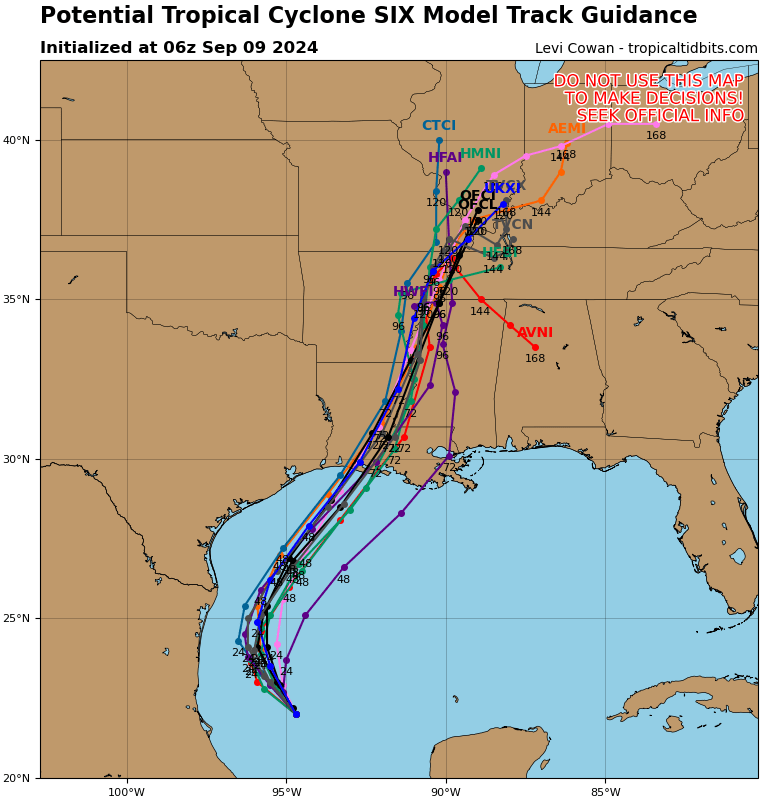
The latest hurricane trajectory models show strong consensus that the tropical system could make landfall along the Louisiana coast.
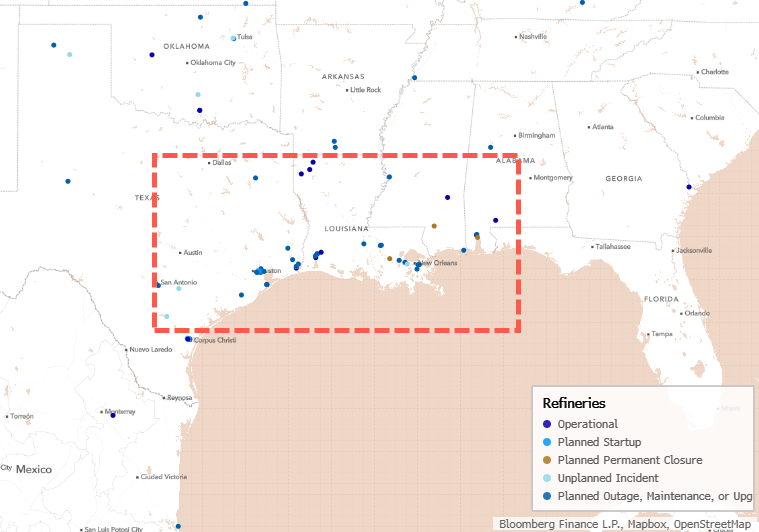
This area of the Gulf Coast is home to approximately 60% of US refining capacity. Bloomberg data shows several refineries are in the storm’s cone of uncertainty.
“A small recovery in prices is underway this morning, inspired by hurricane warnings that might threaten the US Gulf Coast, but the wider conversation remains on where demand will come from and what OPEC+ can do,” PVM analyst John Evans told Reuters.
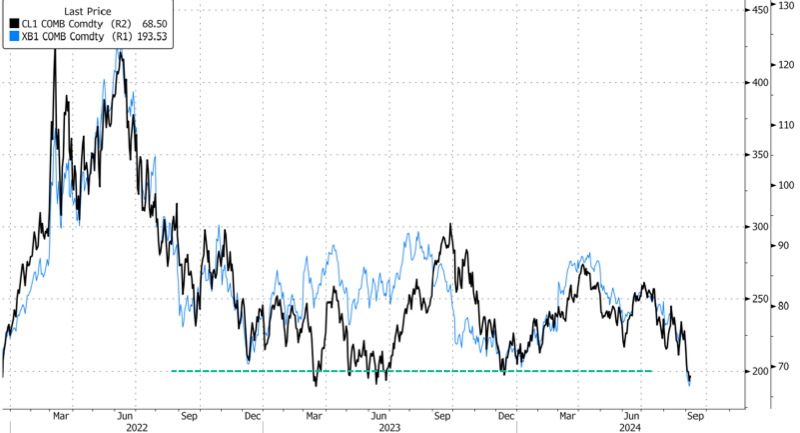
In recent weeks, Goldman’s commodity analyst—now without “supercycle” permeable Jeff Currie—Daan Struyven slashed his expected range for Brent oil prices by $5 to $70-$85 per barrel, citing weaker Chinese oil demand, high inventories, and rising US shale production. The biggest driver for the cut is his belief that “OPEC will raise production in Q4…”
Morgan Stanley has also recently revised its oil price forecasts downward, reflecting expectations of increased supply from OPEC and non-OPEC producers amid signs of weakening global demand. The bank now anticipates that while the crude oil market will remain tight through the third quarter, it will begin to stabilize in the fourth quarter and potentially move into a surplus by 2025.
Morgan Stanley has cut its forecast for the fourth quarter to $80 per barrel, down from $85, and now expects prices to gradually decline to $75 per barrel by the end of 2025, slightly lower than their previous estimate of $76.
None of this is new to the market, where sentiment is ultra-bear…
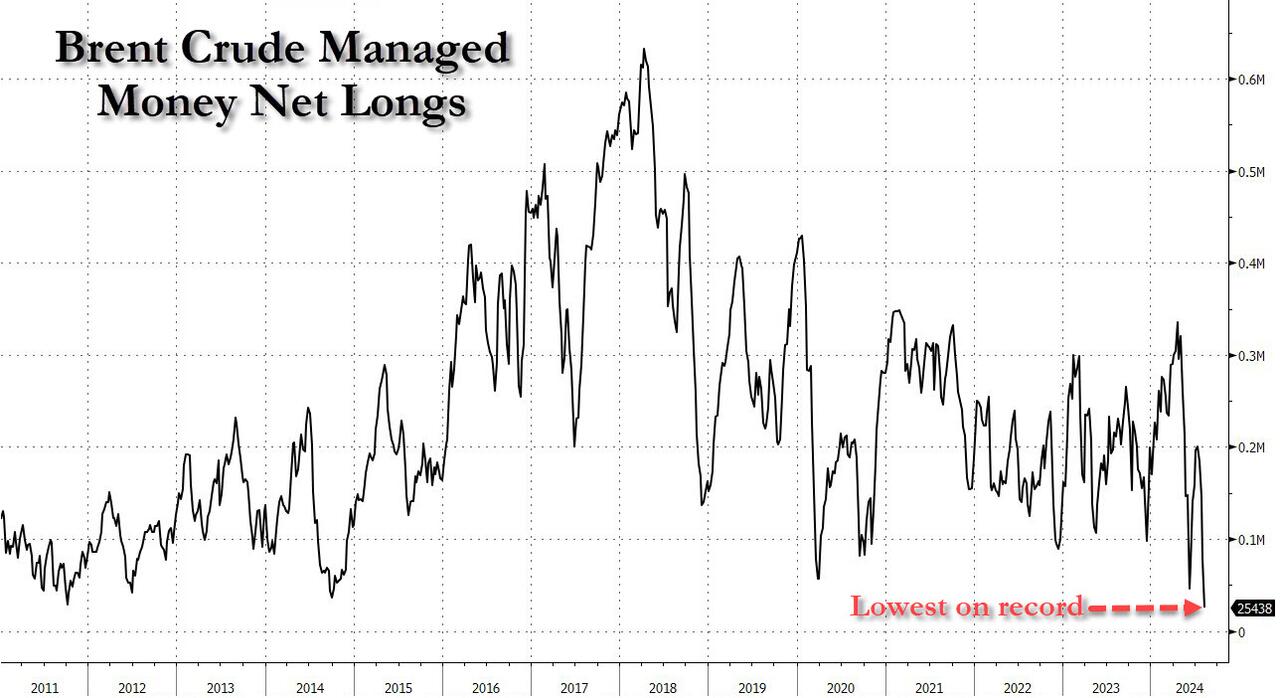
However, a tropical system that supercharges in the Gulf of Mexico’s warm waters and knocks out a few refineries could easily send energy prices back up.
https://www.zerohedge.com/commodities/oil-rises-major-us-refineries-path-strengthening-gulf-storm
September 9, 2024
Henkel and 4JET revolutionize silent tire production for EVs

Share LinkedIn Twitter Facebook Email

L-R: Dr. Armin Kraus, co-CEO at 4JET, Imke Vogel, Market Segment Head Automotive Components Europe at Henkel, Dr. Jan Flohre, Head of Laser Process Development at 4JET and Dr. Rainer Schönfeld, Global Market Strategy Head Automotive Components at Henkel.
As EVs lack engine noise, tire rolling sound becomes more noticeable, often perceived as intrusive and unpleasant. To combat this, manufacturers have been equipping EVs with “Silent Tires,” featuring acoustic polyurethane foam linings. However, this solution has presented logistical and cost challenges, increasing tire production expenses by up to 25%.
The new Laser-Fit process, developed by Henkel and 4JET, promises to streamline production and reduce costs. This method involves creating acoustic foam directly inside the tire from liquid materials at the end of the production line, eliminating complex logistics and manual steps.
“Our new to market Loctite Laser-Fit acoustic foam achieves its sound absorption effect through a large inner surface and a pore design specifically tailored for tire noise suppression,” said Dr. Rainer Schönfeld, Global Market Strategy Head in Henkel’s Automotive Component business unit.
The process utilizes a patented laser activation technique to remove the foam’s air-impermeable skin, allowing for effective sound absorption. This innovation not only simplifies production but also offers manufacturers greater flexibility in foam design and reduces waste.
“This revolutionary direct-foam-to-tire technology represents our joint commitment to innovation and sustainability,” said George Kazantzis, Global Head of Henkel’s Automotive Components business unit. “By eliminating the transportation of pre-fabricated foam and reducing cutting waste, we will enable our customers to lower their carbon footprint.”
The partners developed this technology in record time, showcasing the innovative strength of German SMEs. Dr. Armin Kraus, co-CEO of the 4JET Group, praised the collaboration: “In Henkel, we have found the ideal development partner for this innovation… From the idea to the finished application in record time.”
The complete solution will be presented at RubberTech24 in Shanghai this month, marking, the companies hope, a significant advancement in EV tire technology.
www.electrichybridvehicletechnology.com/news/henkel-and-4jet-revolutionize-silent-tire-production-for-evs.html
September 5, 2024
Single-family demand is up, multifamily construction down
By Dakota Smith
September 3, 2024 | 10:12 am CDT

A lack of resale homes and pent-up demand more than offset high mortgage rates and contributed to solid single-family permit growth across nearly all geographic regions in the second quarter. However, multifamily construction permit activity continued its slide downward across the board to the start 2024. Meanwhile, single-family and multifamily construction exhibited strong growth in second-home markets over the past decade, according to the latest findings from the National Association of Home Builders (NAHB) Home Building Geography Index (HBGI) for the second quarter of 2024.
Single family
“Despite the elevated interest rate environment, single-family construction continues to move along at a better pace than 2023 and has been led by a rebound in construction activity in high-density areas,” said NAHB Chairman Carl Harris, a custom home builder from Wichita, Kansas. “Multifamily construction continues to slow as builders deal with higher rates, a shortage of workers, and supply chain concerns for some building materials.”
“The strength in single-family construction at the start of the year continued in higher density areas, matching other data indicating a gain for townhouse construction in 2024,” said NAHB chief economist Robert Dietz. “New data on second homes points to most housing construction taking place in areas with fewer second homes, as most second family homes are located in less urban areas such as non-metro counties.”
The HBGI is a quarterly measurement of building conditions across the country and uses county-level information about single- and multifamily permits to gauge housing construction growth in various urban and rural geographies.
The single-family permit growth rates for all of the HBGI geographic regions were positive in the second quarter, with five of the seven posting double-digit gains. Large metro core counties had the highest growth rate for the second straight quarter at 17.6%. Micro counties had the smallest growth rate, posting a 3.4% gain.
All seven HBGI geographic regions posted negative multifamily permit rates in the second quarter because financing remained tight and high levels of construction inventory of just under 900,000 units are limiting the need for new multifamily permits. This weakness is consistent with the NAHB Multifamily Production Index, which had a second-quarter reading of just 44, marking a year-over-year decrease of 12 points.
Second homes
Using the latest government data on second homes, the HBGI found that 17.5% of single-family home construction and 8.6% of multifamily development occurred in second-home areas during the second quarter of 2024. NAHB defines a second home area as a county where at least 10.3% of the total housing stock consists of a second home.
The county that had the highest share of second homes was Hamilton County, N.Y., where 75.3% of homes were considered a second home based on NAHB’s definition. By contrast, Scott County, Kan.; Andrews County, Texas; Crane County, Texas; and Hansford County, Texas all had no second homes.
The 17.5% of single-family construction in second-home counties during the second quarter of 2024 is up significantly from the fourth quarter of 2014, when these second-home counties posted a single-family market share of 12.9%.
On a percentage basis, multifamily construction in second-home counties experienced a higher growth during the same 10-year span, rising from 4.6% in the fourth quarter of 2014 to 8.6% in the second quarter of 2024.
Key findings
- The year-over-year growth rates for all single-family markets further increased to positive territory, adding to the gains recorded in the first quarter. This positive news was fueled by the limited amount of existing inventory and pent-up demand for single-family construction.
- In the multifamily sector, growth rates remained negative for all markets, continuing the downward trend from last quarter. With over 900,000 apartments currently under construction (the most since 1973) and tighter financial conditions, multifamily construction is slowing from the last year’s highs.
- Labor shortages, supply shortages and higher mortgage rates continue to be issues for both the single-family and multifamily markets.
The full HBGI data with geographic market shares and growth rates can be found here
September 3, 2024
Unveiling New VOC Tax Policy: Challenges and Opportunities of Green Transformation in PU
PUdaily | Updated: September 3, 2024
On July 31, 2024, Wang Dongwei, vice minister at China’s Ministry of Finance, announced an important decision at a press conference held by the State Council Information Office that volatile organic compounds (VOCs) will be included in the scope of environmental protection tax. This decision not only signifies a further improvement in China’s tax system but also marks a significant leap in the process of ecological civilization construction.
Background of the Policy
As China’s economy has transitioned to a stage of high-quality development, environmental protection and ecological civilization construction have been increasingly emphasized. VOCs are precursors to fine particulate matter (PM2.5) and ozone (O3) among other secondary pollutants, posing a serious threat to air quality and human health. Therefore, the inclusion of VOCs in the tax scope has become inevitable for environmental governance and pollution control.
Looking back, China’s VOCs control has undergone a gradual deepening process from the formulation of laws to policy promotion. China’s new Air Pollution Prevention and Control Law, which took effect in 2016, first explicitly defined the legal responsibility for VOCs prevention and control. The subsequent introduction of governance measures such as the 13th Five-Year VOC Prevention and Control Work Plan and the Three-Year Action Plan to Win the Blue Sky Defense War, has continuously promoted VOC governance efforts. In January 2024, the Central Committee of the Communist Party of China and the State Council issued guidelines to comprehensively promote the development of a Beautiful China, which clearly stated the need to expedite the inclusion of VOCs in the tax scope, laying a solid foundation for the Ministry of Finance’s policy decision.
As a major source of VOCs, the polyurethane industry mainly generates them from reaction kettles, storage tanks, pipelines, finished product storage and some other production processes. The VOCs in polyurethane include unreacted isocyanates, polyols, solvents (such as DMF, DMAc, etc.), additives, and various by-products. These compounds not only easily form photochemical smog in the atmosphere, affecting air quality but may also pose health risks through respiratory pathways, skin contact, among others.
To further reduce VOC emissions in polyurethane, VOCs emission characteristics in each process have been preliminarily analyzed so as to implement targeted emission reduction measures. The methods include reducing by-products by optimizing reaction conditions, improving production processes to achieve solvent-free or low-solvent manufacturing, and perfecting waste gas collection and treatment systems.
The Impact of VOC Tax on the Polyurethane Industry
1. Deep Economic Impact and Restructuring
Reshaping Cost Structures: The introduction of tax on VOCs will compel polyurethane companies to revisit their cost structures. Apart from direct tax expenditures, businesses need to consider the indirect costs associated with upgrading, maintaining, and managing environmental protection facilities. These cost increases will have a profound impact on business strategies and financial status, prompting companies to seek more economically efficient solutions.
Rebuilding Market Competitiveness: The prices of polyurethane-related products may be adjusted accordingly with rising costs. This will change consumers’ perceptions of value, thus affecting market demand structures. Those who successfully achieve green transformation and reduce VOC emissions will become more competitive in the market.
2. Driving Forces and Challenges of Technological Innovation
Breakthroughs in Green Manufacturing: Businesses need to increase R&D investments in green manufacturing to address the challenges of VOC taxes, including exploring new catalysts, optimizing reaction routes, and developing recyclable or biodegradable materials. Breakthrough technologies will deliver significant environmental and economic benefits.
Upgrading Waste Gas Treatment Technologies: Existing waste gas treatment technologies may struggle to meet stricter environmental standards. Therefore, businesses need to focus on the latest developments in waste gas treatment technologies domestically and internationally, actively introducing and grasping advanced technologies. Furthermore, strengthening independent R&D capabilities and developing more efficient, cost-effective waste gas treatment technologies are crucial.
3. Far-reaching Changes and Opportunities in Industry Chain
Supply Chain Integration and Green Transformation: The introduction of VOC tax will prompt businesses in the polyurethane supply chain to enhance cooperation. Raw material suppliers need to provide more eco-friendly materials to support downstream manufacturers’ green transformation, while downstream manufacturers may demand higher environmental performance from products to improve their brand image and meet customer requirements. The supply chain integration will push the industry towards a green and sustainable future.
Enhancing Industry Standards and Aligning with International Standards: With increasingly stringent environmental policies and the implementation of environmental taxes, relevant standards and specifications in the polyurethane industry will be gradually enhanced, helping regulate market order, raising the industry level and promoting fair competition. Aligning with international environmental standards will also provide strong support for polyurethane businesses’ global expansion.
Strategies for the Polyurethane Industry
1. Strengthening Internal Management for Enhanced Environmental Performance
Building and improving environmental management systems, reinforcing the daily operation and meticulous maintenance of environmental facilities are crucial to support the high-quality development. Through fine-tuned management strategies, businesses can effectively control energy and material consumption, significantly reducing the emission of pollutants like VOCs, thereby contributing to environmental protection. Sustainability training for employees, integrating green concepts into each employee’s mindset to enhance their social responsibility and participation, is essential for paving the way for green roads. These measures not only showcase businesses’ environmental responsibility but also serve as key drivers for transitioning towards a better and more sustainable future.
2. Increasing R&D Investment to Promote Technological Innovation
Increasing R&D efforts in green manufacturing and air pollution control technologies, actively incorporating advanced technological achievements are strategic focuses. Beyond the industrial sphere, businesses can deepen collaborations with universities and research institutes to facilitate the conversion of research outcomes into practical applications, jointly advancing technological upgrades and industrial advancements.
3. Monitoring Policy Changes and Flexibly Adjusting Business Strategies
Businesses should closely monitor changes in national environmental and tax policies, stay informed about policy requirements and demand changes. Based on this information, flexibly adjusting business strategies and development directions ensures their sustained growth and market adaptability. For instance, adapting product structures, exploring emerging markets, or intensifying communication and collaboration with government entities based on policy trends.
4. Actively Engaging in Industry Self-Regulation and Cooperation
Polyurethane businesses should actively engage in self-regulation and enhance collaboration with industry peers. By jointly formulating industry standards and regulations, sharing technologies and experiences, they can promote industry transformation and sustainable development.
In conclusion, the impact of VOC tax on the polyurethane industry is diverse and far-reaching. Market participants need to adopt an open innovation approach to embrace challenges and opportunities actively. Green transformation and sustainable development can be achieved through initiatives such as strengthening internal management, promoting technological innovation, flexibly adjusting business strategies, and actively engaging in industry self-regulation and cooperation.
September 3, 2024
BASF to shut down adipic acid production at Ludwigshafen next year
Tom Brown
29-Aug-2024

LONDON (ICIS)–BASF is to end production of adipic acid and several downstream units at Ludwigshafen, Germany, as part of structural changes underway at the site, the company said on Thursday.
Production of adipic acid will conclude at the site over the course of 2025, while units to manufacture cyclododecanone (CDon) and cyclopentanone (CPon), which utilize adipic acid as a raw material, will cease in the first half of the year.
The company is planning to cut around €1 billion in costs from the site, with new CEO Markus Kamieth expected to fully set out what steps will be taken at the company’s capital markets day in September this year.
The company had already cut back adipic acid production capacity at the site in 2023, but had kept a some capacity onstream to feed into those downstream units.
BASF expects to cease deliveries of CDon and CPon, which are used in nylon 12 and pharmaceuticals production respectively, and is in talks with customers, the company added.
It will continue to produce adipic acid in Onsan, South Korea, and Chalampe, France, BASF added.
The decision was taken as part of the ongoing strategic review of site operations to “ensure competitiveness under changing market conditions”, the company said in a statement.
Around 180 workers will be affected by the closures, with BASF planning to explore the possibility of employment positions elsewhere within the group.
“These closures are part of the development of a long-term target picture for the transformation of the Ludwigshafen site,” said BASF industrial relations director Katja Schwarpwinkel.
 Everchem Updates Archive
 Sign Up for Email Updates


