
Pricing and Markets
February 28, 2025
Chemical Grade Propylene Up 4c/lb

Chemical Grade Propylene is $0.465/lb in February
January 15, 2025
Propylene Oxide in China
China Propylene Oxide & Polyols Market in January
PUdaily | Updated: January 14, 2025
In January 2025, due to the production of new facilities at Befar Group and Wanhua Chemical, these two suppliers in Shandong showed stronger intentions to clear inventory and cut prices by CNY 300/tonne. PO prices in East China dropped by CNY 100/tonne as a result. The price difference between the North and the South widened, leading to slightly varied sales performance. Meanwhile, recent import prices for PO have been continuously decreasing, with the latest offer at USD 990/tonne.

In terms of import, China’s import volume of PO has been declining in recent years and the annual import volume for 2024 is estimated to total 250 kT, marking a more than 20% decrease compared to the previous year.

As Chinese New Year approaches, downstream manufacturers are increasing purchases at relatively low prices, while the growth in new orders has been muted. Suppliers may maintain willingness to sell and negotiate. With ongoing inventory reduction, the market is projected to fluctuate slightly in the near future.
Prices for flexible slabstock polyols have moved down due to reduced costs. However, the drop in polyols prices is less than in PO prices, resulting in increased profits for polyols producers. Acrylonitrile prices have risen from CNY 9,400/tonne to CNY 10,500/tonne, causing a shrink in profits for polymer polyols. It is expected that the acrylonitrile market will remain high next week. Owing to limited supply increases and low inventories, coupled with the pre-holiday restocking blitz, the market is likely to keep resilient.
January 6, 2025
Chinese PMDI Overview
Will China’s PMDI Market Continue Its Upsurge in 2025?
PUdaily | Updated: January 3, 2025
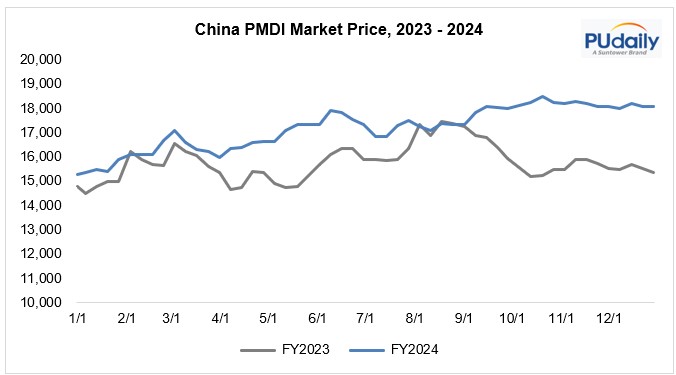
On December 31, 2024, China’s PMDI market closed at a range of CNY 18,100-18,300/tonne, reflecting a remarkable increase of CNY 2,800/tonne (+18.2%) compared to the range of CNY 15,300-15,500/tonne at the end of December 2023. The average price of PMDI in China in 2024 stood at CNY 17,200/tonne, remaining basically same with the yearly average in 2022. The market price in 2024 indicated an upward trend. In December, as most suppliers had completed sales targets and halted or reduced deliveries, PMDI supply remained tight. Many distributors had no stock nor quotations, awaiting shipments from suppliers in the upcoming month.
In Supply Side
In 2024, PMDI suppliers’ pricing strategies and inventory management practices maintained PMDI social stocks at low levels.
In February, global oil prices increased during the Chinese New Year holiday, then China benzene market followed to increase, leading to increased PMDI production costs, pushing major MDI suppliers to raise list prices, then distributors followed to increase their quotations.
However, in late February, sudden severe cold weather across several regions in China delayed resumption of production and procurement for raw materials including PMDI in downstream sectors, leading to insufficient support for PMDI price increases. PMDI prices moved down in March.
In April, as it turned warmer, demand picked up gradually in construction sectors. but PMDI supply was relatively slow, leading to further depletion of spot inventories and a rebound in PMDI prices.
The uptrend continued during May and mid-June.
The market faced a marginal retreat due to off-season factors towards the end of June until August, and picked up again from September onwards.
In November and December, the price stabilized in the range of CNY 18,000-18,500/tonne.
In Demand Side
The downstream sectors for PMDI include home appliances, building insulation, cold chain logistics, transportation., etc. Home appliance is currently the largest downstream sectors of PMDI demand markets in China. Thanks to trade-in policies and leading home appliance companies’ ambitious actions on exploring overseas markets, both domestic sales and exports of refrigerators in China saw unexpected growths in 2024, contributing to ongoing increases in refrigerator production. The growth in international trade, the upturn in container shipping segment and incidents like Red Sea Crisis brought substantial orders for Chinese reefer container and LNG carrier manufacturers. In addition, Chinese PMDI exports from January to November 2024 rose by 11.5% year on year.
Looking ahead to 2025, suppliers’ pricing and inventory management are expected to maintain stable support to the market. In terms of demand, China set top of key tasks for 2025 at the Central Economic Work Conference as “vigorously boosting consumption, improving investment efficiency and expanding domestic demand on all fronts”. The conference prioritized supporting expanding domestic demand, particularly in consumer demand, which in turn will have a positive effect on industries like automobiles and home appliances. Furthermore, as 2025 marks the conclusion of China’s 14th Five-Year Plan (2021-2025), most market participants are observing the support given by the national and local governments in infrastructure projects. Despite market concerns about the risks associated with U.S. tariffs, which may impact on PMDI prices and export business of PMDI-based products from China to the U.S., Chinese PMDI market is projected to continue its upsurge driven by bullish factors in both supply and demand sides.
October 31, 2024
Chemical Grade Propylene Falls 6c/lb
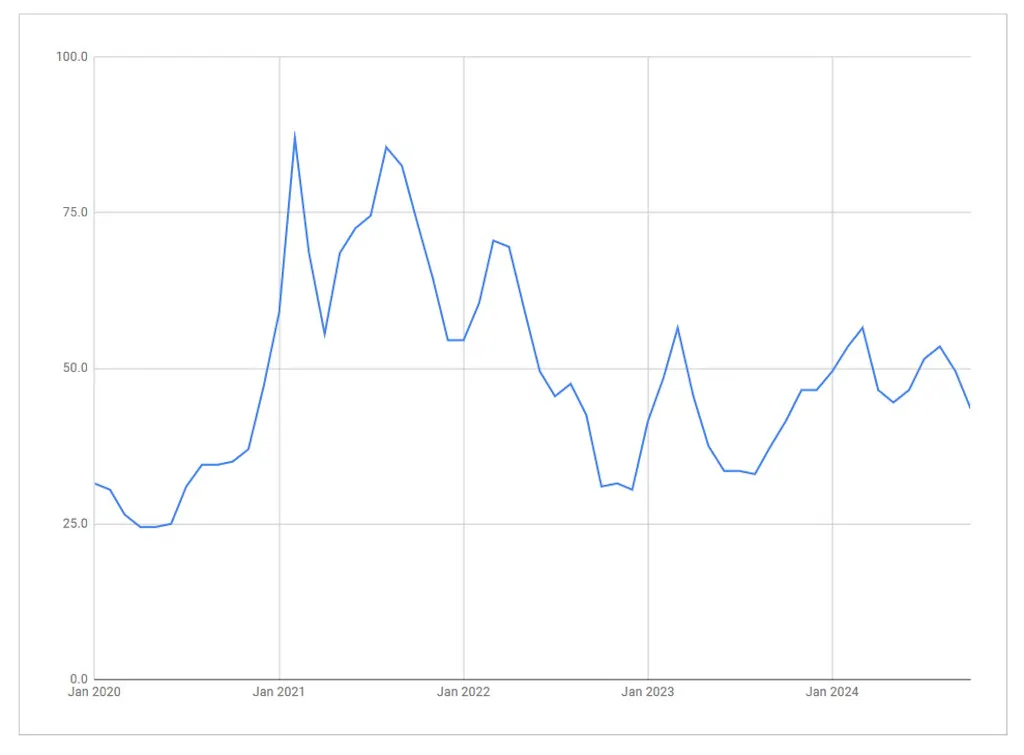
Chemical Grade Propylene is $0.435/lb in October
October 20, 2024
Isocyanates Update
PRICING Global MDI and TDI markets face supply tightness and varied demand

MDI North America
The MDI market has been under pressure due to tight supply and demand continues to be healthy. Dow was reported to have declared force majeure at its 340 ktpa MDI plant in Freeport, Texas after hurricane Beryl and the turnaround is expected to be lifted after the producer completes a turnaround at the site in October. Demand for MDI has remained stable from most sectors. The construction sector is seeing good levels even though stats showed a decline in the housing sector. Prices could remain high as supply is tight due to turnarounds and demand is steady.
MDI Europe
The MDI market has been quiet as the holiday season was underway. Supply is still available even though operations have been reduced. Borsodchem maintenance at its MDI unit in Kazincbarcika, Hungary started at the end of July and completed mid-August. Huntsman is planning to have a turnaround at its Rozenburg, the Netherlands site in Q4. Covestro is reported to have its annual turnaround at its 400 ktpa MDI plant in Brunsbüttel, Germany during September. Demand was weak due to the holiday season in most of Europe. Demand from the insulation and other construction related applications are heard to be improving. Demand from the comfort industry is still weak. Demand from all sectors is expected to pick up somewhat from September as the market resumes after the summer period.
MDI China
The Chinese domestic MDI market price showed an upward trend in Q3 due to low supply availability. MDI units operated at around 50% capacity in August. On the demand side, there was little change in downstream orders, as the macroeconomy environment remained weak. Buyers reported that MDI prices remained high in the market. Most procurement was for immediate use, primarily in traditional industries such as foaming agents, spraying, and asphalt.
TDI North America
The TDI supply situation in North America is heard to be stable and reports suggest supply is currently on the long side. Demand remains stable, with offtake volumes from the construction sector reported as steady. In terms of TDI prices, prices ended August on the softer side due to low demand levels and healthy supply. TDI prices are expected to be stable to higher in the short term as supply is expected to tighten somewhat in Q4 due to turnarounds.
TDI Europe
TDI supply in Europe has been reduced and is not expected to improve leading to price firming. Covestro is reported to have its annual turnaround at its TDI plant in Brunsbüttel, Germany during September. Demand has been slow over the last couple of months in some southern European countries as downstream plants were shut for the summer holidays. A summer slowdown had been expected but this year it has been worse than previous years. Demand usually picks up again in September as downstream plants return to operation following the summer holidays but so far this has not been the case. August was the weakest month of the year and September levels are really low so far in the month.
TDI China
The Chinese market firmed in August due to low supply levels as maintenance turnarounds took place at a number of plant. TDI units operated at around 50%. News of these significant maintenance activities spurred increased market activity, pushing prices up in August. However, a lack of further orders from buyers stabilised prices as the end date of the maintenance approached, TDI price softened in the last few days of August. Downstream demand remained weak in line with the traditional off-season. Upholstered furniture buyers maintained a high inventory level and resisted the price increase.
Polyether Polyols North America
The polyether polyol market in the US is balanced and stocks are being rebuilt and availability is sufficient. In general though, the supply/demand picture for polyether polyols remains balanced, and there are no reported problems with availability. Demand has been steady again in August, as it has been for much of the year so far. Demand for rigid polyether polyols into construction and appliances is stable and expected to remain so over the next few months. Demand into auto applications is also said to be steady but lower than expected. Demand for flexible polyether polyols into furniture and bedding is described as stable.
Polyether Polyols Europe
The polyether polyol market slowed further in August as demand declined. Supply levels are stable even though there are production issues upstream. A market participant mentioned concerns about PO availability, as there have been operational issues at some PO plants recently. Consumers say that the impact of these PO production issues on polyols, thus far, has been limited as inventories are sufficient to meet current demand levels. Demand has weakened during the summer months and a modest increase in demand is expected for September/October.
Polyether Polyols China
In China, polyether polyols prices have softened due to fluctuation in PO markets and weak demand. On the supply side, operating rates remain stable, and supply also remained steady. Polyether polyols prices softened due declining PO prices. Although buyers showed stronger purchasing intent mid-August, the increase in offtake volumes was not sustained, and prices eventually resumed their downward trend. Demand for polyether polyols saw non-significant improvement. Export orders remained robust, but major manufacturers are supply mostly to long-term contracts and adopted a wait-and-see attitude. Procurement in the distribution channel was mainly for immediate use.
Regina Sousa is a senior consultant at Tecnon Orbichem.
 Everchem Updates Archive
 Sign Up for Email Updates
