
Asian Markets
April 2, 2024
Rigid Foam Used in LNG Carriers
China’s Accelerated Construction of LNG Carriers and Receiving Terminals Drives Demand for Rigid Foam
PUdaily | Updated: March 29, 2024

4 Carriers Built Simultaneously in the Same Dock in Shanghai, Accelerating Construction of Large LNG Carriers
On March 24, inside the No. 2 dock of the Changxing shipbuilding base at China State Shipbuilding Corp’s Hudong-Zhonghua Shipbuilding (Group) Co., Ltd, four LNG carriers under construction were densely arranged. Two of these carriers were launched on the same day, while the other two were half-floated. Huadong-Zhonghua Shipbuilding is for the first time building four 174,000-cbm liquefied natural gas (LNG) carriers simultaneously in the same dock. This milestone signifies a new record in LNG carrier construction for the company, set to become a regular practice in the future. 2024 is a crucial year for the shipbuilder’s plans to double LNG carrier production capacity. Hudong-Zhonghua currently has more than 50 LNG carriers on order, including more than 30 fifth-generation vessels, with delivery dates stretching until 2028, positioning it as a pioneer in global LNG carrier sector.
Continued Surge in Global Demand for LNG
Global trade in LNG reached 404 million tonnes in 2023, up from 397 million tonnes in 2022, showing a 1.76% year-on-year increase, with tight supplies of LNG constraining growth, according to Shell LNG Outlook 2024. Natural gas demand has already peaked in some regions like Europe, Japan and Australia, but globally is set to continue growing. Shell predicts that global demand for LNG will rise by more than 50% by the year of 2040, reaching around 625-685 million tonnes per year. Looking at the phased growth, China is poised to dominate LNG demand growth this decade as its industry seeks to cut carbon emissions by switching from coal to gas. Over the following decade, declining domestic gas production in parts of South Asia and South-east Asia could drive a surge in demand for LNG as these economies increasingly need fuel for gas-fired power plants or industry. However, countries in South Asia and South-east Asia would need significant investments in gas import infrastructure.
China’s LNG Outputs and Imports Both Grew, with Robust Expansion of LNG Receiving Capacity
As the transition from coal to gas in its industry accelerates and the push for net zero emissions continues, the share of natural gas in China’s energy mix is steadily rising, making China a key driving force for global natural gas industry growth. China’s natural gas output reached 230 billion cubic meters in 2023, maintaining an annual increase of 10 Bcm for seven consecutive years, according to National Energy Administration. In the same year, China’s LNG imports totaled 71.32 million tonnes, a 12.6% year-on-year increase (source: General Administration of Customs of China), surpassing Japan once again to become the world’s largest LNG importer.
On the other hand, China achieved a historical high in newly added LNG receiving capacities. There were six LNG terminals projects, including new and expansion projects, which started operations in 2023, adding a capacity of 18.8mtpa, bringing China’s total LNG receiving capacity to 116mtpa at the end of 2023, with 28 LNG receiving terminals were operational. China is expected to add ten LNG receiving terminals in 2024, most of which are scheduled to commence operations by year-end, raising China’s LNG receiving capacity to 170.29mtpa, an increase of 40.75mtpa from 2023.
Polyurethane Application in LNG
The growth in demand for LNG carriers, onshore LNG storage facilities (such as LNG-FSRUs – Floating Storage and Regasification Units, LNG-FPSOs – Floating Production Storage and Offloading Units), and a series of transportation and storage facilities has boosted the demand for PU insulation materials, especially reinforced PU insulated panels. For example, in the construction of LNG carriers, as shipowners increasingly focus on reducing evaporation to decrease LNG losses, LNG containment systems are transitioning from traditional GTT-NO96 membrane technology to new structures such as NO96-L-03+, MARK-III, and MARK-III Flex. Insulation materials are also transitioning from insulation boxes filled with expanded perlite to fiberglass-reinforced PU panels. Moreover, PU insulation materials are also used in LNG pipelines and storage facilities. The consumption of PU rigid foam in Chinese LNG sector saw a growth of over 30% in 2023, according to PUdaily.
February 25, 2024
Yantai’s Push for Sustainability
Yantai ascends beyond trillion yuan milestone with eye on sustainable innovation
In a landmark achievement for 2023, Yantai’s GDP soared to 1.02 trillion yuan (approximately $141.31 billion), making it the third city in Shandong and the 26th in China to surpass 1 trillion yuan.
The city’s ambitious strategy for acquiring projects has yielded remarkable results, with 485 projects signed into effect and 89 policies implemented in 2023, both record highs. These achievements have notably improved Yantai’s business environment, earning it a spot among the top 10 cities in China in terms of business climate.
Innovation is at the core of Yantai’s economic agenda, with significant investments made in critical sectors like aviation, nuclear power, and marine equipment.
The Yantai Chemical Industrial Park, nestled in the Huang-Bohai New Area, epitomizes the city’s ambition for upscale, sustainable production. The park has outlined an annual investment of 40 billion yuan across 40 city-level industrial projects, all of which have kicked off construction, with 11 billion yuan already invested, providing a strong foundation towards meeting this year’s objectives.
Home to global industrial giants, the park is poised to exceed 200 billion yuan in output within the next five years, highlighting Yantai’s dedication to green, low-carbon development and innovation.
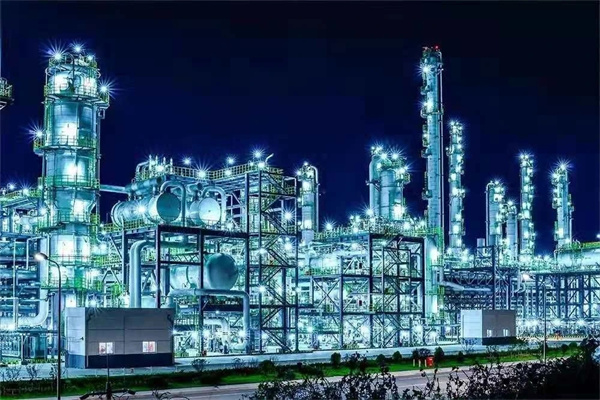
The Wanhua Chemical in Yantai Huang-Bohai New Area. [Photo by Guo Chuanyi for chinadaily.com.cn]
Yantai’s commitment to sustainability is further demonstrated by the Laishan floating photovoltaic power station, China’s first sea-based floating solar power facility. This groundbreaking project, developed by CIMC Raffles, marks a significant leap forward in clean energy, with the capacity to power numerous homes and underscoring Yantai’s leadership in renewable energy innovation.
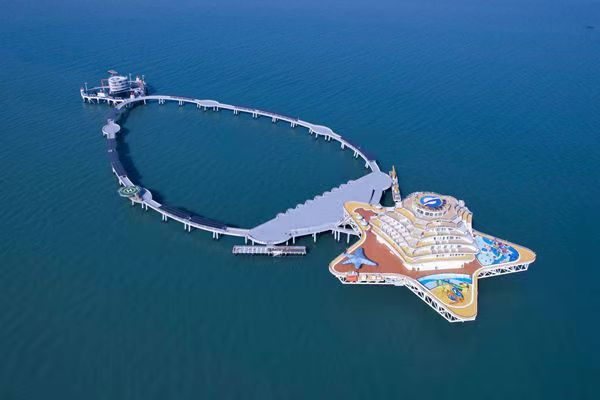
An aerial view of the “Genghai No 1” marine ranch complex located in the waters of the Laishan district. [Photo by Yu Fengyuan for chinadaily.com.cn]
In Longkou city, there has been a noticeable shift towards high-end manufacturing, as the traditional automotive industry transitions to new energy vehicles and other advanced sectors. The rapid growth of China’s automobile exports is evident in this area, with pure car and truck carriers manufactured at the CIMC Raffles Longkou base recently shipped from Longkou Port to Shenzhen via Yantai. They were carrying over 5,000 domestically produced new energy vehicles destined for Europe.
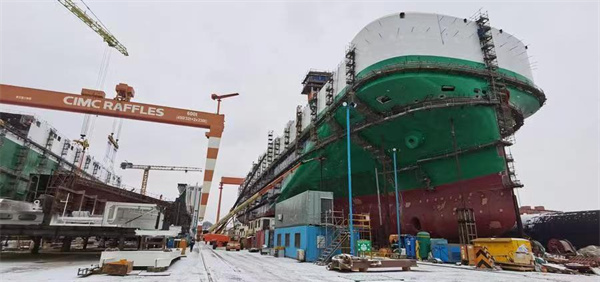
The shipyard production line of CIMC Raffles is engaged in the manufacturing of pure car and truck carriers. [Photo by Xie Hongyu for chinadaily.com.cn]
Yantai’s industrial strength and innovative spirit position it for continued success, solidifying its status as a leading city both regionally and nationally.
With a vision set on becoming a central city in the Huang-Bohai region by 2035, Yantai is fast-tracking the development of a green, low-carbon, and high-quality development model city, marking a new chapter of ambitious goals and sustainable growth.
February 6, 2024
Wanhua 2023 Results
Wanhua Chemical Group Co., Ltd. Reports Earnings Results for the Full Year Ended December 31, 2023
February 02, 2024 at 04:51 pm IST

Wanhua Chemical Group Co., Ltd. reported earnings results for the full year ended December 31, 2023. For the full year, the company reported sales was CNY 17.54 million compared to CNY 16.56 million a year ago. Net income was CNY 1.68 million compared to CNY 1.62 million a year ago.
Basic earnings per share from continuing operations was CNY 5.36 compared to CNY 5.17 a year ago.
January 25, 2024
Chinese MDI Overview
China MDI Market Review 2023
PUdaily | Updated: January 19, 2024
China MDI Market Review 2023
In 2023, China MDI market experienced periods of downturn followed by rebound, with a narrowing price range. The yearly PMDI price was CNY 15,808/tonne, dropped by 8.3% year-on-year. The yearly MMDI price was CNY 19,991/tonne, dropped by 3.8% year-on-year. Despite both PMDI price and MMDI price dropped, the overall trend of “downturn followed by rebound” throughout the year reflects a gradual recovery in China MDI market.
In the first two months of 2023, MDI facilities in Ningbo and Chongqing underwent maintenance, leading to a significant decrease in operating rates. Suppliers either reduced supply or controlled deliveries. Additionally, due to the anticipated recovery of domestic demand from March, suppliers increased their guide prices and traders followed suit. From March to May, facilities undergoing maintenance gradually resumed production, but demand recovery fell short of expectations. Construction was under pressure due to the real estate downturn and macroeconomic factors. Major downstream sectors of MMDI such as spandex saw decreased operating rates, as did PU resin for shoe sole and PU resin for synthetic leather. The momentum for price increases in the MDI market weakened and experienced a pullback. From June to August, the news of maintenance from suppliers in Shanghai, Yantai, and Ruian drove a resurgence and stabilization in the MDI market. Meanwhile, the shipments of PU panels increased compared to the previous months. Operating rates of TPU and spandex, downstream sectors of MMDI, saw increases, expanding demand for MDI. However, from October to December, as the off-season for downstream industries such as building insulation arrived, the MDI market once again weakened and moved at a low level.

China’s MDI Output Amounted to 4 Million Tonnes, Up 12% YoY; MDI Demand Totaled 3.15 Million Tonnes, Up 14% YoY.
In 2023, China’s MDI output amounted to around 4 million tonnes, increased by 12% year-on-year, with an average operating rate of 91%. Wanhua Chemical’s 400 ktpa MDI facility in Fujian, which commenced operations at the end of 2022, effectively utilized its capacity within the year. Meanwhile, China’s MDI demand showed a restorative growth. In 2023, MDI demand in China totaled around 3.15 million tonnes, representing a 14% year-on-year increase, significantly outpacing China’s GDP growth rate (5.2%). The downstream industries of PMDI that displayed significant growth included refrigerators, PU panels, and formaldehyde-free panels (woodbinder). In the downstream industries of MMDI, spandex and TPU showed demand growth rates higher than the overall level. In the automobile industry, the continual penetration of EVs, along with the increasing use of polyurethane in such vehicles as compared to traditional FVs, collectively drove the per-vehicle consumption of MDI and the overall MDI consumption in the industry.
…….
If you are interested in Global/Asia-Pacific/Chinese MDI markets, price forecasts, and other related information, you can subscribe to Asia-Pacific MDI Market Research Report 2023, published by PUdaily, via Tel: 86-21-61250980 and E-mail: marketing@pudaily.com.
December 26, 2023
Good Update on Chinese Furniture and Mattresses
Upholstered Furniture: The Leader in Polyether Polyols

PUdaily | Updated: December 19, 2023
Furniture industry status
China’s furniture industry has intensified competition and increased concentration: China’s furniture industry has developed into an important industry with mainly mechanized production, continuous improvement of technical content and continuous emergence of well-known brands. With the country’s attention to the quality of architectural decoration products and the rise of consumer brand awareness, China’s furniture market is gradually moving towards brand competition. By improving the technical level, strengthening quality management, and increasing investment in advertising and marketing, the brand advantages of leading enterprises in the furniture industry have gradually emerged, which has led to the continuous upgrading of the level of industrial competition, and promoted the development trend of the whole industry driven by brand enterprises and continuous innovation, thus improving the concentration of China’s furniture industry.
China’s furniture industry will develop in the direction of new retail, new marketing and new services: With the rise of a new generation of consumer groups, people’s lifestyle and life concept have undergone changes, furniture products have also put forward higher requirements, the choice of furniture products more pursuit of personalized and fashionable, the future of customized furniture personality, fashion, time saving, labor saving, will conquer more consumer groups. Furniture companies need to pay more attention to brand building and product design to meet the new needs of consumers for furniture products, and the furniture industry as a whole is developing in the direction of new retail, new marketing and new services.
Furniture industry anti-dumping policy impact
With the continuous development of global trade, trade barriers and tariffs between countries have become an important factor hindering the process of globalization. Among them, anti-dumping measures, as a means of trade protection, have been frequently used by many countries in recent years. As the world’s largest mattress producer, China’s mattress exports are also facing anti-dumping pressure from the United States.
Under the influence of the anti-dumping strategy of the United States for China’s mattress, China’s furniture enterprises have gone through two stages. The first phase is from 2018 to 2021, given that the United States has imposed tariffs of up to 25 percent on almost all household categories in China, of which mattresses are also subject to anti-dumping duties. During this period, China’s foreign trade household industry began to transfer to Southeast Asia, through Vietnam, Thailand and other Southeast Asian countries to export to Europe and the United States. The second stage is from 2021 to the present, and in April 2021, the US Department of Commerce officially announced the high anti-dumping tax rate against the seven countries. Chinese home furnishing enterprises have to adjust their strategy again, on the one hand, to dig deep into the domestic domestic market, on the other hand, to build factories in the United States and Europe. For the domestic domestic market, furniture companies will focus on expanding the sinking market. Sinking market is one of the biggest consumption growth points in China, with a huge market size and increasing purchasing power. According to data from the National Bureau of Statistics, the per capita disposable income of rural residents in China has increased year by year, with a year-on-year growth of 7.6% from January to September 2023, bringing more opportunities for “high-quality and low-cost” mattresses. For overseas demand, even in the face of Chinese workers to sea difficulties, high labor costs in the United States pain points, furniture companies still choose to build factories in Europe and the United States. In the case of Dream Lily, under the influence of anti-dumping policies, the company accelerated the production capacity of the factory in the eastern United States, and at the same time built a new factory in the western United States to meet the order demand of the American market. Pudaily believes that furniture companies with forward-looking layout of U.S. production capacity can better meet the local market demand, thus benefiting from this round of anti-dumping.
Us mattress dumping timeline
| Targeted Country | Timeline | Content |
| China | 2018/10/10 | In response to the application submitted by a number of mattress companies in the United States on September 18, the United States Department of Commerce announced the launch of an anti-dumping investigation on mattresses imported from China |
| China | 2019/10/18 | On October 18, 2019, the US Department of Commerce announced a final anti-dumping ruling on mattresses imported from China: ruled that the compulsory response enterprise Healthcare Co., Ltd. The dumping rate is 57.03%, the dumping rate of Jinorsi Light Industrial Products Co., LTD., JiNorsi (Xiamen) Light Industrial Products Co., LTD., JiNorsi (Zhangzhou) Light Industrial Products Co., Ltd. is 192.04%, the dumping rate of other exporters with separate tax rates is 162.76%, and the general dumping rate of China is 1731.75%. |
| China, Cambodia, Indonesia, Malaysia, Serbia, Thailand, Turkey and Vietnam | 2021/4/21 | The US International Trade Commission (ITC) voted to make a final determination of anti-dumping industrial injury for Mattresses imported from Cambodia, Indonesia, Malaysia, Serbia, Thailand, Turkey and Vietnam, and a final determination of anti-subsidy industrial injury for mattresses imported from China. |
| Mexico, Philippines, Poland, Slovenia, Spain, Taiwan, Bosnia and Herzegovina, Bulgaria, Myanmar, India, Italy, Kosovo | 2023/7/28 | The U.S. mattress industry and several trade associations filed anti-dumping duty complaints (AD) against mattresses from 13 countries and regions, including Mexico, the Philippines, Poland, Slovenia, Spain and Taiwan, as well as Bosnia and Herzegovina, Bulgaria, Myanmar, India, Italy and Kosovo, as well as against mattresses from Indonesia. Filing a Countervailing Duty Complaint (CVD) |
Demand for polyether polyols in furniture industry
Sofas and mattresses consume more polyether in upholstered furniture, accounting for more than 80% of the total consumption. Sofa fillings are basically polyurethane, a single sofa products, ordinary polyether accounted for about 45%-60%, 10kg sponge about x kg x kg polyether; The proportion of ordinary polyether in the thin mattress is about 50%-60%, and the 10kg sponge is about x kg-x kg of ordinary polyether. In the soft furniture industry, although the overall demand is limited under the influence of the real estate downturn, under the development trend of “everyone lives” and customized integration, the growth of leading enterprises and high-quality enterprises is significantly higher than the industry as a whole, which has led to the steady growth of polyether consumption in the soft furniture industry. According to estimates, in 2023, the polyether consumption of China’s upholstered furniture industry is about xx million tons, with a growth rate of about xx%.
If you are interested in the Chinese furniture market in 2023 and the consumption of polyether polyols,
Welcome to inquire and subscribe: PUdaily’s “2023 Asia-Pacific PPG Market Research Report”.
 Everchem Updates Archive
 Sign Up for Email Updates