
Asian Markets
November 21, 2023
Chinese PU Market
China’s PU Market Experienced Sluggishness in October
PUdaily | Updated: November 16, 2023
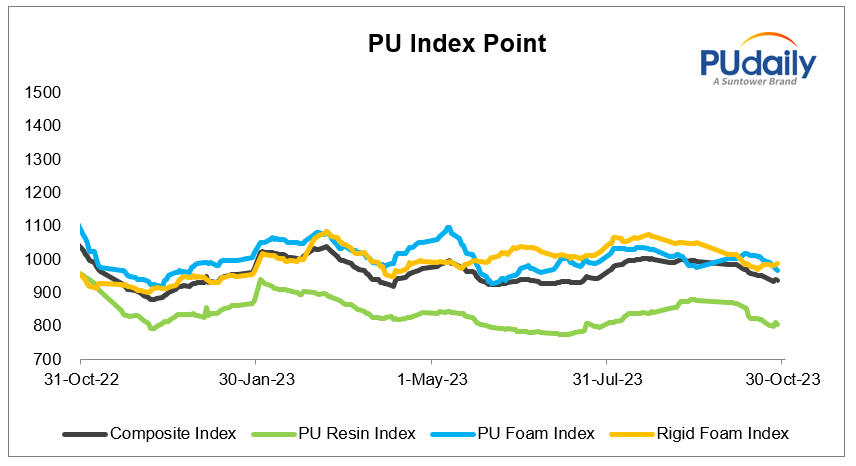
The PU composite index for October fluctuated. September saw a weaker-than-expected PU market. in October, the market became even more sluggish.Amid few inquiries, trading in PU raw materials was thin, resulting in a consolidating PU market.
The flexible PU foam index declined in October Earlier this month, spot TDI supply was tight as Wanhua(Xinjiang), Wanhua(Fujian) and Gansu Yinguang Chemical Industry shut their plants.In addition, some manufacturers needed to fulfill orders placed in September, and Covestro (Shanghai) stopped selling to boost the market. As a result, the TDI market rose significantly. Later, however, as demand became weak and spot supply increased with facilities restarted, manufacturers had to reduce prices to facilitate sale, resulting in a sharp fall in the TDI market. Flexible slabstock polyols manufacturers discussed prices with buyers.
In October, the rigid PU foam index consolidated at a low level. In the month, demand for rigid PU foam was sluggish.Specifically, demand from refrigerator manufacturers continued to rise, thanks to the double-digit year-on-year growth in refrigerator exports; that from insulated pipeline project in North China shrank; and that from the cold chain and OCF sectors remained weak. Late this month, due to tight MDI supply, the market bottomed out. With ample supply and finding it hard to sell, rigid polyols manufacturers discussed prices with buyers.
The resin index remained low in October. In the month, the AA market dipped. The high costs lent some support, but demand was sluggish as buyers made purchases as needed. The BDO market was down. In the month, the prices of feedstocks calcium carbide and methanol fell, lending decreased support to the BDO market. The supply rose significantly as maintenance was completed. However, demand was sluggish. Due to cost pressure, manufacturers were loath to reduce prices and decreased supply. but this provided limited support. traders were keen to sell. The THF market was soft-to-stable in October. The industry operating rate decreased, while operating rates in downstream sectors increased. traders sold goods according to market conditions. The PTMEG market remained stable in October. The operating rates in spandex industry remained stable, but the inventory cycle was extended. In the non-spandex products industry, synthetic leather resin manufacturers kept their operating rates low and made purchases as needed.
November 13, 2023
Sinochem PO
Sinochem International 400kT PO Facility Set to Produce Qualified Products in December
PUdaily | Updated: November 8, 2023
Since 2022, Sinochem International has successively completed and put into operation major facilities such as phenol acetone, bisphenol A, epoxy chloropropane, and epoxy resin as part of its first-phase C3 project. The 600 ktpa propane dehydrogenation (PDH) facility was recently commissioned for trial production, marking the complete integration of the entire epoxy resin industry chain at Sinochem International’s site in Lianyungang.
Over the years, Sinochem International has undergone a strategic transformation, evolving from a trading-oriented company into an internationally operated conglomerate primarily focused on fine chemical production. Through investments and acquisitions, the company has acquired a significant number of high-quality assets, including majority stakes in companies like Sennics, Yangnong Chemical, Elix Polymers, among others, laying a strong foundation for a successful industrial transformation. The company’s business encompasses chemical intermediates, polymer additives, new materials, new energy, and other traditional sectors, with complementary advantages between industries. Leveraging a green and circular economy industrial chain, Sinochem International has achieved continuous product diversification and efficient resource utilization, establishing a core competitive edge. The products offered include chlorobenzene series, nitrochlorobenzene series, widely used in industries such as pharmaceuticals, agrochemicals, and dyes. In the field of new materials, the company deals with high-performance fiber materials like aramid and high-strength polyethylene, as well as materials like epoxy chloropropane and epoxy resin used in industries such as coatings and electronics. They also handle lightweight materials such as PU, PC, PS, ABS, and others.
It’s worth mentioning that Sinochem International’s C3 project, with a production capacity of 400 ktpa of propylene oxide (PO), is expected to start commissioning on November 8 and is projected to produce qualified products in early December.
In the context of increasingly stringent environmental regulations, traditional chlorohydrin processes, which have not effectively addressed the “three wastes” issue, are gradually being phased out. In the draft of China’s 2023 Catalogue for Guiding Industry Restructuring, issued by National Development and Reform Commission on July 14, 2023, the calcium saponification chlorohydrin process should be eliminated by December 31, 2025. Following the elimination of a 50 ktpa chlorohydrin-based facility in Shandong, in recent years, chlorohydrin-based PO facilities, such as those in Jinpu, Tianjin, and Fujian, have successively ceased operations. As a result, the proportion of chlorohydrin processes has decreased from 55.9% in 2018 to 27.1% in 2022.
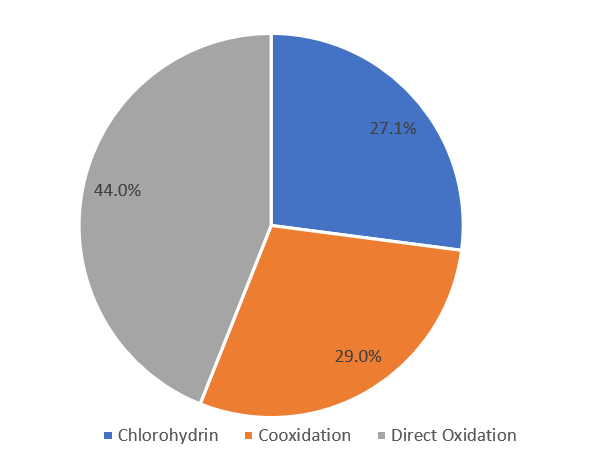
Currently, new PO facilities primarily use direct oxidation (HPPO) and cooxidation (PO/SM, PO/TBA) processes.
Sinochem International is expanding its capacity by 400 ktpa using the direct oxidation process for PO production, and its scale and technology are at the forefront domestically. The C3 project includes a 400 ktpa HPPO facility with supporting facilities, in line with national environmental protection policies. As an environmentally encouraged process, the direct oxidation process can overcome the drawbacks of severe equipment corrosion and high waste generation associated with chlorohydrin processes. This method features a simple process, high product yield, and only generates PO and water during production. Raw materials and auxiliary agents can be recycled, resulting in lower raw material and energy consumption and a significant reduction in production costs. It is also environmentally friendly and non-polluting. Furthermore, the direct oxidation process is expensive and challenging to acquire, with a high entry barrier. Once the facility is operational, Sinochem International will hold a leading position in terms of production capacity and technology in the domestic market.
Dimethyl carbonate (DMC) is a co-product produced by ester exchange in the production of propylene glycol. Thanks to green chemistry, new energy promotion, and sustainable development, DMC has gained attention due to its low toxicity and excellent environmental performance. It finds wide applications in various industrial fields. Apart from its traditional uses in adhesives, coatings, developers, and polycarbonates, DMC has seen significant growth in the downstream applications of lithium-ion battery electrolyte solvents, which now account for 30% of its usage. High purity is crucial for these applications, with industrial-grade DMC primarily used in traditional downstream applications and polycarbonates (PC), while battery-grade DMC requires higher purity. Currently, suppliers of battery-grade DMC include Shida Shenghua (75 ktpa), Oxiranchem (20 ktpa), etc. New entrants in this market include Capchem, Sinochem Quanzhou, Zhejiang Petrochemical, and Hualu Hengsheng. In the next 3-5 years, the newly established production capacity for carbonates in China is expected to exceed 4 mtpa, contributing to the increased demand for PO.
October 29, 2023
Wind Turbine Prices Fall
Profit At China’s Top Wind Firm Slumps 98%
by Tyler Durden
Friday, Oct 27, 2023 – 05:00 AM
By Charles Kennedy of Oilprice.com
Lower prices for turbines amid a price war in China have resulted in a 98% plunge in the net profit of the top Chinese wind turbine maker, Xinjiang Goldwind Science & Technology Co.
While investments in renewable energy projects in China are booming, intensified competition has led to a race to the bottom for wind turbine prices—a race that has dented profits at the biggest Chinese manufacturer.
Goldwind booked $1.28 million in net income for the third quarter of 2023, down by a massive 98% compared to the same period of 2022, a company statement quoted by Bloomberg showed on Thursday.
Chinese clean energy technology manufacturers have also come under EU scrutiny as the bloc fears cheaper products from China would undermine the European Union’s goals of having a strong EU clean energy manufacturing industry.
Globally, the wind power industry faces additional challenges. Offshore projects are being scrapped amid rising costs and interest rates and supply chain issues.
In August, Siemens Energy initiated a review of its wind business after taking a large hit to earnings and expected full-year revenues and profits due to problems at its unit Siemens Gamesa, one of the largest wind turbine makers in the world. At the end of June, Siemens Energy withdrew the profit guidance for the company due to problems with wind turbines at Siemens Gamesa.
“Following a substantial increase in failure rates of certain wind turbine components, an extended technical review suggested that significantly higher costs will be incurred than previously assumed to reach the targeted quality level,” Siemens Energy said in August.
On Thursday, October 26, Siemens Energy shares plunged by more than 30% to an all-time low after the company said it is in preliminary talks with different stakeholders, including banking partners and the German government, to ensure access to guarantees for long-term projects. More than $3 billion of Siemens Energy’s market value was wiped out by the early afternoon in Frankfurt today.
https://www.zerohedge.com/markets/profit-chinas-top-wind-firm-slumps-98
October 16, 2023
TDI in China
TDI Market is Poised to Take Off Amidst Intensive Maintenance Plans
PUdaily | Updated: October 13, 2023
Not long after the restart of Wanhua Chemical’s facility in Yantai, several TDI facilities have started or are about to undergo maintenance. The maintenance plans of TDI suppliers in the fourth quarter of this year are intensively scheduled.
Table 1: Recent TDI Facility Maintenance Plans in China and South Korea
| Juli Chemical | Maintenance started on September 25, expected to last about 40 days. |
| Wanhua Chemical | Rumored to start maintenance on October 6, expected to last about 15 days. |
| Yinguang Chemical | Temporary shutdown for maintenance on October 9. |
| Hanwha | Maintenance started on October 13, expected to last about 25 days. |
| Cangzhou Dahua | Maintenance scheduled to start on October 20, expected to last for 1 month. |
| Covestro Shanghai | Maintenance to start in mid-November, expected to last about 40 days. |
| BASF Korea | Maintenance to start on November 17, expected to last about 25 days. |
Although TDI suppliers have typically concentrated their maintenance plans in the fourth quarter in previous years, this year the maintenance at Wanhua Chemical and Yinguang Chemical have exceeded industry expectations, and Cangzhou Dahua did not undergo maintenance last year. The maintenance duration of the facilities at Juli Chemical and Covestro is also longer than in previous years.
Amidst the contradiction between intensive maintenance plans and the recovery of demand, TDI suppliers, especially Covestro, have frequently raised their guide prices:
- On October 7, Covestro raised its opening price for October and only offered 50% of supplies to distributors in November, while providing 80% to direct customers.
- On October 8, Covestro stopped trading due to strong demand and extremely low inventory.
- On October 9, the price offered by the North China plant was raised to CNY 20,000/tonne. Covestro raised its fixed price to CNY 19,200/tonne.
- As of the latest update on October 11, Covestro has stopped trading again due to tight supply…
Looking back at October last year, the price of TDI surged from CNY 19,000/tonne to surpass CNY 26,000/tonne due to tight supply. And in the same period this year, with the same supply significantly reduced, the price level remains the same… Stay tuned for the subsequent market trend!
October 12, 2023
Shell Fire at Singapore POSM Plant
Shell’s Singapore Petrochemical Unit Puts Out Fire; Styrene Impact Likely — OPIS Update

Provided by Dow Jones
Oct 11, 2023 9:39 AM EDT
Singapore’s Shell Jurong Island (SJI) has extinguished a fire that broke out at one of its petrochemical unit manufacturing site on Jurong Island, according to market sources.
The fire occurred at around 3:00 hours Singapore time on Oct.10 and was extinguished with no reported casualties, according to the source.
Market sources said that the fire would most likely impact Shell’s styrene monomer (SM) production.
“The specific impact of the styrene plant is still being evaluated by Shell. We will have to wait and see how serious the damages are,” said a China-based SM broker.
A Shell spokesperson confirmed the incident and said no injuries were reported.
“Our emergency response team is currently monitoring the situation closely. Safety is a key priority to Shell,” the spokesperson said.
At its site, SJI can produce a total of 1,040 million metric ton (mt) per year of SM and 490,000 mt/year propylene oxide (PO) between its two POSM lines, according to its website.
Operations at Shell’s cracker on the same site do not appear to have been disrupted, sources said.
“Besides PO and SM, there should be no disruption to the other chemical production,” added the SM broker.
This content was created by Oil Price Information Service, which is operated by Dow Jones & Co. OPIS is run independently from Dow Jones Newswires and The Wall Street Journal.
–Reporting by Hazel Kumari, hkumari@opisnet.com; Editing by Hanwei Wu, hwu@opisnet.com
 Everchem Updates Archive
 Sign Up for Email Updates
