
Asian Markets
June 13, 2023
Butanediol in China
BDO Market Booms with Growing Demand in Traditional and Emerging Industries
ECHEMI2023-06-12
1,4-butanediol (BDO) is an influential organic and fine chemical raw material, widely used in textile, chemical and other fields. Demand for BDO has formed a significant driving force in recent years with the expansion of applications in emerging fields such as biodegradable plastics and lithium batteries, as well as the recovery of traditional downstream industries such as spandex and PBT plastics.
According to SteelHome, the BDO market is currently extremely hot, with prices rising sharply. The benchmark price of BDO in the East China market has exceeded 11000-11100 yuan/ton, with a growth to the past week. According to research by Shenwan Hongyuan Securities, China’s apparent BDO consumption is expected to reach about 4.47 million tons per year by 2025, and the compound annual growth rate of BDO demand from 2020 to 2025 will be 26.5 percent.
BDO’s traditional application areas are primarily spandex and PBT engineered plastics, with BDO’s downstream applications in the spandex industry chain and PBT engineered plastics reaching 51% and 26% respectively. The spandex market is extremely hot, with product prices up nearly 200 percent, as demand for textiles and clothing recovers and export orders rise. The PBT plastics sector is also showing a clear trend of growth, with increasing applications in new energy vehicles and charging devices.
In addition to traditional application areas, BDO is rapidly expanding its applications in emerging areas such as biodegradable plastics and lithium batteries. With the frequent introduction of domestic plastic reduction policies, the demand for biodegradable plastics is about to enter a period of explosive growth, and PBAT is expected to lead the way in the agricultural plastic film and packaging materials and other biodegradable plastic markets with well-established production technologies and high cost-effectiveness. As a major feedstock for PBAT, PBAT is expected to generate approximately 2.5 million tonnes/year of new demand for BDO by 2025. At the same time, BDO is an essential raw material in the hottest lithium battery industry chain, and its downstream NMP is an important solvent in the production process of lithium battery cathodes, as well as a cleaning agent for semiconductors and integrated circuits.
Due to the long-term low BDO product prices, companies can only barely maintain a break-even point, and the industry’s sluggish business environment severely hinders new capital expenditures. Currently, the d Chinese annual production capacity of BDO is about 1.45 million tons, and the demand gap exceeds 200,000 tons. Only two A-share listed companies, Zhongtai Chemical and Shaanxi Black Cat, have BDO production capacity, with a combined annual capacity of only 330,000 tons. The huge gap between supply and demand has attracted a group of domestic companies to ramp up production on a regular basis. More than 1.5 million tons of new BDO capacity are currently planned in China, but the construction of BDO capacity usually takes about two years and there is a certain commissioning period after completion to achieve stable production. The fastest new capacity will gradually enter the production release period in the second half of 2022. Many industry insiders believe that the mismatch between new capacity and downstream demand growth will keep this cycle of BDO shortages going for more than two years, and that the BDO business environment will continue to improve as a result.
Recently, the world’s largest BDO project with an annual production capacity of 900,000 tons was settled in Fujian. The project will help boost China’s new energy and environmental protection industries by using the large amount of hydrogen produced as a by-product of propane dehydrogenation to produce BDO, a new chemical material that can be used to produce lithium batteries, high-end spandex, fully biodegradable plastics and other products. The move is an important boost for China’s plasticization industry and will help promote the transformation and upgrading of the country’s chemical industry, as well as the development of new energy and environmental protection industries.
https://www.echemi.com/cms/1416474.html
Polybutylene adipate terephthalate
From Wikipedia, the free encyclopedia
PBAT (short for polybutylene adipate terephthalate) is a biodegradable random copolymer, specifically a copolyester of adipic acid, 1,4-butanediol and terephthalic acid (from dimethyl terephthalate). PBAT is produced by many different manufacturers and may be known by the brand names ecoflex, Wango, Ecoworld, Eastar Bio, and Origo-Bi. It is also called poly(butylene adipate-co-terephthalate) and sometimes polybutyrate-adipate-terephthalate[1] (a misnomer) or even just “polybutyrate”.[2] It is generally marketed as a fully biodegradable alternative to low-density polyethylene, having many similar properties including flexibility and resilience, allowing it to be used for many similar uses such as plastic bags and wraps.[3] It is depicted as a block co-polymer here due to the common synthetic method of first synthesizing two copolymer blocks and then combining them. However, it is important to note that the actual structure of the polymer is a random co-polymer of the blocks shown.
Read more here: https://en.wikipedia.org/wiki/Polybutylene_adipate_terephthalate
May 29, 2023
PO Trade Flows in the Future
Will Shutdown of Dow’s PO Plant in U.S. Change Asian Trade Flow?
PUdaily | Updated: May 29, 2023
The end-users of propylene oxide (PO) include industries such as real estate, automobiles, furniture, refrigerators, and freezers, which are closely related to the development of the national economy. An increase in demand for polyurethane due to the rise in the prosperity of these industries will stimulate polyols suppliers to increase production, thereby increasing the demand for PO and driving up prices.
On May 16, it was reported that Dow Chemical plans to close its PO plant in Freeport, Texas, by the end of 2025.
The decision to close the PO plant arose from the fact that the plant is approaching its end-of-life, and the overall chemical industry is not prosperous due to the slowing global economic growth and various uncontrollable factors. The demand from most end-users is weakening, and polyurethane suppliers are paying more attention to higher value-added segments. Therefore, the decision to close the plant is part of Dow Chemical’s efforts to optimize costs and supply conditions.
Dow’s PO plant in Freeport will continue to operate until the end of 2025, while downstream polyether polyol plants will continue to operate after the PO plant is shut down. After 2025, Dow will use resources from other regions or third-party suppliers to supply PO to its polyol plants. Dow is also investing in logistics capabilities, such as PO tanks, pipelines, and new barges to ensure the normal supply.
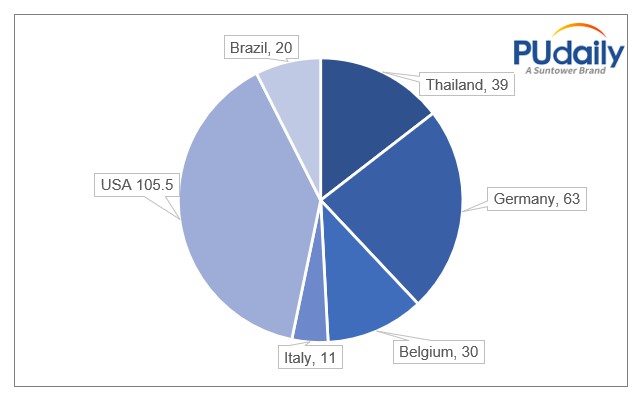
Currently, Dow Chemical is the world’s largest PO producer with an extensive layout of plants in the U.S., Germany, Brazil, Belgium, and Thailand. Its total capacity is 2.685 mtpa, contributing 20.24% of the global PO output.
Dow Chemical’s PO Capacity Layout (10kT)
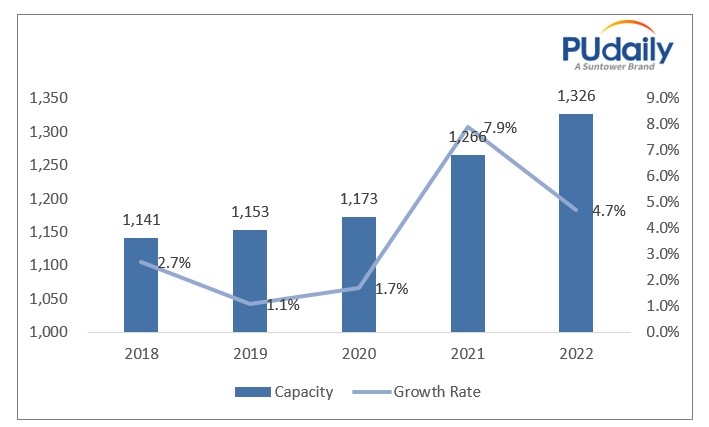
Global PO Capacity & YoY Changes, 2018-2022 (10kT, %)
Dow’s PO production uses the chlorohydrin process technology. The patent owners of the chlorohydrin process are mainly Dow in U.S., Asahi Glass, Mitsui Toatsu and Showa Denko in Japan. The chlorohydrin process was industrialized as early as 1931 and has the advantages of mature technology, short process, low purity requirements for raw materials, and low investment. The key of this technology is the chlorohydrin reactor, and Dow Chemical’s tubular reactor is representative of the chlorohydrin process.
But the chlorohydrin process causes severe environmental pollution, and under the background of increasingly stringent environmental regulations, the use of chlorohydrin technology faces enormous challenges. The US government has already eliminated chlorohydrin technology in 2000, and China has also listed chlorohydrin process as a restricted item in the Guidance Catalogue for Industrial Structure Adjustment (2011), and new facilities cannot adopt this technology.
The shutdown of Dow’s PO plant in the U.S. will cause a supply gap. Part of the gap will be filled by LyondellBasell (In March of this year, LyondellBasell successfully started up the world’s largest PO and TBA plant in Texas. These new assets on the U.S. Gulf Coast have an annual capacity of 470,000 tonnes of PO and 1 million tonnes of TBA and its derivatives). Some PO suppliers in countries such as South Korea, Saudi Arabia, and Thailand will also increase exports to the U.S. China’s PO export is constrained by process requirements and lack of export tax refunds. The tax rebate rate for downstream products of PO, such as polyether polyols, propylene glycol, and propylene glycol methyl ether, has been increased to 13%, further enhancing their export competitiveness.
May 29, 2023
Wanhua Starts TDI Plant
Wanhua’s 250kT TDI Facility in Fujian Starts Production, Phase II 300kT TDI Project is Around The Corner

PUdaily | Updated: May 24, 2023
On May 22, 2023, Wanhua Chemical successfully started its 250kT TDI facility in Fujian with producing qualified products, marking another breakthrough in the TDI industry, according to the company announcement. With this, Wanhua now has four TDI production bases globally, with a total production capacity of 950 ktpa, including 300 ktpa in Yantai, 250 ktpa in Fujian, 250 ktpa in Hungary, and 150 ktpa at former Juli Group’s plant. The company contributes 30% of the global TDI capacity, making it the largest TDI supplier in the world.
Meanwhile, Wanhua Chemical is preparing to launch its Phase II 300 ktpa TDI project in Fujian, according to public information. It is estimated that Wanhua’s TDI capacity in Fujian will exceed 550 ktpa after the operation of its Phase II 300 ktpa facility. Based on the construction speed of Wanhua’s previous projects, it is likely that the Phase II TDI facility in Fujian will start operating at the end of 2024.
The global TDI consumption will be around 2 million tonnes in 2023 and roughly 2.4 million tonnes in 2025, according to Pudaily’s forecast. It is estimated that global TDI capacity will reach 3.515 mtpa after the completion of Wanhua’s Phase II 300 ktpa TDI facility in 2024. In the future, the TDI supply-demand balance will continue to tilt, and the oversupply situation will become prominent, leading to intense competition.
May 16, 2023
Chinese Mattress Exports
China Mattress Exports Increase Significantly in Q1 2023
PUdaily | Updated: May 16, 2023
China exported a total of 2.457 million spring mattresses in the first quarter of 2023, a year-on-year increase of 14.8%. The export value reached USD 194.02 million, a year-on-year increase of 2.5%, according to customs data.
Figure 1: China Spring Mattress Export, 2022-2023 (10,000 pieces)
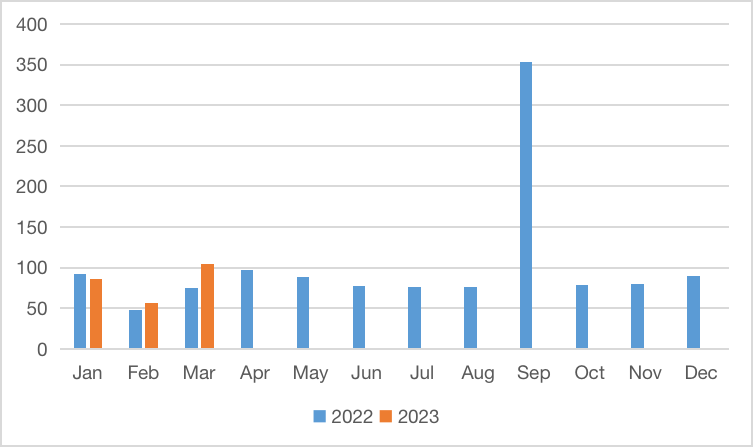
China exported a total of 7.511 million foam mattresses in Q1 2023, a year-on-year increase of 7.9%. The export value was USD 163.93 million, which remained basically stable compared to the same period last year.
Figure 2: China Foam Mattress Export, 2022-2023 (10,000 pieces)
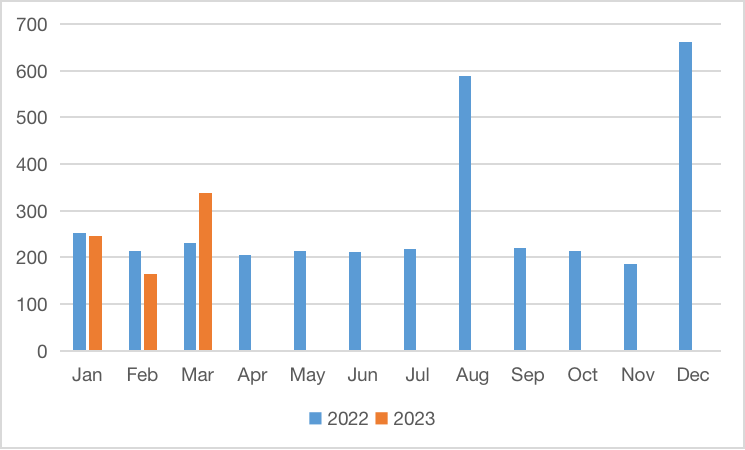
It is noteworthy that although the export volume increased significantly year-on-year, the growth rate of export value was significantly smaller, and the unit price and profit for exports declined year-on-year.
From January to March 2023, the operating revenue of furniture manufacturers above designated size in China totalled CNY 148.59 billion, a year-on-year decrease of 13.2%; operating costs reached CNY 123.12 billion, a year-on-year decrease of 14.3%; and their total profit was CNY 5.56 billion, a year-on-year decrease of 12.6%, according to the National Bureau of Statistics of China.
Looking at the quarterly reports of listed companies in Chinese home furnishing industry, among nearly 120 home furnishing companies that had already published their reports this quarter, 83 companies experienced a decline in revenue and 29 companies suffered losses.
However, the prosperity of China’s real estate industry in the first quarter partially restored, with housing completions accelerating growth in March and home sales keeping recovery. In terms of end-user spending, there have been signs of a rebound in domestic and foreign consumption. Offline store traffic has significantly increased. Under sales promotions, some demand for replacement in mature markets has been boosted. It is predicted that China’s home furnishing market will experience marginal improvement in the near future.
May 11, 2023
Chinese Furniture and Mattress Overview
Upholstered Furniture Market Situation & Trends
PUdaily | Updated: May 9, 2023
Upholstered furniture refers to furniture added with padding, foam, fabric and other materials. This involves sofas, upholstered beds, mattresses, nightstands, coffee tables and other relative products. Among them, mattresses and sofas are the two main types of upholstered furniture. The industrialization of upholstered furniture began in Europe in the early 20th century. Global upholstered furniture industry has greatly increased its production capacity thanks to continuously advanced manufacturing technologies, and the market demand has also kept growing.
As the upholstered furniture industry is labor-intensive, developed countries are continuing to transfer their manufacturing to developing countries, which have low labor costs and sufficient raw materials. The main upholstered furniture manufacturing countries currently include China, U.S., Poland, India, Italy, and Germany.
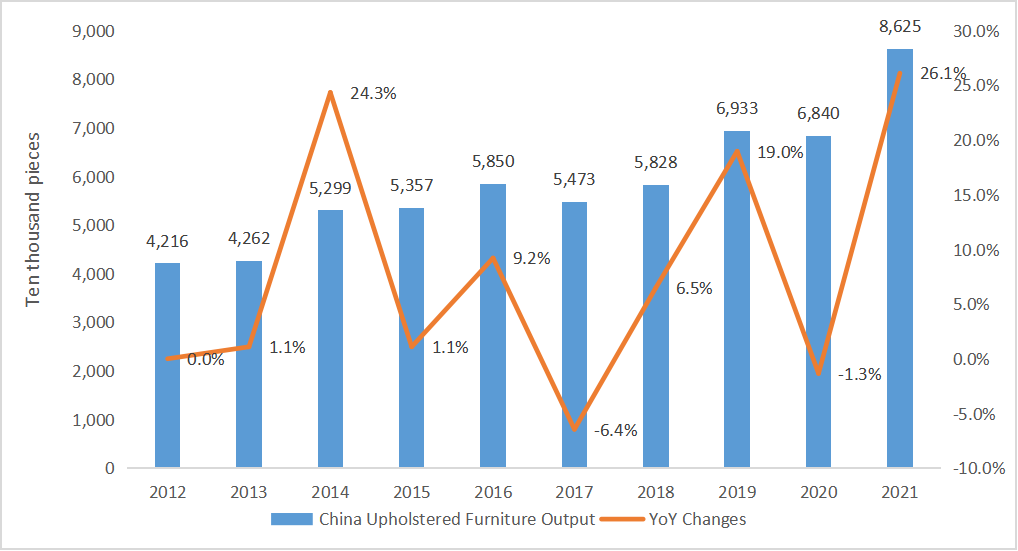
China has become one of major producers and consumers of upholstered furniture. China’s modern upholstered furniture industry began in the early 1980s. In recent years, through introduction of advanced furniture design technology and processing technology from abroad, and on the basis of fully leveraging the advantages of raw material resources and labor costs, China’s upholstered furniture industry has developed rapidly. At present, China’s upholstered furniture output value makes up 46.4% of the world, contributing about 30.7% of the global upholstered furniture consumption.
Figure 1 China Upholstered Furniture Outputs & YoY Changes, 2012-2021
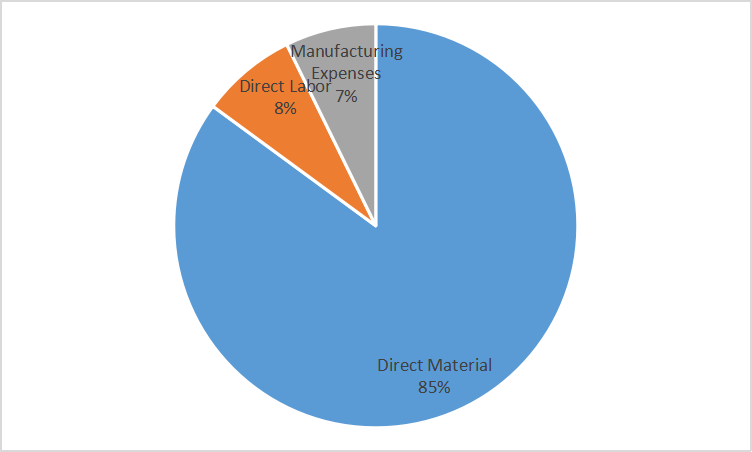
The upholstered furniture industry has a long industrial chain that spans agriculture, manufacturing, and retail industries. Its upstream industries mainly include leather, wood, foam, and other raw material industries. Downstream manufacturers mainly sell products to end consumers through channels such as dealers, ODMs, and direct-sale stores. Leather is mainly used for the outer surface of upholstered furniture, primarily natural cowhide. Wood is mainly used for the main structure of upholstered furniture, and the development of forest planting directly affects the wood supply and procurement costs of the upholstered furniture industry. Foam, namely polyurethane foam, is a typical cushioning material mainly used for cushions, armrests, backrests, etc., to improve the softness and comfort of upholstered furniture. It is made from polyurethane through processes such as foaming, hot pressing, and cutting, and is a derivative product in the petrochemical processing industry. Therefore, its price is greatly affected by fluctuations in oil prices. Downstream manufacturers of upholstered furniture mainly sell products to end users through direct-sale stores, dealers, etc., and factors such as household income and real estate industry development drive consumer demand.
Commodity prices have risen sharply since 2021. The low added value and high cost of the upholstered furniture industry have been greatly affected by rising raw material prices. Meanwhile, under the policy of “housing is for living, not for speculation”, the prosperity of the real estate industry has significantly declined, which also brings obvious suppression on the demand for upholstered furniture. Under the dual impact of rising costs and weakening demand, the overall profit margin of the upholstered furniture industry has significantly decreased. Especially for small and micro manufacturers that rely on price advantages, their survival space has been squeezed.
Figure 2 Cost Structure of a Mattress Manufacturer
In the future, China’s upholstered furniture industry could follow two important directions:
1) A boom in established market:
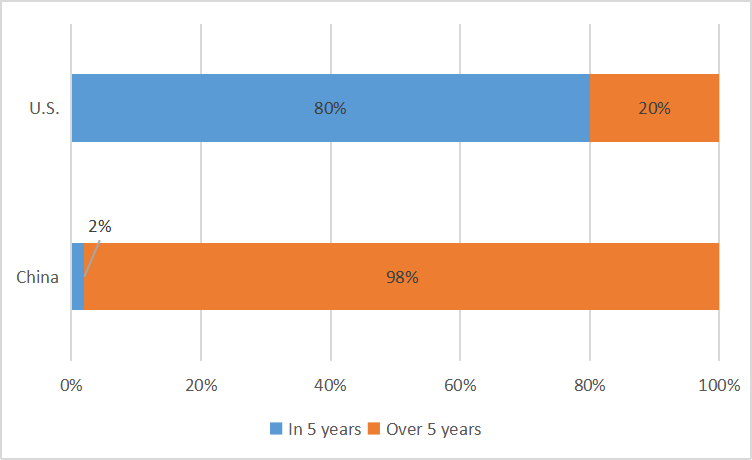
A few decades ago, spring mattresses were popularized in China. For a spring mattress, the lifespan of spring is usually 10-20 years, and that of filler and fabric is about 5-10 years. At present, the frequency of mattress replacement in China is much lower than that in U.S. 37% of Chinese consumers replace mattresses in 10-15 years, while 47% of consumers have never changed them, which are mostly under serviceability limit state. We believe that increasingly frequent mattress replacement and higher requirements for comfort level of beddings may boost the demand for mattresses.
Figure 3 Mattress Replacement Frequency in China
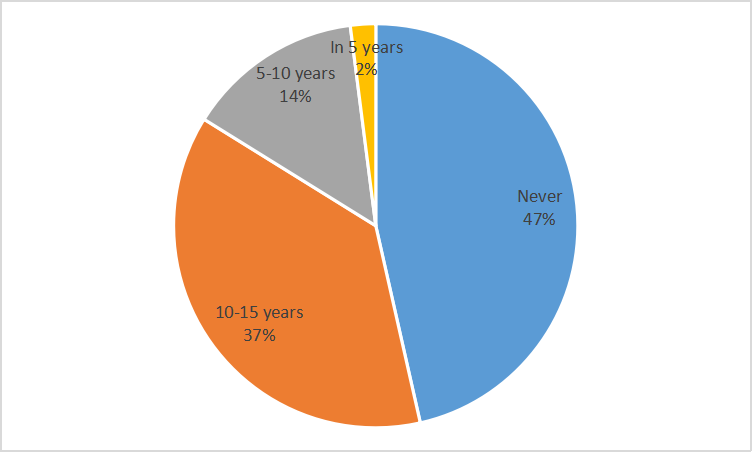
Figure 4 Comparison of Mattress Replacement Frequency in China and U.S.
2) Rising industrial concentration:
At present, China’s sofa industry is fragmented. CR4 (the concentration ratio of the top four manufacturers) in China was only 30% in 2021, with Man Wah holding the largest market share (about 12%); the concentration of U.S. sofa industry was higher, with CR4 reaching 51% and CR10 reaching 79% in 2017, and the market share of top manufacturers la-z-boy/Ashley/Man Wah reached 21%/11%/10% respectively.
In terms of the mattress industry, the U.S. market is dominated by a few top brands, while Chinese mattress market is inundated with small and medium-sized manufacturers.
The top 5 brands in U.S., (CR5), Sealy, Simmons, Serta, Tempur-Pedic and Sleep Number, together occupied 69.40% of the mattress market. CR3 and CR8 in China’s mattress market are only 11.43% and 18.66%. The market share of top three brands – Sleemon, Serta and DeRucci – is 4.38%, 3.88% and 3.17% respectively.
With the improvement of residents’ consumption levels and the broad demand for mattress replacement, top manufacturers with advantages in brand, channels, and services are expected to usher in a significant growth in the next few years.
 Everchem Updates Archive
 Sign Up for Email Updates