Current Affairs
October 8, 2020
Ten Bad Years for Department Stores
Department Stores’ Dismal Decade Of Decline
by Tyler Durden Thu, 10/08/2020 – 14:51
By Daphne Howland, of RetailDive
The heyday is over. The question for department stores now is whether there will be a new day.
Certainly, the pandemic has made that already sticky question all the more difficult to answer. But many retailers in the space had been trying. Early this year, for example, Macy’s inched toward rehabilitation as it outlined plans to get away from so many enclosed malls, close more than 100 stores and improve its private labels. Late last year, Nordstrom made strides executing its vision for a 21st century department store when it put the finishing touches on its retail ecosystem in New York City. Now, forced to institute layoffs and take on new debt, they and many others are just hoping to hang on through the holidays.
Yet the pandemic, as devastating as it’s been to people’s lives and livelihoods, didn’t provoke the current existential crisis for these retailers. That came earlier, through consolidation and over-expansion — especially at Macy’s, which broke several cities’ hearts when it took over and renamed their local department stores as with Chicago’s beloved Marshall Field’s in the Loop 14 years ago. E-commerce is a factor, but by now, department stores are e-commerce players too. More devastating have been the declines— possibly all related —of the middle class, the mall and the need to dress up for workor occasions.
The Great Recession was technically over by 2010, but retail has never been the same since. And the last 10 years have been especially brutal to department stores. The following timeline provides a few snapshots of how things have gone.
Department stores in the last decade
2010
Things are looking up for most department stores as they recoup from the Great Recession.
- Nordstrom looks back at 2010 as a “terrific year that exceeded our expectations,” noting that it opened three full-line stores and 17 off-price Racks in the period, topping 200 locations for the first time.
- Sears is a notable exception, with revenue, profit and store comps all down for the year. Still, the company signs a lease in a historic downtown San Francisco building to house a newly energized apparel team.
- Macy’s boasts that the impact of nearly doubling in size through its takeover of the May Company a few years before came “to fruition in 2010,” propelling it to a national brand through the conversion of nearly 600 stores from regional banners to Macy’s stores and centralization of its operations.
- Southern retailer Belk, the largest privately owned department store in the U.S., updates its logo and unveils a new slogan, “Modern. Southern. Style.”
- Kohl’s says it will open 30 new stores, for a total of 1,089 in 49 states.
- Dillard’s, with a footprint largely in the South and Southwest and a strong private label portfolio, announces a new line of women’s apparel and accessories from Arkansas native Korto Momolu, who unveils the collection at New York Fashion Week. At the end of the year the company acquires a former Target distribution facility with plans to grow online sales.
- It’s J.C. Penney’s last year of positive net income.
2011
- J.C. Penney hires Ron Johnson, who enjoys a renowned reputation as Apple’s store guru, as CEO. He takes swift and drastic measures in pricing and merchandising that are immediately controversial with its customer base and investors.
- Sears wins “Mobile Retailer of the Year” from the Mobile Commerce Awards for innovations like bar codes in its catalogs and online order pickup services, offered at a time when few retailers are paying attention to the channel.
2012
EMarketer expects online apparel sales to help push U.S. e-commerce up 15.4% to $224.2 billion, a rise blamed for lagging traffic to malls and their department store anchors.
- Macy’s closes five stores, but also opens five stores. In its annual report, the company attributes the year’s performance to “a three-pronged business strategy known by the acronym of M.O.M. — My Macy’s, Omnichannel and MAGIC Selling.” The company says Bloomingdale’s will focus “on an upscale niche.”
- Sears announces a series of “hyper-local” websites, which contain localized deals beyond the national weekly circular.
2013
- Ron Johnson is out at J.C. Penney after 17 months; retired CEO emeritus Mike Ullman returns to take his place.
- Hudson’s Bay Co., which owns Lord & Taylor and Canadian department store Hudson’s Bay, buys luxury department store Saks Fifth Avenue for $2.9 billion, including debt.
2014
The economic recovery continues, but consumers remain wary. The Organisation for Economic Co-operation and Development releases a report detailing how income inequality is rising in the U.S. and is already starker than in other countries studied by the group, a situation some analysts believe is pressuring retailers like department stores that sell to middle-income consumers.
- In a settlement with the New York State Attorney General over allegations of racially profiling customers in its Herald Square flagship, Macy’s agrees to pay $650,000, hire an anti-discrimination expert and train employees.
- J.C. Penney taps Home Depot executive Marvin Ellison to take over as CEO the following year.
- Nordstrom buys men’s apparel subscription service Trunk Club for $350 million and hires its founder, Bonobos co-founder Brian Spaly.
2015
Mall vacancies spike — almost 15% of malls are 10% to 40% empty (compared to 5% that empty nine years before) and 3.4% are more than 40% empty, which one Green Street analyst tells the New York Times indicates a “death spiral.”
- Private equity firm Sycamore buys Belk for $3 billion, the first department store in its retail-heavy portfolio.
- Macy’s buys beauty and spa business Bluemercury for $210 million in cash and pilots its first Backstage off-price stores. Its Bloomingdale’s marketing team apologizes for a holiday ad that is a far cry from the holiday whimsy usually affiliated with department stores: “Spike your best friend’s eggnog when they’re not looking.”
- Nordstrom invests in custom footwear startup Shoes of Prey; the DTC retailer shuts down less than four years later.
- Sears establishes a real estate investment trust with its extensive land holdings and raises $2.7 billion.
2016
About two-thirds of all shoppers are spending at off-price retailers and making 75% of apparel purchases there, according to research from the NPD Group, while Moody’s Investors Service finds that growth at off-price retailers T.J. Maxx, Ross, and Burlington will outpace specialty and department stores.
- Sears sells its DieHard battery brand for $200 million to Advance Auto Parts.
- Seeing opportunity in Sears’ decline, J.C. Penney resumes major appliance sales after a 33-year hiatus. To save costs, the company also sells its sprawling Dallas-area headquarters campus, with plans to rent a portion of it instead.
- Nordstrom joins investors for a $100 million funding round in menswear startup Bonobos; later Walmart buys Bonobos, but Nordstrom develops a merchandise-free store concept similar to Bonobos Guideshops. However, losses at Trunk Club fuel a $10 million loss in Nordstrom’s third quarter, prompting a $197 million write-down on that business, and, soon after, the founder exits.
- Stein Mart founder Jay Stein steps down as CEO.
- Also announcing plans to step down is Macy’s CEO Terry Lundgren, who orchestrated Macy’s explosive expansion early in the century. He also announces the closure of 100 stores. Later he also casts doubt on Amazon’s ability to handle the logistics of selling apparel.
2017
Apparel sales shrink to a new low of 3.1% of the average U.S. consumer’s budget, down from 5.9% in 1987. When they do buy clothes, many shop on price and eschew department stores in favor of discounters like mass merchants, fast-fashion retailers or off-pricers.
- Sears announces it will shutter 150 Kmart and Sears stores — some 400 by the end of the year — and sells its iconic Craftsman tools line to Black and Decker for $900 million. In May, CEO Sears CEO Edward Lampert tells shareholders, “We don’t need more customers. We have all the customers we could possibly want.”
- Lord & Taylor opens a digital storefront on Walmart.com, a move deemed “Crazy. Loony. Madness,” by retail analyst Howard Davidowitz.
- Kohl’s begins taking Amazon returns.
- Midwest discount department store chain Gordmans files for Chapter 11 and is acquired by Texas-based Stage Stores when it outbids former CEO (and the founder’s great-grandson) Jeff Gordman.
- After sweeping away much of its women’s apparel inventory and conducting a series of focus groups, J.C. Penney institutes a new strategy evocative of Ron Johnson’s controversial approach of years before.
- Jeff Gennette takes over from Terry Lundgren as CEO of Macy’s, as planned.
- Belk takes on The Limited as an in-house private label after owner Sycamore buys the specialty apparel retailer at a bankruptcy auction for $26.8 million.
- Barneys New York unveils its immersive “The Drop” event in partnership with fashion streetwear company Highsnobiety, reprising it in Los Angeles the following year.
2018
Some department stores begin to take extreme measures.
- Stein Mart announces it is exploring strategic alternatives.
- Macy’s invests in retail-experience startup b8ta and acquires quirky concept retailer Story, hiring Story founder Rachel Shechtman as its first-ever “brand experience officer.” Meanwhile, Amazon is taking share in apparel sales from Macy’s, according to Coresight Research.
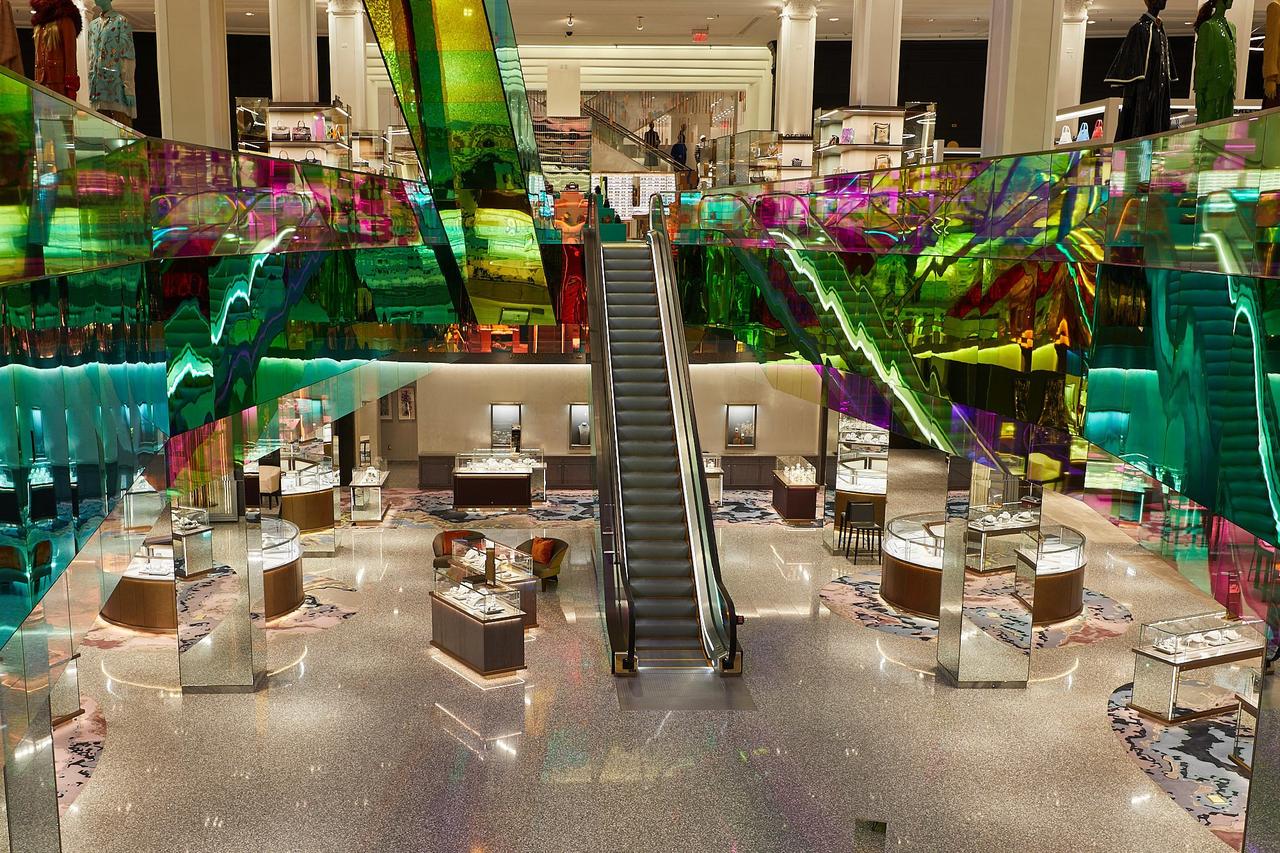
- Bucking longstanding department store tradition, Saks moves its beauty sales to the second floor as part of its $250 million “Grand Renovation.”
- J.C. Penney CEO Marvin Ellison departs to lead home improvement retailer Lowe’s. Joann CEO Jill Soltau, known as a talented merchandiser, is tapped to take the spot.
- Nordstrom opens a men’s store in New York City, across the street from where it’s building a new flagship store.
- Barneys closes its Upper West Side store in New York.
- After years shrinking its physical footprint by 75%, selling off critical assets and laying off thousands, Sears files Chapter 11, with plans to close 142 stores. Among its closures for the year is its last location in hometown Chicago.
- Lord & Taylor displays its last holiday windows, after first innovating the animated presentations in 1938.
2019
Things get a little weird.
- Barneys New York announces “The High End,” a “luxury cannabis lifestyle shop” at its Beverly Hills flagship. Months later, after toppling into bankruptcy, however, the department store survives only as a brand licensed to Saks, with plans to close all locations, most immediately.
- Goldman Sachs loosens its dress code, one of the last blue-blood firms to open the door to “business casual,” further imperiling sales of men’s suits.
- HBC sells Lord & Taylor’s Manhattan flagship to coworking startup WeWork for $850 million; the building is in Amazon’s hands within two years. The Canadian department store conglomerate later sells Lord & Taylor itself to apparel rental site Le Tote for $100 million. HBC also shuts its specialty home stores in Canada and announces a 20-store cut to Saks Off 5th’s off-price fleet.
- Remnants of “old” Sears battle post-bankruptcy “new” Sears in court.
- After scaling down the project, Neiman Marcus opens its first New York store at the new Hudson Yards development on the city’s West Side.
- Nordstrom stops reporting store comps, a metric analysts use to assess a retailer’s strength. Executives also tell analysts that its merchandise-free Local concept — which serves as a hub for returns, e-commerce pickup, and services like tailoring — is its future. The company opens two Locals in New York just ahead of the October debut of its first flagship in the city.
- Macy’s explores capping its Herald square flagship in New York with an office tower. Under pressure from activist investors, Macy’s pockets millions after selling off some of its best stores, including its Minneapolis flagship.
- Macy’s and J.C. Penney both announce partnerships with apparel resale site ThredUp.
- J.C. Penney pulls the plug on sales of furniture and major appliances.
2020
Several department stores report holiday comp declines in a season notable for its markdowns, but that is quickly overshadowed by the arrival of the COVID-19 pandemic to the U.S. Supply chains are roiled and department stores, with other nonessential retailers, are forced to temporarily close their doors for weeks as public health officials scramble to contain the coronavirus.
- Nordstrom pilots its own resale business at its New York store in January.
- In February, Macy’s says it will close 125 stores as it embarks on its Polaris turnaround strategy and suffers the first of several downgrades.
- Saks owner HBC finally goes private after months of negotiations. The company turns to a Nordstrom Rack veteran to lead its Saks Off 5th off-price business.
- Coresight finds that 70% of apparel consumers buy from Amazon, which is taking share from Macy’s, Walmart and Target, among others.
- Beginning in March, department stores of all stripes institute mass furloughs and pull various financial levers as the coronavirus pandemic takes a toll. Credit Suisse analysts deem department stores the “worst positioned” in retail to survive the pandemic’s challenges, “due to high debt levels, and low mixes of discretionary costs to cut (most have already had several rounds of cost cuts).”
- Dillard’s receives blowback for its resistance to closing stores.
- Green Street in April says the disease outbreak contracted a five-to 10-year trend of department stores exiting as mall anchors to the point where a little more than half of U.S. mall-based department stores could close for good by the end of 2021.
- J.C. Penney files for bankruptcy.
- Neiman Marcus files for bankruptcy and exits fairly quickly. The company won’t reopen its Hudson Yards store and six other locations nationwide. Earlier the company closed almost all off-price Last Call stores to focus on luxury.
- Lord & Taylor files for bankruptcy and, with no buyer in sight, liquidates all stores.
- Stage Stores files for bankruptcy, with plans to liquidate.
- Stein Mart files for bankruptcy.
- Forbes reports that Belk can’t pay vendors.
- Macy’s Polaris plans are put on ice as the pandemic disrupts business, and later the retailer says it will lay off nearly 4,000 corporate employees, including Story founder Rachel Shechtman. Macy’s reduces its Thanksgiving Day parade to a television-only event in Herald Square in place of its traditional blocks-long procession.
- Nordstrom says it will permanently close 16 full-line stores and its three Jeffrey specialty stores.
- Macy’s is dropped from the S&P 500 in April. When Kohl’s is dropped in September, it brings the number of department stores listed on that stock market index to zero. As Kohl’s is ejected in September, online marketplace Etsy is added.
https://www.zerohedge.com/markets/department-stores-dismal-decade-decline
October 6, 2020
Shipping Rates Rise
Dry Bulk Shipping Rates Just Hit A New 2020 High
by Tyler Durden Tue, 10/06/2020 – 13:25
By Greg Miller, senior editor at FreightWaves,
More ocean shipping signals are flashing green. First came a recovery in the container sector, driven by surging U.S. consumer demand. Now comes a rebound in dry bulk, the world’s largest freight market in terms of volume.
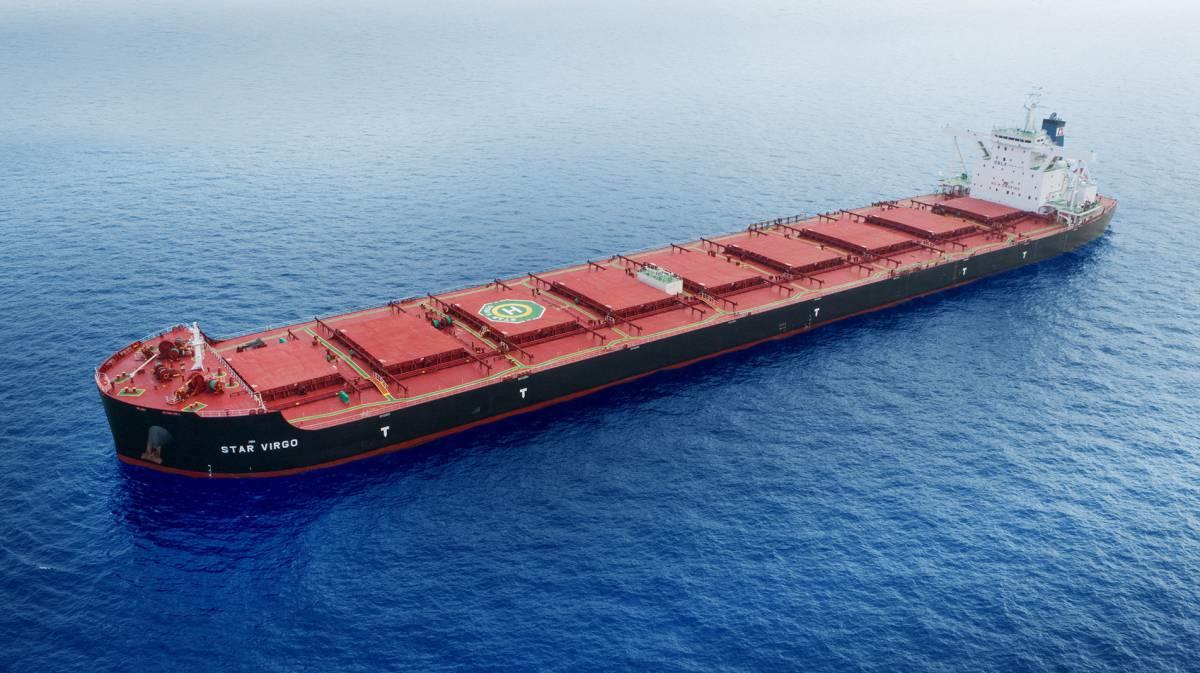
Rates for large bulkers known as Capesizes — ships carrying iron ore and coal that have a capacity of around 180,000 deadweight tons (DWT) — just hit year-to-date highs, driven primarily by industrial demand.
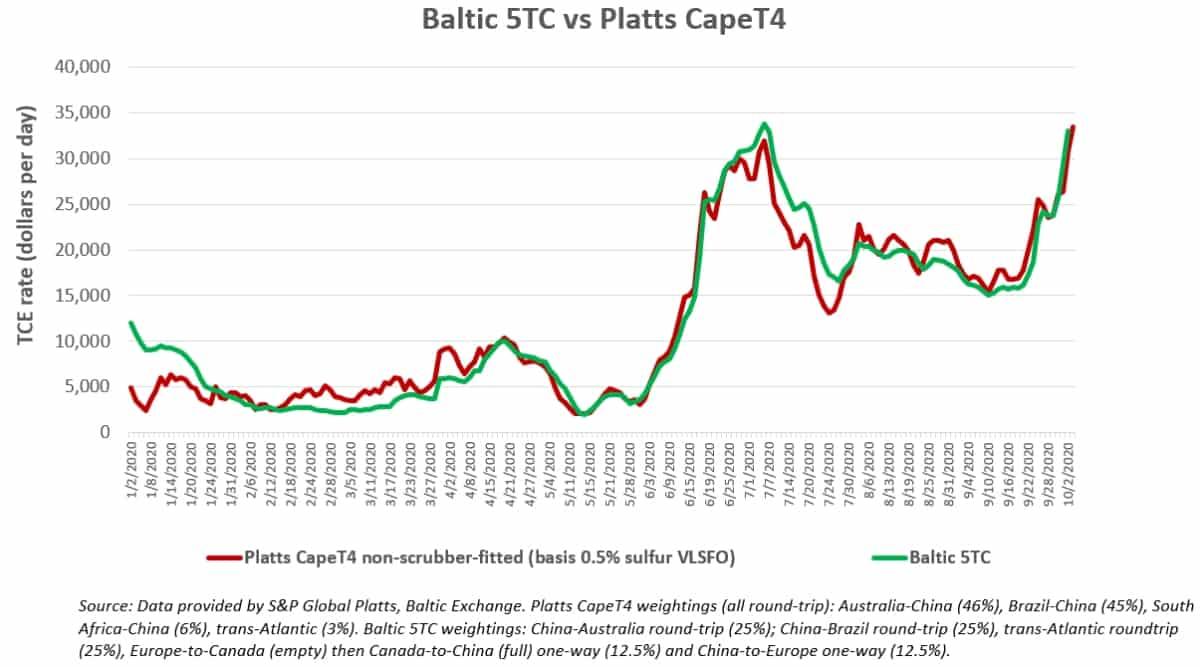
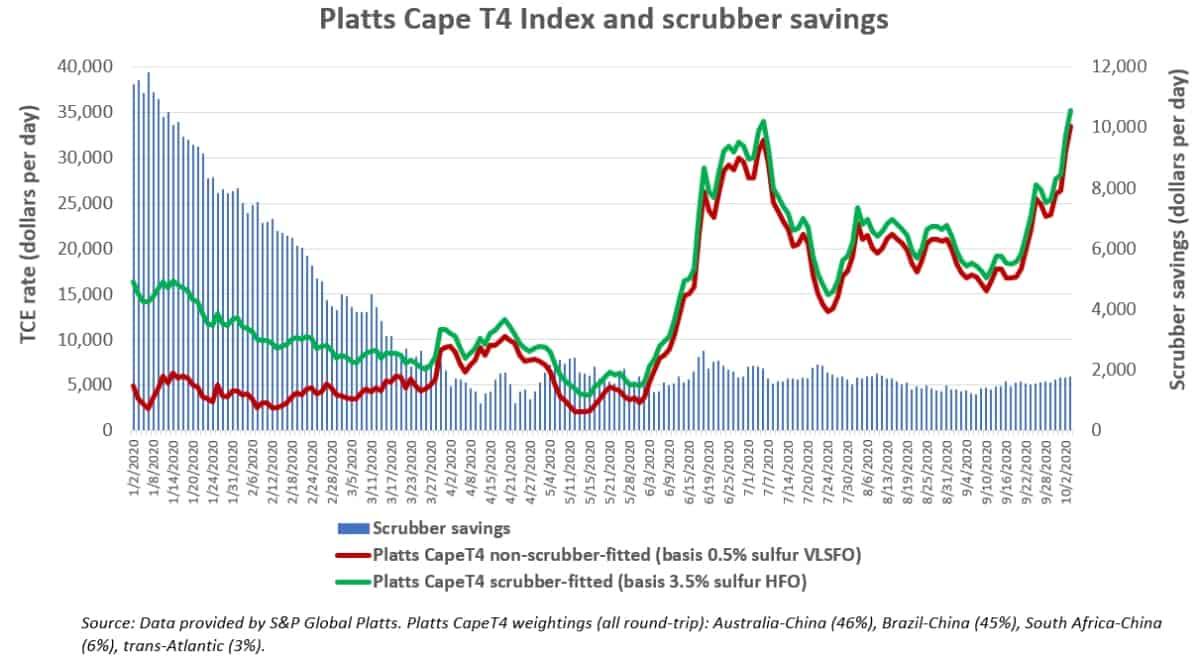
The Baltic Exchange’s 5TC index assessed Monday’s time-charter equivalent (TCE) rates for Capesizes burning 0.5% sulfur fuel at $34,293 per day. That’s up a whopping 127% month-on-month, marking the highest daily average since Sept. 23, 2019, and a year-on-year rise of 45%. Similarly, the Platts CapeT4 index assessed Monday’s rates for Capesizes burning 0.5% sulfur fuel at $33,438 per day.
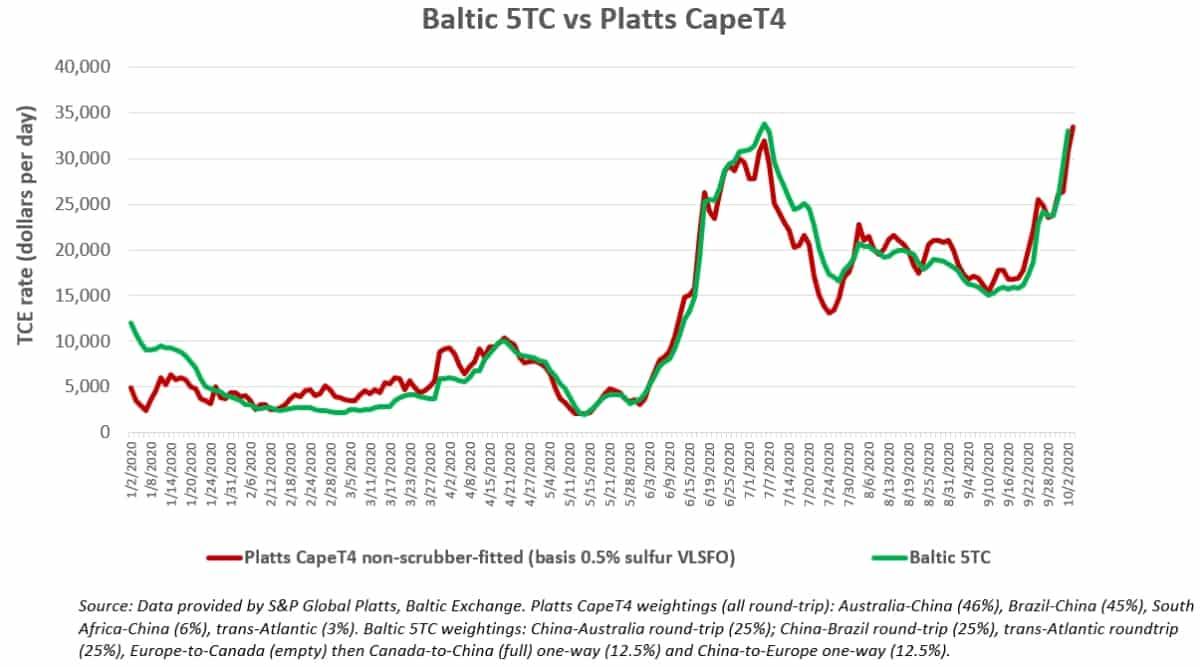
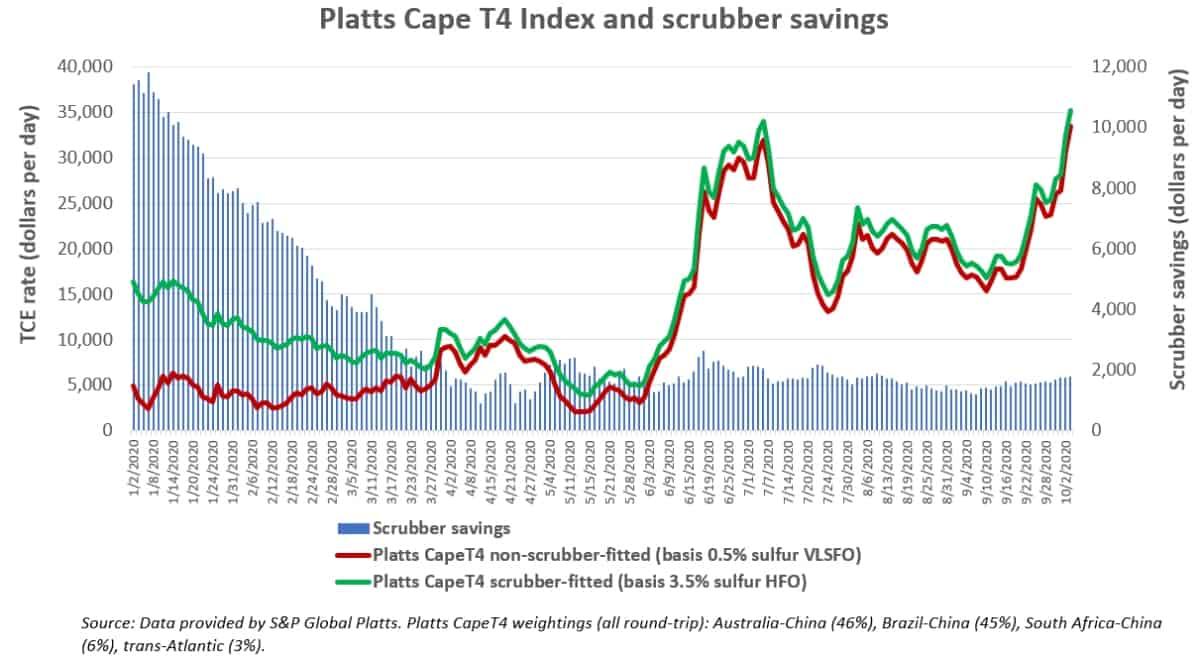
Platts also assesses rates for Capes that use exhaust-gas scrubbers and burn 3.5% sulfur heavy fuel oil. Due to much-slimmer-than-expected fuel spreads in the wake of the coronavirus, scrubber-equipped Capes currently save just under $1,800 per day. That brought scrubber Capes’ TCE rate to $35,253 per day.
Capesize rate drivers
Capesize rates are largely driven by iron ore volumes from Australia and Brazil and the extent that exports from those two sources match up (or not) with vessel tonnage positioned in the Atlantic and Pacific basins.
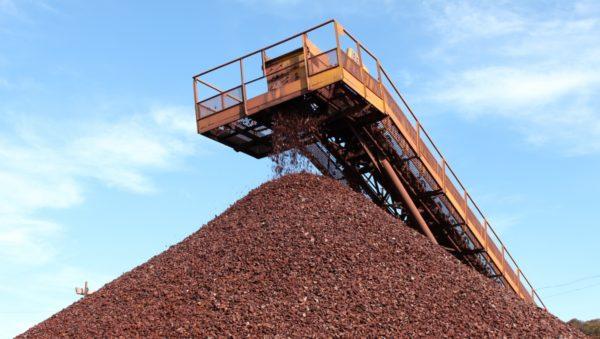
“The Cape index has been very strong on a lack of tonnage in the Atlantic,” Nick Ristic, lead dry cargo analyst at Braemar ACM Shipbroking, told FreightWaves. “Brazilian charterers have been extremely busy over the last couple of weeks covering October volumes, while shipments have jumped. Daily shipments from Brazil over the past seven days averaged 1.25 million [metric] tons per day, up 18% over the previous 10 days.”Brazilian iron-ore operations (Photo: Vale)
And it’s not all about Brazil and the country’s giant iron-ore miner, Vale (NYSE: VALE). According to Clarksons Platou Securities analyst Frode Mørkedal, “During the July-September period a good amount of Australian cargoes were removed from the market due to normal seasonal maintenance on the part of the large iron ore miners. But higher volumes have now returned to the market.”
Regardless of whether the iron ore is coming from Brazil or Australia, the demand driver is Chinese steel production. “Iron-ore demand from China continues to boom,” affirmed S&P Global Platts.
Sub-Cape vessel classes
Rates for smaller bulkers — which unlike Capes have high exposure to grain transport — have yet to follow the Capes’ lead.
The rates for Panamaxes (60,000-95,000 DWT) are only $12,400 per day, down 17% year-on-year, according to Clarksons. Rates for Supramaxes (45,000-60,000 DWT) are $10,900 per day, down 19% year-on-year.
Asked about the smaller bulker classes, Ristic told FreightWaves, “We are fairly positive on grain trades in the fourth quarter. U.S. soybean volumes are picking up, Brazilian corn shipments remain strong and Ukrainian corn exports are about to kick off.”
On the downside, “seriously depressed coal volumes globally are keeping some pressure on Panamax earnings.”
On the upside, Capesize strength should trickle down. “If high Cape rates are sustained, Panamaxes will naturally follow as Cape stems will start to be split,” said Ristic. A “stem” is a shipper’s quantity of cargo. Shippers will split a Capesize cargo into two Panamax cargoes if it’s cheaper to do so.
S&P Global Platts reported Monday that charterers are already starting to split Atlantic Basin Capesize cargoes into smaller stems.
Dry bulk stocks to bounce?
Shipping stock performance has diverged over the past three months. Tanker stocks have languished near their year-to-date lows, battered by storage-destocking headwinds. In contrast, container-ship leasing stocks have risen sharply over recent weeks, playing catch-up with already recovered charter rates. Will dry bulk stocks now bounce as rates rise?
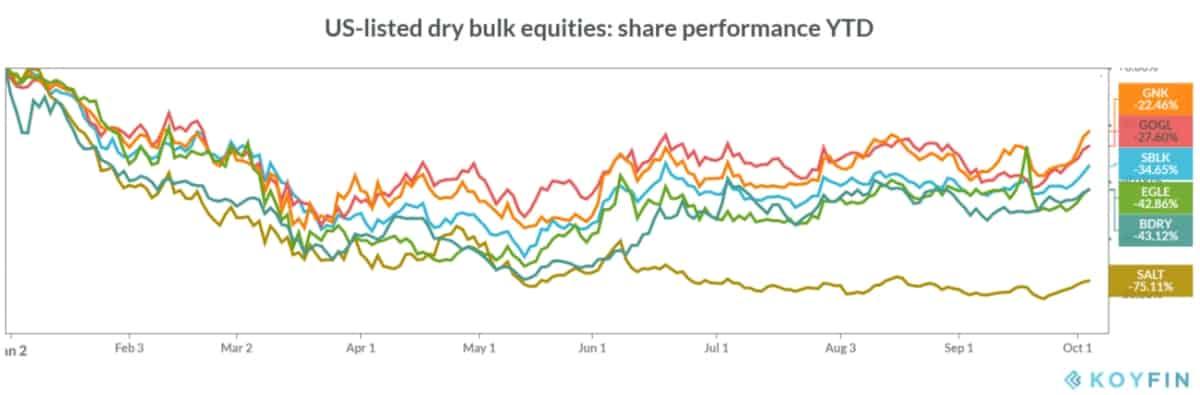
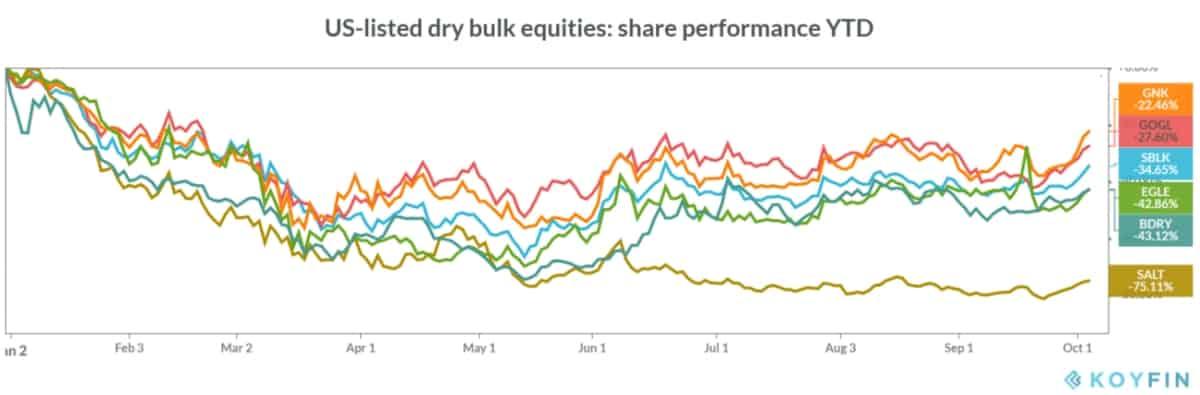
Stocks with high Capesize exposure include Star Bulk, Golden Ocean and Genco Shipping & Trading. Dry bulk stocks with high exposure to smaller asset classes include Scorpio Bulkers and Eagle Bulk. In addition, the Breakwave Dry Bulk Shipping Exchange Traded Fund buys freight futures to offer investors more direct exposure to rates.
These equities have been rising over the past week, however, with one exception they are still down 22%-43% year-to-date. (The outlier is Scorpio Bulkers, which is doing far worse: down 75%.)
When will rates retreat?
The problem for dry bulk stocks is that rates will almost certainly retreat in the months ahead. Is fleeting rate strength is enough to entice investors? “Some seem to be wondering how much more juice is left in the cherry [but] don’t be Boo-Boo Bear. There’s more juice. We promise!” wrote a broker at Barry Rogliano Salles.
Looking at the forward curve, Cape futures for the month of October rose to $28,553 per day on Monday — a positive sign. That said, December futures fell to $18,672 per day.
As Ristic explained, “Fourth-quarter FFAs [futures] are lower than current earnings and it’s extremely unlikely for these levels to be sustained for months at a time. The longer the current spike is sustained, futures will continue to rally. But if rates start to rapidly fall, the sell-off will likely be even more aggressive than the rally.”
Breakwave Advisors argued in a new blog post that it’s not about where rates peak, it’s about the average. In the past decade, Capesize rates peaked at $42,000 per day in 2013. “It will not be surprising to surpass such levels soon,” Breakwave predicted, acknowledging that rates would then inevitably correct.
Instead of dismissing the current situation as “another short-term spike,” Breakwave advised investors to focus on freight cost relative to the price of a cargo of iron ore or another dry commodity. Looked at this way, the freight cost percentage is now at a seven-year low relative to the cargo price.
Breakwave maintained that this creates room for the freight cost to rise, as the percentage of freight cost relative to the cargo price could revert higher. This could benefit rates over time. And for investors, the average rate over time is what to watch, not press headlines like Monday’s on new highs
https://www.zerohedge.com/commodities/dry-bulk-shipping-rates-hust-hit-new-2020-high
October 6, 2020
Shipping Rates Rise
Dry Bulk Shipping Rates Just Hit A New 2020 High
by Tyler Durden Tue, 10/06/2020 – 13:25
By Greg Miller, senior editor at FreightWaves,
More ocean shipping signals are flashing green. First came a recovery in the container sector, driven by surging U.S. consumer demand. Now comes a rebound in dry bulk, the world’s largest freight market in terms of volume.
Rates for large bulkers known as Capesizes — ships carrying iron ore and coal that have a capacity of around 180,000 deadweight tons (DWT) — just hit year-to-date highs, driven primarily by industrial demand.
The Baltic Exchange’s 5TC index assessed Monday’s time-charter equivalent (TCE) rates for Capesizes burning 0.5% sulfur fuel at $34,293 per day. That’s up a whopping 127% month-on-month, marking the highest daily average since Sept. 23, 2019, and a year-on-year rise of 45%. Similarly, the Platts CapeT4 index assessed Monday’s rates for Capesizes burning 0.5% sulfur fuel at $33,438 per day.
Platts also assesses rates for Capes that use exhaust-gas scrubbers and burn 3.5% sulfur heavy fuel oil. Due to much-slimmer-than-expected fuel spreads in the wake of the coronavirus, scrubber-equipped Capes currently save just under $1,800 per day. That brought scrubber Capes’ TCE rate to $35,253 per day.
Capesize rate drivers
Capesize rates are largely driven by iron ore volumes from Australia and Brazil and the extent that exports from those two sources match up (or not) with vessel tonnage positioned in the Atlantic and Pacific basins.
“The Cape index has been very strong on a lack of tonnage in the Atlantic,” Nick Ristic, lead dry cargo analyst at Braemar ACM Shipbroking, told FreightWaves. “Brazilian charterers have been extremely busy over the last couple of weeks covering October volumes, while shipments have jumped. Daily shipments from Brazil over the past seven days averaged 1.25 million [metric] tons per day, up 18% over the previous 10 days.”Brazilian iron-ore operations (Photo: Vale)
And it’s not all about Brazil and the country’s giant iron-ore miner, Vale (NYSE: VALE). According to Clarksons Platou Securities analyst Frode Mørkedal, “During the July-September period a good amount of Australian cargoes were removed from the market due to normal seasonal maintenance on the part of the large iron ore miners. But higher volumes have now returned to the market.”
Regardless of whether the iron ore is coming from Brazil or Australia, the demand driver is Chinese steel production. “Iron-ore demand from China continues to boom,” affirmed S&P Global Platts.
Sub-Cape vessel classes
Rates for smaller bulkers — which unlike Capes have high exposure to grain transport — have yet to follow the Capes’ lead.
The rates for Panamaxes (60,000-95,000 DWT) are only $12,400 per day, down 17% year-on-year, according to Clarksons. Rates for Supramaxes (45,000-60,000 DWT) are $10,900 per day, down 19% year-on-year.
Asked about the smaller bulker classes, Ristic told FreightWaves, “We are fairly positive on grain trades in the fourth quarter. U.S. soybean volumes are picking up, Brazilian corn shipments remain strong and Ukrainian corn exports are about to kick off.”
On the downside, “seriously depressed coal volumes globally are keeping some pressure on Panamax earnings.”
On the upside, Capesize strength should trickle down. “If high Cape rates are sustained, Panamaxes will naturally follow as Cape stems will start to be split,” said Ristic. A “stem” is a shipper’s quantity of cargo. Shippers will split a Capesize cargo into two Panamax cargoes if it’s cheaper to do so.
S&P Global Platts reported Monday that charterers are already starting to split Atlantic Basin Capesize cargoes into smaller stems.
Dry bulk stocks to bounce?
Shipping stock performance has diverged over the past three months. Tanker stocks have languished near their year-to-date lows, battered by storage-destocking headwinds. In contrast, container-ship leasing stocks have risen sharply over recent weeks, playing catch-up with already recovered charter rates. Will dry bulk stocks now bounce as rates rise?
Stocks with high Capesize exposure include Star Bulk, Golden Ocean and Genco Shipping & Trading. Dry bulk stocks with high exposure to smaller asset classes include Scorpio Bulkers and Eagle Bulk. In addition, the Breakwave Dry Bulk Shipping Exchange Traded Fund buys freight futures to offer investors more direct exposure to rates.
These equities have been rising over the past week, however, with one exception they are still down 22%-43% year-to-date. (The outlier is Scorpio Bulkers, which is doing far worse: down 75%.)
When will rates retreat?
The problem for dry bulk stocks is that rates will almost certainly retreat in the months ahead. Is fleeting rate strength is enough to entice investors? “Some seem to be wondering how much more juice is left in the cherry [but] don’t be Boo-Boo Bear. There’s more juice. We promise!” wrote a broker at Barry Rogliano Salles.
Looking at the forward curve, Cape futures for the month of October rose to $28,553 per day on Monday — a positive sign. That said, December futures fell to $18,672 per day.
As Ristic explained, “Fourth-quarter FFAs [futures] are lower than current earnings and it’s extremely unlikely for these levels to be sustained for months at a time. The longer the current spike is sustained, futures will continue to rally. But if rates start to rapidly fall, the sell-off will likely be even more aggressive than the rally.”
Breakwave Advisors argued in a new blog post that it’s not about where rates peak, it’s about the average. In the past decade, Capesize rates peaked at $42,000 per day in 2013. “It will not be surprising to surpass such levels soon,” Breakwave predicted, acknowledging that rates would then inevitably correct.
Instead of dismissing the current situation as “another short-term spike,” Breakwave advised investors to focus on freight cost relative to the price of a cargo of iron ore or another dry commodity. Looked at this way, the freight cost percentage is now at a seven-year low relative to the cargo price.
Breakwave maintained that this creates room for the freight cost to rise, as the percentage of freight cost relative to the cargo price could revert higher. This could benefit rates over time. And for investors, the average rate over time is what to watch, not press headlines like Monday’s on new highs
https://www.zerohedge.com/commodities/dry-bulk-shipping-rates-hust-hit-new-2020-high
October 5, 2020
NACD Interview
NACD Weighs In On the Chemicals and Coatings Markets
October 5, 2020 Eric Byer
The National Association of Chemical Distributors (NACD) is an international association based in Arlington, Virginia, with a membership comprising nearly 430 chemical distribution companies and their supply chain partners. NACD members represent more than 85 percent of the chemical distribution capacity in the nation and generate 93 percent of the industry’s gross revenue.
The organization’s members, operating in nearly every U.S. state through approximately 3,400 facilities, are responsible for more than 26,000 direct jobs in the U.S. Collectively, the distribution industry is responsible for almost 137,000 direct and indirect jobs. Chemical distributors in the U.S. are predominantly small regional businesses, many of which are family owned and multigenerational – on average having 30 employees and operating under extremely low margins.
PCI recently talked to Eric R. Byer, President and CEO of NACD, about the effect the global pandemic has had on chemical distributors, the outlook for the coatings market, and current legislation that the NACD is actively involved in to protect the chemicals industry.
PCI: How has the COVID-19 pandemic affected chemical distributors specifically, and what have they done to respond?
Byer: Fortunately, the chemical distribution industry has, by and large, fared much better than other sectors of the U.S. economy due to our essential link in commercial and industrial supply chains, and our ability to distribute much-needed products to combat the Coronavirus, like sterilizers needed for medical equipment, cleansers consumers use in their homes, hand sanitizer, and even personal protective equipment for first responders.
Nevertheless, like most of the world, the U.S. economy and the chemical distribution industry have not been immune to the ill effects COVID-19 has flung upon the globe. In terms of the broader United States, Gross Domestic Product fell five percent in the first quarter of 2020, and some estimate it fell by as much as 35 percent in the second quarter. Unless there is a dramatic improvement in growth over the remaining two quarters of the year, it is very likely the U.S. economy will have contracted for the first time since 2009.
The U.S. chemical sector has been able to weather the health and economic crisis better, but it still has had its share of troubles. Since February, employment has been down 2.1 percent – a fraction of what other industries like entertainment and hospitality have faced, but still concerning given the number of high-skilled jobs the industry needs to perform well. Chemical production is down 12 percent from this time last year, but the good news is shipments are up 2.3 percent in the last five months. And again, since February, prices are down 5.6 percent. However, wages have been holding steady, meaning that profit margins have been absorbing most of the price drop.
Most of the major industries that are users of chemicals have seen a large drop-off in demand. One particularly bright spot for chemical distributors has been the sale of isopropyl alcohol (IPA). Beginning in March, demand surged for IPA both here in the United States and globally due to its use in hand sanitizers and cleaning agents. Many NACD members store IPA as a “rainy day fund” of sorts, and have been able to draw upon those reserves to boost their sales when demand for other products has fallen off. Prices for IPA spiked across the globe to historically high levels this spring, and while they remain historically high, they are starting to come down slowly from their peak levels. This increase in demand and prices has been a key lifeline for NACD members that have been able to tap into that product market during the COVID-19 crisis.
Chemical distributors were deemed essential businesses during the pandemic and able to continue doing business serving their customers in paints, coatings and many other industries. They continued to take the safety and security of their operations, their employees, and their communities seriously – thanks to NACD Responsible Distribution®, NACD’s mandatory third-party-verified environmental, health, safety and security program. Throughout this entire health crisis, NACD members have taken steps to limit the spread of COVID-19 within their ranks. Most have allowed front office employees to work remotely when possible. For staff that are needed onsite, companies have instituted social distancing practices and daily temperature checks, restricted visitors from entering their facilities, provided PPE to workers, and undergone daily facility cleanings, among other strategies.
PCI: Have the partnerships between distributors and their principals been a benefit to the industries they serve throughout the pandemic? If so, how?
Byer: We saw many examples of the benefit of the close relationship between chemical distributors, their suppliers and their customers. Many were able to help each other obtain access to critical PPE when it wasn’t available from their regular providers. Additionally, many chemical distributors were able to become essential suppliers of hand sanitizer in volume to those companies who needed it for their operations and employees, as well as keeping product moving through the supply chain to keep customers’ businesses up and operating during the pandemic.
PCI: How has “virtual” business and learning been a factor throughout the pandemic?
Byer: Until recently, chemical producers and distributors have been slower to adopt to new opportunities posed by digital tools and technologies than some other industries such as banking and manufacturing that have streamlined operations and improve productivity as a result of digitalization.
However, opinions are changing, and chemical distributors are becoming far more aware of the benefits of investing and innovating in the digital space, especially in light of the COVID-19 pandemic. There are several platforms in the marketplace that have helped distributors launch their own branded e-commerce portals and supplement existing sales channels.
Shifting demographics are also driving change. A significant proportion of those working in the chemical industry are expected to retire in the next five years, and the younger generation entering the workforce are bringing with them a better understanding of how these new technologies work. Many of these systems offer distributors and manufacturers/customers with a closed B-to-B network offering a simple-to-use, secure way to buy and sell chemicals.
Beyond these sales platforms, chemical distributors have been engaging in many on-line webinars, workshops and conferences through NACD to continue to invest in their employees and meet their training and compliance needs. The Association’s online training platform, NACD U, offers the industry over 200 courses on safety, security, operations and Responsible Distribution at low cost.
PCI: What is your outlook for the coatings industry in the short and long term?
Byer: The paint and coatings industry is one of the key customers for NACD members. Based on data from the Bureau of Economic Analysis (BEA), more than $27.00 of every $100 of paints and coatings produced in the United States consists of chemicals like industrial gases, basic organic/inorganic chemicals, and resins used by paint manufacturers in their production process. This figure compares with the 20.6 percent of the overall cost of paints and coatings going to wages and benefits for company workers.
Considering that about $40.3 billion worth of paints and coatings were produced in the United States last year, this is a very important segment for the chemical distribution industry, with over $11.2 billion worth of chemical products purchases.
Paint and coatings sales have been relatively flat over the past few years. According to the Bureau of Economic Analysis, paint and coatings manufacturers’ sales are up by just 5.8 percent, for a compound annual growth rate of 0.3 percent per year, which is well below the 2.2 percent growth in the overall economy during the same period.
Interestingly, the growth in paint and coatings sales has not kept pace with new home sales, a major market for such products. Back in 1997, overall paint sales were equivalent to 6.8 percent of the value of every new home sold in America. This does not mean that each home used this much paint, but overall sales for all markets equaled 6.8 percent of the value of every new house. A similar ratio continued up until the recession when it fell to about 4.6 percent, a level that is up to just about 5 percent today (Figure 1). Comparing overall paint sales to overall construction spending, the trend is even more dramatic, and paint as a percent of construction spending has fallen by 26.9 percent.
What this means is that the housing and construction market is less important for paint and coatings sales than it was prior to the 2006/07 recession. According to the American Coatings Association, the largest drivers impacting the coatings industry overall are the rising needs in the construction and automotive sectors, with the architectural segment alone accounting for about half of the market. The trends therefore, are problematic, and may be a big reason why paint and coating sales have not kept up with overall economic activity.
In order to keep up sales, paint and coatings manufacturers will need to develop new markets outside of automotive (which is likely to be impacted by tariffs in the near term) and construction. Again, according to the American Coatings Association, the industrial and specialty purpose segments have contributed to the growth of the paint and coatings market, with demand for products like marine, antimicrobial and corrosion resistant coatings all increasing in recent years.
PCI: What is some of the current legislation that the NACD is actively involved in to protect the chemicals industry?
Byer: As NACD set out our priorities at the beginning of this year, we were hopeful but acknowledged what would likely be a challenging environment in a presidential election year. Then the Coronavirus pandemic hit and turned everything upside down for the chemical distribution industry, our country and the world, and we immediately pivoted to supporting our members through this extraordinary time. NACD established an online Coronavirus Resource Center to keep the industry up to date on the latest developments. We worked closely with the Administration to ensure that chemical distributors were allowed to continue their important work as essential businesses, and we developed guidance for accessing the Paycheck Protection Program (PPP) for those who needed it to weather the pandemic. NACD continues to work to encourage common-sense approaches to taxation and forgiveness of PPP loan dollars.
Fortunately, Congress has also continued its work on important issues beyond COVID-19. Most notably for our industry is reauthorization of the U.S. Department of Homeland Security’s Chemical Facility Anti-Terrorism Standards (CFATS) program, which after several small extensions was reauthorized in July for a three-year period. This program is critical to securing our nation’s chemical facilities against potential acts of terrorism.
Another important issue for the chemical distribution and paint and coatings industry is recent action to designate per- and polyfluoroalkyl substances (PFAS) as hazardous substances. The U.S. Environmental Protection Agency (EPA) already requires comprehensive toxicity testing be conducted on all PFAS under the Toxic Substances Control Act (TSCA) – a move the effectively bars the manufacturing of PFAS of concern. Our industries must be constantly vigilant against efforts to group very different chemicals under a single regulatory umbrella, and we at NACD will continue to closely follow and thoughtfully weigh in on this issue.
Trade is also front and center. Last year, NACD successfully petitioned the Trump administration to exempt hundreds of chemical products from the Section 301 tariffs on imported goods, but the tariffs continue to have an adverse impact on our industry and others. NACD supports the Generalized System of Preferences (GSP) and the Miscellaneous Tariff Bill (MTB) – two programs that effectively reduce the tariff rates on thousands of goods that either cannot be sourced domestically or otherwise would put U.S. businesses at a global disadvantage because of higher import duties – and both require action in 2020. The GSP, which helps the world’s developing countries increase and diversify their trade with the U.S while significantly reducing tariffs on imported raw materials used by chemical distributors and others, must be reauthorized before the end of this year. We’ll be working tirelessly to ensure it remains a priority.
https://www.pcimag.com/articles/107930-nacd-weighs-in-on-the-chemicals-and-coatings-markets
October 5, 2020
NACD Interview
NACD Weighs In On the Chemicals and Coatings Markets
October 5, 2020 Eric Byer
The National Association of Chemical Distributors (NACD) is an international association based in Arlington, Virginia, with a membership comprising nearly 430 chemical distribution companies and their supply chain partners. NACD members represent more than 85 percent of the chemical distribution capacity in the nation and generate 93 percent of the industry’s gross revenue.
The organization’s members, operating in nearly every U.S. state through approximately 3,400 facilities, are responsible for more than 26,000 direct jobs in the U.S. Collectively, the distribution industry is responsible for almost 137,000 direct and indirect jobs. Chemical distributors in the U.S. are predominantly small regional businesses, many of which are family owned and multigenerational – on average having 30 employees and operating under extremely low margins.
PCI recently talked to Eric R. Byer, President and CEO of NACD, about the effect the global pandemic has had on chemical distributors, the outlook for the coatings market, and current legislation that the NACD is actively involved in to protect the chemicals industry.
PCI: How has the COVID-19 pandemic affected chemical distributors specifically, and what have they done to respond?
Byer: Fortunately, the chemical distribution industry has, by and large, fared much better than other sectors of the U.S. economy due to our essential link in commercial and industrial supply chains, and our ability to distribute much-needed products to combat the Coronavirus, like sterilizers needed for medical equipment, cleansers consumers use in their homes, hand sanitizer, and even personal protective equipment for first responders.
Nevertheless, like most of the world, the U.S. economy and the chemical distribution industry have not been immune to the ill effects COVID-19 has flung upon the globe. In terms of the broader United States, Gross Domestic Product fell five percent in the first quarter of 2020, and some estimate it fell by as much as 35 percent in the second quarter. Unless there is a dramatic improvement in growth over the remaining two quarters of the year, it is very likely the U.S. economy will have contracted for the first time since 2009.
The U.S. chemical sector has been able to weather the health and economic crisis better, but it still has had its share of troubles. Since February, employment has been down 2.1 percent – a fraction of what other industries like entertainment and hospitality have faced, but still concerning given the number of high-skilled jobs the industry needs to perform well. Chemical production is down 12 percent from this time last year, but the good news is shipments are up 2.3 percent in the last five months. And again, since February, prices are down 5.6 percent. However, wages have been holding steady, meaning that profit margins have been absorbing most of the price drop.
Most of the major industries that are users of chemicals have seen a large drop-off in demand. One particularly bright spot for chemical distributors has been the sale of isopropyl alcohol (IPA). Beginning in March, demand surged for IPA both here in the United States and globally due to its use in hand sanitizers and cleaning agents. Many NACD members store IPA as a “rainy day fund” of sorts, and have been able to draw upon those reserves to boost their sales when demand for other products has fallen off. Prices for IPA spiked across the globe to historically high levels this spring, and while they remain historically high, they are starting to come down slowly from their peak levels. This increase in demand and prices has been a key lifeline for NACD members that have been able to tap into that product market during the COVID-19 crisis.
Chemical distributors were deemed essential businesses during the pandemic and able to continue doing business serving their customers in paints, coatings and many other industries. They continued to take the safety and security of their operations, their employees, and their communities seriously – thanks to NACD Responsible Distribution®, NACD’s mandatory third-party-verified environmental, health, safety and security program. Throughout this entire health crisis, NACD members have taken steps to limit the spread of COVID-19 within their ranks. Most have allowed front office employees to work remotely when possible. For staff that are needed onsite, companies have instituted social distancing practices and daily temperature checks, restricted visitors from entering their facilities, provided PPE to workers, and undergone daily facility cleanings, among other strategies.
PCI: Have the partnerships between distributors and their principals been a benefit to the industries they serve throughout the pandemic? If so, how?
Byer: We saw many examples of the benefit of the close relationship between chemical distributors, their suppliers and their customers. Many were able to help each other obtain access to critical PPE when it wasn’t available from their regular providers. Additionally, many chemical distributors were able to become essential suppliers of hand sanitizer in volume to those companies who needed it for their operations and employees, as well as keeping product moving through the supply chain to keep customers’ businesses up and operating during the pandemic.
PCI: How has “virtual” business and learning been a factor throughout the pandemic?
Byer: Until recently, chemical producers and distributors have been slower to adopt to new opportunities posed by digital tools and technologies than some other industries such as banking and manufacturing that have streamlined operations and improve productivity as a result of digitalization.
However, opinions are changing, and chemical distributors are becoming far more aware of the benefits of investing and innovating in the digital space, especially in light of the COVID-19 pandemic. There are several platforms in the marketplace that have helped distributors launch their own branded e-commerce portals and supplement existing sales channels.
Shifting demographics are also driving change. A significant proportion of those working in the chemical industry are expected to retire in the next five years, and the younger generation entering the workforce are bringing with them a better understanding of how these new technologies work. Many of these systems offer distributors and manufacturers/customers with a closed B-to-B network offering a simple-to-use, secure way to buy and sell chemicals.
Beyond these sales platforms, chemical distributors have been engaging in many on-line webinars, workshops and conferences through NACD to continue to invest in their employees and meet their training and compliance needs. The Association’s online training platform, NACD U, offers the industry over 200 courses on safety, security, operations and Responsible Distribution at low cost.
PCI: What is your outlook for the coatings industry in the short and long term?
Byer: The paint and coatings industry is one of the key customers for NACD members. Based on data from the Bureau of Economic Analysis (BEA), more than $27.00 of every $100 of paints and coatings produced in the United States consists of chemicals like industrial gases, basic organic/inorganic chemicals, and resins used by paint manufacturers in their production process. This figure compares with the 20.6 percent of the overall cost of paints and coatings going to wages and benefits for company workers.
Considering that about $40.3 billion worth of paints and coatings were produced in the United States last year, this is a very important segment for the chemical distribution industry, with over $11.2 billion worth of chemical products purchases.
Paint and coatings sales have been relatively flat over the past few years. According to the Bureau of Economic Analysis, paint and coatings manufacturers’ sales are up by just 5.8 percent, for a compound annual growth rate of 0.3 percent per year, which is well below the 2.2 percent growth in the overall economy during the same period.
Interestingly, the growth in paint and coatings sales has not kept pace with new home sales, a major market for such products. Back in 1997, overall paint sales were equivalent to 6.8 percent of the value of every new home sold in America. This does not mean that each home used this much paint, but overall sales for all markets equaled 6.8 percent of the value of every new house. A similar ratio continued up until the recession when it fell to about 4.6 percent, a level that is up to just about 5 percent today (Figure 1). Comparing overall paint sales to overall construction spending, the trend is even more dramatic, and paint as a percent of construction spending has fallen by 26.9 percent.
What this means is that the housing and construction market is less important for paint and coatings sales than it was prior to the 2006/07 recession. According to the American Coatings Association, the largest drivers impacting the coatings industry overall are the rising needs in the construction and automotive sectors, with the architectural segment alone accounting for about half of the market. The trends therefore, are problematic, and may be a big reason why paint and coating sales have not kept up with overall economic activity.
In order to keep up sales, paint and coatings manufacturers will need to develop new markets outside of automotive (which is likely to be impacted by tariffs in the near term) and construction. Again, according to the American Coatings Association, the industrial and specialty purpose segments have contributed to the growth of the paint and coatings market, with demand for products like marine, antimicrobial and corrosion resistant coatings all increasing in recent years.
PCI: What is some of the current legislation that the NACD is actively involved in to protect the chemicals industry?
Byer: As NACD set out our priorities at the beginning of this year, we were hopeful but acknowledged what would likely be a challenging environment in a presidential election year. Then the Coronavirus pandemic hit and turned everything upside down for the chemical distribution industry, our country and the world, and we immediately pivoted to supporting our members through this extraordinary time. NACD established an online Coronavirus Resource Center to keep the industry up to date on the latest developments. We worked closely with the Administration to ensure that chemical distributors were allowed to continue their important work as essential businesses, and we developed guidance for accessing the Paycheck Protection Program (PPP) for those who needed it to weather the pandemic. NACD continues to work to encourage common-sense approaches to taxation and forgiveness of PPP loan dollars.
Fortunately, Congress has also continued its work on important issues beyond COVID-19. Most notably for our industry is reauthorization of the U.S. Department of Homeland Security’s Chemical Facility Anti-Terrorism Standards (CFATS) program, which after several small extensions was reauthorized in July for a three-year period. This program is critical to securing our nation’s chemical facilities against potential acts of terrorism.
Another important issue for the chemical distribution and paint and coatings industry is recent action to designate per- and polyfluoroalkyl substances (PFAS) as hazardous substances. The U.S. Environmental Protection Agency (EPA) already requires comprehensive toxicity testing be conducted on all PFAS under the Toxic Substances Control Act (TSCA) – a move the effectively bars the manufacturing of PFAS of concern. Our industries must be constantly vigilant against efforts to group very different chemicals under a single regulatory umbrella, and we at NACD will continue to closely follow and thoughtfully weigh in on this issue.
Trade is also front and center. Last year, NACD successfully petitioned the Trump administration to exempt hundreds of chemical products from the Section 301 tariffs on imported goods, but the tariffs continue to have an adverse impact on our industry and others. NACD supports the Generalized System of Preferences (GSP) and the Miscellaneous Tariff Bill (MTB) – two programs that effectively reduce the tariff rates on thousands of goods that either cannot be sourced domestically or otherwise would put U.S. businesses at a global disadvantage because of higher import duties – and both require action in 2020. The GSP, which helps the world’s developing countries increase and diversify their trade with the U.S while significantly reducing tariffs on imported raw materials used by chemical distributors and others, must be reauthorized before the end of this year. We’ll be working tirelessly to ensure it remains a priority.
https://www.pcimag.com/articles/107930-nacd-weighs-in-on-the-chemicals-and-coatings-markets
 Everchem Updates Archive
 Sign Up for Email Updates