
Current Affairs
February 6, 2025
Residential Furniture Update
Residential furniture orders slump in November, cautious optimism for 2025
February 4, 2025 | 3:02 pm CST

Photo By Spacejoy on Unsplash
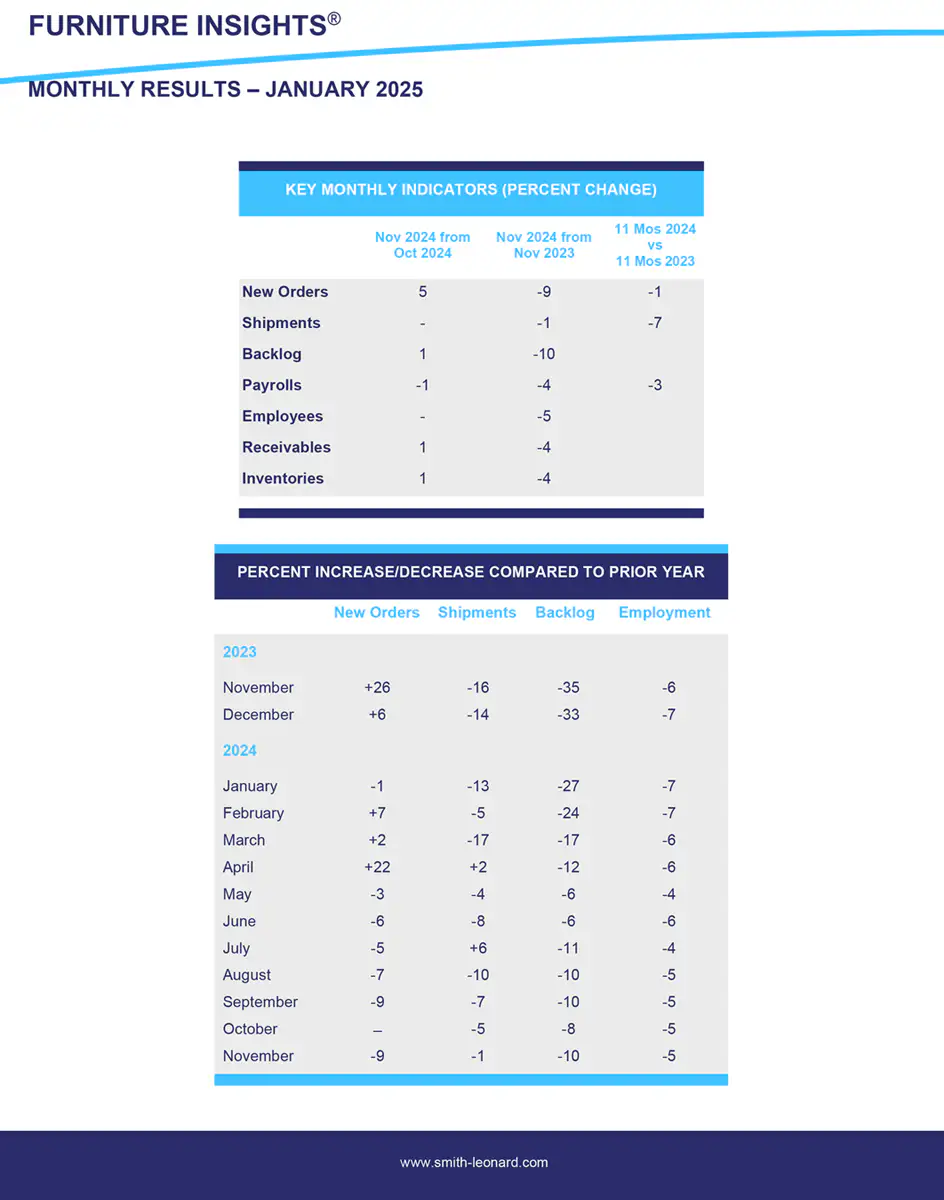
HIGH POINT, N.C. — New residential furniture orders fell 9% in November compared to the same period in 2023, according to the January issue of Furniture Insights. This decline follows a relatively flat October and marks a return to the downward trend observed from May through September. Approximately 40% of the survey participants reported increased orders in November compared to a year ago.
However, new orders were up 5% compared to October 2024 figures although down slightly for the year-to-date, noted Mark Laferriere, assurance partner at Smith Leonard, the accounting and consulting firm that produces the monthly report.
November shipments were down 1% compared to 2023 figures, and flat with October 2024. Year to date through November 2024, shipments were down 7% compared to 2023. Backlogs were down 10% compared to November 2023, but up 1% from October 2024 “as current new orders outpaced shipments during the last month.”
“Receivable levels were up 1% from October 2024, but down 4% from November 2023, both of which are materially in line with the respective shipment trends, given normal timing differences with collections,” Laferriere noted. “Inventories were consistent with October 2024 at up 1% and down 4% from
November 2023, which are in line with prior periods and current operational levels,” he added.
On a seasonally adjusted basis, sales at furniture and home furnishings stores were up 2.3% in December compared to the previous month and up 8.4% from December 2023. However, sales were down 2.2% for the year to date December 2024, compared to the same period for 2023 on an unadjusted basis, according to the January Furniture Insights.
Future projections are difficult, Laferriere said, without knowing the extent of the impact tariffs will have on the furniture industry, housing and the overall economy. Domestic manufacturers, especially those with “hybrid operations,” will be impacted through their outsourcing of materials and components.
“While likely greatly oversimplifying a very complex situation, an additional 10% tariff on Chinese goods would seem manageable given the inflationary pressures the industry has dealt with in the last few years, coupled with the long product pipeline allowing time for companies to make necessary adjustments,” he noted. “What seems more immediately concerning is the potential impact of tariffs on Canadian lumber utilized by the US housing industry as well as Canadian energy and the impact that could have on inflation in general, and specifically, consumer spending, interest rates, and ultimately housing activity that drives the furniture industry.
“This all follows a Vegas market which was largely reported to be positive, an averted port strike last month, as well as recent gains in housing and positive trends at retail.”
Laferriere added, “What makes this situation so difficult are the unknowns, the volatility, and the potential for change/reversals with or without notice, including the potential for tariffs on other Asian countries such as Vietnam and the impact of expected retaliatory tariffs on U.S. exports.
“Those in the industry are certainly smart enough and experienced enough to navigate any playing field, but they just need to know the rules of the game they’re playing. So, while these items are certainly disruptive in the short-term, the industry has dealt with similar situations in the past and we’re hopeful there are still enough things trending in the right direction so that the positive outlook for 2025, especially the second half, will materialize for those who have worked so hard to get to this point.”
February 2, 2025
Tariff Thoughts
All About The New Trump Tariffs, And Why The Hysteria Is Overblown
by Tyler Durden
Sunday, Feb 02, 2025 – 02:35 PM
By Peter Tchir of Academy Securities
Some Tariff Basics
Report after report I read seems to jump straight to either the good from tariffs (getting others to pay our taxes, advantage to American manufacturing, etc.) or to the doom and gloom of tariffs (inflation, trade wars, etc.). While we all understand the basics of tariffs, or at least I think I do, it seems worth spending a minute or two making sure that we are all on the same page.
My understanding is that the importer of a good pays the tariff to the government at the port or place of entry of the good into the country.
So, if you pay $100 for something from Canada or Mexico, you pay a $25 tariff, and your cost has increased to $125.
Which begs the question – who pays the $25 tariff?
One of the first things most importers will do is ask for a reduction in price from the exporter. If I was doing business thinking that something was only going to cost $100 and it now costs $125, I’d try to negotiate my purchase price down.
What I find “interesting” is if the exporter takes a 20% haircut, the price stays at $100. 20%off of $100 is $80. Then a 25% tariff on something for $80 is $20, getting us back to $100.
Step 1 is getting a discount, where even a 10% discount means the tariff only increases costs by 12.5%.
Now let’s look at the FX market (which maybe we should have done before step 1, but it would be a pain to rewrite stuff, and it isn’t really a step, as it is outside the control of the importer and the exporter, though no less important).
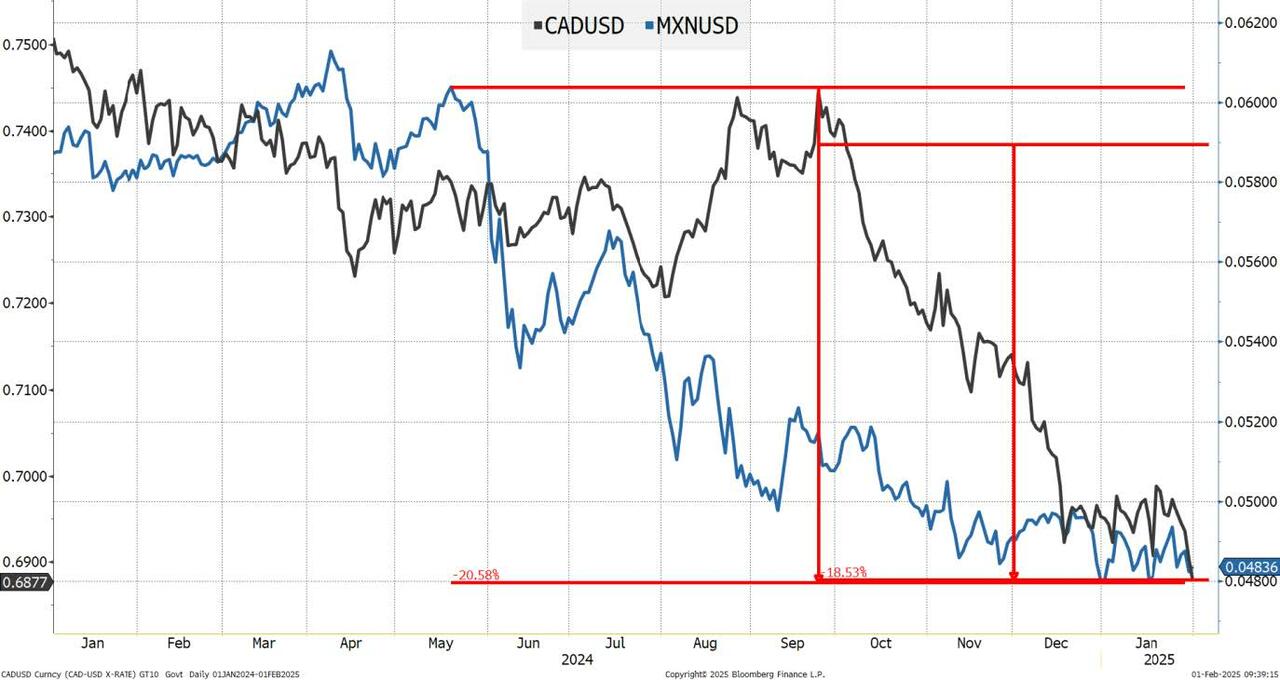
Since the summer, the Peso has declined by 20% versus the dollar and since late September, the Canadian Dollar has dropped by around 18%.
Let’s say that back in September, a Canadian exporter was happy to get paid 135 CAD. That translates into 100 USD for the importer. Let’s say that the Canadian exporter is still happy to accept the equivalent of 135 CAD. That drops the USD price to 93 for the importer. Making the “new” cost to the importer, including the tariff, “only” $116.25. This is all moving around in real time and has been a cumulative move, so this is a massive oversimplification, but still relevant.
The currency market is already helping the importer.
Step 2 is for the importer to figure out what amount of profit he is willing to forgo, if any. Assuming the importer was paying $100 it seems reasonable to assume that the price for the consumer is significantly more. For argument’s sake, let’s say the final price was $200. There is distribution and selling costs, etc. that the importer pays to sell the product on to the next leg. Maybe $200 is too high? Possibly, but I’m not sure it is that unreasonable for many finished goods. Now $25 out of $200 is “only” 12.5%. Giving up 12.5% is probably too much, but is 5% reasonable?
So, let’s look at this possibility (which as a whole, doesn’t seem too far-fetched to me).
Negotiate a 10% discount from the Canadian or Mexican exporter. Argue that it is “temporary” but crucial if you don’t want me (the importer) looking for alternative suppliers. Add in that you (the exporter) will also take a hit.
So, the Canadian exporter reduces the cost from 135 CAD to 121.5 CAD (in hopes it is temporary, and they don’t want to risk losing this customer to another provider of such goods).
Due to the big increase in the USD, the cost is only $83.40 (the importer has been making a lot of extra money in the past few months, but that is always a risk and may well have been hedged).
The 25% tariff is $20.85, bringing the total cost to $104.25.
In your planning, as of a month or two ago, you were anticipating a cost of $100. It is now just under $105. Do you raise your final prices, or leave them, at least for a little while, anticipating Canada (or Mexico) will make progress on fentanyl and the tariff will go away? That seems at least plausible, and it might depend on how easy it is for you to raise and lower prices. Is the hit to profit margin, hopefully a temporary one, worth not having to deal with a new supplier?
If the alternative supplier is Canadian or Mexican, they have the same problem.
If the supplier is from elsewhere, presumably there will be some logistics in getting their goods over in time.
The alternative, an American supplier, does look better as they were just given an effective cost benefit, but not really a 25% cost benefit. The dollar strength takes away some of the desire to shift to a domestic supplier. Presumably, the domestic supplier was already more expensive (or not as good, or there is some other reason why they weren’t being used). So, even with the indirect competitive boost, is it worth it?
Read more here: https://www.zerohedge.com/markets/all-about-new-trump-tariffs-and-why-hysteria-overblown
January 29, 2025
Office Market Rebounds
Investors Who Shunned the U.S. Office Market Are Coming Back
Investors who shunned the beleaguered U.S. office market in recent years are coming back, brightening the outlook for the sector after five years of turmoil.
Some investors are buying premium-quality buildings that are burdened with debt, or scooping up half-empty towers for pennies on the dollar. Others are bidding on obsolete office properties with an eye toward converting them to apartments. Some big foreign investors are showing renewed interest, hoping to beat what they believe will be an even larger surge of buying later in 2025.
“People are making their bets,” said Gary Phillips, managing director of real-estate investment banking firm Eastdil Secured.
The volume of office building sales increased to $63.6 billion in 2024, up 20% from 2023, according to data firm MSCI. That activity still pales compared with 2015 to 2019, when volume averaged $142.9 billion a year. But it marked the first increase since 2021.
And with a lot of cash sitting on the sidelines, brokers expect sales activity to continue to accelerate in 2025. Opportunistic real-estate funds had $196.8 billion available at the end of last year, up from $179.9 billion at the end of 2020, according to data fund Preqin.
Norges Bank Investment Management, the giant Norwegian sovereign-wealth fund, last month purchased the 50.1% stake it didn’t own in eight office properties in Boston, San Francisco and Washington, D.C., in a deal that valued them at $1.9 billion.
Norges last year also bought an office building on Sand Hill Road in Menlo Park, Calif., a strip filled with venture-capital firms. The two deals last year were the fund’s first U.S. office investments since 2018.
“We see an opportunity being a very large capital source that is willing to write checks in a sector that most of our peers are still not willing to invest in,” said John McCarthy, head of U.S. real estate for Norges.
The budding buying spree offers more encouraging news after the rise of remote work and the increase in interest rates greatly depressed office values.
Now, investors point to a pickup in leasing activity as businesses start requiring workers to be back in offices more.
“We hear from customers they’re going to continue bringing more workers back to the office. In many cases, they don’t have enough space to accommodate the transition,” said Colin Connolly, chief executive of Cousins Properties. His firm bought office properties in Atlanta, Austin, Texas, and Charlotte, N.C., recently.
Certain business districts are also experiencing shortages of the most desirable space and rising rents because there has been practically no new development in recent years.
Owners of high-quality office buildings in good markets “should be on much better footing to start the new year than they have in recent memory,” real-estate analytics firm Green Street said in a January report.
A venture of investment manager Hines and Rialto Capital has raised nearly $750 million for a debt fund, after banks and other lenders have fled the office market.
The partnership is targeting well-leased office buildings that are having trouble finding lenders. It is also looking to lend to buyers of office buildings sold at huge discounts from what they were worth before the pandemic.
Office towers acquired at cut-rate prices offer the new owner a lot more flexibility. “By financing an asset reduced in price, it allows owners to lower rents,” said Alfonso Munk, co-head of investment management for Hines.
The office market still faces a number of challenges, including high vacancy rates and loan delinquencies. Many investors remain leery about the sector and favor other types of commercial real estate, such as multifamily buildings or warehouses.
Values for less than premium grade A office buildings are about 35% to 60% lower than they were before the pandemic, according to Green Street.
But more sellers are finally capitulating. Many had been hoping that interest rates would fall further this year, boosting commercial property values. Recently, the Federal Reserve indicated that it would likely keep rates steady, convincing more owners to put their properties on the block.
“Rates aren’t going to be the saving grace that a lot of people thought,” said Dylan Burzinski of Green Street.
Some buyers are even ready to take a chance on buildings that are located in prime locations near transport hubs but are struggling with debt and too much empty space. New York landlord RXR this month acquired a 49% stake in a Midtown Manhattan tower. (The building is home to Fox Corp. and Wall Street Journal owner News Corp.)
The 2 million-square-foot building is losing one of its largest tenants, which will drive vacancy up to about 25%. It also has $1 billion of debt coming due this year, making it tricky to refinance because of high rates.
RXR is planning to invest more than $300 million to attract new tenants by adding a new entrance, new plaza and gym. The firm can afford to do this because its purchase of a 49% stake values the building at $1.3 billion, including the new capital. That is about $700 million less than the building was worth in a 2015 refinancing.
“If we can come in and fix the capital structure, we’ll have no problem leasing the space because the market has gotten stronger,” said Scott Rechler, RXR’s chief executive.
January 23, 2025
Wood Coatings Update
Wood coatings market to reach $15.18 billion by 2030
By Dakota Smith
January 22, 2025 | 11:49 am CST

NEWARK, Del. — The global wood coatings market is poised for significant growth, with demand expected to reach $15.18 billion by 2030. Driven by increasing construction activities, furniture production, and the rising demand for protective and aesthetic solutions, The market is projected to expand at a robust CAGR of 6.2% during the forecast period from 2025 to 2035.
Residential end-user is the largest market for wood protection products, driven by maintenance demand for items such as fences, siding, and decks. Non-residential and non-building use account for a much smaller market for wood protection products.
Market growth drivers:
- Housing market expansion: The steady growth of the housing sector, especially in emerging economies, has significantly boosted the demand for wood coatings. The need for durable and visually appealing wooden furniture and flooring is a major contributor to market growth.
- Preference for eco-friendly solutions: Consumers and industries alike are shifting towards low-VOC (volatile organic compound) and water-based coatings to meet stringent environmental regulations and reduce the carbon footprint.
- Rising renovation and remodeling: The increased frequency of home renovations, spurred by urbanization and lifestyle changes, has escalated the use of wood coatings in the maintenance of doors, cabinets, and furniture.
- Technological advancements: Innovations such as UV-cured coatings and nanotechnology-based products have enhanced the durability, scratch resistance, and aesthetic quality of wood coatings, broadening their applications.
Trends in the wood coatings market:
- Sustainable coatings: As sustainability becomes a priority, manufacturers are developing bio-based coatings derived from renewable resources. These products cater to environmentally conscious consumers and comply with global sustainability goals.
- Growth in UV-cured coatings: UV-cured coatings are gaining traction due to their quick drying times and superior finish, offering cost-effective solutions for industrial applications.
- Customization: Consumers’ demand for unique and personalized finishes has spurred the development of customized color palettes, matte finishes, and textured coatings.
- Expanding applications in construction: Beyond furniture, wood coatings are finding increased use in architectural applications such as wood paneling and decking, driven by growing infrastructural projects worldwide.

January 20, 2025
Another Gulf Coast Freeze This Week
Extreme Cold, Snow Places Texas Power Grid & Permian On Alert
by Tyler Durden
Monday, Jan 20, 2025 – 03:00 PM
Texas’ top electricity regulator issued a “Weather Watch” from Monday morning through Thursday, citing “extreme cold weather” and the potential for snow, which could send electrical demand soaring across the state.
According to the National Weather Service, snow is forecasted to begin in Houston on Monday evening and accumulate to upwards of 4 inches by Tuesday. After the snow, frigid temperatures are expected to sweep in, bringing dangerously cold conditions that could jeopardize the power grid and energy infrastructure.
“Weather Watch goes into effect today through January 23 due to forecasted extreme cold weather across the ERCOT region, higher electrical demand, and the potential for lower reserves,” the Electric Reliability Council of Texas wrote on X, adding, “Winter precipitation is also expected across parts of the state. Grid conditions are expected to be normal.”
Tony Fracasso, a senior branch forecaster at the US Weather Prediction Center, said, “It’s a significant storm for so far south.”
“It looks like almost the entirety of Texas has some chance of wintery precipitation,” Fracasso noted.
The early alert issued by ERCOT implies that extreme cold could pressure the power grid. ERCOT stated that peak electricity demand is expected to rise over the next two days, reaching about 77.2 gigawatts. Even though ERCOT predicts high demand, it anticipates having sufficient supply to meet demand.
“As freezing temps blanket Texas, the power grid is performing better than ever,” Governor Greg Abbott wrote on X Sunday evening, adding, “There is ample supply of power available to meet your needs.”
Besides potential grid strains, frigid temperatures could curtail natural gas supplies due to the freezing of oil and gas wells and pipes, known as “freeze-offs” by energy analysts.
On Tuesday, West Texas temperatures will average around 29F. Through Saturday, average temperatures in the oil-rich Permian basin will remain below the 30-year average of 47F for this time of year. This cold could disrupt oil and gas output by freezing water in wells and pipelines.

Ahead of the snow, Houston Airports announced that flights at George Bush Intercontinental Airport, William P. Hobby Airport, and Ellington Airport will be suspended on Tuesday morning.
The storm is expected to blanket snow across the Gulf Coast and Deep South coastal areas.
Meteorologist Tony Pann questioned if this wintery weather for the Gulf Coast was a “once-in-a-lifetime event“…
Here’s our latest reporting on the polar vortex and energy markets:
- Goldman: “Cold January” & “Record LNG Demand” Drive Upside Risk In Natty Prices
- Incoming: “Big Dumps Of Cold Air. Reminiscent Of 2013/14 Winter”
- Doesn’t Fit MSM Narrative: Parts Of US Could Rival Coldest January Since 1977
- Polar Vortex, Back-To-Back-To-Back Winter Storms Target Eastern Half Of US
Where did global warming go? Please come back.
https://www.zerohedge.com/weather/extreme-cold-snow-places-texas-power-grid-permian-alert
 Everchem Updates Archive
 Sign Up for Email Updates

