
Current Affairs
June 1, 2022
Memorial Day Mattress Update
Slowing sales for mattress retailers ‘on par with Great Recession’ – Wedbush
Jun. 01, 2022 3:25 PM ETPurple Innovation, Inc. (PRPL), SNBR, TPXBy: Kevin P. Curran, SA News Editor7 Comments
Lagging sales for mattress retailers over the Memorial Day holiday point to a rough rest of the year, according to Wedbush analyst Seth Basham.
In a research note authored on Wednesday, the analyst reported that recent sales checks came back negative while demand generally continues to wane. Basham added that advertisement and promotional activity did not pay off as many of the retailers had hoped.
“Our analysis found incremental promotional intensity with outsized discounting on the low-end and in the Direct-to-Consumer Bed-In-Box (BiB) channel while Tempur-Pedic (TPX-O) increased its promotional intensity on lower-end mattress and base bundles,” he wrote in a research note on Wednesday. “As sales trends for this key period often set the tone for the entire summer season, the soft performance over the Memorial Weekend suggests continued sharp [mid-single digit to high-single digit] unit declines through the summer in the absence of incremental discounting to spur demand—this level of unit decline is on par with the Great Recession.”
On top of that bearish comparison, Basham noted that increased commodity costs and supply chain problems present only added issues for these retail chains as they are likely forced into further promotional activity and price cuts due to waning demand. In particular, his team expects increased clearance-type sales around the July 4 and Labor Day holidays.
“In sum, it appears to be too early for a turn in fundamentals or mattress industry stocks,” he concluded.
May 31, 2022
Lockdown Lifted
Shanghai Is Finally Lifting Its COVID Lockdown
by Tyler DurdenTuesday, May 31, 2022 – 06:00 PM
After another two months of misery and lockdowns, Shanghai is finally starting to lift its Covid restrictions (again).
Authorities in the Chinese city have started “dismantling fences around housing compounds and ripping police tape off public squares and buildings”, according to a report published on Tuesday by Reuters.
On Monday night, residents were being allowed out of their compounds for the first time in two months, the report says. Despite the lockdowns starting to come to an end, “there was a sense of wariness and anxiety among residents,” Reuters reported.
Joseph Mak, who works in education, commented: “I feel a little nervous. It’s hard to believe it’s actually happening.”
Not only has the recent bout of lockdowns triggered public protests and anger in the city of more than 25 million people, it also threw another sizeable wrench into the global supply chain at a time when the world could least afford it.
Shanghai government spokeswoman Yin Xin told reporters this week: “This is a day that we dreamed of for a very long time. Everyone has sacrificed a lot. This day has been hard-won, and we need to cherish and protect it, and welcome back the Shanghai we are familiar with and missed.”
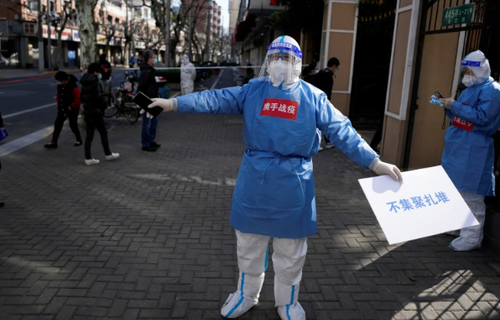
Despite the lockdowns being lifted, residents will still have to test every 72 hours to take public transportation and those who test positive will still be subjected to China’s “normal” quarantine procedures.
Shanghai brought COVID under control at “very significant personal and economic cost”, commented Julian MacCormac, chair of the British Chamber in China. He continued: “What has materially changed to ensure that this will not happen again? That’s where the uncertainty lies.”
Todd Pearson, managing director of Camel Hospitality Group added: “I’m hopeful that they will rush things along to restart the economy. I just hope it’s not at the cost of more outbreaks. I’m not sure many businesses or the people could handle much more.”
Qu Weiguo, a professor at the Fudan University school of foreign languages even wrote online: “The Shanghai government needs to make a public apology in order to obtain the understanding and support of the people of Shanghai and repair the damaged relationship between the government and the people.”
https://www.zerohedge.com/markets/shanghai-finally-lifting-its-covid-lockdown
May 31, 2022
Lockdown Lifted
Shanghai Is Finally Lifting Its COVID Lockdown
by Tyler DurdenTuesday, May 31, 2022 – 06:00 PM
After another two months of misery and lockdowns, Shanghai is finally starting to lift its Covid restrictions (again).
Authorities in the Chinese city have started “dismantling fences around housing compounds and ripping police tape off public squares and buildings”, according to a report published on Tuesday by Reuters.
On Monday night, residents were being allowed out of their compounds for the first time in two months, the report says. Despite the lockdowns starting to come to an end, “there was a sense of wariness and anxiety among residents,” Reuters reported.
Joseph Mak, who works in education, commented: “I feel a little nervous. It’s hard to believe it’s actually happening.”
Not only has the recent bout of lockdowns triggered public protests and anger in the city of more than 25 million people, it also threw another sizeable wrench into the global supply chain at a time when the world could least afford it.
Shanghai government spokeswoman Yin Xin told reporters this week: “This is a day that we dreamed of for a very long time. Everyone has sacrificed a lot. This day has been hard-won, and we need to cherish and protect it, and welcome back the Shanghai we are familiar with and missed.”
Despite the lockdowns being lifted, residents will still have to test every 72 hours to take public transportation and those who test positive will still be subjected to China’s “normal” quarantine procedures.
Shanghai brought COVID under control at “very significant personal and economic cost”, commented Julian MacCormac, chair of the British Chamber in China. He continued: “What has materially changed to ensure that this will not happen again? That’s where the uncertainty lies.”
Todd Pearson, managing director of Camel Hospitality Group added: “I’m hopeful that they will rush things along to restart the economy. I just hope it’s not at the cost of more outbreaks. I’m not sure many businesses or the people could handle much more.”
Qu Weiguo, a professor at the Fudan University school of foreign languages even wrote online: “The Shanghai government needs to make a public apology in order to obtain the understanding and support of the people of Shanghai and repair the damaged relationship between the government and the people.”
https://www.zerohedge.com/markets/shanghai-finally-lifting-its-covid-lockdown
May 23, 2022
More on Inventories
Bloated inventories hit Walmart, Target and other retailers’ profits, trucking demand
Too much stock means lower truckload volumes, more intermodal business
Mark SolomonFriday, May 20, 2022 4 minutes read

Listen to this article 0:00 / 6:18 BeyondWords
There’s little in retailing that Walmart Inc. and Target Corp. aren’t prepared to handle. So it was jarring that over a 24-hour period the two scions of the trade posted weak first-quarter profits that appeared to blindside their management teams.
Part of the bottom-line blowup was due to fuel, which soared to record highs following Russia’s Feb. 24 invasion of Ukraine. Part of it was due to margin pressures caused by an unfavorable sales mix as consumers shifted their buying from higher-margin goods like electronics to less profitable items like groceries. An extension of that was an overshoot of inventory-stocking activity, which came back to bite the retailers after waning concerns over the COVID-19 pandemic pushed more consumer buying toward services and “experiences” and away from goods.
There’s little that retailers can do about fuel prices. It can be argued they should have expected the pandemic-driven buying spree from March 2020 until the end of 2021 to peter out and that they should have planned their inventory strategies accordingly. Yet demand forecasting has always been a tough nut to crack, and the market is where it is. Inventory build may also have been the result of supply chain delays at the start of the year that resulted in some late deliveries of impaired freight.
Inventory levels as of March, when compared to activity in March 2019 after inventories stabilized following a major pull-forward in 2018 ahead of the Trump administration’s China tariffs, produce a mixed bag of results. Unsurprisingly given the current dearth of motor vehicles, the ratio of vehicle and parts inventories to sales has fallen considerably, according to federal government data analyzed by Michigan State University. Apparel inventories to sales also declined over those periods, as did e-commerce.
However, furniture, home furnishings and appliances, building materials and garden equipment, and a category known as “other general merchandise,” which includes Walmart and Target, among others, reported higher inventory-to-sales ratios, according to government data analyzed by Michigan State.

For the latter sectors, the change has happened fast, according to Jason Miller, logistics professor at MSU’s Eli Broad College of Business. As of November, inventory-to-sales ratios were at pre-COVID levels, Miller said. They have since exploded upward.
Miller said he expects a “cooldown” in retailer order volumes, even if inflation-adjusted sales stay constant, as retailers look to reduce their existing stock. He also expects retailers to launch major discounting programs to expedite the inventory burn. Fewer orders within certain categories bodes ill for carriers whose networks are strongly tied to inbound lanes to retailers’ distribution centers, Miller said.
In a Friday note, Bascome Majors, analyst for Susquehanna Investment Group, said that the spread between year-over-year sales and inventories — a rough barometer of the impact of higher sales on restocking activity — turned positive in spring 2020 and accelerated in favorable territory for four consecutive quarters. Gradually, however, the spread has turned negative, according to Majors. In this year’s first quarter, inventory growth exceeded sales growth by 200 basis points. The recent surge in inflation, Majors wrote, has severely distorted inventory and sales trends.
Freight recession priced in?
For some, high inventory levels are an expected occurrence and should be welcomed. In a Tuesday note, Amit Mehrotra, transport analyst at Deutsche Bank, said rising buffer stock is part of retailers’ desire to have goods available when consumers scan the shelves. Mehrotra added, however, that the data points translate into a likely slowdown in freight flows in the coming months and quarters.
He said that a recession is already priced into most transportation equities, noting that the shares of most trucking companies are higher over the past 30 days while the broader market is about 7% lower.
In an unusual world, Walmart, Target and other retailers are likely to turn to the one area where they’ve traditionally found leverage: their shipping bill. During the quarter, Target (NYSE: TGT) faced freight and transportation costs that were hundreds of millions of dollars above already-elevated expectations, COO John Mulligan said on the company’s Wednesday analyst call. It was essentially the same story at Walmart (NYSE: WMT).
Retailers’ efforts to rein in transportation costs will translate into an unprecedented third and even fourth round of truckload contract negotiations, with users getting more aggressive in their bids to extract greater cost savings, according to industry experts.
The discussions could get contentious. In a LinkedIn post on Friday, Jason Ickert, president of trucking firm Sonwil Logistics, said a large shipper that Ickert wouldn’t identify suggested on a conference call this week with truckload carriers that they were “artificially propping up their rates” above accepted market levels. The shipper “stated clearly” that the carriers were expected to adjust their rates during what would be an “unprecedented and unplanned” third round of request for proposals, Ickert wrote.
A potential shift to intermodal
Pressures to drive down transport expenses will also trigger increased interest in intermodal, whose all-in costs are cheaper relative to contract truckload than at any time since 2018. Intermodal rates have risen at a slower pace than truckload contract rates, a turnabout from the 2019 freight recession when higher intermodal rates allowed over-the-road transport to gain market share.

The shift to intermodal, if it happens, would benefit the railroads and intermodal marketers like J.B. Hunt Transport Services Inc. (NASDAQ: JBHT), Hub Group Inc. (NASDAQ: HUBG) and Schneider Inc. (NASDAQ: SNDR). However, experts caution that intermodal capacity remains constrained, as does warehouse space needed to store the stuff.
“Walmart, Target and other retailers will soak up every drop of intermodal capacity that Hunt, Hub, Schneider and the rails deliver in 2022 and probably in 2023,” said Majors of Susquehanna Investment Group. The elevated level of activity, he said, should occur even if retailers are working through a multiquarter process of de-stocking.
May 23, 2022
More on Inventories
Bloated inventories hit Walmart, Target and other retailers’ profits, trucking demand
Too much stock means lower truckload volumes, more intermodal business
Mark SolomonFriday, May 20, 2022 4 minutes read
Listen to this article 0:00 / 6:18 BeyondWords
There’s little in retailing that Walmart Inc. and Target Corp. aren’t prepared to handle. So it was jarring that over a 24-hour period the two scions of the trade posted weak first-quarter profits that appeared to blindside their management teams.
Part of the bottom-line blowup was due to fuel, which soared to record highs following Russia’s Feb. 24 invasion of Ukraine. Part of it was due to margin pressures caused by an unfavorable sales mix as consumers shifted their buying from higher-margin goods like electronics to less profitable items like groceries. An extension of that was an overshoot of inventory-stocking activity, which came back to bite the retailers after waning concerns over the COVID-19 pandemic pushed more consumer buying toward services and “experiences” and away from goods.
There’s little that retailers can do about fuel prices. It can be argued they should have expected the pandemic-driven buying spree from March 2020 until the end of 2021 to peter out and that they should have planned their inventory strategies accordingly. Yet demand forecasting has always been a tough nut to crack, and the market is where it is. Inventory build may also have been the result of supply chain delays at the start of the year that resulted in some late deliveries of impaired freight.
Inventory levels as of March, when compared to activity in March 2019 after inventories stabilized following a major pull-forward in 2018 ahead of the Trump administration’s China tariffs, produce a mixed bag of results. Unsurprisingly given the current dearth of motor vehicles, the ratio of vehicle and parts inventories to sales has fallen considerably, according to federal government data analyzed by Michigan State University. Apparel inventories to sales also declined over those periods, as did e-commerce.
However, furniture, home furnishings and appliances, building materials and garden equipment, and a category known as “other general merchandise,” which includes Walmart and Target, among others, reported higher inventory-to-sales ratios, according to government data analyzed by Michigan State.
For the latter sectors, the change has happened fast, according to Jason Miller, logistics professor at MSU’s Eli Broad College of Business. As of November, inventory-to-sales ratios were at pre-COVID levels, Miller said. They have since exploded upward.
Miller said he expects a “cooldown” in retailer order volumes, even if inflation-adjusted sales stay constant, as retailers look to reduce their existing stock. He also expects retailers to launch major discounting programs to expedite the inventory burn. Fewer orders within certain categories bodes ill for carriers whose networks are strongly tied to inbound lanes to retailers’ distribution centers, Miller said.
In a Friday note, Bascome Majors, analyst for Susquehanna Investment Group, said that the spread between year-over-year sales and inventories — a rough barometer of the impact of higher sales on restocking activity — turned positive in spring 2020 and accelerated in favorable territory for four consecutive quarters. Gradually, however, the spread has turned negative, according to Majors. In this year’s first quarter, inventory growth exceeded sales growth by 200 basis points. The recent surge in inflation, Majors wrote, has severely distorted inventory and sales trends.
Freight recession priced in?
For some, high inventory levels are an expected occurrence and should be welcomed. In a Tuesday note, Amit Mehrotra, transport analyst at Deutsche Bank, said rising buffer stock is part of retailers’ desire to have goods available when consumers scan the shelves. Mehrotra added, however, that the data points translate into a likely slowdown in freight flows in the coming months and quarters.
He said that a recession is already priced into most transportation equities, noting that the shares of most trucking companies are higher over the past 30 days while the broader market is about 7% lower.
In an unusual world, Walmart, Target and other retailers are likely to turn to the one area where they’ve traditionally found leverage: their shipping bill. During the quarter, Target (NYSE: TGT) faced freight and transportation costs that were hundreds of millions of dollars above already-elevated expectations, COO John Mulligan said on the company’s Wednesday analyst call. It was essentially the same story at Walmart (NYSE: WMT).
Retailers’ efforts to rein in transportation costs will translate into an unprecedented third and even fourth round of truckload contract negotiations, with users getting more aggressive in their bids to extract greater cost savings, according to industry experts.
The discussions could get contentious. In a LinkedIn post on Friday, Jason Ickert, president of trucking firm Sonwil Logistics, said a large shipper that Ickert wouldn’t identify suggested on a conference call this week with truckload carriers that they were “artificially propping up their rates” above accepted market levels. The shipper “stated clearly” that the carriers were expected to adjust their rates during what would be an “unprecedented and unplanned” third round of request for proposals, Ickert wrote.
A potential shift to intermodal
Pressures to drive down transport expenses will also trigger increased interest in intermodal, whose all-in costs are cheaper relative to contract truckload than at any time since 2018. Intermodal rates have risen at a slower pace than truckload contract rates, a turnabout from the 2019 freight recession when higher intermodal rates allowed over-the-road transport to gain market share.
The shift to intermodal, if it happens, would benefit the railroads and intermodal marketers like J.B. Hunt Transport Services Inc. (NASDAQ: JBHT), Hub Group Inc. (NASDAQ: HUBG) and Schneider Inc. (NASDAQ: SNDR). However, experts caution that intermodal capacity remains constrained, as does warehouse space needed to store the stuff.
“Walmart, Target and other retailers will soak up every drop of intermodal capacity that Hunt, Hub, Schneider and the rails deliver in 2022 and probably in 2023,” said Majors of Susquehanna Investment Group. The elevated level of activity, he said, should occur even if retailers are working through a multiquarter process of de-stocking.
 Everchem Updates Archive
 Sign Up for Email Updates
