
The Urethane Blog
November 13, 2023
Sinochem International 400kT PO Facility Set to Produce Qualified Products in December
PUdaily | Updated: November 8, 2023
Since 2022, Sinochem International has successively completed and put into operation major facilities such as phenol acetone, bisphenol A, epoxy chloropropane, and epoxy resin as part of its first-phase C3 project. The 600 ktpa propane dehydrogenation (PDH) facility was recently commissioned for trial production, marking the complete integration of the entire epoxy resin industry chain at Sinochem International’s site in Lianyungang.
Over the years, Sinochem International has undergone a strategic transformation, evolving from a trading-oriented company into an internationally operated conglomerate primarily focused on fine chemical production. Through investments and acquisitions, the company has acquired a significant number of high-quality assets, including majority stakes in companies like Sennics, Yangnong Chemical, Elix Polymers, among others, laying a strong foundation for a successful industrial transformation. The company’s business encompasses chemical intermediates, polymer additives, new materials, new energy, and other traditional sectors, with complementary advantages between industries. Leveraging a green and circular economy industrial chain, Sinochem International has achieved continuous product diversification and efficient resource utilization, establishing a core competitive edge. The products offered include chlorobenzene series, nitrochlorobenzene series, widely used in industries such as pharmaceuticals, agrochemicals, and dyes. In the field of new materials, the company deals with high-performance fiber materials like aramid and high-strength polyethylene, as well as materials like epoxy chloropropane and epoxy resin used in industries such as coatings and electronics. They also handle lightweight materials such as PU, PC, PS, ABS, and others.
It’s worth mentioning that Sinochem International’s C3 project, with a production capacity of 400 ktpa of propylene oxide (PO), is expected to start commissioning on November 8 and is projected to produce qualified products in early December.
In the context of increasingly stringent environmental regulations, traditional chlorohydrin processes, which have not effectively addressed the “three wastes” issue, are gradually being phased out. In the draft of China’s 2023 Catalogue for Guiding Industry Restructuring, issued by National Development and Reform Commission on July 14, 2023, the calcium saponification chlorohydrin process should be eliminated by December 31, 2025. Following the elimination of a 50 ktpa chlorohydrin-based facility in Shandong, in recent years, chlorohydrin-based PO facilities, such as those in Jinpu, Tianjin, and Fujian, have successively ceased operations. As a result, the proportion of chlorohydrin processes has decreased from 55.9% in 2018 to 27.1% in 2022.
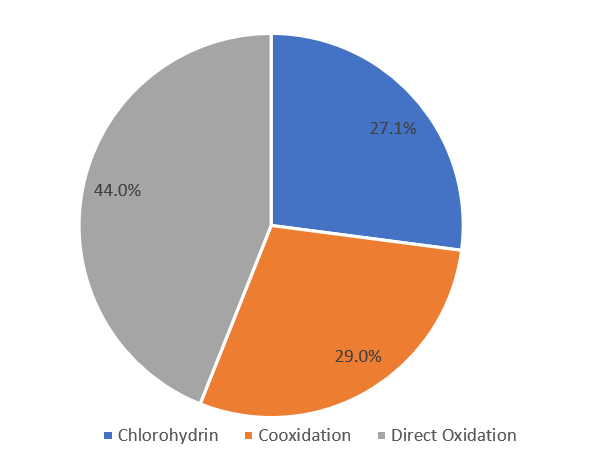
Currently, new PO facilities primarily use direct oxidation (HPPO) and cooxidation (PO/SM, PO/TBA) processes.
Sinochem International is expanding its capacity by 400 ktpa using the direct oxidation process for PO production, and its scale and technology are at the forefront domestically. The C3 project includes a 400 ktpa HPPO facility with supporting facilities, in line with national environmental protection policies. As an environmentally encouraged process, the direct oxidation process can overcome the drawbacks of severe equipment corrosion and high waste generation associated with chlorohydrin processes. This method features a simple process, high product yield, and only generates PO and water during production. Raw materials and auxiliary agents can be recycled, resulting in lower raw material and energy consumption and a significant reduction in production costs. It is also environmentally friendly and non-polluting. Furthermore, the direct oxidation process is expensive and challenging to acquire, with a high entry barrier. Once the facility is operational, Sinochem International will hold a leading position in terms of production capacity and technology in the domestic market.
Dimethyl carbonate (DMC) is a co-product produced by ester exchange in the production of propylene glycol. Thanks to green chemistry, new energy promotion, and sustainable development, DMC has gained attention due to its low toxicity and excellent environmental performance. It finds wide applications in various industrial fields. Apart from its traditional uses in adhesives, coatings, developers, and polycarbonates, DMC has seen significant growth in the downstream applications of lithium-ion battery electrolyte solvents, which now account for 30% of its usage. High purity is crucial for these applications, with industrial-grade DMC primarily used in traditional downstream applications and polycarbonates (PC), while battery-grade DMC requires higher purity. Currently, suppliers of battery-grade DMC include Shida Shenghua (75 ktpa), Oxiranchem (20 ktpa), etc. New entrants in this market include Capchem, Sinochem Quanzhou, Zhejiang Petrochemical, and Hualu Hengsheng. In the next 3-5 years, the newly established production capacity for carbonates in China is expected to exceed 4 mtpa, contributing to the increased demand for PO.
November 13, 2023
Persistently weak demand impacts third quarter
- Sales down 26.7 percent to EUR 1.601 billion in the third quarter of 2023
- EBITDA pre exceptionals down 50.4 percent year-on-year at EUR 119 million
- Further significant reduction of net financial liabilities to EUR 2.557 billion
- Guidance for fiscal year 2023: EBITDA pre exceptionals expected to be between EUR 500 and 550 million
- Board of Management plans dividend reduction to EUR 0.10
- Sale of Urethane Systems business unit initiated
- “FORWARD!” action plan: structural measures to permanently reduce costs by EUR 150 million
CologneNovember 08, 2023
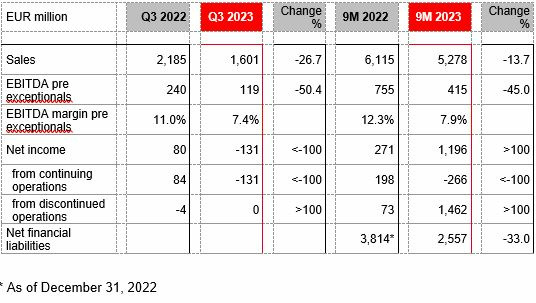
In the third quarter of 2023, LANXESS’ business figures were again influenced by the persistently weak economy. Sales amounted to EUR 1.601 billion, down 26.7 percent on the previous year’s figure of EUR 2.185 million. EBITDA pre exceptionals fell by 50.4 percent from EUR 240 million to EUR 119 million.
The main reasons for this development were the low demand from nearly all industries and customers’ ongoing albeit diminishing inventory reduction. The associated reduction in sales volumes and high idle costs led to declining earnings, especially in the Specialty Additives and Advanced Intermediates segments. The Consumer Protection segment saw only a comparatively moderate earnings decline.
The Group’s EBITDA margin pre exceptionals was 7.4 percent, against 11.0 percent in the prior-year quarter. Net income declined to minus EUR 131 million in the third quarter compared with EUR 80 million in the prior-year quarter.
“The weak demand in the global chemicals industry persists, and we see no signs of recovery for the rest of the year. On the contrary, demand in the fourth quarter to date seems to be even weaker than expected,” said Matthias Zachert, Chairman of the Board of Management at LANXESS AG.
LANXESS had already announced the unexpectedly weak start to the fourth quarter on November 6. Initiated destocking of customers in the agroindustry and a supplier-related production limitation for the Business Unit Flavors & Fragrances at its production site in Botlek (NL) impact results additionally. LANXESS therefore expects EBITDA pre exceptionals for the full year 2023 to be between EUR 500 and 550 million. LANXESS’ previous guidance was EUR 600 to 650 million for EBITDA pre exceptionals for the total year.
Dividend cut and sale of Urethane Systems
Given the weak business development, the Board of Management intends to propose a reduction of the full year 2023 dividend to EUR 0.10. The hereby avoided cash outflow would result in a further reduction of net financial debt. Expected proceeds from the now initiated sale of the Business Unit Urethane Systems would contribute as well.
As the last remaining polymer business at LANXESS, the business unit no longer fits in with the strategic orientation of the Group, which has systematically realigned its portfolio in recent years. The business unit has a global presence with six production sites and employs around 400 staff.
https://lanxess.com/en/Media/Press-Releases/2023/11/Persistently-weak-demand-impacts-third-quarter
November 6, 2023
Tempur Sealy International, Inc. (TPX) Q3 2023 Earnings Call Transcript
Nov. 02, 2023 11:17 AM ETTempur Sealy International, Inc. (TPX)1 Comment
141.65K Followers
Q3: 2023-11-02 Earnings Summary
EPS of $0.66 misses by $0.17 | Revenue of $1.28B (-0.48% Y/Y) misses by $25.12M
Tempur Sealy International, Inc. (NYSE:TPX) Q3 2023 Earnings Conference Call November 2, 2023 8:00 AM ET
Company Participants
Aubrey Moore – VP, IR
Scott L. Thompson – Chairman, CEO & President
Bhaskar Rao – EVP & CFO
Scott L. Thompson
Thanks Aubrey. Good morning everyone and thank you for joining us on our 2023 third quarter earnings call. I will start by sharing some highlights for my third quarter performance and then Bhaskar will review our financial performance in more detail. After that I will provide an update on a proposed acquisition of Mattress Firm before opening up the call for Q&A. Today we are reporting the third best third quarter sales and ETF in the company’s history. For the third quarter of 2023, we reported net sales of approximately 1.3 billion and adjusted EPS of $0.77. Our results are approximately consistent with the third quarter of last year despite a more challenging macroeconomic operating background.
The U.S. betting industry as a whole underperformed our expectations with estimated volume down low double-digits in the quarter. We mitigated the impact of the softer than expected U.S. market with solid company performance that exceeded our expectations on both a relative market performance and year-over-year gross margin expansion. Internationally, the betting industry and our operations performed in line with our expectations. Overall, despite down markets and the disruption of a major cyber security incident in the third quarter, our strong relative performance and cash flow generation demonstrate strong — strength of our brands, operations, and team. We believe Tempur Sealy is well positioned for continued success.
Turning to highlights for the quarter. First, our industry leading brands and products continue to resonate with the U.S. consumer, driving our strong performance relative to the broader market. All of our new Tempur products and supporting advertising initiatives has strengthened Tempur’s appeal to the premium, relative minded consumer. The incremental cooling and comfort innovation of our new lineup of breeze mattresses generate robust retail advocacy and favorable mix in the quarter compared to the prior year. The lumbar feature acoustic massage, the wake up and wind down technologies, and our new smart based lineup continue to strengthen the value proposition of our adjustable offering driving an improvement in detachment rates year-over-year. These innovations drove a 5% increase in Tempur Mattress and Foundation ASP in the third quarter. Looking ahead to 2024, we expect to complete the full refresh of our U.S. Tempur portfolio by introducing our next generation of adapter products. We expect strong returns on investment and our new products for years to come.
Over the quarter we continued to support our new Tempur products and along from health of our Tempur brands with continued investments in national and digital Tempur-Pedic advertising. These marketing investments support very solid e-commerce performance and drove an increase in US Tempur search interest year-over-year. Our strategic investment and product distribution and marketing also continue to drive strong performance and expand brand awareness of Stearns & Foster in the U.S. market. We completed the roll out of our all new Stearns & Foster mattress collection earlier this year. We continue to see these new products connecting with the premium traditional inner spring consumer driving sales growth year-over-year. The consumer centric innovation, elevated design, and pants step up opportunities are resonating with premium inner spring customer. We are thrilled that our high end products are performing well and the ASP of Stearns & Foster product is up double-digit from last year. Additionally, Stearns & Foster’s search interest and e-commerce traffic were up 50% this year. Clearly our multiyear strategy for Stearns & Foster is working well for us and our retailers.
Second highlight, our international operation is performing well and driving solid sales growth amid the current macro backdrop. We successfully launched our new international Tempur lineup in over 90 markets worldwide including the rollout in nearly all the key markets in Europe and Asia. The launch is on track and will be substantially completed before the end of the year. The new products are being well received. Additionally, Dreams our UK retail operation is also performing well in both sales outperforming versus the broader market and has a record customer satisfaction. This quarter performance demonstrates the strength of our international strategy and pain [ph], highlighting the long-term opportunity for the international operations.
Third, we choose significant consolidated growth margin expansion year-over-year, and are progressing towards normalized margins. After multiple years of COVID overhang, rapid inflation, macroeconomic disruption, pressured margins for a while, we are pleased to report 340 basis point improvement to consolidated adjusted gross margin year-over-year thanks to the successful management of commodity fluctuations, improved supplier contracts, and operational improvements. This is a significant step towards driving profitability, which the team remains laser focus on achieving. The growth driver of our gross margin improvement is our ability to pass on pricing to offset commodity inflation. As you may recall we experienced approximately 400 basis points of margin compression between 2020 and 2022. This commodity price has increased at a historical pace. Now that pricing changes have been implemented, the commodity prices have started to normalize. You can see the positive results in our reported financial statements. Additionally, we’re optimistic that our scale in the market and our new product innovations would drive further gross margin expansion.
Bhaskar Rao
Thank you, Scott. In the third quarter of 2023, consolidated sales were approximately $1.3 billion and adjusted earnings per share was $0.77. While these results were slightly below our expectations, we believe we continue to outperform our competitive set in a challenging market. We have approximately $32 million of Pro Forma adjustments in the quarter, all of which are consistent with the terms of our senior credit facility. These adjustments are primarily related to cost incurred in connection with the planned acquisition of Mattress Firm and the previously disclosed cyber event.
Turning to North American results. Net sales declined 3% in the third quarter. On a reported basis the wholesale channel declined 4% and the direct channel declined 1%. North American adjusted gross margin improved a very robust 300 basis points to 43.2% driven by favorable commodities and operational efficiencies partially offset by deleverage. North American adjusted operating margin improved 50 bps to 20.3% driven by improvement in gross margins partially offset by investments in growth initiatives.
Now turning to international. International net sales increased a very solid 12% on a reported basis and 7% on a constant currency basis. As compared to the prior year, our international gross margin improved a robust 320 basis points to 56.6% driven by commodities, mix, and favorable leverage. Our international adjusted operating margin improved a 150 basis points to 16.2% driven by improvements in gross margin partially offset by investments. Global commodity prices continued to brand largely in line with our expectations. We continue to expect favorable commodity prices for the remainder of the year, though remaining significantly elevated from 2020 levels. In addition to the benefit of favorable commodity markets we assigned multiple agreements with certain global suppliers who have recognized our scale momentum. These relationships will benefit our gross margins over the long-term
Scott L. Thompson
Thanks. Nice job, Bhaskar. Before opening up the call for questions let me provide a brief update on our pending acquisition of Mattress Firm. Consistent with our expectations we’re currently responding to the Federal Trade Commission’s robust second request, which we expect to complete in the fourth quarter of 2023. We continue to expect the transactions to close in mid to late 2024. We continue to work closely with Mattress Firm’s leadership team. We received high level updates on numerous topics, including their financial performance. Mattress Firm has an October 3 fiscal year end and will report their physical results when their audit is complete, most likely in early December. The preliminary results are in line with our expectations.
Finally, I’m pleased to share that Tempur Sealy and Mattress Firm continue to make joint progress in planning for post-closing, including solidifying key supplier relations ahead of the expected close. Since announcing the acquisition in May Tempur Sealy has signed numerous post-closing supply agreements with existing Mattress Firm suppliers and one supply agreement for the company not currently supplying Mattress Firm. These contracts are consistent with our expectation for Mattress Firm to continue as a multi branded retailer post-closing. A few additional discussions regarding supplier relations are ongoing.
In summary, our progress towards the transaction close is on track and we look forward to joining with the Mattress Firm team. And with that, I’ll open up the call for questions. Operator.
Susan Maklari
Thank you. Good morning, everyone. Scott, why don’t we start by talking a bit about the demand environment. I think that, obviously things felt a little softer in the quarter than maybe some had anticipated and appreciating the color you gave in your comments. But, can you talk a bit more about how things trended during the quarter, any sort of anything of note in there, and how you’re thinking about the business as we progress through the balance of this year?
Scott L. Thompson
Sure. Thanks for your question, Susan. I mean, first of all, let’s not overlook that the international team had good solid growth in the quarter. And I think your question is really more directed towards North America. And then to kind of streamline your question even further, our Mexico operations had a great quarter and Canada was solid. So kind of ratcheted down our largest market, which is where your question is really focused is the U.S. market. As far as how that quarter progressed, the same trends that I think we talked about probably in the second quarter we saw in the third quarter, which is in non-holiday periods, the troughs had gotten deeper and then during holiday periods, we’re seeing growth in the market. But the holiday periods haven’t been strong enough to offset the trough. So that would be we’ll call that in quarter kind of trend. That’s the same trend that we would expect in the fourth quarter. It continues to be what I’d call the normalization of the seasonality that the business used to incur before COVID with maybe slightly deeper troughs, and slightly higher peaks during the holiday period.
I think you also kind of asked in general, just like demand. I mean, I think as you well know, the industry has been — from a unit standpoint has been in decline for nine quarters, making it where we currently are sitting at great recession kind of volumes in the industry that we’re working through and ensure some of that has to do with slowdown in the general economy. And we’re talking U.S. here and wallet shift. There’s probably some minor pullback, a pull forward from COVID. Although we’ve never really thought that that was a big number. I think the biggest thing that the industry is working through is really advertising. And, as you know, we’ve got a lot of smart people, a lot of analytics that go on to look at advertising both ours and the effectiveness of it, what goes on in the industry. And in looking at it as we tried to understand why the industry is having such a tough slug compared to historical volumes that were offered trend lines.
If you look at it manufacturer advertising over the last three years is down 40%. And if you look at the retailer’s, their advertising is down 20%. And yeah, that’s an issue. But I think probably a bigger issue is when you dive into that reduced advertising and you look at the mix of what people are doing both from a manufacturing standpoint and a retailer standpoint. They’ve moved from top of funnel advertising over the last three years to the bottom of the funnel. The manufacturers have moved about 40% of their advertising from the top of the funnel to the bottom. And retailers have also moved probably 40% to 40% plus of their advertising from the top of the funnel to the bottom of the funnel.
So what’s that mean? That means we’re not putting enough customers in the funnel triggering, they’re thinking about mattresses, and we’re all kind of fighting for the few customers that happen to trip into the funnel is what’s going on in the industry. If you play with the math, that means total top funnel advertising for manufacturers is down 64% when you include the decline in advertising plus the mix change. And for retailers, it’s down 44%. That is an enormous amount of advertising dollars taken off the top of the funnel. And I think that’s the big problem in traffic. I think that’s actually the bigger issue than share of wallet and other things that people like to talk about.
Now from our standpoint, we continue to support the industry as a manufacturer and in our advertising expense we have not cut. So with us not cutting, you can see the other ad manufacturers are clearly not helping pull the funnel forward. We have moved some to the bottom of the funnel and we’re looking at that. And what we’re doing to help kind of get the industry back on track is we’re working with other retailers and major retailers, walking them through some of this analysis, talking to them about it. And it’s resonating with them. And some of the large retailers are really looking at their advertising mix in dollar amount.
Jason Haas
Hey, good morning, and thanks for taking my question. Scott, in light of your comments to a previous question, I’m curious if you could say what you think is needed for the industry to get back to more normalized unit levels, do you think we need to see a pickup in industry advertising, do we need to see more housing turnover, is it just going to take time, what do you think is key to get there?
Scott L. Thompson
Yeah, I think we all fell in love with low funnel advertising. And some others pulled back on their advertising hoping to draft on other people. I think the bedding is an industry that you have to trigger the customer to think about. People don’t wake up one day and say let’s go buy a bunch of beds and the industry is very successful when it advertises. And so I think it’s primarily a lack of advertising by people and probably a little bit of a mixed fine tuning. I think I would also point to if you look at what Tempur Sealy has done, I mean, look, it’s not any secret. We’ve gathered a lot of market share and you can see that in our Stearns & Foster product where we’ve done higher than historical advertising dollars in there. So we’ve proven that advertising works. Yeah, the product is great, sales team is great but you got to have the advertising in there. And so yeah, I think advertising is the key. You’ll hear retailers talk about traffic and that is the issue and everybody needs to get back to working a little bit on the top funnel and getting people in the funnel rather than waiting till the last minute grab them off their purchase journey at the end. Things like manufacturers slot mind are doing spiffs those kinds of dollar investments are all just fighting over the customers in the marketplace and aren’t productive. And they really aren’t something that Tempur Sealy is done. We’ve had some other manufacturers try to work that angle.
Brad Thomas
Hey, thanks, good morning. Scott, was hoping I could get a little bit of your kind of first blush on how you’re thinking about the industry as you look out to 2024. Obviously, some of the leading indicators of the health of the consumer like ramping student loan payments could be a headwind, obviously interest rates are going higher. Housing has been slower. So curious, your early take on 2024 and if the industry stays challenge, can you help us think about how Tempur might change strategy if at all in that kind of environment? Thanks.
Scott L. Thompson
And we certainly see and agree that there are some headwinds in 2024 and don’t want to underestimate those or let you think that we’ve got our head in the sand. Those are those are all good points of why the macro, there should be some headwinds in there. But if you look at the industry, we’re already so far on the bottom from historical standpoint that I think that we probably are in good shape. I think some of this is self-inflicted from our execution of an industry standpoint on advertising. So I’ve used the term bouncing around the bottom. Probably the industry took a little bit of a step down, probably bounced a little further down in the bottom. But I think you either get in 2024 bouncing around the bottom or you get this slow recovery that we’ve been looking for in the industry. What that means for Tempur Sealy, I see nothing going on in the marketplace that would make me think that we would not continue to take market share. And so without I don’t know what 2024 looks like yet, we haven’t finished our budgeting. But I think even if it’s we’ll call it a softer overall market, I think more market share gains will help offset issues there. And then as I mentioned earlier on the call, we’ve got some internal issues that we’re in control of from a cost standpoint, that I think give us some optimism, as to we’ll call it EPS, when you get down there. Top line is going to be a little more volatile to look at but I think we feel relatively comfortable going into 2024 with more details coming when it’s appropriate.
Carla Casella
Hi, thank you for taking the question. You commented on commodities and how they’re improving or normalizing a bit but there’s still some that are well above the pandemic. Can you just break it down a little bit in terms of what some of the key commodities that you’re seeing?
Scott L. Thompson
Absolutely. So the way I think about that is just from a framing standpoint is that we indicated historically that we’ve been able to cover the cost of the commodity inflation through taking price however, from a mathematical standpoint that created a margin, meaning the math issue approximately 400 basis points. So sitting here today, we think there is still about half of that to go. The way I think about from a commodity overall standpoint, it’s really puts and takes. Everything is definitely off its peaks and whether that be chemicals, lumber, steel, etc. However, if you look at where we started this journey, there’s still a way, there’s still a way to go. However, commodities in and of itself is not the story. It is that there’s also another component of that story, which is we continue to work with our suppliers, our major suppliers to make sure that they understand the potential from a company standpoint and the momentum that we have. So yes, we’ve seen some tailwinds from commodities over the last couple of bps. However, what we’ve also done is we’ve entered into very constructive win-win contracts and relationships with our existing suppliers to ensure that the gift keeps on giving not only from a commodity standpoint but as a relationship, strategic relationship to see benefits from an EBITDA standpoint.
November 6, 2023
Leggett & Platt, Incorporated (LEG) Q3 2023 Earnings Call Transcript
Oct. 31, 2023 10:34 AM ETLeggett & Platt, Incorporated (LEG)

Q3: 2023-10-30 Earnings Summary
EPS of $0.36 misses by $0.04 | Revenue of $1.18B (-9.19% Y/Y) misses by $64.81M
Leggett & Platt, Incorporated (NYSE:LEG) Q3 2023 Earnings Call Transcript October 31, 2023 8:30 AM ET
Company Participants
Cassie Branscum – Senior Director, Investor Relations
Mitch Dolloff – President and Chief Executive Officer
Ben Burns – Executive Vice President and Chief Financial Officer
Tyson Hagale – Executive Vice President and President-Bedding Products
Mitch Dolloff
Good morning, and thank you for participating in our third quarter call. I would like to start the call by thanking our employees for their tremendous efforts in what was another challenging quarter. Ongoing weak demand impacted our bedding products and furniture, flooring and textile product segments, but was partially offset by continued demand strength in our specialized product segment. Sales in the quarter were down 9% versus third quarter 2022 from lower volume and raw material related price decreases. Acquisitions added 2% to sales.
Third quarter earnings per share were $0.39. This includes $5 million or $0.03 per share of gain from the sale of real estate. Excluding this item, adjusted earnings per share were $0.36. Earnings decreased year-over-year, primarily from lower metal margin in our steel rod business and lower volume in our residential end markets. These decreases were partially offset by lower incentive compensation and bad debt expense.
Cash flow from operations was $144 million, up $78 million versus third quarter of 2022. We are lowering our full-year guidance to reflect continued volatility in the macroeconomic environment, continued low consumer demand in residential end markets, and the modest impact we’ve experienced so far from the UAW strike on our automotive business. We are focused on anticipating and adapting to market changes, improving operating efficiency, driving strong cash management, and engaging with our customers on new product opportunities. We are evaluating opportunities across our businesses, including further integration of our specialty foam and interspring operations that are expected to support improved profitability, a strong balance sheet, and continued shareholder returns.
Now moving on to segment results and demand trends. Sales in our betting product segment were down 17% versus third quarter of 2022. Demand in the US betting market remains soft, but relatively stable sequentially. We continue to anticipate full-year mattress consumption to be down high single digits. In the quarter, we saw modest sequential improvement in innerspring and mattress units, but we expect a deceleration in units sequentially in the fourth quarter due to normal seasonality. Metal margin expanded to its highest point in mid-2022 and narrowed as expected. We still anticipate metal margin to be down mid-teens versus 2022.
While our commercial teams continue to evaluate customer opportunities and commercialize new products, soft demand remains the largest headwind to profits. In the near term, we continue to drive operational efficiencies, especially in our specialty foam business to help offset soft volume. Additionally, we believe meaningful opportunities to increase profitability exist and are evaluating a number of possibilities, including the further integration of our specialty foam and innerspring operations I mentioned a moment ago, which should drive manufacturing savings and product development gains, optimizing our production and distribution capacity to service our customers effectively and efficiently, and enhancing our value proposition to our customers through expanded product capabilities and growing content at attractive price points.
Sales in our furniture, flooring, and textile product segment were down 11% versus third quarter 2022, driven by soft demand across the segment. Sales in home furniture, fabric converting, and flooring were down year-over-year, but roughly in line with second quarter levels. Work furniture demand has softened modestly with slower activity in European markets. In geo components, demand continued to soften in home improvement retail and civil construction end markets. We expect demand across the segment to decelerate sequentially in the fourth quarter due to normal seasonality.
Susan Maklari
Good morning. I want to start on the specialized segment. Perhaps a couple of things in there as we think about auto, especially. I guess first, can you talk about your ability to return to volumes as the strike eventually hits full resolution and those OEMs start getting back to work in there. How should we think about that potentially coming through the business? And then I also noticed in the release you mentioned that you had consolidated some facilities in there. Any thoughts on, one, the impact to the margin perhaps this quarter, but two, just how we should think about the cost structure of that business and any further improvements or things that you can do there?
Mitch Dolloff
Yes. Sure, Susan. I’ll try and get to all those. Remind me if I miss them.
Susan Maklari
I know it’s a lot.
Mitch Dolloff
That’s good. On the UAW impact, let’s start there. I mean, of course, things appear to be moving in a better direction now with tentative agreements reached among the big three U.S. auto producers. Still have to be approved by the union members themselves, so still some uncertainty out there, but definitely appear to be moving towards a better spot than could have been possible. And so, a little tricky there for us on the guidance because of the way the strike progressed against all three OEMs in a different facility. So really each of those steps had a different impact.
You saw for us that the impact was pretty minimal in the third quarter. And so far, as we’ve gone through the fourth quarter, through October, basically, not too significant as well. I think that’s due mainly for three reasons. One, as I said, it’s very facility-specific at the OEMs. And so it’s a different impact to everybody. I also would say that I think that as you go through the tears in the supply chain, I think people, all of us, including us, have tried to learn from the difficulties that we had during the pandemic. And so, while the orders decreased some and sales decreased some, people were trying to be very cautious through the supply chain and not put ourselves in a position where we couldn’t respond with the strike ended.
And so that gets to your question. So I think that as now the labor is coming back and those facilities are getting back up and running, I don’t think it’ll just have to go back to normal overnight, as we know. But I think if we continue to move forward as we are, there’ll be a little bit of a slowdown, but it shouldn’t be too significant. Hard to tell. We’ve baked in, of course, in our outlook what we’ve seen through our order book so far. So maybe it gets a little bit worse, but if things return in a decent way, I think that will continue to move forward pretty much as we are. So we’ll stay posted there. I don’t think that it is likely to be a significant change to us, but if it is, then we’ll think about whether we need to report on that or not.
Then in the consolidation there, yes, I think that’s a good example of us continuing to look for ways to improve our operating efficiency and cost structure and really optimizing our footprint there in the automotive business. So facilities in Asia that had a relatively small one and a large one that made the same type of products. And after doing some work, realized that we could pull those together. So it did have some cost impact for us in the third quarter. It should drive some good gains for us going forward. It wasn’t a huge consolidation, but I think it’s a good example of taking advantage of the opportunities that we have. And we’ll continue to look for more of those across the full business.
I think the outlook for automotive continues to be strong. We still have low inventories. We have an aging vehicle fleet. There’s certainly some dynamics that have been showing up in the market and the forecast, I would say, especially with the UAW strike, but kind of ups and downs in China as well. But I think the long-term outlook is encouraging there for us. Finally, I think we’ve making — the team is doing a good job of making progress in solving some of the production issues that we had here in the U.S. that we talked about at one of our facilities earlier in the year. So, we still have some work to do, but have made significant progress there. And we’ll continue to drive margin improvement across the business, continue to make progress in our inflation recovery there, probably up to about 85% recovery, and with some of the commodity costs deflating now, probably about the end of us talking about that online. But feel good about our outlook there, and we’ll continue to drive larger improvements.
Bobby Griffin
Good morning, everybody. Thanks for taking my questions. I guess, first I want to talk about — first I want to hit on the bedding product segment. It’s more just of a longer term question. A lot’s changed in that segment over the last, call it, 18 months, especially with the spread coming down. So if we’re in a world where the spread on rod is kind of stays where it is today or is under a little bit further pressure, would volumes come back in a recovery scenario? What is the margin profile of that business in that type of setup? We used to think of that business as a 10-ish, 9-ish to probably 11-ish EBIT margin business? What could it be if the spread doesn’t ever go back to those all-time high levels?
Tyson Hagale
Hey, Bobby. This is Tyson. I’ll jump in and try to answer it for you. I think we — obviously, there have been a lot of changes over the last 18 months, a lot of craziness, supply chain and demand related. I think over the longer term, we still think the fundamental margin profile exists. We have some work to do. The top drag, of course, we’ve said it quite a few times is volume and so a big part of this will be what the recovery looks like and exactly where it comes from and what type of products.
We’ve mentioned our work that we need to do to not only integrate but improve the operating efficiencies in our specialty foam business. That’s a big driver for us as well. On top of that, just continuing to try to think how we can most effectively serve our customer base from our manufacturing operations and distribution. And then also continuing to work in our product development and commercializing our new products, and especially with content games. So I think all of the market is changing a lot and continues to. We have a lot of different things that we push on that we think gets us kind of to that same type level in terms of margin.
Bobby Griffin
Okay. And then I think this is the second time you guys have called out about the potential of facilities, rationalizations, or just some work you’re doing inside the ECS business and looking at some different options. Is there a time frame to kind of complete that initial dive through where we could think about maybe the potential impact from some of these changes, or are we still in the early innings of looking at all the different options?
Mitch Dolloff
Bobby, I think we’re still in the early innings. It’s a great question. And also about the changes in the bedding market. I think that’s really fueling us to go back and say, hey, how do we need to adjust our outlook and take actions to make sure we’re driving profitability and strong cash flow and shareholder returns. And so, that’s what we’re doing. We still have work to do. I think the consolidation that we mentioned in automotive is a good small example of that. So we’ll look across other businesses, but certainly a lot in bedding that we’ve mentioned before.
But Tyson, anything you would add there? I know there’s not a lot more that we can say at this point.
Tyson Hagale
Sure. No, I mean, we’re working on a couple of things in specialty foam. I can’t remember if we’ve mentioned them in the past, but just trying to optimize our footprint. We have some on the west coast where we’re just trying to reduce some of the complexity and also in the southeast part of the United States where we’re already working on some there as well. But I think it probably also goes, Bobby, to what we’ve talked about where we had to pause, the integration of specialty foam into L&P. And even beyond that, when Leggett acquired the ETF business, it was four companies that were also being brought together. So on top of that, as Mitch said, it’s early innings because we still have a lot of that work that needs to be completed.
Keith Hughes
Okay. And in the bedding, your specialty foam business compared to US Spring has done better, really for every quarter this year. Could you talk about, do you think that’s share wins, is that just the market as a whole? What’s going on with the dynamic between those two? And I’m speaking to unit performance.
Tyson Hagale
Sure, Keith. This is Tyson. We talked about this, I think, going back to last year where we had a pretty heavy emphasis in our specialty foam business with our digitally native customers and, even more so than the broad bedding market in the U.S., that segment of the market was really disrupted. And so we talked about the need that we had even in the early part of the recovery, as the market recovers, that we needed to diversify our customer base. And so, our commercial team has been working really hard, even in a tough market, trying to uncover those opportunities and they’ve been making some progress there. And so, I think it’s more of — more that the nature of the improvement there is just as we’ve been able to pick up some wins, even in the [sole] (ph) market, diversifying the customer base and that’s helping us even as the market’s recovering.
Keith Hughes
And that’s in foam you’re referring to, correct?
Tyson Hagale
I’m referring to foam, yes.
Keith Hughes
Yes, okay. And I guess final thing on this, if you look at the customer list in specialty foam, are — at one time I think [ECSI] (ph) was very concentrated with a couple. Can you give us an idea of the largest customers, how much they represent of foam sales?
Mitch Dolloff
It’s kind of a tough question to answer, Keith, but going back into history, it was more concentrated, like with the digitally native customer list. Don’t want to get into how many that represented, but we still have some key customers, but we are growing that as we try to diversify the customer base.
Ben Burns
Yes, so Tyson, is it right to say, I mean, at the time of acquisition, as you said, focused in the D&Bs, still a decent list of them. It wasn’t just one or two. And as that part — that segment of the market has struggled a little bit, the team has done a good job of diversifying our customer base.
November 2, 2023
Huntsman Corporation (HUN) Q3 2023 Earnings Call Transcript
Nov. 01, 2023 3:44 PM ETHuntsman Corporation (HUN)

141.44K Followers
Q3: 2023-10-31 Earnings Summary
EPS of $0.15 misses by $0.04 | Revenue of $1.51B (-25.11% Y/Y) misses by $60.92M
Huntsman Corporation (NYSE:HUN) Q3 2023 Results Conference Call November 1, 2023 10:00 AM ET
Company Participants
Ivan Marcuse – VP, IR
Peter Huntsman – Chairman, CEO & President
Phil Lister – EVP, CFO
Peter Huntsman
Ivan, thank you very much, and thank you all for taking the time to join us this morning. This past week, I had the opportunity to visit one of our largest aerospace customers with our Board of Directors. We watched firsthand as Huntsman’s composite raw materials were applied to some of the most fuel efficient and modern aircraft built anywhere in the world today. We also visited one of our plants that is making Germany’s premier sports cars lighter and consume less electricity. We spoke to our associates at the same plant who are responsible for making components for a smarter, more reliable power distribution and grid system.
I’d go on about the numerous applications that Huntsman is now pushing to serve a less energy intensive, but more energy-reliant economy. All this give me cause for optimism, and it’s a great reminder about our company’s position in the global marketplace.
Over the past 24 months, we’ve seen some of the strongest economic performance as we recovered from a global pandemic and subsequently among the most chaotic economic conditions as European energy policy seemingly collapsed, China’s bounced back stumbled along and North America’s construction markets took a beating over high interest rates and consumer uncertainty.
As we now have some visibility into the beginning of the fourth quarter, as I said during our last earnings call, we expect this to be a tough quarter depending on the amount of customer deinventoring we see and lack of consumer confidence. Our projections for the fourth quarter remain murky, as the real year-end seasonality does not yet start for a couple more weeks.
However, our customer and plant business demonstrates how vital our products are in an evolving global economy. We continue to see the recovery of the aerospace industry. In all of our other divisions, we will be a vital supplier to both the EV and ICE automotive industry. We continue to see growing demand in power and electronics, building insulation materials, cleaner solvents for the chip industry and expanding markets for lightweight and stronger materials.
We will pace our share buyback program to make sure we are both returning value to our shareholders and preserving a strong balance sheet that will assure our flexibility and allow us to capitalize on M&A opportunities.
During 2024, we will complete a $280 million cost realignment, a European restructuring program we announced over the past 2 years. This will help offset inflation, flatten our organization and allow us to compete more aggressively and respond quicker to market conditions.
As mentioned in our prepared remarks, we will be very conservative on our capital spend this next year. We will spend what is needed to assure our reliability and safety as well as investing in high-priority growth projects. Depending on the speed of an expected recovery in 2024, we will be ready to proceed with other projects as market conditions may warrant.
In short, as we conclude what has been a year with more challenges and opportunities, we believe that we’re in a unique position to rebound quickly as markets shift direction. We will also be calibrating our operations around a conservative approach to and capital allocation towards long-term shareholder return and reliability.
Aleksey Yefremov
Peter, it seems like China could be one of the main reasons, things global or so tough in MDI, in particular. Do you see anything in China to suggest a path for better 2024?
Peter Huntsman
Well, I think that it’ll — actually, first of all, it’s good to hear from you. And as I look at China, look, we’ve been saying for the past year that we’re seeing a slow and steady recovery taking place in China. I think we’re a little bit of an outlier earlier in the year when we were saying that people we’re expecting that there was going to be a very sudden bounce back. But I — we’re seeing in the housing market that interest rates are dropping. And typically, that will mean that there’ll be a recovery following, but we’re not overly reliant on that.
I think where we are invested on the domestic energy conservation in China around insulation, around building materials, around the EV market. We continue to get market share in the auto, both in ICE and in EV and in consumer goods and appliances. So our focus is not on the export segment of the Chinese economy rather the domestic consumption and building side of the Chinese economy.
And in that, I think that we’re going to just continue to see slow but steady growth and recovery in that area. And to that end, as I look at Chinese prices from the beginning of the year, they’re actually slightly up from where they started the year. And I think that we’re going to continue to see continued improvement throughout 2024 in China.
Phil Lister
Yes. Aleksey, I think it’s clear we’ve got a headwind going to the fourth quarter, particularly when you look at benzene, which averaged about $3.10 in quarter 3. It settled in October over $4. It settled for November at $3.65. Spot price is lower, but that is our largest raw material. Natural gas in Europe has also risen from approximately $10 a Btu to about $14 to $15 today. So some headwinds there, there are some benefits in the chlorine chain, with chlorine coming down, epichlorohydrin is falling. But those are outweighed by benzene and natural gas.
Michael Sison
Peter, when you think about, I guess, Polyurethanes in total, you’ve done a lot of things over the last several years going downstream and trying to improve the quality of the business. This year’s, for a lot of businesses, look really tough to see those changes. But when you think about, again, just thinking where the business see when things recur, maybe talk about whether EBITDA margins can get back to all this destock in difficult times end?
Peter Huntsman
Yes. I think that as we look at MDI, fundamentally, I do think that we’re in unprecedented downdraft right now with MDI, putting it mildly. The reason I say that is this is a product since I’ve been in it for the last 25 years, and some of the veterans that been in the last 30-plus years, we’ve not seen 2 consecutive years of falling demand. And that’s largely not about because of macroeconomic conditions. We’re not seeing competing materials. We’re not seeing a lots of people that are — or stopped building homes with OSP. They’ve stopped using MDI and furniture and bedding. And so it wasn’t anything. We see MDI continuing to expand its application base, its chemistry base and getting better.
So — I mean, if I look at the bare fundamentals, there’s absolutely no reason why this material during normal economic conditions, or even normal economic minus a bit, shouldn’t be doing immensely better than it’s doing today. And so I think that getting back to what I would see as mid-teens — plus mid-teens sort of margins. I personally don’t think that it’s going to take a great deal of change just from the sense that I don’t see any fundamentals in the business that have changed the broader outlook of MDI.
When U.S. housing comes back, that’s obviously a very large component of MDI demand. When people buy a new home, not only did the product that goes and build the home, but also to furnish a home and — means of furniture, bedding and paints and coatings, electronics and so forth. When you look at the automotive industry, particularly this last quarter, while we weren’t directly hit with strikes that we saw in North America, our customers weren’t hit by that. That did put more MDI on the market than you otherwise would have seen, probably having a detrimental effect.
And as we look at the global energy conservation and insulation areas around spray foam and insulation materials again, I look at those big macro issues. I see no reason why MDI shouldn’t recover. And when it recovers, I gladly predict — when it recovers, I think it’s going to surprise me how quickly it does.
Michael Sison
And as a quick follow-up. You referenced a Chinese MDIs in the prepared remarks. Where are we in the U.S. and Europe? And how much lower do you think will go into the fourth quarter on those prices? And do you think — what’s your thought about ’24? And what needs to happen to shore up all the regions?
Peter Huntsman
Well, fundamentally, in ’24, people need to stop tolerating losing money. And I think that, that fundamentally has to be a broad issue. It’s the age-old issue of any product that’s being bought and sold at very low margins, is that what’s the discipline of an industry to be able to sell a product and set a price to return money to shareholders. And right now, MDI is not doing that. And so fundamentally, I think that there needs to be a change in the entire MDI market.
Now that doesn’t just come about without economic recovery. It doesn’t come about through without customer demand returning. And those things will happen. But as I look at how close much of this is getting to fixed cost sort of return, it seems like we’re there. As I look at pricing in Europe, we’ve been able to get some modest increases in the fourth quarter. I’d like to say that’s because demand is improving, but I think it’s more just discipline. And there are signs that I’m saying or at least feeling that we’re to the bottom. But unfortunately, I think I’ve probably said that in the past. And so I’m not ready to call the bottom out, but I think that we’re very close to it.
Hassan Ahmed
On the polyurethane side of things, obviously, a bunch of questions around trying to sort of forecast demand, obviously, in our industry is always challenging to do. But it seems that the supply side of thing’s easier to forecast, right? So as you sort of sit there and look at polyurethane, sort of cost curves. I mean, in the response to one of your earlier questions, you talked about how margins are same for some of the marginal producers. You guys, yourselves, reported 8% EBITDA margins this quarter.
So I’m just trying to understand the marginal guys presumably are losing money right now. So with the supply looking the way it’s looking, I mean, do you forecast potentially shutdowns, more delays in capacity additions and the like and how will that play out as it pertains to a potential recovery going forward?
Peter Huntsman
I’m not sure that the recovery going forward is going to be dependent on any shutdowns. I am a bit surprised that, that hasn’t happened yet. As I look at the various regions, I look at the U.S. I don’t see a lot of shutdowns of total facilities in the U.S. because the major producers in the U.S. only have one facility. And I don’t see somebody exiting the North American market. And I think the same can be said for China.
Now there are people that are like — that have multiple facilities in China but I personally just don’t see them shutting one of down. They’re very competitive. They start with foam and they work their way through on a competitive set of economics.
Europe, in my opinion, longer term, when I look at the size of the facilities that are in Europe and the number of people that have multiple facilities in Europe, I do question the longer-term viability of some of those assets. But again, I’m not privy to decisions that are made, obviously. In those companies, I don’t know what their economics are. To the degree that they’ve got longer-term contracts with government-assisted money or with unions and so forth, I have no idea what limitations there might be on that. But fundamentally, I think that the industry is shutting down lines more than they’re shutting down facilities. And I think you’re probably going to continue to see that.
Phil Lister
The only supply coming to the market, Hassan, will really be 1 month over the next sort of 4 to 5 years, but there’s nothing else major that’s been announced and if the industry returns to its 4.5%, 5% growth level, then that will have strip supply as a rebound occurs.
Q – Unidentified Analyst
Perfect. And just a follow-up on the raw materials for MDI, besides a well-known increase in benzene prices, can you provide us a little bit with what you are assuming for Q4 in each of the key regions, Europe, China and the U.S. for other key raw materials, chlorine, et cetera?
Phil Lister
Yes. I think we said — so we outlined benzene, we outlined natural gas was headed in Europe intended to 15. Chlorine caustic under a little bit of downward pressure overall, so we built that in. This will remain I think — which are the two main raw materials, although they still represent a minority of Advanced Materials is coming off as well.
And then you’ve got ammonia, which is obviously a big raw material into Performance Products, which has been moving upwards. It moved down throughout the year, but it’s been moving upwards. That also impacts Polyurethanes in nitric — into nitric acid. So that’s the way to think about our raw material base pending still remains the biggest raw material that we purchase globally.
Peter Huntsman
And certainly, the most volatile — a lot of those products that Phil just mentioned on longer-term contracts or pass-through contracts with natural gas and so forth.
Matthew Blair
Peter, so it’s obviously a tough market, but your prepared comments did mention that building solutions volumes were up both quarter-over-quarter as well as year-over-year. So I don’t know that seems encouraging in the tough construction market. Should that be the read-through for investors? And do you have any more color here? And also, is this because you’re gaining share in the spray foam market or are there other dynamics at play?
Peter Huntsman
Well, a couple of things. First of all, last year, third quarter was a pretty tough year. I mean, it was a low point, I think, as we look at the overall business. But as you look at the third quarter, we’re up 2% from — versus the prior quarter. We’re up 10% a year ago.
If you look at some of our other products like the composite wood products and so forth, as we look at the order patterns thus far into fourth quarter, and I don’t want to get ahead of myself, but we’re seeing a positive year-on-year comparison there. And that’s the first time we’ve seen a positive comparison there for probably over a year on a quarterly basis.
So again, I’m not — I don’t want to get overly encouraged by this, but these are signs you first have to hit the bottom, and then you’re going to see a bounce back. So as I look at things from where we are in the third quarter, I think there’s some positive signs I’m seeing in HBS and the building solutions, all around in — areas around our total insulation business. From the prior quarter, it was up 3%.
From a year ago and again, this isn’t just spray foam. This is our installation that goes into rigid panels, construction panels and so forth, we’re down 4% over a year ago but up 3% sequentially. So starting to see, I think, signs that we’re hitting the bottom in some of these areas, and I’d like to think that we’re recovering in others of them.
So I would take those as — we call them green shoots, but I think it’s a tired metaphor because we’ve used it now the course in — and we haven’t seen much more than green shoots. But no, I think there’s probably more of those we see today than we did certainly a quarter ago.
 Everchem Updates Archive
 Sign Up for Email Updates