The Urethane Blog
How hard would it be to bring a bunch of laptops and a couple company cell phones, beach chairs and coolers, and get the job rocking like it’s meant to be?
Subscribe to the Urethane blog for more Everchem Updates here
July 27, 2023
“The Housing Recession Is Over”: Pending Home Sales Post First Increase Since February
by Tyler Durden
Thursday, Jul 27, 2023 – 10:15 AM
The housing market may be paralyzed, with the gap between bids and asks wide enough for an army of Hummers to drive though, but where the rare transasction is still taking place, buyers have been aggressively chasing offers as recent existing home sales and the just released pending home sales data revealed.
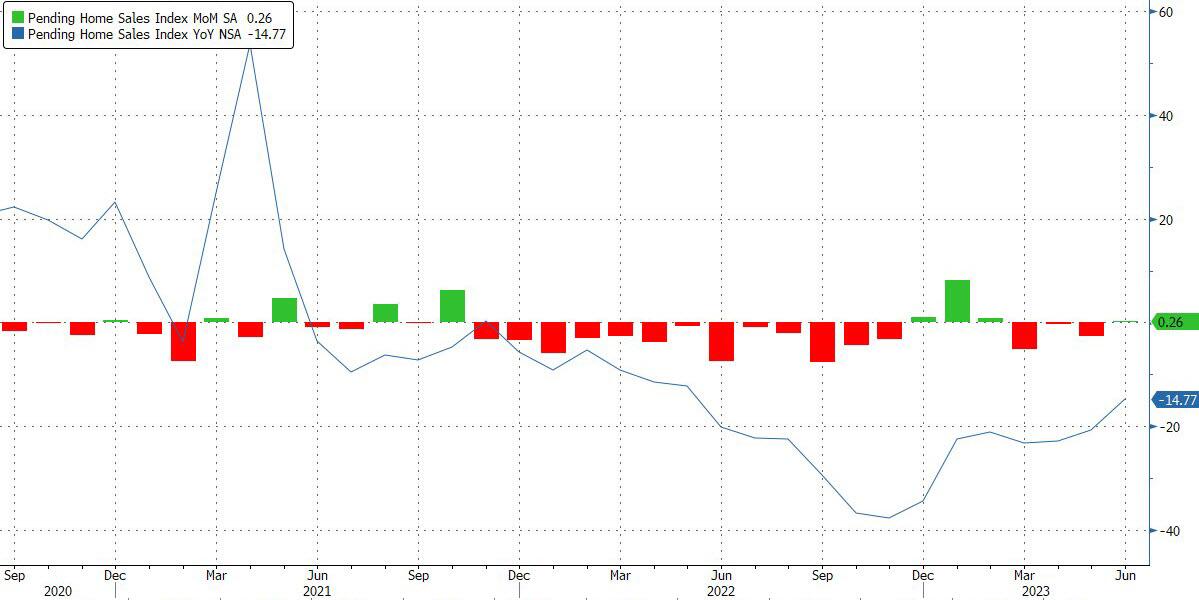
In June, pending home sales registered a modest increase of 0.3% the previous month – the first increase since February – according to the National Association of Realtors, beating estimates of a -0.5% drop and following last month’s -2.5% decline. The modest sequential increase raised the annual drop to -14.8%, an improvement from the -20.7% drop in May.
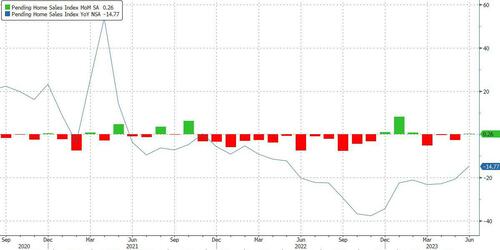
Regionally, the South and West posted monthly losses, while sales in the Northeast and Midwest grew. All four U.S. regions saw year-over-year declines in transactions.
“The recovery has not taken place, but the housing recession is over,” said the always cheerful NAR Chief Economist Lawrence Yun, “The presence of multiple offers implies that housing demand is not being satisfied due to lack of supply. Homebuilders are ramping up production and hiring workers.”
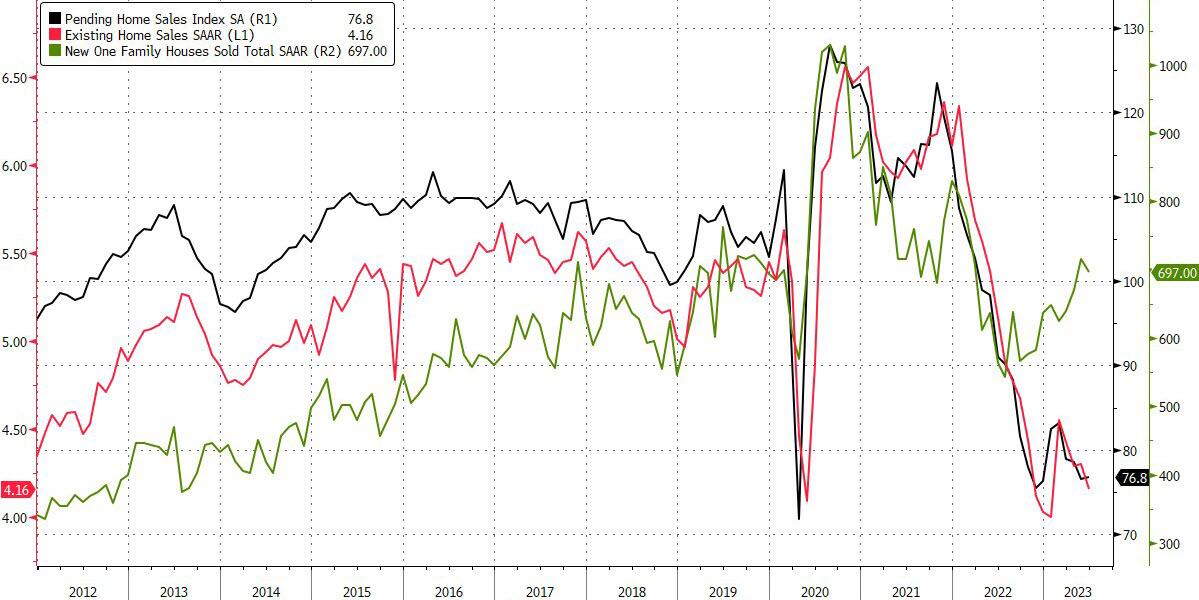
Still, when one looks at both the pending and existing home sales index, it is difficult to share Larry’s enthusiasm. Also notable is the record disconnect between existing/pending transactions and new home sales which have been storming higher in recent months.
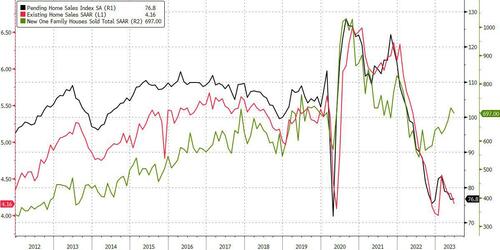
The Pending Home Sales Index – a forward-looking indicator of home sales based on contract signings – rose 0.3% to 76.8 in May. Year over year, pending transactions fell by 15.6%. An index of 100 is equal to the level of contract activity in 2001.
NAR forecasts that the 30-year fixed mortgage rate will hit 6.4% this year and then decline to 6.0% in 2024, while the unemployment rate will rise slightly to 3.7% in 2023 before increasing to 4.1% in 2024.
“With consumer price inflation calming close to the Federal Reserve’s desired conditions, mortgage rates look to have topped out,” Yun added. “Given the ongoing job additions, any meaningful decline in mortgage rates could lead to a rush of buyers later in the year and into the next.”
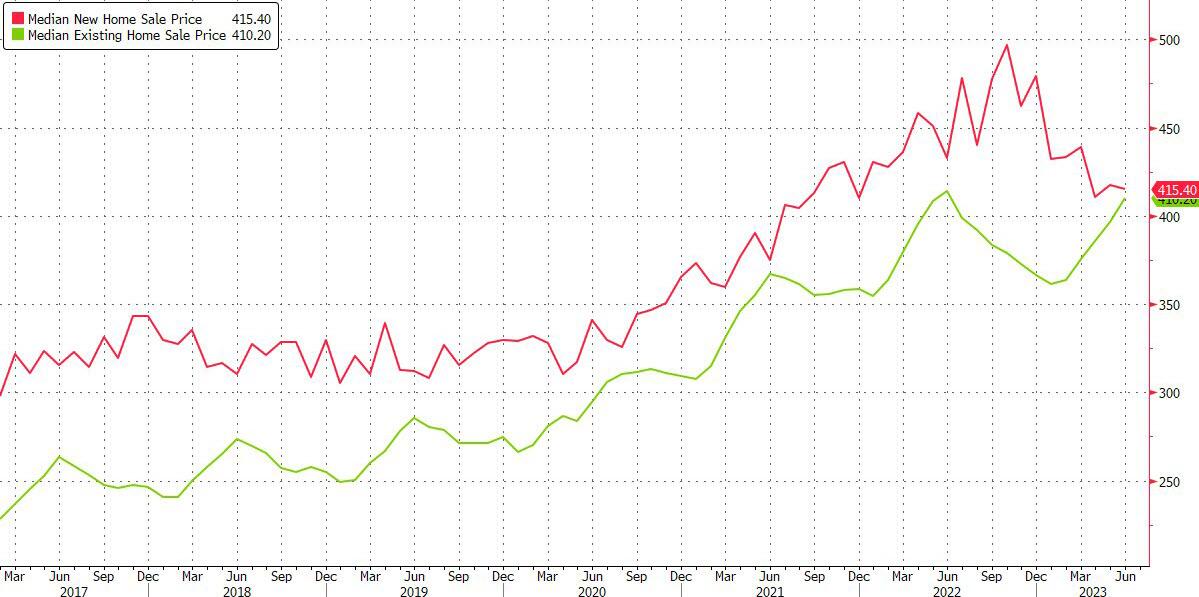
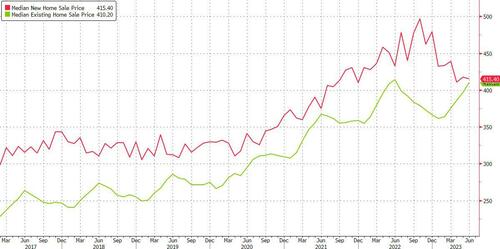
NAR expects existing-home sales to decrease 12.9% from 2022 to 2023, settling at 4.38 million, before climbing 15.5%, to 5.06 million in 2024. Compared to last year, national median existing-home prices will remain steady – declining 0.4%, to $384,900, before rebounding by 2.6% next year, to $395,000. The West – the country’s most expensive region – will see reduced prices while the more affordable Midwest region is likely to see a small, positive increase. Housing starts will drop 5.3% from 2022 to 2023, to 1.47 million, before increasing to 1.55 million, or 5.4%, in 2024.
“It is critical to expand supply as much as possible to widen access to homebuying for more Americans,” Yun said. “Home prices will be influenced by how much inventory is brought to market. Increased homebuilding will tame price growth, while limited construction will lead to home price appreciation outpacing income growth.”
Newly constructed home sales will increase from last year by 12.3% in 2023, to 720,000 – due to additional inventory in this segment of the market – and increase by another 13.9% in 2024, to 820,000. The national median new home price will decrease by 1.9% this year, to $449,100, and then improve by 4.2% next year, to $468,000.
July 27, 2023
Dow announces FM following fire at Plaquemine, Louisiana, US EO unit
Melissa Wheeler
18-Jul-2023

HOUSTON (ICIS)–Dow has announced a force majeure (FM) on ethylene oxide (EO) following a fire at its Plaquemine, Louisiana, unit.
According to the company, the fire was extinguished on Sunday; however, it will take several weeks before the unit restarts.
Currently, demand for EO has been weak as downstream ethylene glycols (EG) and surfactants demand has been negatively impacted by shifting consumer spending habits.
As a result of low demand, it is unlikely market supply will be negatively impacted.
The majority of EO contracts are formula-based, and price movement comprises 80% of the change in the ethylene price and an additional conversion fee, or adder.
Like ethylene, EO contracts are settled at the beginning of the month for the previous month’s price.
EO is largely used to make monoethylene glycol (MEG), a key feedstock for polyethylene terephthalate (PET). EO’s secondary outlet is in surfactants.
Other EO derivatives include glycol ethers, polyols for polyurethane systems, polyethylene glycols and polyalkylene glycols.
EO producers in the US include BASF, Dow, Eastman Chemical, Formosa, Indorama Ventures, Lotte Chemical, LyondellBasell, Sasol and Shell Chemical.
July 27, 2023
China Polyurethane Products Output Dropped 5.5% YoY to 12 Million Tonnes in 2022
PUdaily | Updated: July 25, 2023

In 2022, the global economy experienced a sharp slowdown due to multiple challenges such as the Russia-Ukraine conflict, the European energy crisis, the pandemic, inflation, aggressive interest rate hikes by the Federal Reserve, and significant depreciation of non-US currencies. The rapid decline in the manufacturing sector further incubated the weaker prospects for global economy.
As a new type of high-performance synthetic material, polyurethane products have significant importance in promoting China’s low-carbon economy and improving the living standards of its residents. Polyurethane (PU) is widely used in various industries related to clothing, food, housing, and transportation due to its outstanding properties. Within the complex and volatile economic context, China, being both the largest producer and consumer of polyurethane products, experienced notable impacts on both the production and demand sides. China’s PU products output in 2022 totaled roughly 12 million tonnes, representing a year-on-year decrease of 5.5%, according to Pudaily. The compound annual growth rate from 2018 to 2022 was 1.4%.
PU products mainly include foam plastics, elastomers, fiber plastics, fibers, leather shoe resins, coatings, adhesives, sealants and others. Foam plastics make up the largest proportion among them. PU foam plastics can be divided into rigid foam and soft foam systems, which have excellent elasticity, elongation, compression strength, and flexibility, as well as excellent chemical stability. Moreover, PU foam plastics also possess superior processability, adhesive properties, and insulation properties, making them high-performance cushioning materials.
PU soft foam products are mainly used for furniture cushions, mattresses, car seat cushions, composite fabrics, packaging materials, and soundproofing materials and more. In 2022, China’s PU soft foam products output reached 2.49 million tonnes, a year-on-year decrease of 10.9%.
The upholstered furniture industry is the largest downstream sector of PU soft foam, with a share of 48.8% in 2022. The consumption of PU soft foam products in the furniture industry contracted significantly in 2022 due to the downturn in the building materials and real estate sectors.
PU rigid foam products are mainly used in refrigerators, freezers, pipelines, spraying foam, panels, containers, etc. In 2022, China’s PU rigid foam products output amounted to 1.96 million tonnes, a decrease of 8.1% compared to the previous year. The refrigeration industry took up the largest share in the PU rigid foam products, accounting for 56.5% of the total output in 2022. Due to factors such as COVID-19 recurrences, changes in the supply chain, and a decline in economic growth, as well as the high ownership and low replacement frequency (a refrigerator’s service life is around 10 years), the decline of the real estate dividend, soft demand caused by low consumer confidence, and high inflation, wars, and interest rate hikes in many European and American regions, the overseas demand for refrigerators shrank in 2022. Furthermore, due to the high base in 2021, China experienced a significant decline in both domestic sales and export of refrigerators.
July 25, 2023
Dow Inc. (DOW) Q2 2023 Earnings Call Transcript
Jul. 25, 2023 10:46 AM ETDow Inc. (DOW)
Dow Inc. (NYSE:DOW) Q2 2023 Earnings Call Transcript July 25, 2023 8:00 AM ET
Company Participants
Pankaj Gupta – Investor Relations, Vice President
Jim Fitterling – Chairman and Chief Executive Officer
Howard Ungerleider – President and Chief Financial Officer
Jim Fitterling
Thank you, Pankaj. Beginning on Slide 3, we continued to navigate a challenging macroeconomic environment with slow global growth in the second quarter. Despite lower year-over-year sales and earnings, Team Dow delivered sequential earnings improvement by executing on our financial and operational playbook. We leveraged our diverse portfolio to capitalize on gains in packaging and modestly higher seasonal demand in building and construction. This resulted in a sequential improvement in volume. In addition, we continue to implement our $1 billion of proactive and targeted cost savings actions delivering $250 million of savings in the quarter and $350 year to date.
Net sales were $11.4 billion, down 27% versus the year ago period, reflecting lower demand and prices due to slower macroeconomic activity. Sales were down 4% sequentially, as volume gains were more than offset by lower local prices. Volume decreased 8% year-over-year, led by a 14% decline in Europe, the Middle East, Africa, and India, or EMEA. Volume was up 1% sequentially, driven by gains in Asia Pacific and Latin America, as well as in industrial intermediates and infrastructure and performance materials and coatings. Local price decreased 18% year-over-year and 5% sequentially due to lower demand on weak macroeconomic activity, as well as lower global raw material costs.
Operating EBIT for the quarter was $885 million, down from $2.4 billion in the year ago period, primarily driven by lower local prices. Operating EBIT increased $177 million sequentially, driven by gains in packaging and specialty plastics. We generated cash flow from operations of more than $1.3 billion, up more than $800 million versus the prior quarter, driven by improved working capital. On a trailing 12 month basis, our cash flow conversion is 98%.
Our strong financial position gives us the flexibility to continue to advance our long term strategic priorities, supported by our disciplined and balanced capital allocation strategy. In the quarter, we returned $743 million to shareholders through dividends and share repurchases. Year to date, we’ve returned nearly $1.4 billion. And our balance sheet remains healthy, supported by strong investment grade credit ratings.
We also published our 2022 INtersections Report in June. The report once again received limited assurance by our external audit firm and showcases Dow’s continued progress on our ambition to be the most innovative customer centric, inclusive and sustainable material science company in the world.
Now turning to our operating segment performance on Slide 4. In the Packaging and Specialty Plastics segment, operating EBIT was $918 million compared to $1.4 billion in the year ago period. Local price declines were driven by lower global energy and feedstock costs, which in turn impacted polyethylene prices across all regions. Volume declines, primarily in EMEA, were driven by lower demand for olefins and aromatics. Sequentially operating EBIT improved by $276 million, driven by lower energy and feedstock costs.
Moving to the Industrial Intermediates and Infrastructure segment, operating EBIT was a loss of $35 million, compared to earnings of 426 million in the year ago period. Results were driven by lower local prices and demand in both businesses. Volume declines were primarily driven by lower demand for consumer durables, building and construction, and industrial applications. Sequentially, operating EBIT was down $158 million due to lower local prices and increased planned maintenance turnaround activity.
And in the Performance Materials and Coatings segment, operating EBIT was $66 million compared to $561 million in the year ago period. Local price decreases were driven primarily by declines for siloxanes and acrylic monomers. Volume was down on lower global demand for silicones and coatings applications. Sequentially, operating EBIT increased $31 million, driven primarily by seasonally higher volumes.
Next, I’ll turn it over to Howard to review our outlook and actions on Slide 5.
Howard Ungerleider
Thank you, Jim, and good morning, everyone. We continue to expect a challenging macroeconomic environment in the third quarter. While inflation is beginning to moderate, the lagging effects of higher monetary policy on consumer demand and a slower than expected demand recovery in China have resulted in a slowdown of industrial economic activity around the world.
In the US, industrial activity remains weak with June manufacturing PMI in contraction at 46.3. However, consumer demand has remained resilient supported by low unemployment levels. With inflation starting to ease, consumer confidence in June is now at the highest levels since early 2022.
In Europe, recessionary conditions persist and are expected to continue, despite lower energy prices and inflation declining to a 17 month low. Industrial activity in the region continues to contract with PMI reaching the lowest level since May 2020. In China, while we are experiencing growth, the anticipated economic rebound following the end of zero COVID restrictions has yet to fully materialize. June manufacturing PMI continues to hover around neutral level of 50, and China’s exports were impacted by the global demand slowdown, contracting at the fastest pace since the beginning of the pandemic.
Around the rest of the world, India’s manufacturing PMI expanded to 57.8 in June as demand outpaced higher input costs and ASEAN manufacturing PMI remained in expansionary territory. Manufacturing activity in Japan, however, retreated back to contractionary levels following improvements in PMI for three consecutive months. Given these regional dynamics, we will continue to take a disciplined approach to managing our operations and adapt our business to the evolving market realities.
In the Industrial Intermediates and Infrastructure segment, while demand in energy end markets remains resilient, we expect continued demand pressuring consumer durable end markets. We anticipate a $15 million tailwind from our cost savings actions, as well as a $25 million tailwind following the completion of a planned maintenance turnaround from the second quarter. Additionally, following an unplanned event at our Louisiana operations this month, our preliminary estimate reflects a $100 million headwind to earnings. I want to please reinforce that this estimate is only preliminary at this point. As we get a more refined estimate, we will update if needed.
In the Performance Materials and Coatings segment, we expect continued price pressure in siloxanes, while seasonal demand remains below normal for building and construction end markets, together contributing a $50 million headwind. Our cost savings are on track to deliver a $35 million tailwind from the segment. Additionally, the completion of second quarter turnarounds at our Carrollton and our Zhangjiagang siloxanes facilities are anticipated to contribute a $25 million tailwind in the third.
Operationally, our earnings are expected to be flat with the prior quarter as our self-help is expected to fully offset the estimated margin compression. All in, we expect third quarter earnings to be down approximately a $150 million sequentially before the impact of the Plaquemine outage as a result of the $50 million higher turnaround expense and the $100 million in project driven licensing sales, which will not recur.
Turning to Slide 7, our commitment to financial and operational discipline enables Dow to navigate the near term market challenges, while continuing to invest for the future. We are on track to deliver our $1 billion of cost savings in 2023. We achieved 35% of the savings in the first half of the year and continue to expect we will deliver the remaining 65% in the second half. This includes our previously announced global workforce reduction program. 75% of the 2,000 impacted roles exited at the end of the second quarter and more than 90% are expected to exit by the end of the year. Our $300 million reduction in planned maintenance turnaround spending remains on track and we’re continuing to execute improvements in our raw materials, logistics, and utility costs.
We’re also continuing to execute actions to rationalize select higher cost, lower return assets in our polyurethanes, coatings, and industrial solutions businesses, in line with market fundamentals. These actions support the strong financial position that Team Dow has purposely built since then. Our debt and our credit profile gives a significant flexibility and optionality to continue to advance our strategic priorities across the economic cycle. All in, our actions have allowed us to lower our cash commitments by approximately $1 billion since spin, driven by significantly lower cash interest and pension liabilities, reduce share count, and no joint venture cash contributions.
Jeff Zekauskas
Thanks very much. Two part question. Can you comment on sequential MDI price trends in the United States? And, secondly, you bought back $250 million in shares So that’s maybe about 5 million shares, but your shares went up 2 million sequentially, and you have them flat for the third quarter. So what’s the magnitude of share issuance this year?
Jim Fitterling
Yeah. I’ll take a look at MDI and then I’ll have Howard get the share buyback part of that. Look, on MDI, I think things are in relatively good position. We’ve seen MDI continue to be relatively strong in the market where MDI impact, obviously, automotive has continued to be strong. Where we’ve seen demand down is obviously in durable goods like appliances. And so, that has in some systems offering there that has put some pressure on prices. I think we are in the process of starting up MDI distillation down in Freeport, which is an expansion off of the La Porte capacity, but allows us to retire the La Porte asset. And so, I think relatively speaking, MDI is holding up relatively well. And I think from a supply demand balance standpoint, our expectation is that, some of the capacity that’s been announced out there is going to come on later than expected. And I think that’s going to offer a little bit tighter operating rates than what the industry analysts might be predicting.
Mike Sison
Hey, guys. Good morning. Your volumes are down 8% in 2Q. I think it’s the fourth quarter of [indiscernible] it sounds like third quarter will be down as well. Are you seeing any bottoming in any of your end markets? And do you think the volumes in the second half will maybe improve on a year-over-year basis at some point?
Jim Fitterling
Good morning, Mike. Good question. Volumes were down 8%, obviously, Europe was off 14%, so that’s a pretty significant part of that volume being down. Asia Pacific and Latin America volumes were stronger, and so they’ve held up relatively well. North America has been relatively flat about 1% on volume. So I think you can see, obviously, the pressure on Europe showing up in some of those markets.
In terms of the look at the macro economy, my feeling is this, we know we’re in a global economic slowdown. It really started mid last year. We saw GDP decline through the back half of last year. We saw a little spike up in Q1 of this year, but it’s been down in Q2. And the expectation is, it’ll be down in Q3 and Q4. I think it’s setting up for a ramp back in 2024. People ask a lot of times, are we in a recession? I think we’ll determine if we’re in a recession or not when we look in the rearview mirror. But the leading indicators, the destocking that happened in the fourth quarter and into the first quarter appears to be over inventories are in relatively good control. MEG ethylene glycol typically leads into a slowdown. We saw that happen last year and, obviously, it led into this slowdown. And then a lagging indicator into a slowdown is caustic and chlorine, both sides of the electrochemical unit.
Kevin McCarthy
Yes. Good morning. Jim, with regards to your industrial intermediates segment, can you speak to some of the actions that you’re taking there in terms of propylene oxide and your kind of two way resupply arrangements with [Olin] (ph) on-site there. And then more broadly, maybe as a follow-up to Mike’s question, you’re guiding 3Q a little bit lower. Do you think you’re at or near an earnings bottom in 3Q in Industrial Intermediates or how would you frame that in terms of the bigger picture cycle there?
Jim Fitterling
Good morning, Kevin. Good questions. Let me just break it up into polyurethanes and construction chemicals or the industrial solutions and look at them differently. In polyurethanes and construction chemicals, we’ve been overweight propylene oxide and underweight isocyanates for some time. So you see what’s happening with the asset moves have been trying to right size a bit on PO and exit the merchant market PO business. And that’s what has been announced so far. And then also increase the MDI distillation capacity in Freeport, which is what we’re doing and retiring the La Porte asset. I think that balances us out better with the growth in polyurethanes, which is in the downstream systems businesses where we make higher value. And so, I think you’ll continue to see us do that.
In terms of the Olin relationship, we’ve completed the negotiation of a series contracts in the US Gulf Coast that extends now through 2035, which means that the value and the sustainability and that integrated economics for both parties remain in place. And we’re going to continue to supply ethylene, energy and site services to Olin, in the US Gulf Coast and Germany. So STADA is the site primarily affected there. We’re going to Olin is going to continue to supply us chlorine and sell ethylene for the PO businesses in Plaquemann and also chlorine to the MDI assets in Freeport. I feel good about the working relationship with Olin. I think we’ve continued to manage this well, and I think we both understand that the best value for each company is to continue to work together and keep that integrated economics alive.
In terms of industrial intermediates, I would say it has been growing well. Our focus there is to continue to invest in downstream alkoxylates means to support the growth in things like home and personal care, areas like low BOC solvents for the paints and coatings industries, the intermediates for the agricultural sector. And, obviously, all of the higher value derivatives that we make that go in pharma applications and energy, think oil and gas and gas treatment, gas scrubbing, all which have great growth drivers. And to deemphasize our exposure to ethylene glycol, which is commodity. And most people probably won’t remember when we did the deal with ME Global. We still had a couple of assets here that made ethylene glycol. Longer term, it doesn’t make sense for us to make ethylene glycol and small scale assets. So we’ll move to purified EO only assets for industrial intermediates. And then all the higher value downstream and really emphasize the specialty side of that business versus the commodity.
And I do think the additional drag in the quarter of the fact that ag intermediates were very slow in second quarter because of the hot weather, farmers did not spray in the second quarter, so they missed the whole spray of crops. That’s a pretty significant volume on II&I intermediate capacity, and that’s really why you saw the drag on them. I do feel like with housing and construction being at the bottom right now, I do think you can say we’re at the bottom in that space. And I think things will look optimistic as we moved in — more optimistic as we move into 2024.
 Everchem Updates Archive
 Sign Up for Email Updates