The Urethane Blog
April 27, 2023
Call Transcript
Apr. 27, 2023 6:12 AM ETBASF SE (BASFY), BFFAF

136.26K Followers
BASF SE (OTCQX:BASFY) Q1 2023 Earnings Conference Call April 27, 2023 2:00 AM ET
Company Participants
Stefanie Wettberg – SVP, IR
Martin Brudermuller – Chairman & CEO
Hans Engel – CFO
Martin Brudermuller
Good morning, ladies and gentlemen. Hans Engel and I would like to welcome you to our analyst conference call on the first quarter 2023. 2 weeks ago, BASF released preliminary figures as we had a quite better start to the year than expected on average by analysts. Today, we will provide you with further details regarding our business development in the first 3 months of the year. Let’s start with the development of global chemical production. Based on currently available data, global chemical production stagnated in Q1 2023 compared with the prior year quarter. Compared with Q4 2022, chemical production recovered by around 2% globally, excluding seasonal effects.
From a regional perspective, chemical production grew only in China at almost 8%. However, this was due to a low baseline in Q1 2022. Chemical production declined in all other regions. The decline compared with Q1 2022 was most pronounced in Europe, followed by Asia, excluding China and North America. From the second quarter of 2022 onwards, high inflation and regulatory price levels reduced consumer demand, particularly in Europe.
Globally, demand from BASF’s key customer industry in the first quarter of 2023 was rather disappointing with 2 exemptions. Global light vehicle production grew by an expected 5.7% compared with Q1 2022. Global agriculture production also continued to grow moderately in the first quarter of 2023.
Moving on to BASF’s sales development. Sales decreased by 13.4% in Q1 2023 to around EUR 20 billion, mainly due to a decline in volume by 12.8%. All segments recorded lower volumes except for Agricultural Solutions where volumes will remain stable.
Sales prices decreased by 0.7% overall. While prices in the Chemicals, Surface Technologies and Materials segments declined, we increased prices, especially in the Agricultural Solutions segment but also in the Nutrition & Care and Industrial Solutions segment. Portfolio effects had a slightly negative impact on sales and were mainly due to the sales of the kaolin minerals business. Until the end of September 2022, this business had been part of the Performance Chemicals division. Currency effects were slightly positive and mainly related to the U.S. dollar.
Let’s move on to our earnings development by segment. The decline in BASF Group EBIT before special items largely resulted from considerably lower contribution from the Chemicals and Materials segment. In Q1 2023, these 2 segments contributed EUR 484 million to BASF Group EBIT before special items compared with EUR 1.6 billion in the prior year quarter. This decline was mainly due to considerably lower volumes and margins on the back of significantly lower demand overall.
The automotive-related business of BASF also developed well. As mentioned earlier, close light vehicle production increased by 5.7% in Q1 2023 according to IHS Markit. Volume growth was most pronounced in Europe and North America with 17% and 10%, respectively, while market in China declined by 8% due to weak demand.
In the first quarter of 2023, BASF’s sales in the automotive industry, excluding sales in precious metal trading and precious metal sales, in the mobile emissions catalyst business amounted to EUR 1.9 billion, again, an increase of 5.7%.
Matthew Yates
Just one question. Perhaps it will be a topic of conversation at the AGM later today, but I’d like to ask you about the restructuring that was announced with the full year results and the plan to reduce headcount by 2,600 jobs. I think that equates to just over 2% of your workforce. This week, I actually saw Dow announced a 2,000 headcount reduction, which is more like 5% of their workforce. So in the context of the challenges European Chemicals face to be competitive, does the Dow announcements suggest that BASF actually isn’t being radical enough in its restructuring? Your EUR 1 billion fixed cost target is not really so different to the EUR 1 billion target, and they’re obviously a much smaller company than you? So I’d appreciate any further thoughts on that.
Hans Engel
Thanks. Matthew. I think we explained our plans with respect to the restructuring that we intend to do. The EUR 1 billion is a figure that’s related to the program in itself. As always, ongoing cost reduction is part of land tackling. That’s something that you do on an ongoing basis. What we provided you with is really this restructuring package and related cost reductions that we’re expecting and the related headcount reductions. So from my perspective, I think, as mentioned, this is a program, but it is supported by a number of additional initiatives that you keep doing on an ongoing basis as an enterprise.
Markus Mayer
Two questions from my side. Firstly, again, on Q2, it’s a challenging Q2 ahead. Regarding the destocking we had in Q1, do you see that now this [indiscernible] has ended, and it’s basically the underlying demand has not yet started to recover? Or is it still going to be stocking you still see in Q2? That would be my first question.
And the second one is on the adoption of Verbund structure and will any kind of view on the timing of the plant closures. That’s all from my side.
Martin Brudermuller
Markus, the destocking, I mean, this is always difficult because you have to rely on that customer tells normally have to go into their shops and look how many pallets are in there.
As I mentioned already, I think on the chemicals raw material side, I don’t think that there’s so much as for destocking anymore into the customer industries. But I’m not so sure about the finished goods. And they have to flow also first before they are really the production. So I mean, I think in the consumer area, as I said earlier, I think it’s still a little bit above the normal average like is filled this is most probably also why it needs to really pick up again. And this is why we are a little bit cautious and have our question marks when it comes to Q2. It is not really super transparent in a moment that a little bit more prudent with my statements. What was the second?
Stefanie Wettberg
The of Ludwigshafen.
Martin Brudermuller
So I mean, I think we mentioned that basically, the last part will be in 2026, but there were some plants that are actually are down now. So CDI is down, ammonia is down, and that depends then on how you do that. But I would say the major contributions are basically down now.
April 21, 2023
SANITIZED AG completes EPA registration for
BBIT in the US
Burgdorf, April 20, 2023: Swiss-based SANITIZED AG receives EPA registration for Butylbenzisothiazolinone (BBIT) offering local stock availability to support the domestic market. BBIT is a best-in-class antimicrobial that provides effective protection against microbial attack, being a solution to degradation, loss of physical properties, and unpleasant odors.
BBIT is a powerful, safe, and versatile antimicrobial that has been designed to control the growth of microorganisms in a wide range of applications. It is highly effective and extensively commercialized in various formulations, including plastic compositions such as PVC, polyurethanes, silicone, polyesters, polyolefin, acrylics, rubber, etc.
“We are thrilled to be able to supply BBIT to the US market,” said Eduardo Costa, Head of Business Unit Polymers Additives of SANITIZED AG. “Over the last years we have invested and developed infrastructure to ensure continuity supply to the growing demand in the US. Furthermore, BBIT offers a safe choice for controlling the growth of microorganisms. The EPA registration is proof of the safety and effectiveness of our product, and we are confident that it will meet the needs of customers across the country.”
Sanitized has partnered-up with Urethane Sciences to supply BBIT to the polyurethane foam industry in North America. BBIT is available for purchase through our authorized distributor Urethane Sciences, in Berlin, NJ. For more information about the product, contact them at orders@usci.net.
Urethane Sciences LLC is an innovation partner, providing research and development, technical service support, supply of chemicals, and testing capabilities for the polyurethane foam comfort space. In our world class Berlin NJ facility, we work closely with our clients to design, create, prototype and support “top of the bed” products that create consumer value. Our extensive experience in providing solutions to problems now includes capabilities to bring a fresh, new relationship approach to improving understanding and application knowledge to the complex anti-microbial world. www.urethanesciences.com
Sanitized® adding value since 1935
Sanitized® enhances textiles, polymer products as well as paints and coatings. The company develops its innovative technologies in Switzerland and markets them worldwide. The Sanitized® additives ensure odor-free textiles, the responsible protection of paints and treat polymers permanently with a hygiene function and material protection. The all-embracing service for customers is unique: Standardized tests in the TecCenter, technical and regulatory advice, marketing support. Manufacturers and consumers have relied on the globally trusted Sanitized® brand for decades. It enables differentiation in the market and creates tangible added value for customers. www.sanitized.com
April 21, 2023
Good News on Inflation
Dan North | April 2023
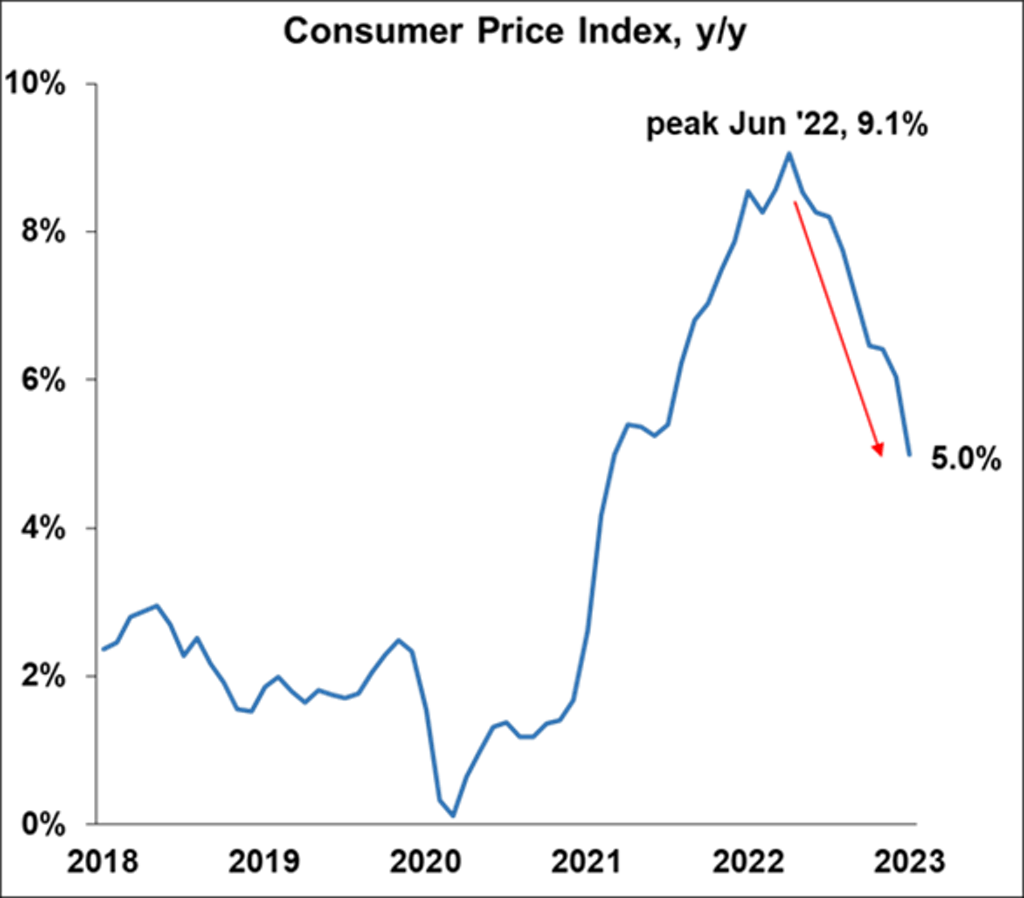
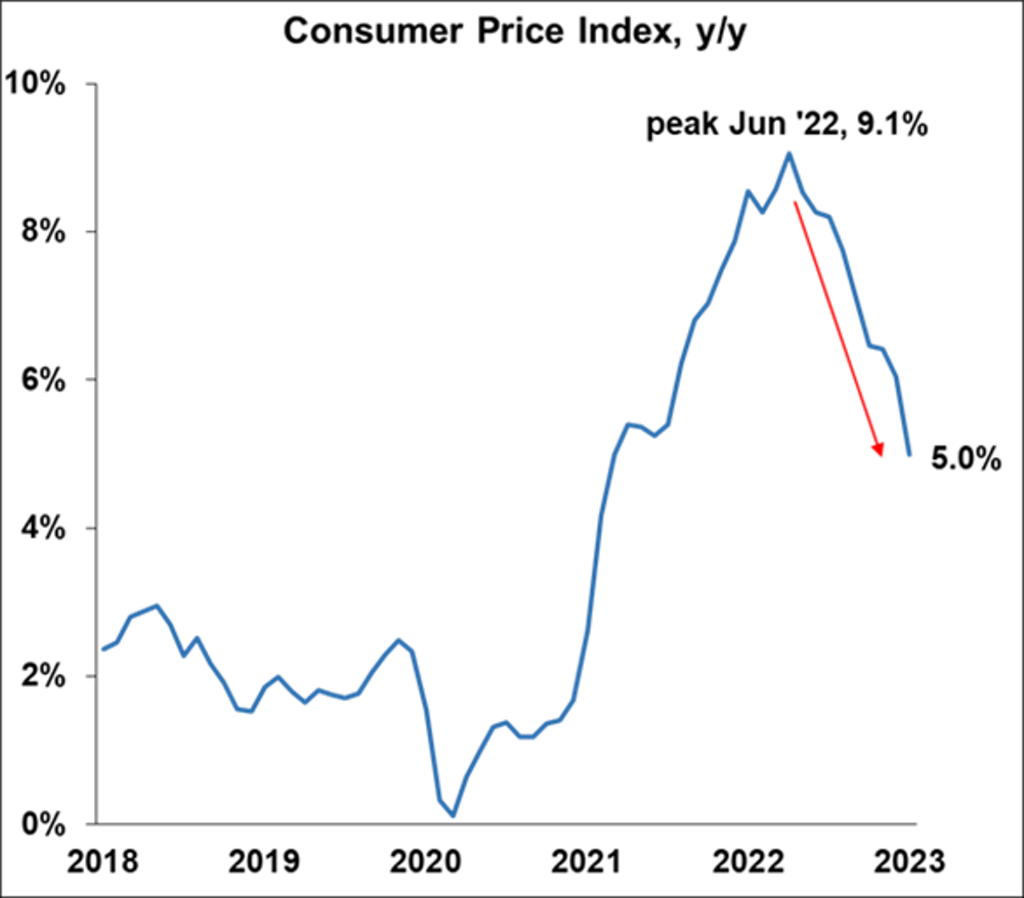
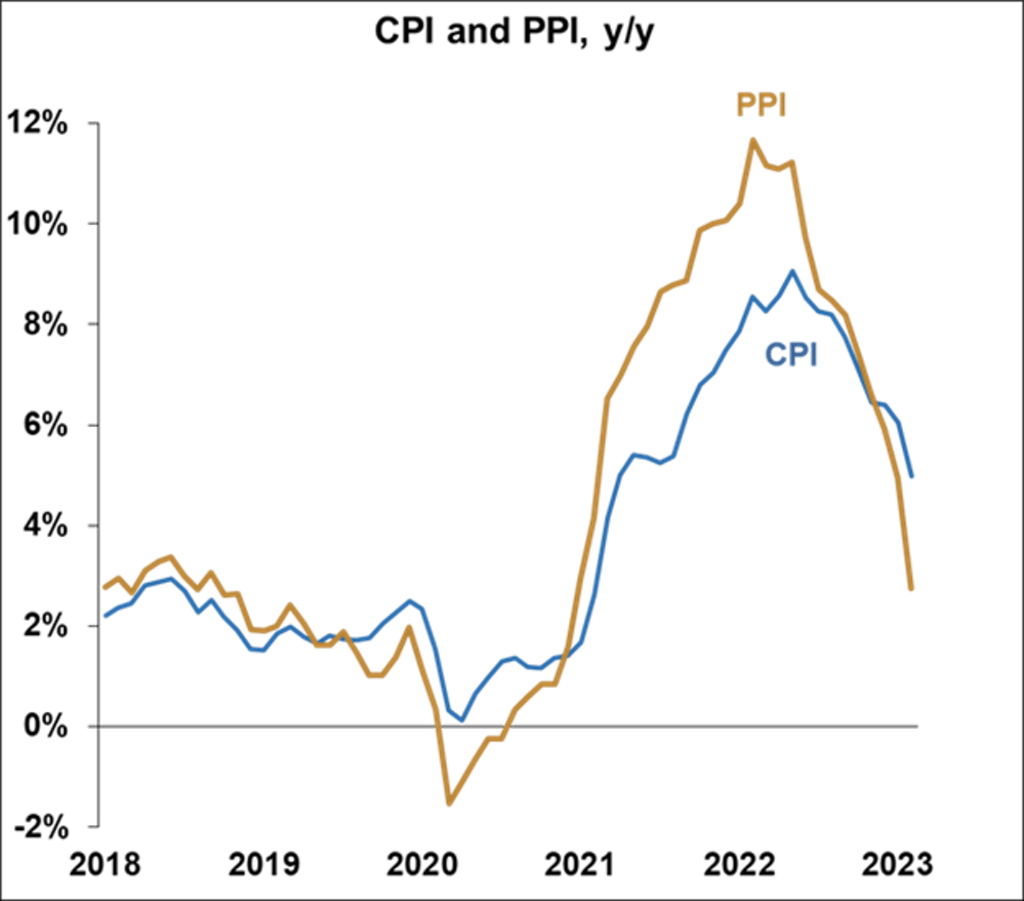
The Consumer Price Index (CPI) rose only 0.1% m/m in March, below expectations of 0.2%. Perhaps more importantly, the y/y rate fell a full 1% from 6.0% in February to 5.0% in March, the lowest since May of 2021. After stripping out volatile food and energy prices, the core rate rose 0.4% m/m putting the y/y rate at 5.6%. However, that’s just above last month’s 5.5% which was the lowest since the peak last September of 6.5%.
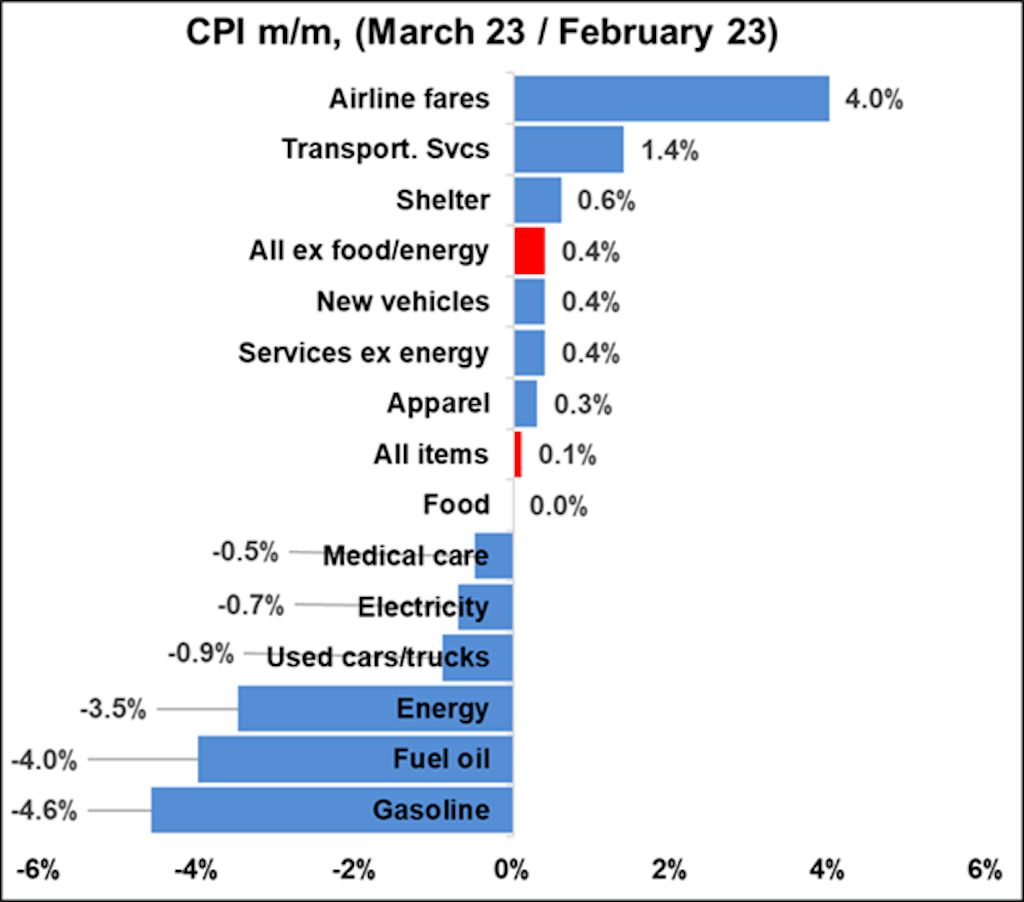
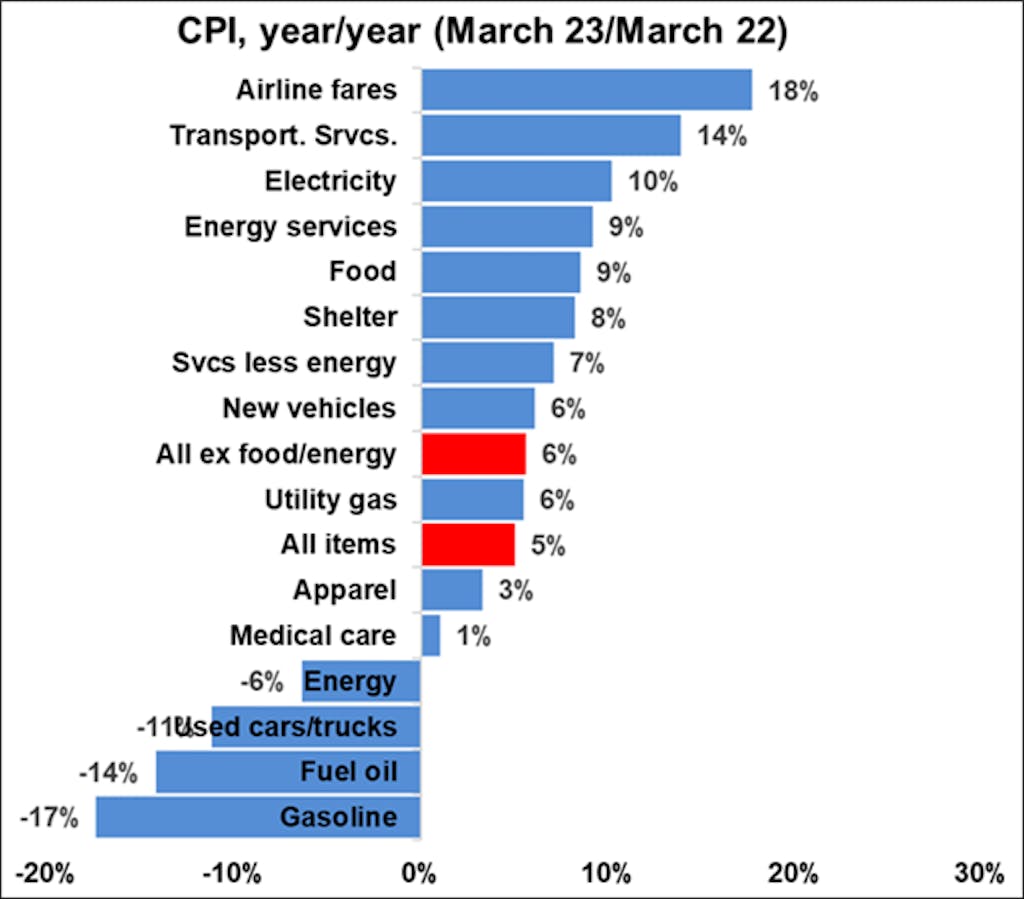
On a mm/m basis, gasoline fell the most, dropping -4.6%, while air fares rose a steep 4.0%. The y/y patterns were the same as gasoline fell -17% while airfares gained 18%.
The Producer Price Index (PPI), which measures the prices that producers receive for their goods and services, delivered very happy news. On a m/m basis, PPI plummeted a dramatic -0.5%, blowing past expectations of 0.0%. It was the biggest decline since just after the pandemic started in April of 2020. The results on a y/y basis were even more startling, nosediving from 4.9% in February to 2.7% in March. That’s a breathtaking descent in one month. Furthermore, over the course of the past year, the PPI has fallen a gigantic 9% from 11.7% last March. Progress is being made.
The core rate (Final Demand Less Foods, Energy, and Trade Services) also delivered inspiration, as the y/y rate fell from 4.8% to 3.7% Looking at the individual industries on a m/m basis, prices in the energy industry fell -6.4%, driven by a huge -11.7% drop in gasoline prices. Energy also had the largest decline on a y/y basis at -7.2% while construction gained an outsized 15.6% over the year.
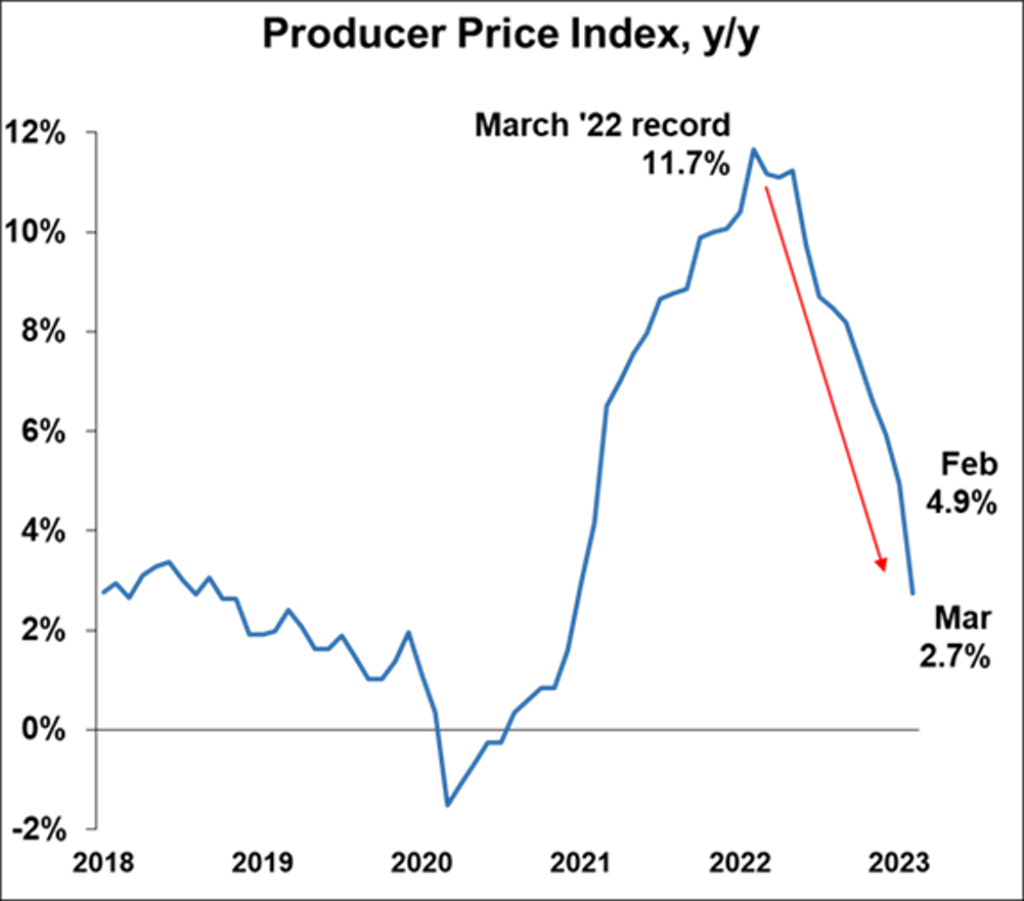
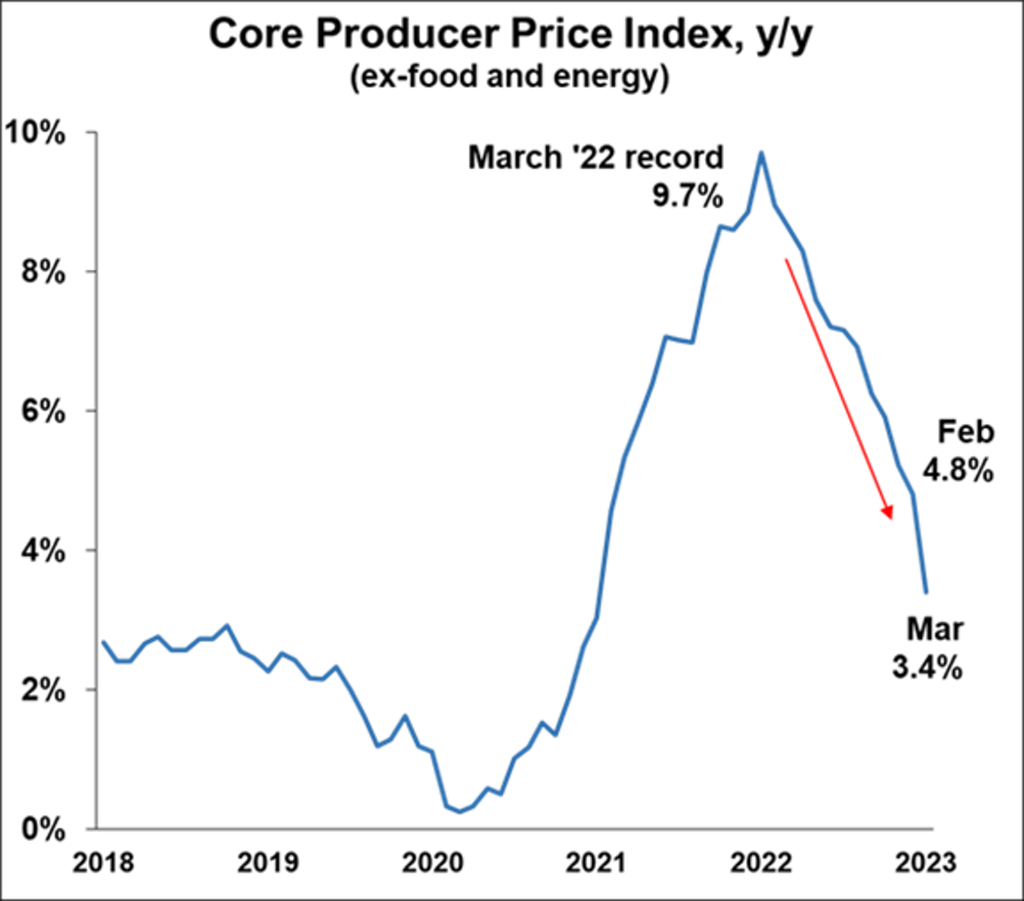
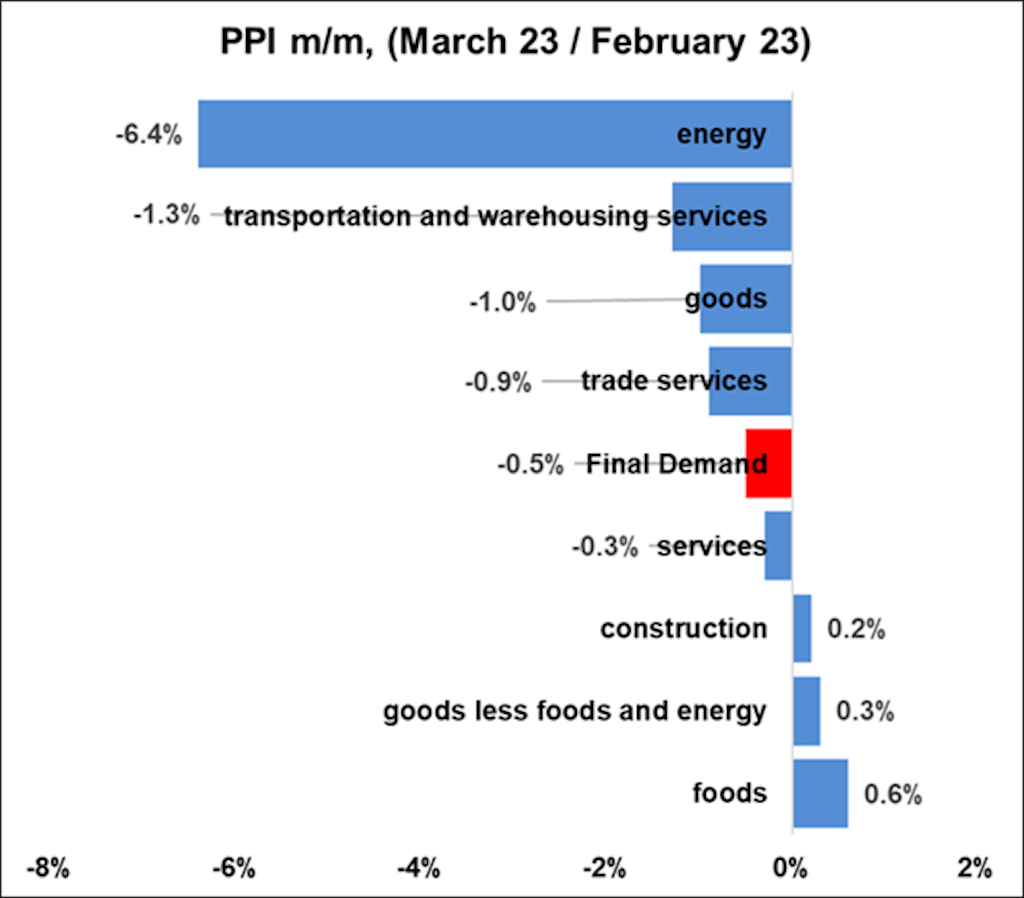
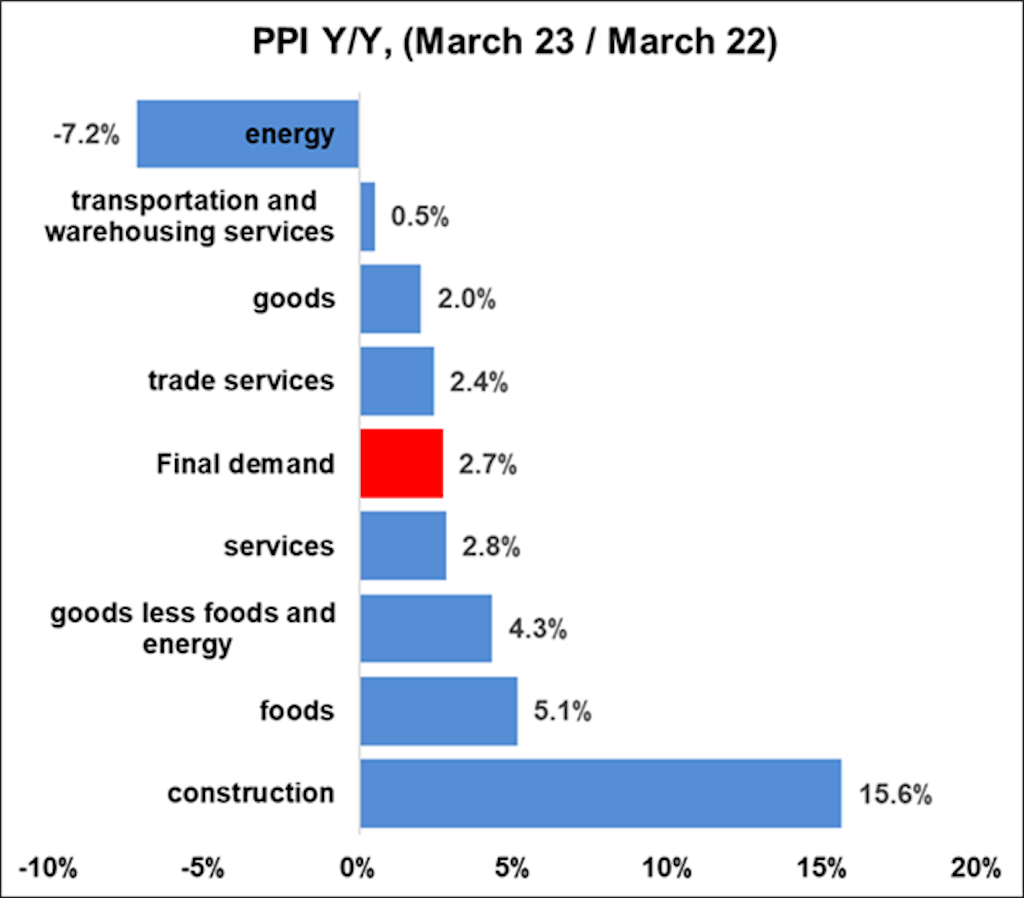
The sharp decline in the PPI y/y is significant because. As shown in the chart below the PPI tends to lead the CPI, suggesting that CPI is likely to continue falling as well.
https://www.allianz-trade.com/en_US/insights/good-news-on-inflation.html
April 18, 2023
“The Recovery Is On Track”: China Economy Rebounds Strongly With 4.5% GDP Jump In Q1
by Tyler Durden
Tuesday, Apr 18, 2023 – 05:58 AM
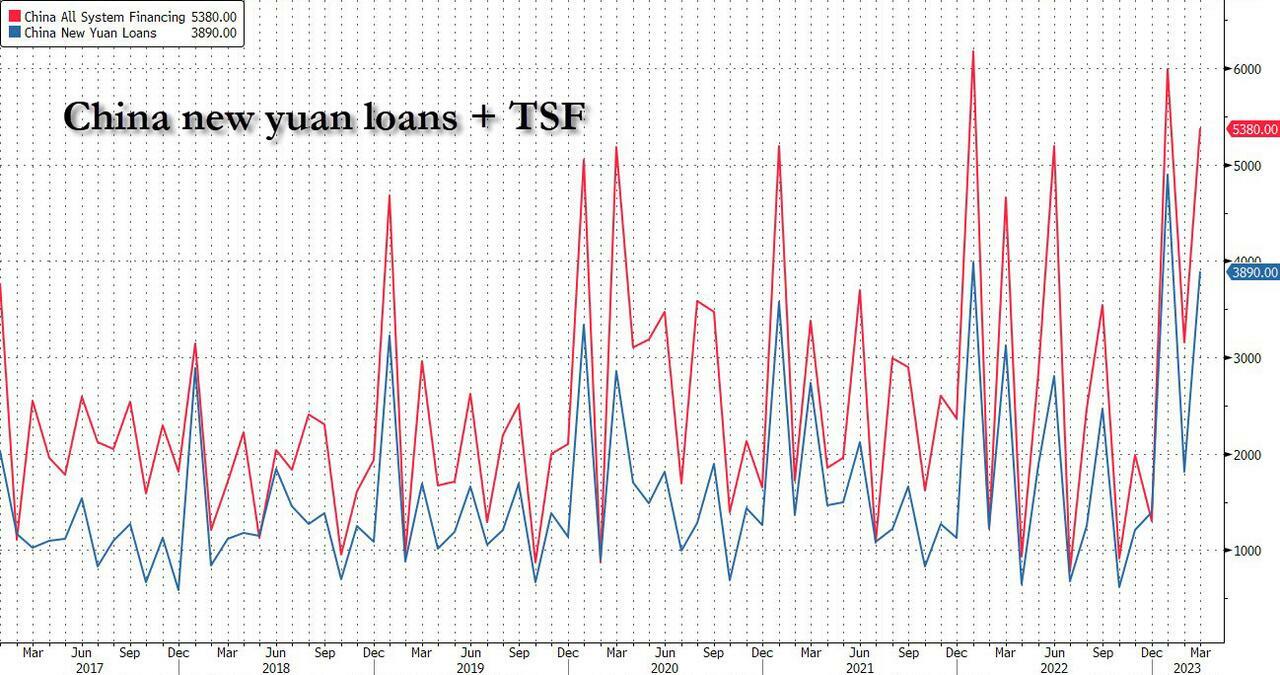
Last week, when discussing the latest record – for the month of March – Chinese credit injection which saw a massive 5.4 trillion yuan in Total Social Financing, beating estimates by almost CNY 1 trillion…
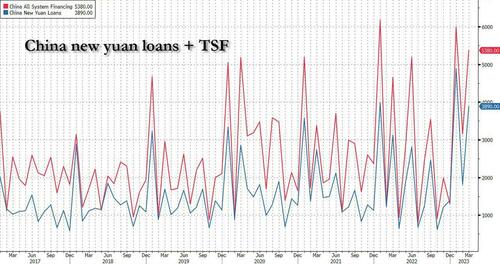
… and sparking a surge in China’s all-important Credit Impulse…

… we said that China’s delayed “liftoff was imminent”, and that “the 2008 deja vu meter just went off the charts, because while the US is about to sink into a recession with commercial real estate set to fall all off a cliff, it is once again China that is – willingly or otherwise – set to serve as the world’s growth dynamo at a time when the entire developed world is about to max out at the same time. This is precisely what happened in 2008 when China unleashed the biggest credit expansion in modern history, sparking not only historic growth spree but also an exponential debt increase that sent China’s debt to over 300% of GDP.”
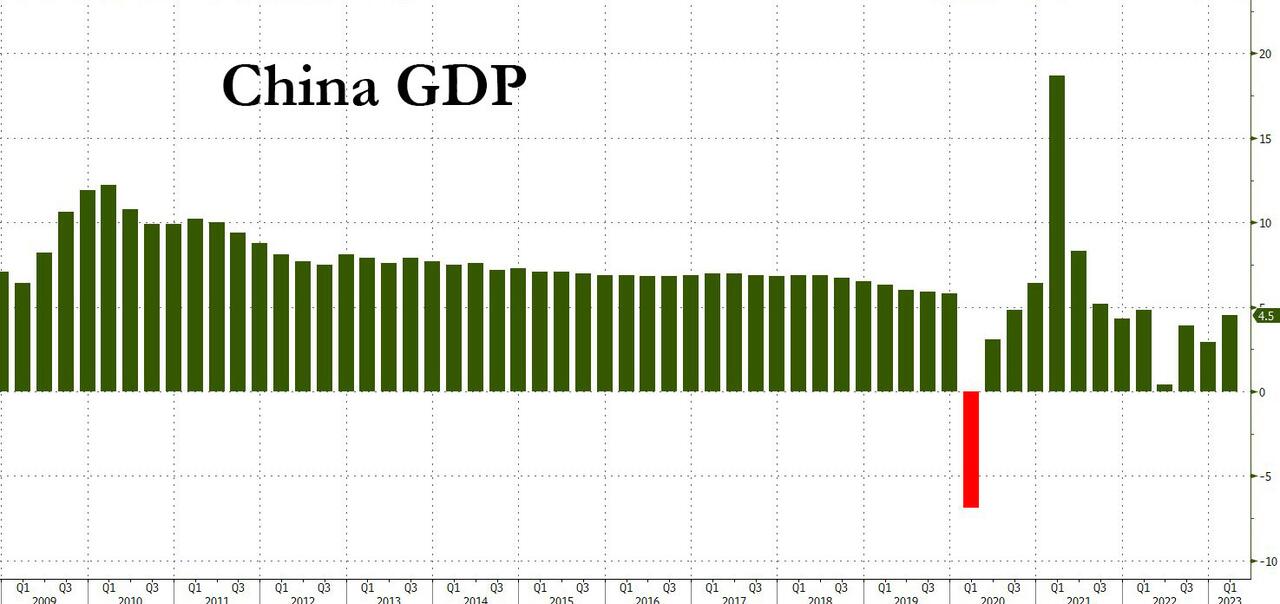
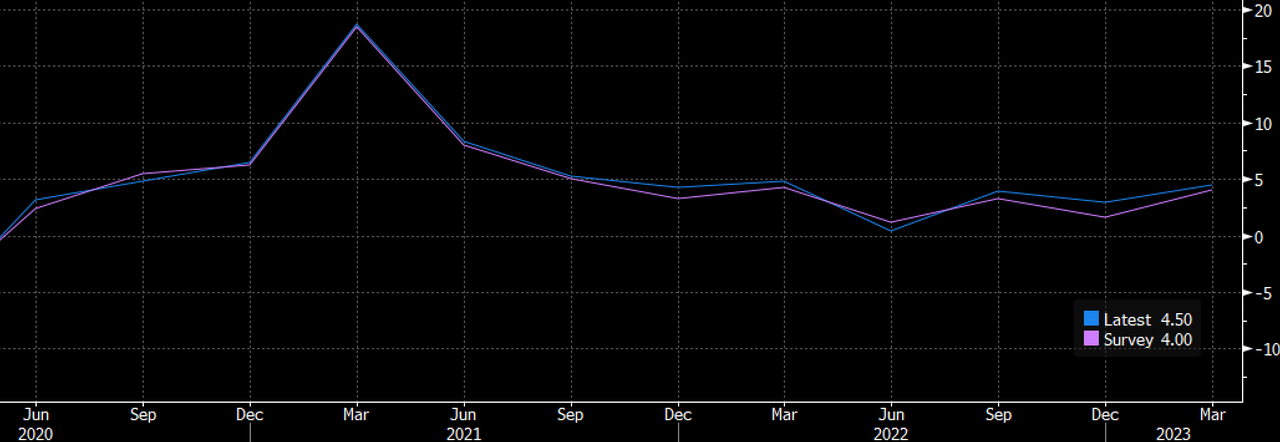
Since then, we have seen China report stellar trade data with both exports and imports sharply higher than expected, more solid real estate prints as housing prices have clearly rebounded from two years of decline, and most importantly, overnight China’s Q1 GDP also surprised to the upside, rising at a 4.5% annual clip in the first quarter – the strongest quarter for the Chinese economy since Q1 2022 – as strong growth in exports and infrastructure investment as well as a rebound in retail consumption and property prices drove a recovery in the world’s second-largest economy.
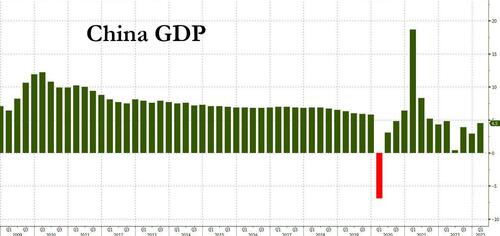
The official figure, which exceeded analyst expectations of a 4% rise and was the third consecutive beat of the median forecast…
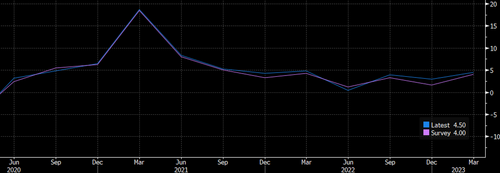
… followed efforts by Chinese leader Xi Jinping’s government to restore business confidence damaged by pandemic controls last year and abrupt policy changes.
That said, the Q1 growth rate was just short of the government’s recently upgraded full-year target of 5%, held back by a nationwide Covid-19 outbreak at the start of this year, but economists expect it to pick up pace as the year progresses.
Xi, who formally embarked on an unprecedented third term as China’s president last month, is keen to revive economic growth following China’s shocking reversal of its covid-zero policy. Last year, GDP expanded just 3%, missing the official target of 5.5% which was already the lowest in decades.
“Definitely, the recovery’s on track,” said Tao Wang, UBS chief China economist. “The momentum at the beginning of the year was stronger than expected.”
Echoing what we said last week, the FT writes that “China’s rebound is crucial to global economic growth this year as developed nations grapple with persistently high inflation, rising interest rates and sluggish expansion in the wake of the pandemic and Russia’s full-scale invasion of Ukraine.”
“The national economy showed a steady recovery and made a good start,” China’s National Bureau of Statistics said. But the agency cautioned the situation was “complex and volatile, inadequate domestic demand remains prominent and the foundation for economic recovery is not solid yet”.
Curiously, while Chinese commodities markets rallied following Tuesday’s data release, equities failed to hold on to early gains. That’s because the data may have snuffed out recent hopes that bad news is good news and would lead to more stimulus. As Bloomberg reports Sofia Horta e Costa writes, “It’s clear markets are setting a high bar for China’s economy. So China data beats estimates yet again, but hardly anything moves in local assets. What’s going on?”
In March I wrote about how some traders were betting on a consumption-driven recovery, and others believed more stimulus would be forthcoming. You were either in one camp or the other. The issue for markets right now is that the macro picture is falling somewhere in the middle. Yes, the data is good — in some ways much better than expected — but not good enough for bulls to make a compelling case for a reopening boom in the economy.
The rebound is fragile, with pockets of weakness including the property market and factories. It’s also uneven: consumers may be spending more but they’re mainly focused on restaurants and jewelry. And the central bank is erring on the cautious side of stimulus. The bar is increasingly getting higher for any meaningful market reaction. We either need a blowout set of data across the board or more action from Beijing.
Indeed, while the Chinese data has been strong so far, it is certainly not blowout, at least not yet.
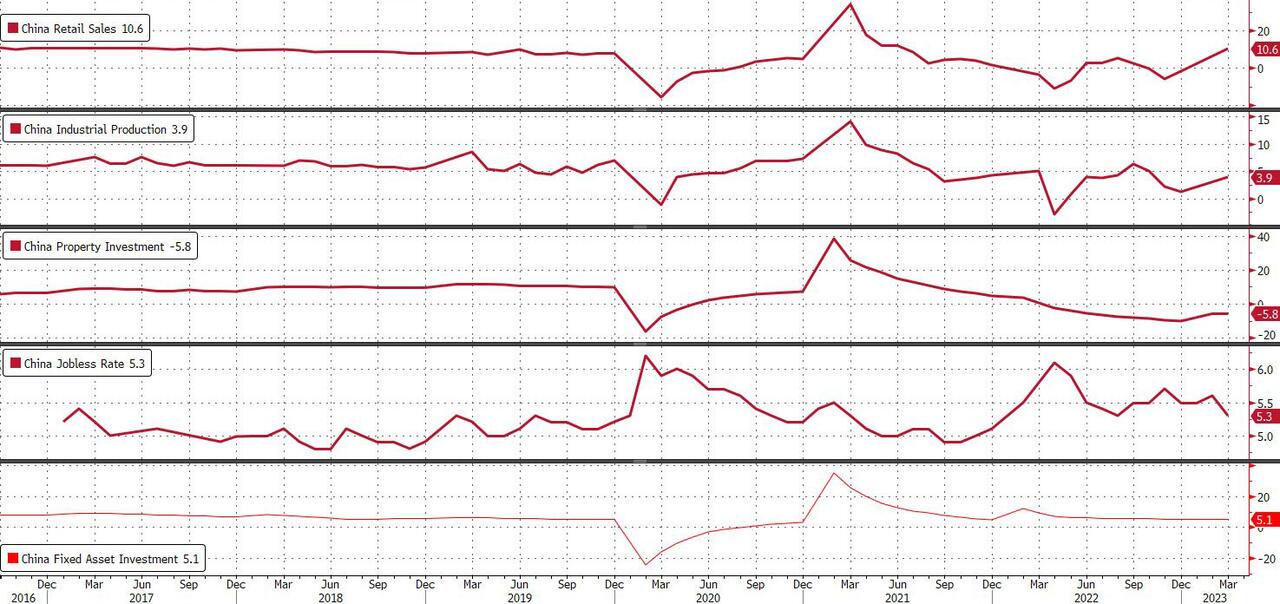
China abandoned zero-Covid restrictions in December amid popular opposition to the rolling lockdowns that paralyzed cities across the country for most of the year. The easing unleashed pent-up demand in the retail sector, where sales rose 5.8% year on year in the first quarter and 10.6% in March, both coming in well above expectations. But the base of comparison with last year was low, given that Shanghai started a months-long lockdown in late February 2022.
Premier Li Qiang, Xi’s new number two, signalled at China’s rubber-stamp parliament last month that the government would relax a crackdown on business that has wiped billions of dollars from property developers and internet platforms.
Elsewhere, manufacturing investment rose 7% year on year in the first quarter and industrial output gained 3%. Exports showed strong growth, up 8.4% in the first quarter, and state-led infrastructure investment climbed 8.8%, while overall fixed asset investment rose 5.1%, a modest miss to expectations. Private investment was weak, up just 0.6 %, suggesting a decline in March. The jobless rate fell to 5.3% in March from 5.6% in February, but youth unemployment hit the second-highest mark on record, at 19.6%.
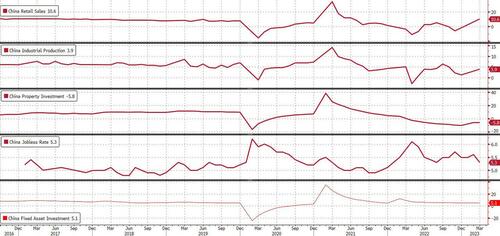
At the same time, while home prices may be rising, housing sector woes persisted: the property sector’s woes continued, with new housing starts tumbling 19.2% year on year in the first quarter. Home sales by area declined 1.8% but sales by value rose 4.1%, pointing to a nascent recovery in prices. Indeed, in March, new home prices rose at their fastest pace in 21 months.
Following the news, Citigroup economists upgraded their forecast for 2023 GDP growth to 6.1% from 5.7% previously after strong data Tuesday. “Consumption recovery continued to be divergent across sectors, with services outperforming,” economists led by Xiangrong Yu wrote in a Tuesday research note. “Normalization in savings and improvement in employment” has provided “potential upside”
The property sector also improved steadily in March compared to the first two months of the year, especially for sales. The growth pickup “perhaps further lowers the necessity of stimulus,” the economists wrote, adding that they “don’t expect anything major” in the upcoming April Politburo meeting. This year could be a “window of opportunities for policymakers to address structural issues, such as weak private confidence, youth unemployment and local government debt.”
Other economists also said momentum would pick up in the second quarter, helped by the low base effect, but warned that consumption and property might struggle to maintain strong growth, while exports could be threatened by weaker developed markets.
Xi’s administration also remained hamstrung by a lack of credibility after hobbling the private sector, experts said.
Keyu Jin, a professor at the London School of Economics and author of The New China Playbook, said the biggest obstacle was the gap in private sector demand, both in consumption and investment.
“It will take time for confidence to come back to the Chinese economy,” she said, although what she really meant is that it would take a lot of new debt and credit. And as we showed last week, Beijing is already injecting record amounts of it as it prepares to become the world’s growth pillar now that the US is set to slide into recession.
https://www.zerohedge.com/markets/recovery-track-china-economy-rebounds-strongly-45-gdp-jump-q1
April 18, 2023
Wanhua Chemical’s operating income at 41.939 billion Yuan and net profit at 4.053 billion Yuan in Q1 2023 Save Print 
Text size
| On April 14, Wanhua Chemical (600309) released the first quarter report of 2023, which showed that the operating income in the first quarter of 2023 was 41939325956.05 yuan, an increase of 0.37% over the same period of last year. The net profit belonging to shareholders of listed companies was 4053161512.31 yuan, down 24.58% on the year. The net cash flow generated by operating activities during the reporting period was 4166884642.68 yuan and the total assets were 237793786466.24 yuan. During the reporting period, the company’s operating income in the first quarter of 2023 was 41939325956.05 yuan, an increase of 0.37% over the same period of last year; the net profit belonging to shareholders of listed companies was 4053161512.31 yuan, down 24.58% year on year, mainly due to the decline in product prices and the reduction of gross profit. Wanhua Chemical is mainly engaged in polyurethane business, petrochemical business and fine chemicals and new materials business. |
https://www.ccfgroup.com/newscenter/newsview.php?Class_ID=600000&Info_ID=2023041830002
 Everchem Updates Archive
 Sign Up for Email Updates