
The Urethane Blog
January 25, 2023
Serta Simmons Files for Bankruptcy Amid Financing Controversy
Amelia Pollard and Luca Casiraghi
Tue, January 24, 2023 at 2:54 PM EST·4 min read
(Bloomberg) — The emergency funding that Serta Simmons Bedding received during the pandemic triggered a blowback that the company is still struggling to recover from.
The mattress manufacturer filed for bankruptcy on Monday, after clashes with lenders including Apollo Global Management Inc. left it with no other options for cutting its debt load while grappling with an economic slowdown that is crimping sales. Serta said the Chapter 11 filing will allow it to continue operating while it fixes its balance sheet, cutting debt to $300 million from $1.9 billion.
When the pandemic was raging in 2020 and the US economy had broadly shut down, Serta Simmons got $200 million of rescue financing to help it stay in business. The funding came from a group of lenders including Eaton Vance and Invesco Ltd., and featured a twist: the firms would be among the first in line to get repaid if the company failed.
Lenders excluded from that financing, including Apollo and Angelo Gordon & Co., responded by suing, arguing that other creditors had violated lending agreements by jumping ahead of them in the line to be repaid. Litigation tied to the transaction is still going on.
The mattress maker, assembled over a decade by private equity firms, faced heavy debt maturities this year. Alongside its Chapter 11 petition, Serta filed a lawsuit asking its bankruptcy judge to bless the 2020 financing that triggered litigation. Settling the fight over that deal is “critical” to the mattress maker’s restructuring, the company said in its lawsuit. The company’s planned deal is backed by a majority of lenders and shareholders.
Plan Details
The Serta litigation was the beginning of a series of clashes between lenders and companies with heavy debt loads that were struggling to navigate the pandemic. Creditors said that companies were pitting lenders against one another to get cheaper funding, and were hurting investors in the process.
Now Serta is trying to fix its financial difficulties with a bankruptcy plan that calls for repaying high-ranking lenders with new debt and stock in the restructured company, court papers show. Holders of more than $830 million of so-called first-lien-second-out debt are slated to get most of the company’s equity.
Loans pushed back in the repayment line in 2020 — more than $860 million of debt — would get a single-digit share of the stock in post-bankruptcy Serta. The plan also calls for paying the company’s continuing vendors in full, as long as they agree to favorable trade terms.
Nearly all of its top unsecured creditors are suppliers, with the top one listed owed more than $17 million, the filings show. The plan requires bankruptcy court approval and could change.
The creditor group has agreed to provide $125 million in the form of an asset-based loan to help the company fund itself in bankruptcy. Serta has also secured a commitment of $125 million in the same form once it exits bankruptcy.
The firm listed assets of $1 billion to $10 billion and liabilities in the same range in its petition. The company’s debt, which stems from a roughly $3 billion leveraged buyout by Advent International in 2012, has hobbled the retailer. Confidential talks over a restructuring plan started late last year, Bloomberg earlier reported.
Serta is working with advisers Weil, Gotshal & Manges, Evercore Group and FTI Consulting, according to the statement. Gibson Dunn & Crutcher and Centerview Partners are advising creditors, while Ropes and Gray are working with Advent.
Joining Forces
The mattress giant’s start can be traced back to the 1870s along the shores of Lake Michigan. There, Simmons first started producing coil spring mattresses, John Linker, the company’s chief financial officer, said in court papers.
The firm grew over the next century until it filed for bankruptcy during the fall-out of the financial crisis. Soon after, the firm combined with competitor Serta to establish the new company, Serta Simmons. In 2018, the company acquired Tuft & Needle, a maker of mattresses that get packaged in boxes and shipped directly to consumers’ homes.
Today, the firm is one of the largest mattress companies in the US, accounting for 19% of annual bedding sales, according to court papers. It operates 21 manufacturing facilities across the US and Canada and sells mattresses at 2,200 independent retailers.
But selling mattresses has grown more difficult, according to Serta. Rising interest rates have weighed on consumer spending, and the company has faced higher raw material costs and supply chain disruptions.
The case is Serta Simmons Bedding LLC, 23-90020, US Bankruptcy Court for the Southern District of Texas.
https://www.yahoo.com/now/mattress-maker-serta-simmons-files-044757930.html
January 24, 2023
Alantra advises Mearthane Products Corp. on a recapitalization by Compass Group Equity Partners
SECTORIndustrials
ServiceM&A
Dec 2022https://www.alantra.com/ib-transaction/mearthane-products-corporation-sell-side-advisory-compass-group-equity-partners/

Sell-side advisory

Boston – Alantra, a leading global investment bank and asset management firm, is pleased to announce that Mearthane Products Corporation (“MPC”), a leader in proprietary, branded urethane-based technology, has been recapitalized by Compass Group Equity Partners (“CGEP”). The deal closed on December 23, 2022, and financial terms were not disclosed.
Founded in North Providence, Rhode Island, in 1965, MPC is a leader in the development and manufacture of polyurethane elastomers with a specific focus on advanced thermoset products for use in high performance applications. With an emphasis on urethane technology, partnership, quality, and community, MPC produces high performance parts including belts, rollers, wheels, seals, and enclosures for diverse end markets such as medical & analytical testing, digital printing, vehicle platforms, and sports & recreation.
“We are very pleased with Alantra’s teamwork and guidance throughout this process,” said Kevin Redmond and Peter Kaczmarek, the shareholders of MPC. “Alantra was a committed advisor from start to finish, and clearly delivered on our objective of finding a partner for the next chapter of growth for MPC.”
Paul Colone, Managing Director & Partner with Alantra, said, “We are very pleased to deliver on the MPC shareholders’ objectives to form a new partnership to support their active pipeline of M&A and organic growth opportunities. We have a very active practice in Specialty Materials and MPC meets the definition in every respect due to their focus on developing technical solutions for high performance applications.”
Alantra Director Jon Tetirick continued, “MPC has found an excellent partner in CGEP and we look forward to following the new owners as they continue to execute on MPC’s M&A add-on strategy in what is sure to be an exciting and rewarding future ahead.”
MPC represents another strong credential supporting Alantra’s expertise with Specialty Materials and Industrials. In addition to Mr. Colone (Boston), and Mr. Tetirick (Boston), the Alantra team advising MPC included Sam Worley (Associate, Boston), and Alif Kanji (Analyst, Boston).
www.alantra.com/what-we-do/investment-banking/transactions/?sector=industrials
Read more here: https://www.cgep.com/news/2023/compass-group-announces-strategic-partnership-with-mearthane-products-corporation
January 24, 2023
The owners of Universal Polymers Corporation (A division under General Coatings Manufacturing
Corporation) would like to announce appointment of Mr. Deepak Mittal as the new President of
Universal Polymers Corporation (UPC).
Deepak Mittal has been involved with the American Polymers Corporation for the last 34 years. He
held various leadership roles including President of Ultimate Linings from 2008-2017. Since 2017
he has been Executive Vice President at UPC helping it grow to be a large spray foam systems
house.
“I am honored and thrilled to be named President of UPC and to continue
the vision of our founder, Lax Gupta. It is an exciting time for UPC since we
are uniquely positioned as one of the few family-owned businesses to
remain in our industry. We currently have and are continuing to build an
extremely talented team who is focused on putting our customers first. UPC
is making continuous strides to offer the highest quality products in the
industry.” – Mittal
January 22, 2023
Leggett & Platt: Sturdy Foundation But Underwhelming Projections
Jan. 21, 2023 1:19 AM ETLeggett & Platt, Incorporated (LEG)2 Comments
Summary
- Leggett & Platt maintains a stable performance despite the softening of demand.
- Its liquidity stays decent, allowing it to sustain its capacity and potential headwinds.
- Projections may not be as exciting as they were in 2022.
- Dividend payments are enticing, given the growth and yield.
- The downward momentum of the stock price remains visible but acceptable.
With over a hundred years of existence, Leggett & Platt, Incorporated (NYSE:LEG) has been through a lot of crests and troughs. It has withstood various market challenges, making it a durable industry staple. In the last two years, it has stayed stable and flourishing amidst changing market dynamics.
Today, Leggett shows well-balanced growth and fundamental stability. The demand has softened, but revenues and margins are still manageable. Lower revenues may be anticipated as market demand cools down. Thankfully, furniture companies, including LEG, have already shown inventory recovery. Supply catches up with demand, so inventory management may become easier. Also, it maintains a decent liquidity position to suffice its operational capacity. It derives adequate core operating returns to cover borrowings. As such, it can sustain itself without raising its financial leverage further.
Moreover, the company remains consistent with dividend payments, making it one of the Dividend Champions. However, the stock price seems too high for fundamentals and does not reflect its intrinsic value.
Company Performance
The past two years had caused dramatic changes in the furniture and home furnishing industry. After suffering from pandemic disruptions that limited its operations, its performance spiked in just a year. It has remained an industry staple with solid market positioning. Thanks to lower prices, remote work setups, and the massive shift in consumer behavior. The real estate market boom also drove its growth. As more houses were bought, furniture and fixtures followed the trend. Today, Leggett & Platt keeps stable core operations amidst the current market patterns.
The operating revenue amounts to $1.3 billion, a 2% year-over-year decrease. Several factors contribute to this downtrend. First, the impact of inflation has been reflected. In 2022, we have seen how inflation peaked and set a new forty-year all-time high. It affected the purchasing power of many customers, especially in the US and Europe. Also, the skyrocketing fuel prices made it more challenging to transport raw materials and process products. Even more noticeable is that other countries reacted slower to inflation than the US. As we can see, the US inflation lull began in 3Q 2022. In Europe, inflation has just started to cool down. So the impact of the rising prices in LEG’s international markets remains keenly felt. It is not easy for consumers to adjust to price changes, putting downward pressure on the demand.

We can also attribute it to the cooling home demand. Home sales have slowed down in the last year. It has become more evident in the second half. In turn, the demand for furniture and home furnishings was impacted. Auto demand also showed a slowdown. Both these segments were vital for Leggett.
Despite this, Leggett now still exudes operational stability. It is an attribute an investor must watch. Indeed, it continues to stand the test of time. One way is through its pricing. It remains capable of making up for the lower demand by imposing strategic prices. These appear effective and flexible to market changes.
Moreover, LEG keeps concentrating on aspects it can manage and enhance. First, we can see it in its inventory adjustments. Supply chain bottlenecks have become one of its problems in the last two years. But we can now see a substantial improvement in its inventory levels. This move is in line with the market. It gives them increased flexibility in pricing and cost-reduction management. It has delivered its backlog, helping it through drastic business cycles. Its backlog delivery has been solid, but now, we can see its end. It is no wonder, the industry, including LEG, is starting to return to a normal business flow. Supply is catching up with market demand, so the company is regaining its stride. Although sales are lower, its supply chains are improving. It will help the company maintain a balance in revenue and margin stability.
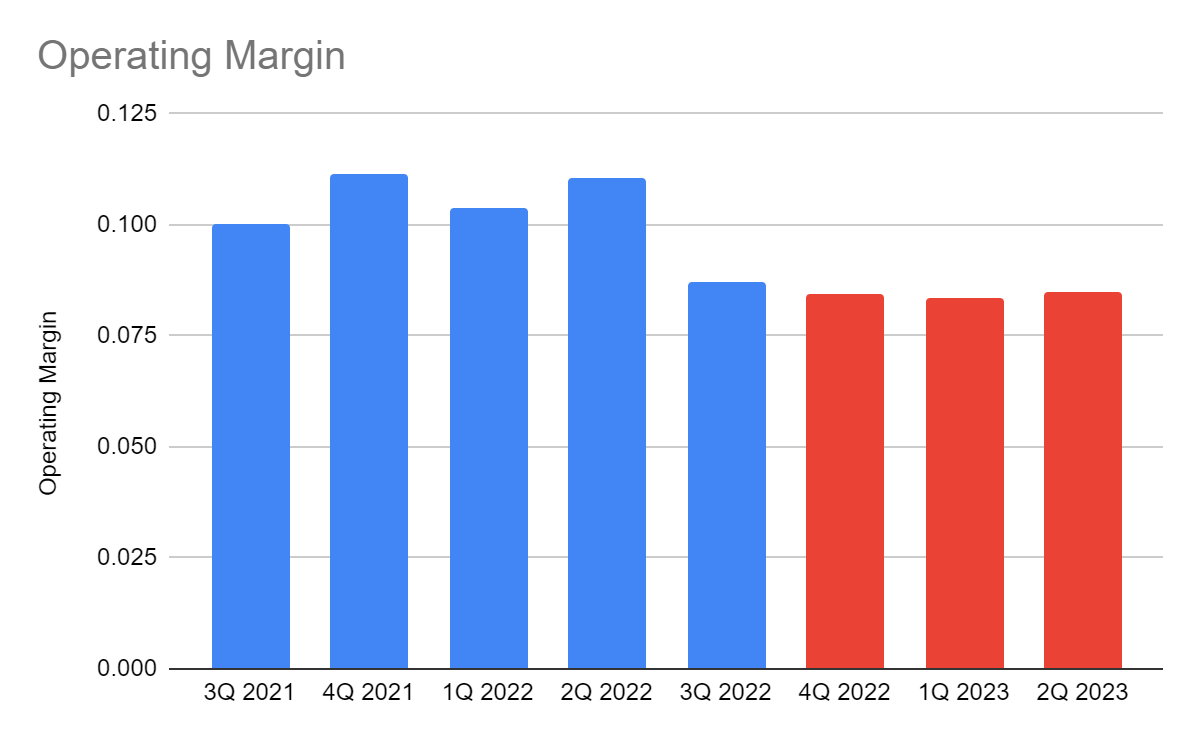
Meanwhile, operating costs and expenses are well-managed despite the high-flying prices. The efficiency of the company is helping it partially offset the revenue decrease. Although it is insufficient, the core operations remain stable and viable. Despite some demand slowdowns, the swift supply chain recovery helps enhance operational efficiency. The operating margin is relatively weaker in sequential values. But it stays decent at 8.7%, down from 10% in the comparative quarter.
This year, I expect more normality in business flows. Seasonality may also return and become a prevalent factor. Near-term performance may not be as robust as in 2021 and 2022, but stability may remain. As the inflation lull continues, producing, transporting, and transporting raw materials and finished products may be less expensive. As LEG regains a grasp of its supply chains, it may keep improving its cost-reduction strategies. It may be more agile in setting optimal prices. I expect growth to cool down, but core operations may stay manageable. I also expect the first-half revenues to decrease more. Even so, expect the operating margin to stay near its current level as costs and expenses decrease. It is a combination of lower inflation and the production volume adjustment of Leggett & Platt. But it may have to work more on advertising to secure its place in the market.
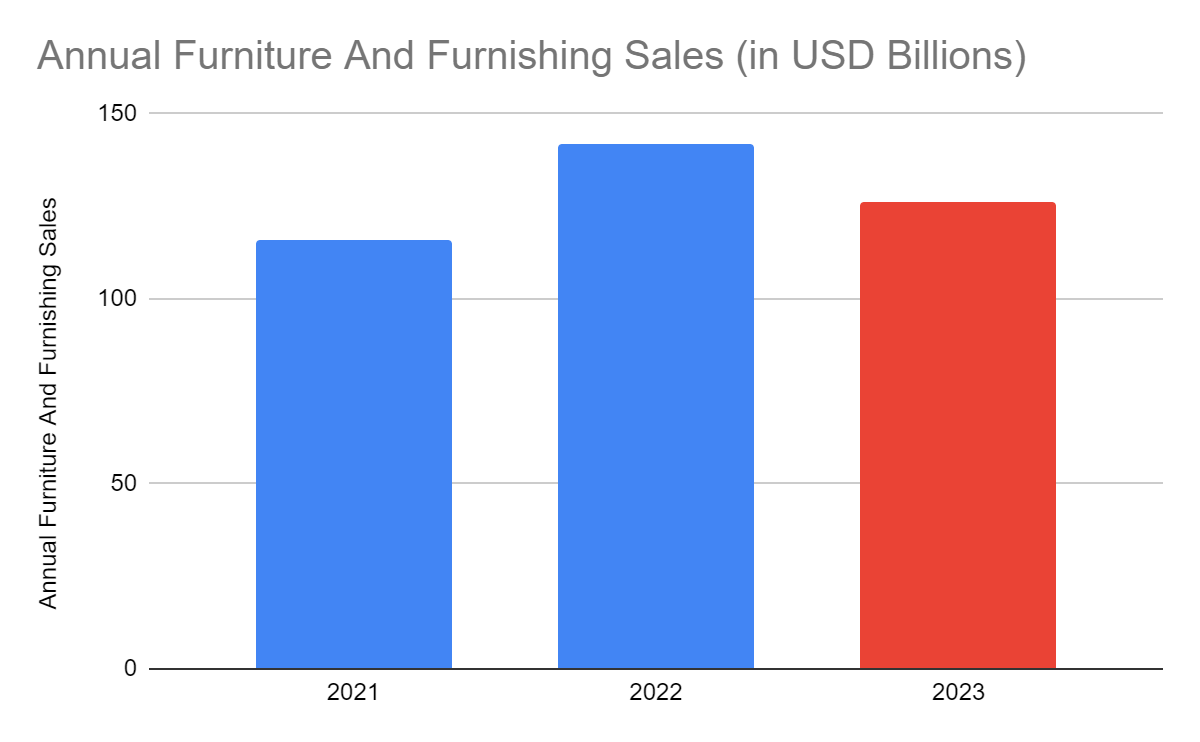
What’s important is that LEG stays consistent with the market trend. As of this writing, the 2022 US furniture and home furnishing sales are 1.6% higher than in 2021. November and December sales are not included yet, so the total value may reach $142 billion. Despite this, the recent market demand and volume trend are in a downtrend and may persist in 2023. Its value may decrease further this year but may stay elevated. But of course, LEG and the whole market must not be complacent. The increased presence of smaller retailers and the rise of e-commerce may become other hurdles.
How Leggett & Platt Can Sustain Its Operations
Leggett & Platt has always been one of the most indelible figures in the industry. In its long existence, it has maintained operational stability, making it a secure investment. Yet, market dynamics are changing and may become underwhelming this year. The consolation we have now is that inflation keeps decreasing, so I expect interest rate increments to cool down. I am not discounting the potential recession, though. Despite this, I am more optimistic since the recent changes are part of economic recovery. The unemployment rate remains manageable and low. Income levels are higher today. Business reopenings and capital inflows may continue.
But what makes LEG durable despite the underwhelming expectations is its market and financial positioning. The decreasing inventory level can help it cope with cooling demand. It can help improve operational efficiency to stabilize margins. Even better, it maintains adequate cash levels. The only worry we have now is the substantial increase in borrowings. It is still understandable since interest rate hikes make borrowing costs higher. But it must be more careful to maintain adequate liquidity. Thankfully, the company is still earning enough to cover borrowings. The Net Debt/EBITDA Ratio remains acceptable at 3.7x. It is lower than the maximum ratio of 4x, especially since LEG is a capital-intensive company.

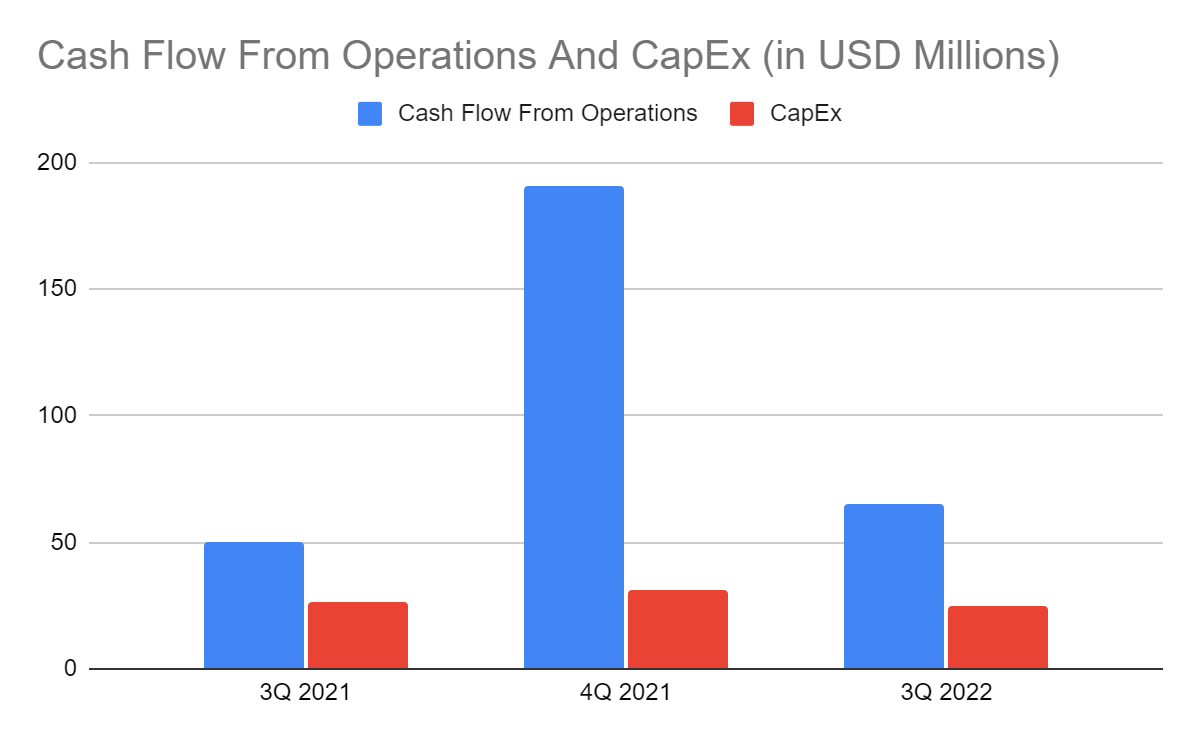
The cash flow of the company can confirm its liquidity. Its operating cash flow of $65 million is more than twice as much as its CapEx of $24 million. With that, it has a remaining amount of $41 million. Its FCF can repay near-term borrowings and dividends. It also has enough cash to preserve its intrinsic value by repurchasing shares.
Stock Price
The stock price of Leggett & Platt remains in a downtrend. It does not convey any upside or reversal potential. At $33.46, it remains 11% lower than its value last year. But it appears reasonable as some price metrics show. Using the current price-earnings multiple of 12.7x and my estimated EPS of $2.32, the target price is $29.46. NASDAQ has a more optimistic view with an estimated EPS of $2.36, but the target price is still low at $29.97. There may be a 10-12% potential downside. The estimation using the EV Model ($6.64 B – $2.51 B) / 132,619,000 shares agrees with it with $31.37 as the target price.
Meanwhile, dividends stay enticing with yields of 5.15%. It is way better than and more than thrice as much as the S&P 400 average of 1.54%. What’s more interesting is its consistent dividend growth for about fifty years, making it a part of the Dividend Champions. The only concern we have is its Dividend Payout Ratio of 74%. To assess the stock price better, we will use the DCF Model.
FCFF $299,000,000
Cash $226,000,000
Borrowings $2,820,000,000
Perpetual Growth Rate 4.8%
WACC 9.2%
Common Shares Outstanding 132,619,000
Stock Price $33.46
Derived Value $31.68
Bottomline
Leggett & Platt remains a secure and stable company. Growth may not be exciting but fundamental soundness remains evident. Dividend payments are consistent with high yields while staying well-covered. However, the stock price remains in a downtrend but still appears overvalued. The recommendation, for now, is that Leggett & Platt is a hold.
This article was written by

Investigating The Stock Market
770 Followers
January 20, 2023
December trailer orders 2nd highest on record
Catch-up of suppressed orders skews bookings in last month of 2022
· Thursday, January 19, 2023

Listen to this article
0:00 / 2:52BeyondWords
Trailer manufacturers posted 57,300 orders in December, the second-highest monthly intake since ACT Research began tracking in 1996. The volume appeared to be a catch-up after OEMs blocked many orders from April to August because they lacked pricing visibility.
“I cannot speak for other OEMs. However, our higher booking in December was driven by the later opening of the order books as we awaited required quoting information from the supply base,” Sean Kenney, chief sales officer for Hyundai Translead, told FreightWaves.
“Hyundai Translead is anticipating continued higher-than-normal orders for the next few months as we work through the impact of this.”

December net U.S. trailer orders came in 46% higher compared to November and 115% above December 2021, ACT Research reported. The highest month on record was September 2018, with 57,800 net orders.
Some manufacturers report that the supply of parts has deteriorated despite their acceptance of the huge number of December orders.
Lingering supply chain concerns for future trailer orders
“Supply-chain concerns still linger,” with no short-term improvement in sight, Jennifer McNealy, ACT director of commercial vehicle market research and publications, said in a news release. “Regarding demand, most trailer makers continue to see demand exceeding capacity through the end of 2023.”
One major OEM, Wabash, announced a long-term supply agreement Jan. 10 with J.B. Hunt Transport covering up to 15,000 trailers over the next few years.
Some OEMs mentioned an erosion in confidence to ACT, but so far it is not showing up in order cancellations.
Mike Baudendistel, a FreightWaves market expert, expressed surprise at the order volume in December.
“It could be some makeup orders to compensate for the supply constraints the past couple years,” he said. “I would think the orders were even more heavily weighted toward the large enterprise carriers than they usually are since they are well capitalized and their business holds up better in a weakening market.”
Total net orders placed in 2022 were 361,500 compared to 249,400 in 2021. The industry produced approximately 306,000 trailers in 2022.
“Our projections point to a continuation of that upward trend into 2023,” McNealy said.
 Everchem Updates Archive
 Sign Up for Email Updates