
The Urethane Blog
March 31, 2026
Saudi Aramco-Dow JV suspends chemical output amid regional disruptions
Mar 31, 2026, 3:45 PM ETDow Inc. (DOW) Stock, ARMCO StockBy: Rob Williams, SA News Editor
A major petrochemical facility in Saudi Arabia operated by a partnership between Saudi Aramco (ARMCO) and Dow (DOW) temporarily stopped production, underscoring how escalating tensions in the Middle East are straining industrial activity and supply chains.
Sadara Chemical Co. confirmed that operations at the complex have been paused, though it didn’t provide a timeline for restarting production, Bloomberg News reported Tuesday. The company said any resumption will depend on both domestic conditions and broader international developments.
The shutdown highlights the growing impact of the Iran conflict on energy infrastructure across the region. The Strait of Hormuz, a critical artery for global energy trade that typically carries roughly 20% of the world’s oil and liquefied natural gas, remains largely obstructed, complicating exports.
Saudi Arabia has already reduced crude output, and alternative logistics are being stretched. A pipeline network connecting eastern production hubs to ports on the Red Sea is reportedly operating at maximum capacity, providing a partial workaround for shipments.
The Sadara complex, a roughly $20 billion investment, is designed to produce about 3 million metric tons of plastics and specialty chemicals annually. Saudi Aramco has previously positioned the facility as a cornerstone of its strategy to diversify revenue by converting crude oil into higher-value products.
March 31, 2026
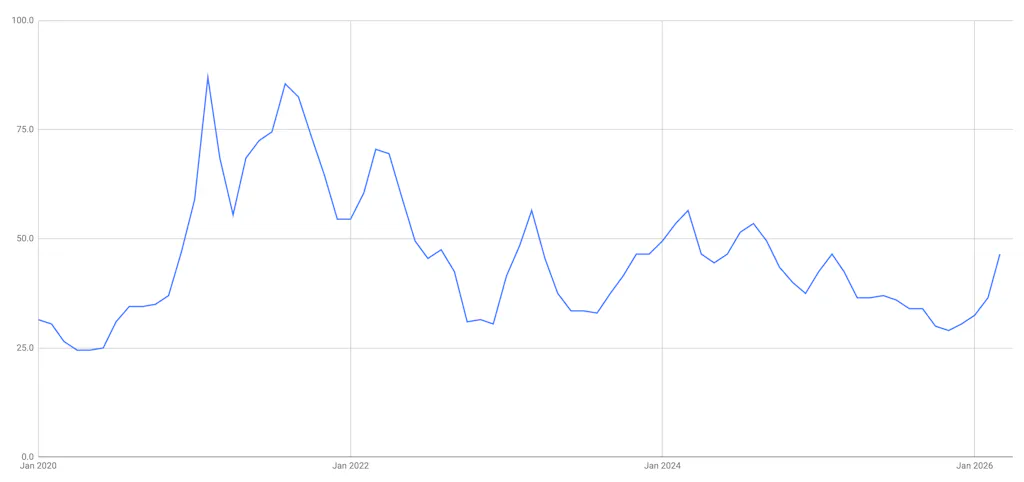
Chemical Grade Propylene is $0.465/lb in March 2026. Up 10cpp from February.
March 24, 2026
Stepan Announces Increases

https://www.stepan.com/content/stepan-dot-com/en/news-events/pricing-announcements.html
March 23, 2026
National trucking capacity is about to tighten significantly
· Sunday, March 22, 2026

The freight market momentum is building at a rapid clip. National dry van spot rates — tracked via the SONAR National Truckload Index (NTI.USA), the 7-day moving average of booked rates including fuel — have broken out to a new cycle high of $2.89 per mile. This represents the strongest level since 2022 and confirms the market’s shift toward carriers is gaining real traction.

Chart: SONAR National Truckload Rate Index (NTI.USA) GoSONAR.com
Even more telling: rates jumped $0.12 per mile in the past week alone. That’s a sharp weekly gain that underscores accelerating tightness and carrier pricing power. Spot rates have now recaptured roughly $0.50–$0.60 per mile net of fuel over recent months, climbing from the low $2.00s that defined much of 2023–2024. We’re witnessing 20–25% year-over-year recovery in key lanes and metrics, with volumes holding at multi-year highs reminiscent of late 2022.
This isn’t isolated noise — it’s driven by fundamentals. The return of industrial demand remains the core engine, with stronger manufacturing signals, flatbed activity, and overall domestic freight resilience putting sustained pressure on a shrunken truckload supply. Multi-year carrier attrition (exits, driver regulations, and structural challenges) has left capacity thin, making the market highly responsive to any demand pickup. National tender rejection rates sit stubbornly in the low-to-mid teens (around 13–14% recently), with the Midwest still leading above 18% and tightness now spreading more broadly.
Seasonal layers are piling on:
- Produce season is ramping in major growing regions.
- Construction is accelerating as weather improves.
- Gardening and home improvement demand is building.
- Beverage season is gearing up for warmer months.
These verticals compound the industrial rebound, further squeezing available trucks.
The West Coast awakening adds a powerful pull. Chinese New Year landed later this year (February 17, 2026, vs. earlier in prior cycles), prolonging the post-CNY slowdown and keeping Southern California unusually loose into early March (outbound rejections below 5%). But the rebound is hitting hard now: inbound containers are surging, outbound tenders are recovering, and rejections are set to rise meaningfully.

This creates a classic “magnet” for capacity. Long-haul carriers chase West-to-East port loads for their superior length of haul (1,500–2,000+ miles per move) versus shorter eastern runs that demand multiple loads for equivalent paid miles. As trucks reposition westward from Midwest/Southeast corridors (along I-35 and parallels) to capture higher-paying outbound freight via I-20 and I-40, interior markets face no relief — expect even tighter conditions back east. The Midwest’s industrial strength and elevated rejections mean any capacity drain will intensify pressure, not ease it.
Broader indicators align:
- Tender rejection rates remain high nationally, with seasonal builds accelerating the spread.
- Dry van spot rates continue rising on resilient volumes and persistent constraints.
- Ocean bookings are starting to recover sharply from Chinese New Year
The bottom line: Spring 2026 is igniting hotter and earlier than recent years. The $2.89 cycle high — fueled by a $0.12 weekly jump — reflects tightening capacity, resurgent industrial demand, seasonal verticals firing up, and the delayed-but-powerful post-CNY import surge creating synchronized tightness. Shippers unprepared for higher costs are under immediate strain, with routing guides tested early. Carriers positioned for West Coast outbound, industrial, and seasonal lanes are capturing the gains as capacity reallocates — but back east, conditions are set to tighten further as carriers shift their focus towards the West to East longhaul.
Monitor SONAR outbound rejections and spot rates from Southern California over the next 2–4 weeks, alongside Midwest/Southeast trends. The speed of this spread will show how broad and sustained the impact becomes.
The spring shipping season is just getting started — and it’s going to be a hot one.
March 23, 2026
BorsodChem Announced Price Increase for All MDI Products Supplied April 2026 Onward
March 20, 2026 1 min read
On March 19, 2026, BorsodChem announced a price increase of €500/MT for all MDI products, effective immediately or as contract terms allow. The price adjustment is necessitated by recent developments in the Middle East, which have caused sharp increases in European natural gas and other raw material costs. Despite the company’s efforts to manage this situation responsibly, it is unable to absorb the escalating costs.
 Everchem Updates Archive
 Sign Up for Email Updates