
The Urethane Blog
April 12, 2026
First Quarter Transactions

2/4/26
Stahl
(68.5% stake fromhttps://www.pnc.com/en/corporate-and-institutional/topics/specialty-segments/chemicals-and-plastics.html?WT.mc_id=CIB_Offline_0065
Wendel; 16.1% from
BASF SE; 14.6% from
Clariant AG)
Henkel AG & Co.
KGaA
EUR 2.1B –
- Henkel AG & Co. KGaA has agreed to acquire Stahl, a Netherlands-based producer of
high-performance specialty coatings for flexible materials, serving companies across
the automotive, fashion & lifestyle and packaging markets. Stahl’s portfolio consists
of leather finishing coatings, performance coatings as well as high-performance
paper packaging & graphics coatings. - “With the acquisition of Stahl, we will further strengthen our Adhesive Technologies
business unit in line with our strategic agenda for purposeful growth. It will enable us
to expand into the attractive adjacent category of specialty coatings with product
offerings in core as well as in new end-markets, driving further growth in our
Adhesive Technologies business unit.” said Henkel CEO Carsten Knobel. - Stahl employs approximately 1,700 people and generates annual revenue of EUR 725
million (2.9x EV / Revenue).
1/27/26
Universal Chemicals
and Coatings
PRO-SET
Formulated
Resin Systems
(Iron Path
Capital)
- –
- PRO-SET Formulated Resin Systems (“PFRS”) has acquired Universal Chemicals and
Coatings, an Illinois-based manufacturer of custom industrial coatings, laminating
adhesives and container linings. - This marks the third acquisition for PFRS, following its acquisition of Gougeon
Brothers, Inc. in May 2025 and Wessex Resins and Adhesives in December 2025.
Furthers PFRS’ strategy to build a global formulated resin systems business focused
on highly specified formulated products for fabricating, bonding, sealing, coating and
repair of advanced non-metallic and metallic composite structures for marine,
aerospace, defense, electronics and industrial applications.
1/22/26
Chemical business of
Kyocera Corporation
Sumitomo
Bakelite
Company Limited
$189M –
- Sumitomo Bakelite Company Limited has agreed to acquire the Chemical business of
Kyocera Corporation. Kyocera’s chemical business, based in Japan, manufactures
epoxy-resin molding compounds for encapsulation of semiconductor devices,
bonding pastes for semiconductor devices and resins for industrial use. - Enhances Sumitomo’s presence in the information & communications technology
industry.
1/14/26
Key Polymer
(DalFort Capital
Partners)
Seatex
(The Riverside
Company)
- –
- Seatex has acquired Key Polymer, a Massachusetts-based manufacturer of highperformance
adhesives, sealants and coatings for a diverse range of industries. - “Key Polymer is an excellent complement to the Seatex platform,” said Riverside
Partner Craig Kahler. “This represents our first follow -on acquisition since we
acquired Seatex in October 2024 and materially advances our plans to expand the end
market and geographic reach of the platform.”
3/19/26 Diversified Plastics
The Rubber
Group
(River Associates)
- –
- The Rubber Group has acquired Diversified Plastics (“DPI”), a Montana-based
precision plastic manufacturer offering urethane casting, thermoforming, machining
and injection molding. - “The combination is about growth. We are bringing together complementary
capabilities to better serve customers,” said Rob Pruyn, President, The Rubber
Group. “By combining rubber, plastics, and urethane capabilities, we can offer a
broader range of engineered solutions to both customer bases, and the cross-selling
opportunity is significant.” - DPI will now be known as Diversified Plastics Industrial Solutions.
April 9, 2026
US announced final anti-dumping duties on MDI imported from China
April 9, 2026 1 min read

On April 8, 2026, The US Department of Commerce announced that it has issued its final affirmative anti-dumping determination on methylene diphenyl diisocyanate (MDI) from China, imposing duties of 85.11% on major producers and 159.04% on others, a sharp reduction from preliminary rates. The final ruling sets a dumping rate of 85.11% for producer and exporter Covestro Polymers (China) Co., Ltd., producer Wanhua Chemical Group Co., Ltd., and its exporter Shandong Mingko Co., Ltd. All other Chinese producers and exporters received a rate of 159.04%. The products involved fall under US Harmonized Tariff Schedule numbers 2929.10.8010 and 3909.31.0000.
These final rates represent a significant reduction from the preliminary dumping duties of 376.12% to 511.75% announced in September 2025.
The US initiated the anti-dumping investigation on MDI from China on March 4, 2025, and issued its affirmative preliminary determination on September 16, 2025.
April 8, 2026
The Great Toilet Paper Shortage
4/8/2026|Updated: 4/8/2026
It was six years ago and most nations of the world had gone into lockdown to beat back a respiratory virus. Nothing like this had ever been tried before, and this is for a reason. Every pandemic protocol recommended against such tactics. This of course included work-from-home orders and a huge disruption in normal work flows, including the forced closure of small businesses.
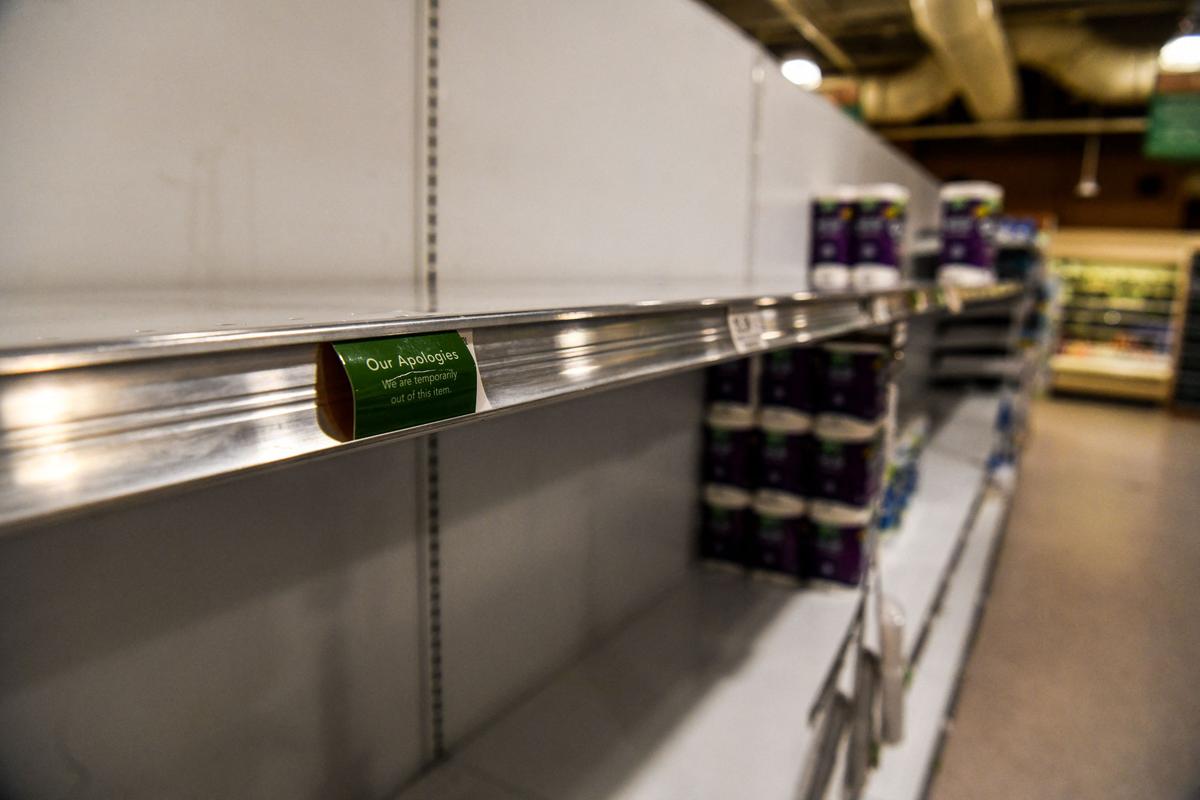
In the early weeks of these wild times, something unusual happened. You would go to the store and could not find toilet paper. You would go to another and it wasn’t there either. Hardly anyone actually stocks up on something that had always been available, so this was something of a shock. It came just as so much else seemed to be breaking, so it seemed in a sense like the world was falling apart.
Suddenly you were seeing toilet paper on sale for high figures on Facebook Marketplace. People were texting my phone with offers. Messages were coming in from all quarters wondering where they could get it. People were driving long distances just on a rumour that some was in stock somewhere.
Who knew just how thin the veneer of civilization truly was? People were losing their minds about what was surely a brief interruption in the availability of a product invented little more than 100 years ago, before which time people would use water or the “Farmer’s Almanac” hanging on the wall of the outhouse. Blech, but come on people!
Folks began to wonder how this had happened. The first theories involved supply chain breakages. Maybe truckers stopped showing up. Maybe we are more dependent on imports than we knew.
Or maybe bad people were stockpiling toilet paper. There were social media posts with pictures of people who had filled their entire garage with toilet paper, thus triggering genuine outrage. Stores that had toilet paper started rationing it. Or raising prices to effectively ration, thus prompting claims of gouging.
This went on for maybe two weeks of extreme deprivation and near panic. Had the forces of supply and demand broken? Was civilization utterly collapsing with this just as a first sign?
The actual explanation is both much simpler and more interesting. As it turns out, the workplace is where most people find the need for toilet paper. Workplace rolls are typically much different. They are industrial-sized rolls using machines wholly unlike anything one would use at home. They also use cheaper-quality paper.
But with millions suddenly working from home and avoiding the office altogether, the demand for workplace commercial varieties of toilet paper collapsed. Warehouses were stuffed with it but demand was nowhere in sight. Conversely, the demand for vast quantities of home use soared even as stay-at-home people decided to stock up. Experience suggests that households staying home will use about 40 percent more toilet paper of the type specifically manufactured for that purpose.
Most stores keep just enough to match supply and demand. Now we had a market shock. Even manufacturers had not prepared and suddenly faced a demand that they could not meet under normal production patterns. They certainly had not anticipated this.
The result was exactly as we saw. The markets had not broken. They were working entirely as they should. Manufacturers retooled and responded. Retailers rushed to stock up. In a few weeks, the panic died down and a new equilibrium was established.
What does this event teach us about economics? Everything. Higher demand and fixed supply drive shortages and higher prices. Higher prices with a premium over costs of production calls forth increased supply. This happens not instantly but in time, as fast as possible so long as the market is working.
Which is precisely why we need markets always to work. This was an unusual and dramatic change but actually the market as a driving force of production decisions operated with great elan and beauty.
As Adam Smith would say, it was almost like an invisible hand was in control. No one needed to know the names of the people running the paper mills and give them a call. We are all only consumers of the product. The prices alone do the work to nudge the producers and retailers in the right direction.
Prices are the signs and symbols of the dynamics of human life itself, instructing and revealing the secrets of the material world to entrepreneurs and managers.
Many societies in history have attempted to replace prices and markets with plans and commands. It works until there is a change in conditions. Here’s the rub: there is always change. Every day, every minute, there is change. The point of the institution of markets is to investigate and instantiate that change in signs and symbols to poke and nudge producers about the right path forward.
What seemed to many to be a major example of markets having broken was actually the opposite. It revealed how markets work brilliantly. Even the most extreme exogenous shock that no one anticipated only caused a fortnight-long disruption in a good that society had decided was essential to human well-being.
I highly regret what our central managers of the microbial kingdom did to us in those days. They are the villains in this story. The free market, on the other hand, is the hero. It adapted and served the human family with essential goods, not immediately but as quickly as humanly possible.
This is the real story of the great toilet-paper shortage of 2020. So many people say it as a failure of capitalistic forces when, in the instance of this product, really it was one of its greatest victories.
April 7, 2026
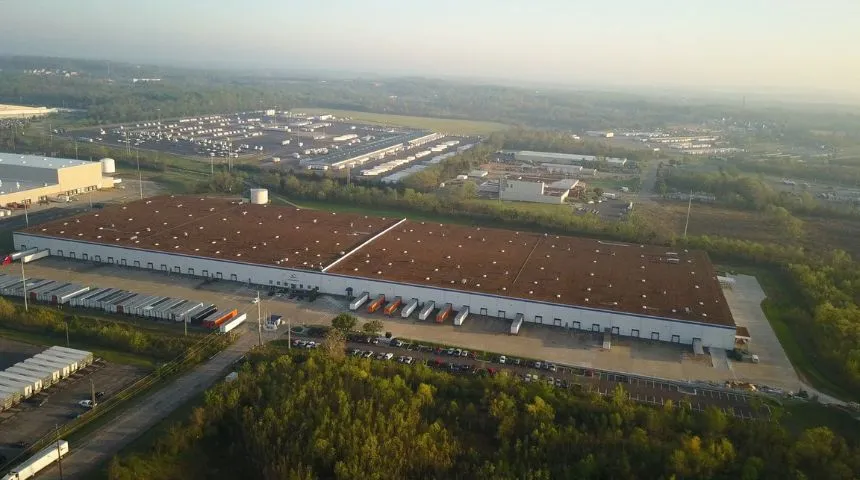
Sinomax is consolidating manufacturing into its Tennessee facility. Photo courtesy of Sinomax.
Sinomax consolidates 2 domestic production facilities into 1 in Tennessee
Sheila Long O’Mara //Executive Editor, Furniture Today//April 2, 2026
PHOENIX – Foam bedding producer Sinomax is consolidating its domestic manufacturing operations into its Tennessee facility, a move that will eliminate 89 manufacturing jobs at its location here, according to the company and a Worker Adjustment and Retraining Notification (WARN) filing.
The company said it is shifting U.S. production to its 1-million-square-foot LaVergne, Tenn., plant as part of a broader effort to improve efficiency and streamline operations.
The transition impacts about 89 employees working in manufacturing roles in Phoenix. The company said it will work with affected employees over the coming month to assist with their transition to new employment opportunities.
Sinomax cited operational challenges in Arizona as a key factor in the decision, particularly difficulties securing permits tied to foam pouring, a key component of its manufacturing process.
“Because of these issues, we cannot consider this location to be a long-term strategic investment in manufacturing,” the company said in a statement.
While manufacturing will cease in Phoenix, the company said the facility, opened in 2021, will continue to serve as a distribution hub for the foreseeable future.
“Although we regret this action had to be taken, we believe it is in the best interest of the health and long-term growth of the organization,” the statement said.
Sinomax’s LaVergne, Tenn., facility opened in 2017 and is the company’s first U.S. factory.
April 6, 2026
Foam prices are on the rise. What does that mean for mattresses, upholstery?
Sheila Long O’Mara //Executive Editor, Furniture Today//April 3, 2026

At A Glance
- Carpenter Co reports double-digit foam price increases and allocations
- FXI and Future Foam announce 12% to 18% price increases with supply cuts
- Manufacturers weigh surcharges amid foam cost increases
HIGH POINT – A fast-moving disruption in the global chemical supply chain is triggering sharp increases in foam costs and tightening allocations across the bedding and upholstery categories, setting the stage for higher retail prices and added pressure on an already strained home furnishings market.
Suppliers are implementing double-digit price increases – in some cases exceeding 20% – while limiting order volumes, creating a dual challenge of rising costs and constrained supply that executives say is unlike recent disruptions.
“It’s not just a North America issue; it’s a global problem,” said Michael Faus, senior vice president of Carpenter Co., the industry’s largest foam producer, noting that unlike prior disruptions such as the 2021 Texas freeze, suppliers today cannot simply source materials from other regions. “Back then, you could go outside the U.S. and bring in a spot buy. In this case, Asia, Europe and Mexico are all dealing with the same issues.”
At the center of the disruption is a shortage of propylene oxide, a critical feedstock used to produce polyols, which in turn are essential to polyurethane foam. Faus said a recent fire at a major Texas chemical plant significantly curtailed supply, creating a bottleneck that is rippling across the entire value chain.
Beyond the plant outages, executives point to geopolitical instability – including the ongoing war with Iran and tensions in the Middle East – as a key driver of rising input costs, which also impact textiles, yarn, steel and other components. Because foam chemicals are petroleum derivatives, increases in crude oil and fuel prices are directly impacting the cost of producing key chemicals like propylene oxide, polyols and isocyanates.
The impact is being felt across the entire cost structure, from raw materials to freight to plastic packaging to polyester thread. Rising fuel prices are increasing transportation costs, while higher energy prices are adding pressure at every stage of chemical production, further tightening an already constrained global supply chain.
“You can have all the TDI you need, but about 60% of the chemistry behind polyurethane depends on propylene oxide,” Faus said. “When that gets disrupted, it impacts everything.”
That constraint – combined with outages at major global chemical producers and rising input costs for energy, freight and raw materials such as benzene and natural gas – is driving multiple rounds of price increases. Carpenter implemented increases in early April and is preparing another round for May, which Faus expects to be in the double digits.
“The reality is, pricing is going up, and there’s another increase coming,” he said.
At the same time, supply remains constrained. Carpenter has implemented allocations and is working hard to manage them across its customer base. “We’re trying to keep allocations steady and consistent,” Faus said.
Carpenter isn’t alone in the price hikes or the allocations, limits on historical purchasing levels.
Suppliers have responded with multiple rounds of increases and allocation policies. FXI notified customers via letters received by Furniture Today of an 18% price increase effective mid-April alongside supply reductions, while Future Foam announced – also via emailed letters received by Furniture Today – a 12% increase with another, larger adjustment expected in early May. Vertically integrated 3Z Brands sent a similar notice to foam customers that conventional polyurethane foam would increase 22% and specialty foam products would jump 8% as of April 15.
Effects are being felt
Manufacturing executives across the industry, including a handful who would only speak on background, say the ripple effects are being felt immediately, with foam producers moving quickly to adjust pricing and control supply.
Increases, manufacturers say, are moving through the system at an unprecedented pace. Those constraints are being reinforced by force majeure declarations tied to shortages of key inputs, as chemical suppliers struggle to meet demand following the disruption in propylene oxide production.
The result is a supply chain shock that is cascading downstream – and one that manufacturers say cannot be absorbed.
For mattress and upholstery manufacturers, foam represents one of the largest component costs, leaving little room to offset increases. Several executives said retail prices on mattresses could rise by $100 or more in the near term, with overall product costs climbing meaningfully across categories.
Nick Bates, president and CEO of Spring Air International, said his company is already preparing to implement surcharges on orders to manage the volatility. “We’re looking at 12% to 18% increases now, and potentially 30% in May,” he said. “We’ll track it with a surcharge because of how fluid this is. No manufacturer is going to eat that; it’s going to show up at retail.”
At the same time, allocations are limiting manufacturers’ ability to grow production or support new business, creating additional friction at a time when demand remains soft.
While demand has softened compared with the pandemic-era surge – a factor Faus described as a “bit of a silver lining” – he emphasized that the current environment remains highly challenging, particularly as rising costs flow downstream to manufacturers and retailers already contending with weak consumer demand.
“This impacts everybody,” he said. “Most retail is struggling, and even some of the luxury segment is being affected. Now you layer on higher costs, and it puts even more pressure on the finished goods.”
Bob Naboicheck, CEO of Gold Bond, said the increases are coming at a particularly difficult moment for both manufacturers and retailers already contending with higher energy and freight costs.
“It’s a horrible time because the cost of energy is so high and chemicals are so high,” he said. “We’ll have to raise prices – probably around 8% on average – because we just can’t absorb it.”
While many executives view the increases as a necessary response to real cost pressures, others expressed skepticism about how quickly and how broadly pricing is moving higher.
“It feels opportunistic,” Bates said. “Every time something like this happens, prices go up quickly, but I’ve never seen a letter saying they’re coming back down.” He said suppliers are saying once the shortages clear pricing will stabilize.
“I’ll believe it when I see it, and I hope they remain true to their word,” he said.
Past comparisons, future expectations
Not all suppliers are reacting in the same way. Vertically integrated manufacturers with internal foam production capabilities say they are working to manage costs more deliberately.
“I believe the cost pressures are real,” said Kyle Robertson, chief operating officer of Mlily USA. “But our goal is to approach any changes thoughtfully. Because we control our foam pouring, we can take a more intentional approach rather than reacting too quickly.”
The current situation has drawn comparisons to past supply shocks, including Hurricane Katrina and the 2021 winter freeze in Texas. But executives say this disruption is more complex because it is global in scope and tied to multiple factors, including geopolitical instability, chemical plant outages and rising energy costs.
“This is about as close as it gets to Katrina, but it’s different,” Faus said. “This is more of a macro challenge.”
Looking ahead, industry leaders expect supply conditions to remain volatile in the near term. If domestic propylene oxide production resumes by early summer, Faus said conditions could begin to ease within 60 to 90 days. However, pricing pressure is expected to linger longer as elevated input costs work their way through the system.
“From a supply standpoint, we’re probably looking at 60 to 90 days of choppy waters,” Faus said. “But from a cost perspective, this will last longer than that.”
 Everchem Updates Archive
 Sign Up for Email Updates