
The Urethane Blog
September 2, 2026
Economic uncertainty weighs on new home sales, reports homebuilding association
By Dakota Smith
August 31, 2026 | 9:42 pm CDT

Elevated borrowing costs, rising inflation and broad economic uncertainty continue to curb buyer demand and hold back new home sales.
Sales of newly built single-family homes declined 10.5% in July to a seasonally adjusted annual rate of 607,000, following a sharply upwardly revised June estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales was 6.3% lower than a year earlier.
“New home sales fell in July to their slowest pace since the start of the year as affordability challenges limited home buyer traffic,” said Bill Owens, chairman of the National Association of Home Builders (NAHB) and a home builder and remodeler from Worthington, Ohio. “NAHB surveys show that a majority of builders continue to offer sales incentives, including mortgage rate buydowns, to support new home sales.”
“The single-family home building market is on track for a second consecutive annual decline in 2026,” said NAHB Chief Economist Robert Dietz. “New home sales are down more than 4% on a year-to-date basis. NAHB research and economic data show community builders continue to outperform the broader market, while the Northeast remains a relative bright spot, with new home sales up nearly 9% year-to-date.”
A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the July reading of 607,000 units is the number of homes that would sell if this pace continued for the next 12 months.
New single-family home inventory in July rose to 488,000 units, up 1.9% from June, and down 1.6% compared to a year ago. This represents an elevated 9.6 months’ supply at the current building pace, the highest measure since January.
The median new home sales price in July fell 2.3% from June to $393,800 and was down 0.9% from a year ago. The new home sales market is showing relative strength at the higher end of the market. The market share of new home sales priced above $800,000 increased from 5% a year ago to 8% in July.
Regionally, on a year-to-date basis, new home sales are up 8.8% in the Northeast but fell in the other three regions, with declines of 6.4% in Midwest, 3.7% in the South and 6.4% in the West.
August 30, 2026
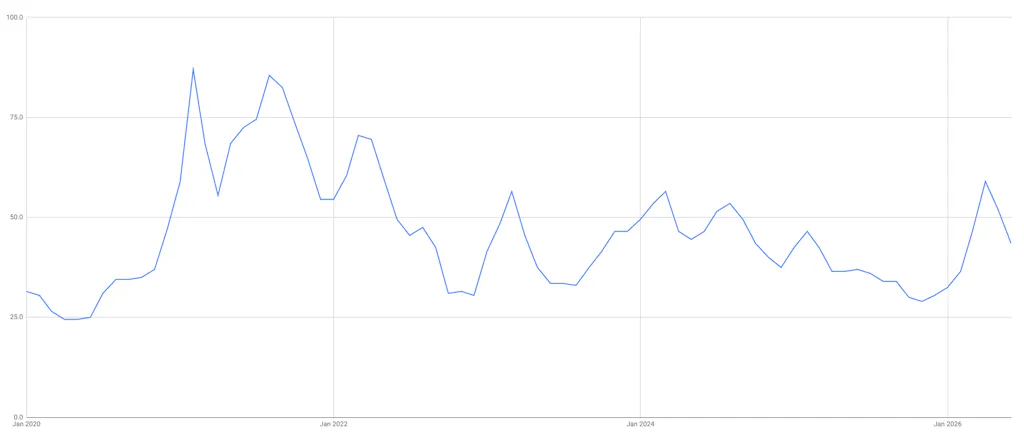
Chemical Grade Propylene is $0.45/lb in August 2026. Down 1.5cpp from July, which was up 3cpp from June.
August 30, 2026
Somnigroup completes $2.3B Leggett & Platt acquisition
By Larry Adams
August 27, 2026 | 11:21 am CDT

DALLAS — Somnigroup International Inc. has completed merger with Leggett & Platt to create a combined company that operates over 170 manufacturing facilities across 37 countries worldwide and is supported by a global workforce of more than 36,000 colleagues.
Chairman and CEO Scott Thompson said, “Today (August 26) marks an exciting milestone for Somnigroup as we complete the combination with Leggett & Platt. Building on nearly 50 years of collaboration, we are bringing together complementary businesses with shared values and a commitment to customer service and product innovation. By combining Leggett & Platt’s engineering expertise and manufacturing capabilities with Somnigroup’s global scale and industry-leading brands, we are fortifying our foundation for future growth and long-term value creation. The addition of Leggett & Platt deepens our vertical integration, secures a critical part of our supply chain, and adds a highly cash-generative business to our portfolio. We thank the employees of both organizations for their dedication and support throughout this process, as well as our suppliers, advisors, and shareholders for their continued partnership and confidence in our team.”
The combination was an all-stock transaction valued at approximately $2.3 billion based on Somnigroup’s closing share price on August 25, 2026, and inclusive of Leggett & Platt’s existing indebtedness. Leggett & Platt shareholders received 0.1455 shares of Somnigroup common stock in exchange for each share of Leggett & Platt common stock they owned. Upon completion of the transaction, former Leggett & Platt shareholders own approximately 9% of the combined company on a fully diluted basis.
Tyson Hagale has been appointed as president of Leggett & Platt, effective immediately. Hagale will report to Karl Glassman, Chief Executive Officer of Leggett & Platt, and will have oversight responsibility for all of Leggett & Platt.
August 27, 2026
U.S. Polyether Trade Flows Shift as Export Volumes Fall and Imports Climb Through Mid-2026

August 24, 2026 5 min read
U.S. trade flows in polyethers shifted noticeably during the first half of 2026, as outbound volumes weakened while imports continued to expand. The latest data point to a gradual rebalancing of the U.S. market, with the country maintaining a net export position but by a significantly narrower margin than a year earlier.
Key Figures (H1 2025 vs. H1 2026)
- Total U.S. exports: down 10.4%, to 178.0 million kg
- Imports for consumption: up 9.1%, to 106.4 million kg
- Net trade surplus: narrowed 29.2%, to 71.6 million kg
- Fastest-growing export market: Peru, up over 500%
- Fastest-growing import source: Turkey, up 104.0%
- China: exports up 40.5% and imports up 28.8%, expanding in both directions
U.S. Trade Surplus Narrows Sharply
During January–June 2026, total U.S. polyether exports reached approximately 178.0 million kg, down 10.4% from 198.7 million kg during the same period of 2025.
Domestic exports, which exclude foreign-origin material subsequently re-exported from the United States, followed a similar trajectory. Volumes declined by 9.5%, from 193.9 million kg to approximately 175.4 million kg.
Imports moved in the opposite direction. U.S. imports for consumption increased by 9.1% year on year, reaching 106.4 million kg, compared with 97.5 million kg during H1 2025.
| U.S. Polyether Trade | H1 2025 | H1 2026 | YoY Change |
| Total exports | 198.7 million kg | 178.0 million kg | -10.4% |
| Domestic exports | 193.9 million kg | 175.4 million kg | -9.5% |
| Imports for consumption | 97.5 million kg | 106.4 million kg | +9.1% |
| Net trade balance* | 101.2 million kg | 71.6 million kg | -29.2% |
The result was a substantial contraction in the U.S. net trade surplus. The volume surplus narrowed from roughly 101.2 million kg in H1 2025 to 71.6 million kg in H1 2026, a decline of around 29%.
The movement is significant because it reflects pressure from both sides of the trade balance: the United States is shipping less product abroad while simultaneously absorbing more foreign material into the domestic market.
North American Export Markets Remain Dominant but Soften
Mexico and Canada continued to anchor U.S. outbound polyether trade, together accounting for more than 45% of total H1 2026 exports. Nevertheless, shipments to both countries declined from a year earlier.
Exports to Mexico fell 6.8% to approximately 42.2 million kg, while shipments to Canada decreased 6.2% to 38.5 million kg.
Although the reductions were moderate relative to some other destinations, their impact on the overall export total was amplified by the scale of the two markets.
More pronounced contractions were recorded across several South American, Asian and overseas destinations.
Exports to South Africa fell 38.9% to around 2.6 million kg, while shipments to Chile declined 38.4% to 2.3 million kg. U.S. exports to Colombia dropped 35.2% to 4.6 million kg and those to India fell 35.1% to 4.3 million kg.
Brazil, another important polyurethane market in the Americas, also purchased less U.S. material. Volumes fell approximately 21.0% year on year to 10.0 million kg.
Exports to Belgium, meanwhile, declined 11.6% to 16.4 million kg.
Taken together, the data suggest that the decline in U.S. exports was relatively broad rather than being driven by the loss of a single major destination.
Peru and China Buck the Export Downtrend
Not every export market weakened.
Peru recorded the strongest percentage increase among the major destinations reviewed, with U.S. shipments rising from roughly 650,000 kg in H1 2025 to approximately 4.0 million kg in H1 2026. This represented an increase of more than 500%, although from a comparatively small starting base.
Exports to China also increased strongly, rising 40.5% from 8.4 million kg to approximately 11.9 million kg. The increase elevated China to the fourth-largest destination for U.S. polyether exports during the first half of 2026.
Shipments to Taiwan increased by approximately 47.6%, from 1.7 million kg to 2.4 million kg, although volumes remained relatively modest compared with the largest destination markets.
These increases partially offset losses elsewhere but were insufficient to reverse the broader decline in outbound trade.
Imports Rise as South Korea Retains Leading Position
The import picture was markedly different.
South Korea remained the dominant supplier to the U.S. market, shipping approximately 40.4 million kg during January–June 2026. Volumes increased by 3.7% year on year, giving South Korea a share of roughly 38% of total U.S. imports for consumption.
China continued to strengthen its position as the second-largest source.
U.S. imports from China rose 28.8%, reaching approximately 23.5 million kg in H1 2026. The increase means South Korea and China together supplied close to 60% of total U.S. polyether import volume during the period.
Imports from Canada recorded an even faster percentage increase, rising 52.8% to approximately 9.7 million kg.
Other suppliers also expanded their presence. Shipments from Germany increased 11.4% to 8.1 million kg, while imports from Vietnam climbed 27.8% to approximately 4.9 million kg.
Turkey registered the largest percentage gain, with shipments more than doubling, although volumes remained comparatively small. Imports increased 104.0%, from approximately 358,000 kg to 731,000 kg.
By contrast, imports from Taiwan declined 32.3%, while volumes from the Netherlands fell 29.6%.
China Emerges as an Increasingly Important Two-Way Trade Partner
One of the more notable features of the data is the simultaneous expansion of polyether trade in both directions between the United States and China.
U.S. exports to China increased 40.5% to 11.9 million kg, while U.S. imports from China rose 28.8% to 23.5 million kg.
Rather than pointing to a straightforward substitution of U.S. production with Chinese supply, the figures indicate increasingly active two-way trade within the broad polyether category.
The U.S. nevertheless imported nearly twice as much polyether material from China as it exported there during H1 2026.
The development may also reflect differences in product grades, downstream applications, producer positioning and regional supply economics within the broad HS classifications. Because the trade codes aggregate several polyether products, the data alone cannot establish that identical grades are moving simultaneously in opposite directions.
What the Shift Means for the U.S. Polyether Market
The H1 figures indicate that the U.S. polyether market entered 2026 with a changing trade configuration.
The United States remains a substantial net exporter, supported particularly by its established trade relationships with Mexico and Canada. However, its export surplus is becoming less pronounced as overseas shipments decline and imported volumes gain ground.
The stronger presence of Asian supply is particularly notable. South Korea already represents the largest foreign source, while China continues to increase its share of the U.S. import market. Together with rising volumes from Vietnam, the figures point to continued Asian participation in U.S. polyether supply.
At the same time, weaker exports to several Latin American destinations, including Brazil, Colombia and Chile, suggest that U.S. suppliers faced greater difficulty maintaining volumes in some regional markets during the first half of the year. This could reflect changing regional sourcing patterns, competitive pricing from Asian suppliers, softer downstream consumption or a combination of these factors, although trade statistics alone cannot determine the underlying cause.
The direction of the trade balance will therefore be important to watch through the remainder of 2026. If import growth persists while exports remain below 2025 levels, foreign-origin supply could play an increasingly important role in U.S. market availability and competitive pricing.
August 25, 2026
Shell could sell U.S. chemicals division for $8 billion as it refocuses on oil and gas
A Shell fuel tanker truck – Credit: K.D.P / DepositPhotos – License: DepositPhotos
Shell has attracted interest from several potential buyers for its chemical business in the United States, according to the Financial Times. Among those reportedly considering a deal are ExxonMobil, LyondellBasell and investment firm Apollo, sources told the newspaper. Shell could raise around $8 billion by selling its U.S. chemical assets, the Financial Times reports. However, the company has not yet decided whether it will proceed with a sale.
Several potential buyers have already made preliminary offers, either for the division as a whole or for individual parts of the business. Kuwait Petroleum Corporation, the state-owned Kuwaiti oil company, is also said to be among those interested.
Shell operates four chemical plants across Louisiana, Texas and Pennsylvania, producing chemicals used in a range of products, including plastics, medicines and cleaning agents. One of its largest facilities is the Monaca plant in Pennsylvania, which can produce up to 1.6 million tons of polymers each year.
A $8 billion sale of the entire chemicals division would represent a substantial shortfall compared with Shell’s previous investments in its U.S. chemicals business, the newspaper reports.
The potential sale comes as Shell increasingly focuses on its core oil and gas operations. The company made its biggest acquisition in more than a decade earlier this year, paying $13.6 billion for Canadian oil and gas producer ARC Resources.
Shell, ExxonMobil and Apollo declined to comment when contacted by the Financial Times. LyondellBasell and Kuwait Petroleum did not respond to the newspaper’s questions.
The potential sale would not cover all of Shell’s U.S. operations, as the company also owns offshore drilling platforms and oil refineries in the country.
https://nltimes.nl/2026/08/24/shell-sell-us-chemicals-division-8-billion-refocuses-oil-gas
 Everchem Updates Archive
 Sign Up for Email Updates