
The Urethane Blog
September 2, 2026
Somnigroup International Inc. (SGI) Discusses Strategic Acquisition of Leggett & Platt and Enhanced Vertical Integration Transcript
Sep 02, 2026, 12:44 PM ETSomnigroup International Inc. (SGI) Stock

Somnigroup International Inc. (SGI) Discusses Strategic Acquisition of Leggett & Platt and Enhanced Vertical Integration September 2, 2026 8:00 AM EDT
Company Participants
Lauren Avritt – Director of Investor Relations
Scott Thompson – Chairman of the Board, CEO & President
Bhaskar Rao – Executive VP & CFO
Scott Thompson
Chairman of the Board, CEO & President
Thank you, Lauren, and good morning, everyone. Today is a significant day. We have officially closed the Leggett & Platt transaction, and I’m pleased to welcome the Leggett & Platt team to the Somnigroup family. This milestone marks the next chapter in our strategic journey and one we believe strengthens Somnigroup’s competitive position around the world.
A few facts on Somnigroup post-closing. Over $11 billion in trailing 12-month sales, over $750 million trailing 12 months net income, $20 billion enterprise value, $15 billion market cap. Over 170 manufacturing plants around the world. 2,800-plus retail stores with various formats customized for each international market. Over 40 e-commerce websites, selling direct to consumer with aggregate sales of over $500 million per year. 36,000 talented associates led by a very experienced management team. And customers, both retail and wholesale in over 100 countries. We are building a special vertically integrated company with numerous competitive advantages, outstanding cash flow generation attributes, a diversified customer base and a passionate workforce dedicated to customers in various markets and industries.
What we see in Leggett & Platt is a company with 143-year long legacy of exceptional people, world-class manufacturing, strong commitment to customer service and best-in-class expertise in bedding components. They also have a long track record as one of our most important suppliers. We know them well, and they know us well. That familiarity is an asset as we move forward as a combined company. First and foremost, the combination deepens our vertical integration, and it adds significant scale expanding sourcing opportunities, enhancing operational flexibility to a portfolio of assets that is already industry-leading. It also extends our reach across industries beyond bedding which will provide the company solid free cash flow and growth as markets normalize and these strategies are implemented. Strategically and economically, this is the right deal at the right time with the right partner.
Let me take you through how this transaction advances the strategic pillars we outlined at our Investor Day last March. Global scale and vertical integration, relentless consumer-centric innovation, relentless cash generation, disciplined capital allocation and a uniquely favorable position in the $120 billion global bedding market recovery. The Leggett & Platt acquisition checks every one of these boxes. Most directly, it strengthened our vertical integration advantages. Leggett & Platt is a primary supplier of important components to the bedding industry and particularly to our own manufacturing operations. They supply innerspring units, specialty foam and other key components to producers around the world, bringing their capabilities in-house further fortifies our supply chain in an uncertain world and allows us to optimize cost and drive quality end-to-end in the supply chain. The combination brings component engineering closer to mattress design and closer to the consumer insights we generate every day across our retail platform. That proximity supports accelerated innovation cycles. It means we can develop more cost-effective and consumer-centric products.
In addition to expanding our addressable market in bedding, Leggett & Platt’s product portfolio includes automotive seating systems, furniture components, geo components, and hydraulic cylinders also allow us to participate in industries beyond global bedding. These diversified sales streams as well as Leggett & Platt’s geographic footprint broadens our earnings base, and mitigates reliance on any single category, product or geographic market.
Let me say a word about how we intend to operate Leggett & Platt within the Somnigroup portfolio. Leggett & Platt will operate as a stand-alone business unit within Somnigroup, consistent with our approach with Tempur Sealy, Mattress Firm and Dreams. We believe this decentralized operating model is one of our structural advantages. It allows each business unit to stay close to its customers and markets and quickly respond and develop strategies in an ever-changing world, while also benefiting from Somnigroup’s expertise, scale, strong balance sheet and operational leverage.
A word on leadership. First, we’re very fortunate that Leggett & Platt has an experienced workforce dedicated to quality and customer service, which is led by a strong committed executive team with depth and a passion to succeed. To enhance their leadership structure, you most likely saw we announced the appointment Tyson Hagale as President of Leggett & Platt. Tyson is a 25-year Leggett & Platt veteran with a broad expertise across all corners of the business, including strategic planning, operational leadership and M&A. Most recently, he served as President of the Bedding Products segment, delivering results and operational improvements through some of the most dynamic conditions in the industry has ever seen. He knows Leggett & Platt well, including the non-bedding components. Karl Glassman will continue to lead Leggett & Platt as CEO over the near term, working closely with Tyson and Somnigroup executives as we bring the companies together. I’m looking forward to working with Karl and Tyson.
Moving to near-term strategic initiatives. We expect some early wins. We have long believed that high-quality innerspring systems represent a meaningful point of differentiation and important feature for customers. While the mattress category has traditionally emphasized finished product branding, we see the opportunity to elevate awareness of underlying technologies and components that contribute to comfort, support, durability and overnight fleet quality. Simply put, what is in your mattress matters. As a result, we are working to amplify the differentiated innovation by incorporating Leggett & Platt innerspring branding on the exterior selected mattress products. We believe this approach helps highlight the value of the technology inside the mattress while creating greater transparency and confidence for customers at the point of purchase. This initiative will initially roll out with our launch of the all-new Stearns & Foster collection this fall. It represents an important step in our broader strategy to increase consumers’ recognition of the premium component of engineering that differentiates our products. We believe stronger visibility of the Leggett & Platt innerspring technology can enhance the consumer shopping experience, support our retail partners’ merchandising efforts and further reinforce the value proposition of mattresses that incorporate our technology.
Ultimately, we view this as much more than a branding initiative. This is a reflection of the strategic vision behind the acquisition of Leggett & Platt’s bedding business and the unique capabilities that the transaction creates. By bringing ownership of innersprings, the heart of the bed, into the portfolio we are now able to more closely integrate component innovation, mattress design, driving consumer engagement. We believe that position enables us to set higher standards for innovation, durability, quality and transparency across the industry, while creating connection between the technology inside the mattress and the magic consumers experience every night. We should also note that Mattress Firm as it continues to focus on customer first, recently communicated to its supplier base, new and more stringent merchandising criteria, including the qualification of key component inputs, both Leggett & Platt’s innerspring systems and the foams produced by ECS, their specialty foam operations have been qualified under these enhanced standards. This is direct validation of the quality and consistency that Leggett & Platt brings us to our supply chain. I’ll say it again, what is inside your mattress matters.
In closing, I want to leave you with a few key thoughts. We are the leading vertically integrated bedding company in the world. We now forge our own steel, create our own springs and foam. We design and build our own products. We develop and market our brands and sell our products, which cover all price points in a balanced omnichannel format across the world. We believe that the $120 billion global bedding market remains structurally intact and positioned to normalize from its historically depressed levels. Now let’s be clear, the bedding market has experienced an extended period of weakness, and we have used that time deliberately to build the platform you see today, while also growing adjusted EPS and deleveraging. We are investing ahead of the recovery and building our brands, driving upper funnel advertising and strengthening our infrastructure. It’s not a question if the bedding market is going to turn around. It’s a question of when and whether you are positioned to lead when it does, and we are positioned to win and win big.
Bhaskar Rao
Executive VP & CFO
Thank you, Scott. Let me start with some housekeeping items on our reporting structure going forward. Leggett & Platt will be reported as a single consolidated reportable segment within Somnigroup, consistent with our other reporting segments, Tempur Sealy North America, Tempur Sealy International and Mattress Firm. Now moving to synergies. When we announced this transaction, we identified approximately $50 million in synergy opportunities on an annual run rate basis, focused on sourcing, operations and product innovation. That figure was based primarily on our internal diligence work at that time. Since then, we have worked with Leggett to refine our expectations. As a result of the team’s combined efforts, we are increasing that synergy estimate by 50% to $75 million on an annual run rate basis with additional opportunities in our synergy funnel that will be evaluated over the next year. .
Within sourcing, we see opportunities to expand profitability by bringing select components in-house and/or improving purchasing economics across our supplier base. To date, we have included $35 million of sourcing related synergies in our target. One of the most immediate and tangible examples is innersprings. Beginning in January 1, 2027, we expect to manufacture over 90% of our total U.S. spring needs internally, creating a meaningful cost savings opportunity and further strengthening integration across the business. We are reviewing additional supply chain opportunities and expect our combined sourcing efforts to support greater cost efficiency, particularly in chemicals. In addition, we expect the broader platform to create savings across third-party professional services.
Rafe Jadrosich
BofA Securities, Research Division
I just wanted to follow-up on the sourcing synergies that the 90% of — the expectation that you’ll be 90% internal sourcing for your springs. Can you talk about where that is today, like what that delta is? How much you’re getting from Leggett versus either other suppliers or internal right now, so like what that changes? And then does that include anything with Elite Comfort Systems in the foam side? Or is that all — that sourcing number all innersprings?
Scott Thompson
Chairman of the Board, CEO & President
Yes. We were under a long-term contract with Leggett pre-combination of 80% of our springs in the U.S., this is just a U.S. comp discussion coming from Leggett, so you should think about it as incrementally 10%, and we’ll probably be a little bit north of 90% over time would be my guess. That number is in the synergies. There’s nothing significant currently in the synergy number on the ECS side as we work through the ECS side of the house. We have a great supplier currently, what I’m going to call base foam, and they’re doing a great job, and we’re working with them and working with ECS and trying to find an optimal structure there, but we’ve got great suppliers on the base foam already.
Michael Lasser
UBS Investment Bank, Research Division
There are very few examples where one company such as Somnigroup control such a disproportionate amount of the profitability within the sector, and the bedding industry is interesting in that historically, it’s relied heavily on pricing as a key contributor to the overall growth of the sector. So my two-part question is, a, Scott, do you see any changes in the overall economics of the bedding industry as a result of Somnigroup’s unique position; and b, how are you looking at the overall pricing architecture of the industry moving forward as a key contributor to the overall top line results?
Scott Thompson
Chairman of the Board, CEO & President
Thank you for the question, and there’s probably some of my lawyers on the phone now that are going like, I hope he doesn’t really say much on that question, but let me talk about — first of all, you’re right. It’s a couple of things that are really unique. It’s really unique that a company was able to take a downturn, and the downturn has been, on a historical basis, it’s been the worst downturn ever, and be able to build what we’ve built. I mean it really is game changing. And you’re right, I don’t know what percentage of worldwide bedding profits Somnigroup now has, but it’s large, we’ll say it.
As far as the pricing architecture, I think the profitability of the bedding industry is going to be enhanced as we take out redundant costs and we add synergies. I think the economists and certainly, history would be the FTC would look at that and expect that some of that would creep into the customers’ pocket. And maybe it does, maybe it doesn’t. But from a competitive advantage standpoint, it certainly should create a competitive advantage in the marketplace.
Peter Keith
Piper Sandler & Co., Research Division
Big picture on the industry and potential rebound, so it looks like we’re now entering our fifth year of mattress industry sales declines. We do have positive GDP growth, there’s been a tax refund cycle earlier in the year. When you guys are thinking about the industry rebounding and getting better, what do you think needs to happen in the economy looking forward? And I understand housing would be an easy answer, but we all agree that, that’s a minority of total mattress sales purchases?
Scott Thompson
Chairman of the Board, CEO & President
The real answer is housing is an incremental headwind or incremental tailwind usually not hugely material, but you’d rather have a tailwind than a headwind. It’s consumer confidence which I would point back into a little less — a little more stable environment because look, these are discretionary goods, they are expensive and so when consumers are not confident and sentiment is really negative, they have — some portion of the customers tend to postpone. It’s interesting because it’s in-floor traffic. The customer who actually is in the funnel to purchase a bed, once in the funnel, gets through the funnel fairly quickly, or in standard form and it gets into the store and the closing rates are very strong.
So you don’t have an issue on pricing. You don’t have an issue on quality of products, quite frankly, the products, ours and others in the bedding industry are good. You’ve got a strong kind of health and wellness concept that goes through the industry. People do care about their bed. They do care about their health, and people with means are showing up and buying. Who’s not showing up are the more of the entry-level customers, if you want to say, the K economy or whatever or people who are a little unsettled by current events. So the first thing I’d say is we just need less drama in the world. And we’ve had it a few times, okay, where there’s a period where there’s a little less drama, and you can see it in the numbers. I mean, floor traffic picks up, sales pick up, but then we get some tariff drama, some Middle East drama and people’s hands go back into their pockets. That would be my first answer to that.
And the second answer is we need to continue to have the industry advertise, have effective advertising, make sure it’s compelling and get it placed in a way in the marketplace that consumers are seeing the ads and that it’s influencing them to think about their bed to get into the purchase funnel. The biggest — the issue is getting people triggered to think about their beds. If you look at the installed base, and this isn’t like the car business where you can look at a VIN and you know exactly what the average age of all the cars are on the road, how many miles they’ve driven. We don’t have that kind of data, but there is no question if you look at the volume declines over what — you’re right, into the fifth year that the products that are in the marketplace are probably older than they’ve ever been. There’s also no question that beds do wear out, and there’s no question that people are going to sleep on beds. The industry is structurally sound. There’s nothing that’s threatening the industry from a structural standpoint. So that’s why I kind of go back to — I don’t know, I can’t tell you the exact turn, but there’s — but everything points to what we just need is a little more stability in the way the consumers are thinking about the world.
September 2, 2026
Economic uncertainty weighs on new home sales, reports homebuilding association
By Dakota Smith
August 31, 2026 | 9:42 pm CDT

Elevated borrowing costs, rising inflation and broad economic uncertainty continue to curb buyer demand and hold back new home sales.
Sales of newly built single-family homes declined 10.5% in July to a seasonally adjusted annual rate of 607,000, following a sharply upwardly revised June estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales was 6.3% lower than a year earlier.
“New home sales fell in July to their slowest pace since the start of the year as affordability challenges limited home buyer traffic,” said Bill Owens, chairman of the National Association of Home Builders (NAHB) and a home builder and remodeler from Worthington, Ohio. “NAHB surveys show that a majority of builders continue to offer sales incentives, including mortgage rate buydowns, to support new home sales.”
“The single-family home building market is on track for a second consecutive annual decline in 2026,” said NAHB Chief Economist Robert Dietz. “New home sales are down more than 4% on a year-to-date basis. NAHB research and economic data show community builders continue to outperform the broader market, while the Northeast remains a relative bright spot, with new home sales up nearly 9% year-to-date.”
A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the July reading of 607,000 units is the number of homes that would sell if this pace continued for the next 12 months.
New single-family home inventory in July rose to 488,000 units, up 1.9% from June, and down 1.6% compared to a year ago. This represents an elevated 9.6 months’ supply at the current building pace, the highest measure since January.
The median new home sales price in July fell 2.3% from June to $393,800 and was down 0.9% from a year ago. The new home sales market is showing relative strength at the higher end of the market. The market share of new home sales priced above $800,000 increased from 5% a year ago to 8% in July.
Regionally, on a year-to-date basis, new home sales are up 8.8% in the Northeast but fell in the other three regions, with declines of 6.4% in Midwest, 3.7% in the South and 6.4% in the West.
August 30, 2026
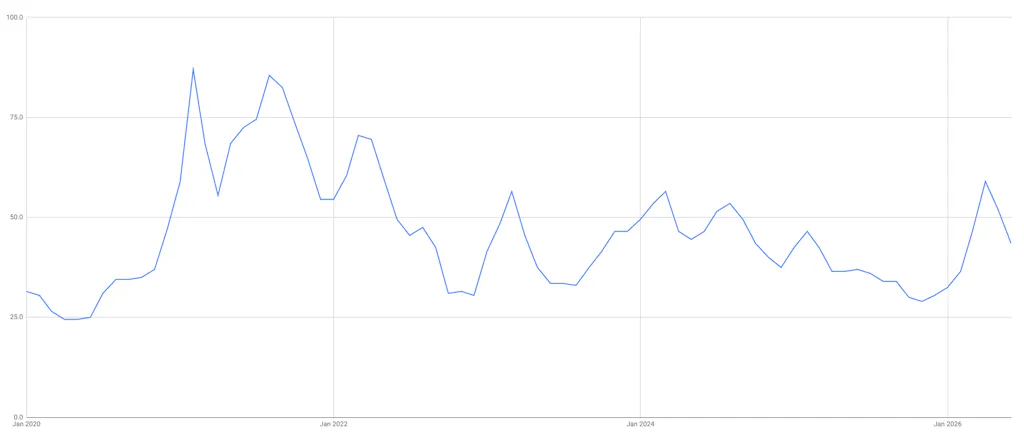
Chemical Grade Propylene is $0.45/lb in August 2026. Down 1.5cpp from July, which was up 3cpp from June.
August 30, 2026
Somnigroup completes $2.3B Leggett & Platt acquisition
By Larry Adams
August 27, 2026 | 11:21 am CDT
DALLAS — Somnigroup International Inc. has completed merger with Leggett & Platt to create a combined company that operates over 170 manufacturing facilities across 37 countries worldwide and is supported by a global workforce of more than 36,000 colleagues.
Chairman and CEO Scott Thompson said, “Today (August 26) marks an exciting milestone for Somnigroup as we complete the combination with Leggett & Platt. Building on nearly 50 years of collaboration, we are bringing together complementary businesses with shared values and a commitment to customer service and product innovation. By combining Leggett & Platt’s engineering expertise and manufacturing capabilities with Somnigroup’s global scale and industry-leading brands, we are fortifying our foundation for future growth and long-term value creation. The addition of Leggett & Platt deepens our vertical integration, secures a critical part of our supply chain, and adds a highly cash-generative business to our portfolio. We thank the employees of both organizations for their dedication and support throughout this process, as well as our suppliers, advisors, and shareholders for their continued partnership and confidence in our team.”
The combination was an all-stock transaction valued at approximately $2.3 billion based on Somnigroup’s closing share price on August 25, 2026, and inclusive of Leggett & Platt’s existing indebtedness. Leggett & Platt shareholders received 0.1455 shares of Somnigroup common stock in exchange for each share of Leggett & Platt common stock they owned. Upon completion of the transaction, former Leggett & Platt shareholders own approximately 9% of the combined company on a fully diluted basis.
Tyson Hagale has been appointed as president of Leggett & Platt, effective immediately. Hagale will report to Karl Glassman, Chief Executive Officer of Leggett & Platt, and will have oversight responsibility for all of Leggett & Platt.
August 27, 2026
U.S. Polyether Trade Flows Shift as Export Volumes Fall and Imports Climb Through Mid-2026

August 24, 2026 5 min read
U.S. trade flows in polyethers shifted noticeably during the first half of 2026, as outbound volumes weakened while imports continued to expand. The latest data point to a gradual rebalancing of the U.S. market, with the country maintaining a net export position but by a significantly narrower margin than a year earlier.
Key Figures (H1 2025 vs. H1 2026)
- Total U.S. exports: down 10.4%, to 178.0 million kg
- Imports for consumption: up 9.1%, to 106.4 million kg
- Net trade surplus: narrowed 29.2%, to 71.6 million kg
- Fastest-growing export market: Peru, up over 500%
- Fastest-growing import source: Turkey, up 104.0%
- China: exports up 40.5% and imports up 28.8%, expanding in both directions
U.S. Trade Surplus Narrows Sharply
During January–June 2026, total U.S. polyether exports reached approximately 178.0 million kg, down 10.4% from 198.7 million kg during the same period of 2025.
Domestic exports, which exclude foreign-origin material subsequently re-exported from the United States, followed a similar trajectory. Volumes declined by 9.5%, from 193.9 million kg to approximately 175.4 million kg.
Imports moved in the opposite direction. U.S. imports for consumption increased by 9.1% year on year, reaching 106.4 million kg, compared with 97.5 million kg during H1 2025.
| U.S. Polyether Trade | H1 2025 | H1 2026 | YoY Change |
| Total exports | 198.7 million kg | 178.0 million kg | -10.4% |
| Domestic exports | 193.9 million kg | 175.4 million kg | -9.5% |
| Imports for consumption | 97.5 million kg | 106.4 million kg | +9.1% |
| Net trade balance* | 101.2 million kg | 71.6 million kg | -29.2% |
The result was a substantial contraction in the U.S. net trade surplus. The volume surplus narrowed from roughly 101.2 million kg in H1 2025 to 71.6 million kg in H1 2026, a decline of around 29%.
The movement is significant because it reflects pressure from both sides of the trade balance: the United States is shipping less product abroad while simultaneously absorbing more foreign material into the domestic market.
North American Export Markets Remain Dominant but Soften
Mexico and Canada continued to anchor U.S. outbound polyether trade, together accounting for more than 45% of total H1 2026 exports. Nevertheless, shipments to both countries declined from a year earlier.
Exports to Mexico fell 6.8% to approximately 42.2 million kg, while shipments to Canada decreased 6.2% to 38.5 million kg.
Although the reductions were moderate relative to some other destinations, their impact on the overall export total was amplified by the scale of the two markets.
More pronounced contractions were recorded across several South American, Asian and overseas destinations.
Exports to South Africa fell 38.9% to around 2.6 million kg, while shipments to Chile declined 38.4% to 2.3 million kg. U.S. exports to Colombia dropped 35.2% to 4.6 million kg and those to India fell 35.1% to 4.3 million kg.
Brazil, another important polyurethane market in the Americas, also purchased less U.S. material. Volumes fell approximately 21.0% year on year to 10.0 million kg.
Exports to Belgium, meanwhile, declined 11.6% to 16.4 million kg.
Taken together, the data suggest that the decline in U.S. exports was relatively broad rather than being driven by the loss of a single major destination.
Peru and China Buck the Export Downtrend
Not every export market weakened.
Peru recorded the strongest percentage increase among the major destinations reviewed, with U.S. shipments rising from roughly 650,000 kg in H1 2025 to approximately 4.0 million kg in H1 2026. This represented an increase of more than 500%, although from a comparatively small starting base.
Exports to China also increased strongly, rising 40.5% from 8.4 million kg to approximately 11.9 million kg. The increase elevated China to the fourth-largest destination for U.S. polyether exports during the first half of 2026.
Shipments to Taiwan increased by approximately 47.6%, from 1.7 million kg to 2.4 million kg, although volumes remained relatively modest compared with the largest destination markets.
These increases partially offset losses elsewhere but were insufficient to reverse the broader decline in outbound trade.
Imports Rise as South Korea Retains Leading Position
The import picture was markedly different.
South Korea remained the dominant supplier to the U.S. market, shipping approximately 40.4 million kg during January–June 2026. Volumes increased by 3.7% year on year, giving South Korea a share of roughly 38% of total U.S. imports for consumption.
China continued to strengthen its position as the second-largest source.
U.S. imports from China rose 28.8%, reaching approximately 23.5 million kg in H1 2026. The increase means South Korea and China together supplied close to 60% of total U.S. polyether import volume during the period.
Imports from Canada recorded an even faster percentage increase, rising 52.8% to approximately 9.7 million kg.
Other suppliers also expanded their presence. Shipments from Germany increased 11.4% to 8.1 million kg, while imports from Vietnam climbed 27.8% to approximately 4.9 million kg.
Turkey registered the largest percentage gain, with shipments more than doubling, although volumes remained comparatively small. Imports increased 104.0%, from approximately 358,000 kg to 731,000 kg.
By contrast, imports from Taiwan declined 32.3%, while volumes from the Netherlands fell 29.6%.
China Emerges as an Increasingly Important Two-Way Trade Partner
One of the more notable features of the data is the simultaneous expansion of polyether trade in both directions between the United States and China.
U.S. exports to China increased 40.5% to 11.9 million kg, while U.S. imports from China rose 28.8% to 23.5 million kg.
Rather than pointing to a straightforward substitution of U.S. production with Chinese supply, the figures indicate increasingly active two-way trade within the broad polyether category.
The U.S. nevertheless imported nearly twice as much polyether material from China as it exported there during H1 2026.
The development may also reflect differences in product grades, downstream applications, producer positioning and regional supply economics within the broad HS classifications. Because the trade codes aggregate several polyether products, the data alone cannot establish that identical grades are moving simultaneously in opposite directions.
What the Shift Means for the U.S. Polyether Market
The H1 figures indicate that the U.S. polyether market entered 2026 with a changing trade configuration.
The United States remains a substantial net exporter, supported particularly by its established trade relationships with Mexico and Canada. However, its export surplus is becoming less pronounced as overseas shipments decline and imported volumes gain ground.
The stronger presence of Asian supply is particularly notable. South Korea already represents the largest foreign source, while China continues to increase its share of the U.S. import market. Together with rising volumes from Vietnam, the figures point to continued Asian participation in U.S. polyether supply.
At the same time, weaker exports to several Latin American destinations, including Brazil, Colombia and Chile, suggest that U.S. suppliers faced greater difficulty maintaining volumes in some regional markets during the first half of the year. This could reflect changing regional sourcing patterns, competitive pricing from Asian suppliers, softer downstream consumption or a combination of these factors, although trade statistics alone cannot determine the underlying cause.
The direction of the trade balance will therefore be important to watch through the remainder of 2026. If import growth persists while exports remain below 2025 levels, foreign-origin supply could play an increasingly important role in U.S. market availability and competitive pricing.
 Everchem Updates Archive
 Sign Up for Email Updates