
The Urethane Blog
January 30, 2025
Dow reports fourth quarter 2024 results
Jan. 30, 2025 6:00 AM ETDow Inc. (DOW)
MIDLAND, Mich., Jan. 30, 2025 /PRNewswire/ — Dow (NYSE: DOW):
FINANCIAL HIGHLIGHTS
- Net sales were $10.4 billion, down 2% year-over-year, reflecting declines in Packaging & Specialty Plastics. Sequentially, net sales were down 4%, led by seasonal declines in Performance Materials & Coatings.
- Volume increased 1% compared to the year-ago period, with gains in most regions. Sequentially, volume decreased 1%, led by seasonally lower demand in Performance Materials & Coatings, partly offset by improved supply availability in Packaging & Specialty Plastics and Industrial Intermediates & Infrastructure.
- Local price was down 3% year-over-year and sequentially, with declines in all operating segments.
- Equity losses were $51 million, down $44 million compared to the year-ago period, primarily driven by lower integrated margins at our Thai joint ventures. Sequentially, equity earnings were down $53 million, driven by lower earnings at our principal joint ventures.
- GAAP net loss was $35 million, or $0.08 per share, including significant items totaling $0.08, primarily from restructuring and efficiency costs. Operating earnings per share¹ was $0.00. Both earnings per share and operating earnings per share include higher-than-expected non-cash tax adjustments of $0.27, primarily related to Argentina, amplified by inflation.
- Op. EBIT1 was $454 million, down $105 million year-over-year, primarily driven by lower prices, which were partly offset by higher operating rates and lower spending. Sequentially, Op. EBIT was down $187 million, reflecting lower integrated margins in Packaging & Specialty Plastics and seasonally lower demand in Performance Materials & Coatings.
- Cash provided by operating activities – continuing operations was $811 million, down $817 million year-over-year, primarily driven by a significant prior period working capital release from destocking. Sequentially, cash from operating activities was up $11 million.
- Returns to shareholders totaled $492 million of dividends in the quarter.
- The Company delivered 2024 full year net sales of $43.0 billion compared to $44.6 billion in 2023. GAAP net income was $1.2 billion, up from $660 million in 2023. Operating EBIT was $2.6 billion, down from $2.8 billion last year. Cash provided by operating activities – continuing operations was $2.9 billion compared to $5.2 billion in 2023. The Company delivered returns to shareholders of $2.5 billion, comprised of $2 billion in dividends and $0.5 billion in share repurchases in 2024.
SUMMARY FINANCIAL RESULTS
| Three Months Ended Dec 31 | Three Months Ended Sep 30 | ||||
| In millions, except per share amounts | 4Q24 | 4Q23 | vs. SQLY [B / (W)] | 3Q24 | vs. PQ [B / (W)] |
| Net Sales | $10,405 | $10,621 | $(216) | $10,879 | $(474) |
| GAAP Income (Loss) Net of Tax | $(35) | $(95) | $60 | $240 | $(275) |
| Operating EBIT¹ | $454 | $559 | $(105) | $641 | $(187) |
| Operating EBIT Margin¹ | 4.4 % | 5.3 % | (90) bps | 5.9 % | (150) bps |
| Operating EBITDA¹ | $1,205 | $1,216 | $(11) | $1,382 | $(177) |
| GAAP Earnings (Loss) Per Share | $(0.08) | $(0.15) | $0.07 | $0.30 | $(0.38) |
| Operating Earnings Per Share¹ | $0.00 | $0.43 | $(0.43) | $0.47 | $(0.47) |
| Cash Provided by Operating Activities – Cont. Ops | $811 | $1,628 | $(817) | $800 | $11 |
| 1. Op. Earnings Per Share, Op. EBIT, Op. EBIT Margin and Op. EBITDA, Free Cash Flow and Cash Flow Conversion are non-GAAP measures. See page 6 for further discussion. |
CEO QUOTE
Jim Fitterling, chair and chief executive officer, commented on the quarter:
“Despite persistently weak macroeconomic conditions, Team Dow delivered our fifth consecutive quarter of year-over-year volume growth, leveraging our cost-advantaged footprint to capture resilient demand for high-value applications. In December, we signed a definitive agreement for the sale of a minority stake in select U.S. Gulf Coast infrastructure assets for expected cash proceeds of up to approximately $3 billion. The partnership represents a new business model designed to drive operational efficiencies and growth with new customers, while providing near-term financial flexibility. We also announced a strategic review of select European assets, and today we are announcing additional actions to deliver $1 billion of targeted cost reductions. These collective actions represent a continuation of Dow’s commitment to maintaining our strong financial foundation and supplementing near-term cash flow.”
SEGMENT HIGHLIGHTS
Packaging & Specialty Plastics
| Three Months Ended Dec 31 | Three Months Ended Sep 30 | ||||
| In millions, except margin percentages | 4Q24 | 4Q23 | vs. SQLY [B / (W)] | 3Q24 | vs. PQ [B / (W)] |
| Net Sales | $5,315 | $5,641 | $(326) | $5,516 | $(201) |
| Operating EBIT | $447 | $664 | $(217) | $618 | $(171) |
| Operating EBIT Margin | 8.4 % | 11.8 % | (340) bps | 11.2 % | (280) bps |
| Equity Earnings (Losses) | $(15) | $40 | $(55) | $16 | $(31) |
Packaging & Specialty Plastics segment net sales in the quarter were $5.3 billion, down 6% versus the year-ago period. Local price decreased 5% year-over-year, primarily driven by lower functional polymers and polyethylene prices. Segment volume was down 1% year-over-year, as polyethylene demand growth was more than offset by lower merchant hydrocarbons and non-recurring licensing revenue. On a sequential basis, net sales were down 4%, primarily driven by lower polyethylene prices.
Equity losses were $15 million, a decrease of $55 million compared to the prior year, led by lower integrated margins at the Thai joint ventures. Sequentially, equity earnings were down $31 million, driven by lower earnings at our principal joint ventures.
Op. EBIT was $447 million, a decrease of $217 million compared to the year-ago period, driven by lower integrated margins, licensing revenue, and reduced equity earnings. Sequentially, Op. EBIT decreased by $171 million, due to lower integrated margins and equity earnings, partly offset by the restart of a cracker in Texas and lower planned maintenance activity.
Packaging and Specialty Plastics business reported a net sales decrease versus the year-ago period, driven by lower functional polymers and polyethylene prices, primarily in Asia Pacific, partly offset by higher demand for flexible food and specialty packaging in all regions except Latin America. Sequentially, net sales decreased, as higher demand for industrial and consumer packaging was more than offset by lower prices.
Hydrocarbons & Energy business reported a net sales decline compared to the year-ago period, driven by lower merchant olefins demand and aromatics prices. Sequentially, net sales decreased, as higher third-party olefins demand from improved supply availability after the restart of a cracker in Texas was more than offset by lower olefins and aromatics prices.
Industrial Intermediates & Infrastructure
| Three Months Ended Dec 31 | Three Months Ended Sep 30 | ||||
| In millions, except margin percentages | 4Q24 | 4Q23 | vs. SQLY [B / (W)] | 3Q24 | vs. PQ [B / (W)] |
| Net Sales | $2,948 | $2,948 | $0 | $2,962 | $(14) |
| Operating EBIT | $84 | $15 | $69 | $(53) | $137 |
| Operating EBIT Margin | 2.8 % | 0.5 % | 230 bps | (1.8) % | 460 bps |
| Equity Earnings (Losses) | $(39) | $(57) | $18 | $(17) | $(22) |
Industrial Intermediates & Infrastructure segment net sales were $2.9 billion, flat versus the year-ago period. Local price declined 1% year-over-year. Volume increased 1% year-over-year, driven by improved supply availability in Industrial Solutions, partially offset by lower volumes in Polyurethanes & Construction Chemicals. On a sequential basis, net sales were flat as seasonal increases in deicing fluid demand offset local price declines and seasonally lower volumes in building & construction.
Equity losses for the segment were $39 million, an improvement of $18 million versus the year-ago period, driven by improved MEG margins at the Kuwait joint ventures. Equity losses in the prior quarter were $17 million. Sequentially, the earnings decline was primarily driven by price declines in Asia Pacific at Sadara.
Op. EBIT increased $69 million versus the year-ago period, primarily driven by higher operating rates and improved supply availability in our Industrial Solutions business. On a sequential basis, Operating EBIT increased by $137 million, driven by lower planned maintenance activity and higher operating rates that were partially offset by local price declines.
Polyurethanes & Construction Chemicals business reported a decrease in net sales compared to the year-ago period, driven by lower volumes primarily in Asia Pacific and Europe, the Middle East, Africa and India (EMEAI). Sequentially, net sales decreased, driven by seasonally lower demand in building & construction applications.
Industrial Solutions business reported an increase in net sales compared to the year-ago period, as local price declines were more than offset by volume gains in all regions on improved supply availability following the restart and continued ramp-up from an outage at Louisiana Operations. Sequentially, net sales increased, driven by higher ethylene oxide project-related catalyst sales and seasonally higher demand for deicing fluids, partly offset by local price declines.
Performance Materials & Coatings
| Three Months Ended Dec 31 | Three Months Ended Sep 30 | ||||
| In millions, except margin percentages | 4Q24 | 4Q23 | vs. SQLY [B / (W)] | 3Q24 | vs. PQ [B / (W)] |
| Net Sales | $1,965 | $1,894 | $71 | $2,214 | $(249) |
| Operating EBIT | $(9) | $(61) | $52 | $140 | $(149) |
| Operating EBIT Margin | (0.5) % | (3.2) % | 270 bps | 6.3 % | (680) bps |
| Equity Earnings (Losses) | $2 | $6 | $(4) | $1 | $1 |
Performance Materials & Coatings segment net sales in the quarter were $2 billion, up 4% versus the year-ago period. Local price decreased 2% year-over-year, primarily driven by lower prices in Consumer Solutions. Volume was up 5% year-over-year, driven by gains in both businesses. On a sequential basis, net sales were down 11%, primarily from seasonally lower demand.
Op. EBIT increased $52 million versus the year-ago period, driven by volume gains as well as lower fixed costs. Sequentially, Op. EBIT decreased $149 million, driven by seasonally lower demand and operating rates.
Consumer Solutions business reported an increase in net sales versus the year-ago period, driven by volume gains across all downstream end markets, led by infrastructure, home care, and electronics, as well as in upstream siloxanes. Sequentially, net sales decreased primarily driven by lower seasonal demand.
Coatings & Performance Monomers business reported an increase in net sales compared to the year-ago period, driven by higher merchant monomers volumes in the U.S. & Canada, which were partly offset by lower volumes in EMEAI. Sequentially, net sales decreased, primarily from seasonally lower demand for pavement markings and architectural coatings.
OUTLOOK
“We remain confident that Dow will benefit from the completion of our near-term incremental growth projects and an enhanced focus on operational discipline in 2025. In addition, we are optimistic that we will see further demand growth in attractive end markets such as packaging, energy and electronics,” said Fitterling. “Our differentiated portfolio and strong balance sheet enable us to deliver on all our capital allocation priorities, including an industry-leading dividend. Until we see more definitive indications of a true recovery taking hold – and in order to deliver improved margins – we are taking actions to reduce our costs by $1 billion as well as our 2025 CapEx plans by $300 – 500 million. We will complete these actions while staying the course on our long-term strategic priorities. Our proactive interventions are necessary for Dow to continue to successfully navigate this economic downcycle.”
January 29, 2025
Investors Who Shunned the U.S. Office Market Are Coming Back
Investors who shunned the beleaguered U.S. office market in recent years are coming back, brightening the outlook for the sector after five years of turmoil.
Some investors are buying premium-quality buildings that are burdened with debt, or scooping up half-empty towers for pennies on the dollar. Others are bidding on obsolete office properties with an eye toward converting them to apartments. Some big foreign investors are showing renewed interest, hoping to beat what they believe will be an even larger surge of buying later in 2025.
“People are making their bets,” said Gary Phillips, managing director of real-estate investment banking firm Eastdil Secured.
The volume of office building sales increased to $63.6 billion in 2024, up 20% from 2023, according to data firm MSCI. That activity still pales compared with 2015 to 2019, when volume averaged $142.9 billion a year. But it marked the first increase since 2021.
And with a lot of cash sitting on the sidelines, brokers expect sales activity to continue to accelerate in 2025. Opportunistic real-estate funds had $196.8 billion available at the end of last year, up from $179.9 billion at the end of 2020, according to data fund Preqin.
Norges Bank Investment Management, the giant Norwegian sovereign-wealth fund, last month purchased the 50.1% stake it didn’t own in eight office properties in Boston, San Francisco and Washington, D.C., in a deal that valued them at $1.9 billion.
Norges last year also bought an office building on Sand Hill Road in Menlo Park, Calif., a strip filled with venture-capital firms. The two deals last year were the fund’s first U.S. office investments since 2018.
“We see an opportunity being a very large capital source that is willing to write checks in a sector that most of our peers are still not willing to invest in,” said John McCarthy, head of U.S. real estate for Norges.
The budding buying spree offers more encouraging news after the rise of remote work and the increase in interest rates greatly depressed office values.
Now, investors point to a pickup in leasing activity as businesses start requiring workers to be back in offices more.
“We hear from customers they’re going to continue bringing more workers back to the office. In many cases, they don’t have enough space to accommodate the transition,” said Colin Connolly, chief executive of Cousins Properties. His firm bought office properties in Atlanta, Austin, Texas, and Charlotte, N.C., recently.
Certain business districts are also experiencing shortages of the most desirable space and rising rents because there has been practically no new development in recent years.
Owners of high-quality office buildings in good markets “should be on much better footing to start the new year than they have in recent memory,” real-estate analytics firm Green Street said in a January report.
A venture of investment manager Hines and Rialto Capital has raised nearly $750 million for a debt fund, after banks and other lenders have fled the office market.
The partnership is targeting well-leased office buildings that are having trouble finding lenders. It is also looking to lend to buyers of office buildings sold at huge discounts from what they were worth before the pandemic.
Office towers acquired at cut-rate prices offer the new owner a lot more flexibility. “By financing an asset reduced in price, it allows owners to lower rents,” said Alfonso Munk, co-head of investment management for Hines.
The office market still faces a number of challenges, including high vacancy rates and loan delinquencies. Many investors remain leery about the sector and favor other types of commercial real estate, such as multifamily buildings or warehouses.
Values for less than premium grade A office buildings are about 35% to 60% lower than they were before the pandemic, according to Green Street.
But more sellers are finally capitulating. Many had been hoping that interest rates would fall further this year, boosting commercial property values. Recently, the Federal Reserve indicated that it would likely keep rates steady, convincing more owners to put their properties on the block.
“Rates aren’t going to be the saving grace that a lot of people thought,” said Dylan Burzinski of Green Street.
Some buyers are even ready to take a chance on buildings that are located in prime locations near transport hubs but are struggling with debt and too much empty space. New York landlord RXR this month acquired a 49% stake in a Midtown Manhattan tower. (The building is home to Fox Corp. and Wall Street Journal owner News Corp.)
The 2 million-square-foot building is losing one of its largest tenants, which will drive vacancy up to about 25%. It also has $1 billion of debt coming due this year, making it tricky to refinance because of high rates.
RXR is planning to invest more than $300 million to attract new tenants by adding a new entrance, new plaza and gym. The firm can afford to do this because its purchase of a 49% stake values the building at $1.3 billion, including the new capital. That is about $700 million less than the building was worth in a 2015 refinancing.
“If we can come in and fix the capital structure, we’ll have no problem leasing the space because the market has gotten stronger,” said Scott Rechler, RXR’s chief executive.
January 26, 2025
Phoenix company buys Nashville mattress manufacturer
3Z Brands to use local office as East Coast e-commerce hub
- William Williams
- Dec 18, 2024
Nashville-based mattress manufacturing company Southerland has been sold for an undisclosed sum.
According to a release, Phoenix-based 3Z Brands is the new owner. 3Z bills itself as a manufacturer, wholesaler, retailer, and direct-to-consumer distributor of sleep products.
In addition to Nashville, Southerland offers manufacturing facilities in Phoenix, Tualatin (Ore.) and Oklahoma City. The company serves wholesale customers in 43 states.
With the acquisition, 3Z will have Southerland’s Nashville location serve as the company’s East Coast e-commerce hub. The release does not note if Southerland will now operate with the 3Z moniker.
The sale comes 3.5 years after Southerland announced plans to lease space in an Antioch facility off Interstate 24, with the move made to increase production capacity by more than a third and yield up to 40 new jobs.
That relocation was necessitated by the November 2020 sale for $6.5 million of the North Davidson County property at which Southerland operated for nearly 50 years (read here). The seller was an LLC that had no affiliation with Southerland.
“This partnership strengthens our ability to serve our loyal customers with the quality they expect while giving us access to new resources and expertise to help us grow,” Bryan Smith, Southerland president, said in the release.
“Together, we’re well-positioned to continue delivering excellence, with exciting opportunities to bring our products to even more customers nationwide.”
With an office also in New York, 3Z operates a portfolio of brands that include Helix, Brooklyn Bedding, Leesa, Birch, Bear, and Nolah.
January 23, 2025
Wood coatings market to reach $15.18 billion by 2030
By Dakota Smith
January 22, 2025 | 11:49 am CST

NEWARK, Del. — The global wood coatings market is poised for significant growth, with demand expected to reach $15.18 billion by 2030. Driven by increasing construction activities, furniture production, and the rising demand for protective and aesthetic solutions, The market is projected to expand at a robust CAGR of 6.2% during the forecast period from 2025 to 2035.
Residential end-user is the largest market for wood protection products, driven by maintenance demand for items such as fences, siding, and decks. Non-residential and non-building use account for a much smaller market for wood protection products.
Market growth drivers:
- Housing market expansion: The steady growth of the housing sector, especially in emerging economies, has significantly boosted the demand for wood coatings. The need for durable and visually appealing wooden furniture and flooring is a major contributor to market growth.
- Preference for eco-friendly solutions: Consumers and industries alike are shifting towards low-VOC (volatile organic compound) and water-based coatings to meet stringent environmental regulations and reduce the carbon footprint.
- Rising renovation and remodeling: The increased frequency of home renovations, spurred by urbanization and lifestyle changes, has escalated the use of wood coatings in the maintenance of doors, cabinets, and furniture.
- Technological advancements: Innovations such as UV-cured coatings and nanotechnology-based products have enhanced the durability, scratch resistance, and aesthetic quality of wood coatings, broadening their applications.
Trends in the wood coatings market:
- Sustainable coatings: As sustainability becomes a priority, manufacturers are developing bio-based coatings derived from renewable resources. These products cater to environmentally conscious consumers and comply with global sustainability goals.
- Growth in UV-cured coatings: UV-cured coatings are gaining traction due to their quick drying times and superior finish, offering cost-effective solutions for industrial applications.
- Customization: Consumers’ demand for unique and personalized finishes has spurred the development of customized color palettes, matte finishes, and textured coatings.
- Expanding applications in construction: Beyond furniture, wood coatings are finding increased use in architectural applications such as wood paneling and decking, driven by growing infrastructural projects worldwide.

January 20, 2025
Extreme Cold, Snow Places Texas Power Grid & Permian On Alert
by Tyler Durden
Monday, Jan 20, 2025 – 03:00 PM
Texas’ top electricity regulator issued a “Weather Watch” from Monday morning through Thursday, citing “extreme cold weather” and the potential for snow, which could send electrical demand soaring across the state.
According to the National Weather Service, snow is forecasted to begin in Houston on Monday evening and accumulate to upwards of 4 inches by Tuesday. After the snow, frigid temperatures are expected to sweep in, bringing dangerously cold conditions that could jeopardize the power grid and energy infrastructure.
“Weather Watch goes into effect today through January 23 due to forecasted extreme cold weather across the ERCOT region, higher electrical demand, and the potential for lower reserves,” the Electric Reliability Council of Texas wrote on X, adding, “Winter precipitation is also expected across parts of the state. Grid conditions are expected to be normal.”
Tony Fracasso, a senior branch forecaster at the US Weather Prediction Center, said, “It’s a significant storm for so far south.”
“It looks like almost the entirety of Texas has some chance of wintery precipitation,” Fracasso noted.
The early alert issued by ERCOT implies that extreme cold could pressure the power grid. ERCOT stated that peak electricity demand is expected to rise over the next two days, reaching about 77.2 gigawatts. Even though ERCOT predicts high demand, it anticipates having sufficient supply to meet demand.
“As freezing temps blanket Texas, the power grid is performing better than ever,” Governor Greg Abbott wrote on X Sunday evening, adding, “There is ample supply of power available to meet your needs.”
Besides potential grid strains, frigid temperatures could curtail natural gas supplies due to the freezing of oil and gas wells and pipes, known as “freeze-offs” by energy analysts.
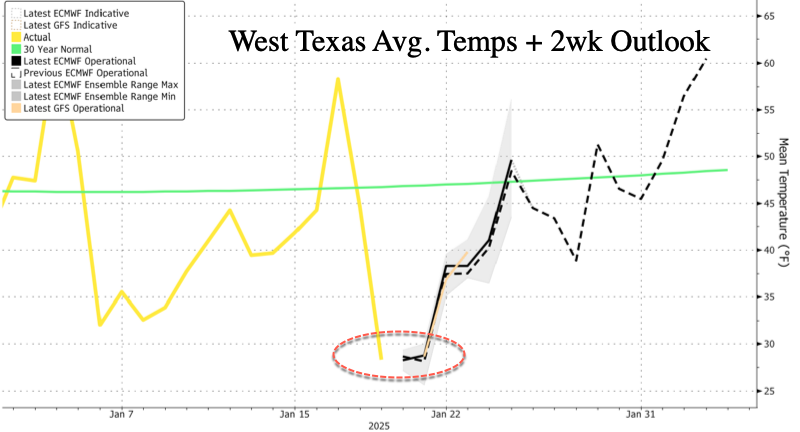
On Tuesday, West Texas temperatures will average around 29F. Through Saturday, average temperatures in the oil-rich Permian basin will remain below the 30-year average of 47F for this time of year. This cold could disrupt oil and gas output by freezing water in wells and pipelines.
Ahead of the snow, Houston Airports announced that flights at George Bush Intercontinental Airport, William P. Hobby Airport, and Ellington Airport will be suspended on Tuesday morning.
The storm is expected to blanket snow across the Gulf Coast and Deep South coastal areas.
Meteorologist Tony Pann questioned if this wintery weather for the Gulf Coast was a “once-in-a-lifetime event“…
Here’s our latest reporting on the polar vortex and energy markets:
- Goldman: “Cold January” & “Record LNG Demand” Drive Upside Risk In Natty Prices
- Incoming: “Big Dumps Of Cold Air. Reminiscent Of 2013/14 Winter”
- Doesn’t Fit MSM Narrative: Parts Of US Could Rival Coldest January Since 1977
- Polar Vortex, Back-To-Back-To-Back Winter Storms Target Eastern Half Of US
Where did global warming go? Please come back.
https://www.zerohedge.com/weather/extreme-cold-snow-places-texas-power-grid-permian-alert
 Everchem Updates Archive
 Sign Up for Email Updates
