
The Urethane Blog
February 4, 2025
Tempur Sealy Cleared to Close Acquisition of Mattress Firm
Feb. 04, 2025 12:10 PM ETTempur Sealy International, Inc. (TPX)
LEXINGTON, Ky., Feb. 4, 2025 /PRNewswire/ — Tempur Sealy International, Inc. (TPX) (NYSE: TPX, “Company” or “Tempur Sealy”) announced today that it expects to close its previously announced acquisition of Mattress Firm Group Inc. (“Mattress Firm”), the nation’s largest mattress specialty retailer, on Wednesday, February 5, 2025. This follows the ruling from the United States District Court for the Southern District of Texas denying the motion by the Federal Trade Commission (“FTC”) for a preliminary injunction to halt the closing of the proposed acquisition. The FTC has indicated that it will not seek emergency relief from the Fifth Circuit and will not prevent the transaction from closing.
Tempur Sealy Chairman and CEO Scott Thompson commented, “We are excited to move forward with our combination with Mattress Firm, which creates the leading vertically integrated global bedding company and which we strongly believe will bring significant benefits to all of our stakeholders.”
Business Update Call
The Company will hold a conference call on Thursday, February 6, 2025 at 8:00 a.m. Eastern Time to discuss the transaction.
The Company has a separate conference call scheduled to discuss the Fourth Quarter and Full Year 2024 financial results on Thursday, February 20th, 2025 at 8:00 a.m. Eastern Time.
The calls will be webcast and can be accessed on the Company’s investor relations website at investor.tempursealy.com. After the conference calls, webcast replays will remain available on the investor relations section of the Company’s website for 30 days.
February 4, 2025
Grace Matthews advises Reaxis on its transaction with TIB Chemicals
MILWAUKEE (February 4, 2025) TIB Chemicals AG (“TIB Chemicals”), headquartered in Mannheim, Germany, has announced that it has acquired Reaxis, Inc. (“Reaxis”), a leading U.S. manufacturer of tin catalysts and metal-based specialty additives. By acquiring Reaxis, TIB Chemicals strengthens its presence in the North American market and reinforces its position as a global leader in tin chemicals, particularly tin catalysts. Together, TIB Chemicals and Reaxis are poised to continue delivering innovative solutions that meet the evolving needs of global markets. Grace Matthews advised Reaxis on the transaction.
ABOUT REAXIS, INC.
Reaxis, Inc. is a leading U.S. supplier of tin catalysts and specialty metal-based additives. Reaxis has built an industry reputation for its product development expertise, scale-up know-how, and dedicated technical support. Reaxis’ chemistries play a pivotal role in delivering cutting-edge performance in its customers’ products and are used in various end markets including polymer synthesis and crosslinking, surface finishing, water treatment, performance chemicals, oil and gas, and peroxide stabilization. For more information, please visit www.reaxis.com.
ABOUT TIB CHEMICALS AG
Founded in 1872, TIB Chemicals AG is a globally oriented, mid-sized company specializing in the development, production, and distribution of high-quality chemicals. With a diverse portfolio of over 1,000 products spanning basic chemicals, inorganic specialty chemicals, and coating systems, TIB Chemicals serves a wide range of international customers through its locations in three countries. With more than 450 dedicated employees who share a passion for chemistry, TIB Chemicals stands out for its extensive 150-year legacy as a family-owned business in the chemical industry. For more information, please visit www.tib-chemicals.com.
ABOUT GRACE MATTHEWS
Grace Matthews, Inc., a Milwaukee-based investment bank, provides merger, acquisition, and corporate finance advisory services to private and public companies across the chemical and material science value chain. Over the past 25 years, Grace Matthews has successfully completed over 150 transactions on behalf of private, middle-market companies, private equity firms, and large multi-national corporations. For more detailed information on Grace Matthews, visit www.gracematthews.com.
February 2, 2025
Tempur Sealy $4B deal for Mattress Firm cleared by federal judge
Feb. 01, 2025 10:22 AM ETTempur Sealy International, Inc. (TPX) StockBy: Rob Johnson, SA News Editor
Update at 2:04 p.m. ET. Adds statement from Tempur Sealy.
A federal judge on Friday cleared Tempur Sealy International’s (NYSE:TPX) $4B takeover of Mattress Firm, rejecting the Federal Trade Commission’s claim that the combination would harm consumers.
U.S. District Judge Charles Eskridge ruled that the companies cannot close the transaction until Feb. 7 to give the FTC time to appeal the decision.
The judge did not disclose his reasons for the decision, which was filed under seal. He cited confidential and proprietary information for his ruling, adding that a redacted version of his full decision will be released Tuesday.
When the deal was first announced in May 2023, Tempur Sealing said it expected the deal to close in the second half of last year.
The FTC sought to block the deal, citing “multiple deal documents” that showed Tempur Sealy’s plans to limit rivals’ access to Mattress Firm and lose access to the single most important retail channel.
“We are pleased the court ruled in favor of completing our previously announced transaction with Tempur Sealy, which we expect to close in the near future,” Mattress Firm Chief Executive John Eck said in a statement to Seeking Alpha.
“We are pleased that the United States District Court for the Southern District of Texas has declined to enjoin our acquisition of Mattress Firm,” Tempur Sealy said in a statement to Seeking Alpha. “Despite the FTC’s ongoing efforts to block the transaction, we will make every effort to close it as soon as possible.”
The FTC did not immediately respond to a request for comment by Seeking Alpha.
February 2, 2025
All About The New Trump Tariffs, And Why The Hysteria Is Overblown
by Tyler Durden
Sunday, Feb 02, 2025 – 02:35 PM
By Peter Tchir of Academy Securities
Some Tariff Basics
Report after report I read seems to jump straight to either the good from tariffs (getting others to pay our taxes, advantage to American manufacturing, etc.) or to the doom and gloom of tariffs (inflation, trade wars, etc.). While we all understand the basics of tariffs, or at least I think I do, it seems worth spending a minute or two making sure that we are all on the same page.
My understanding is that the importer of a good pays the tariff to the government at the port or place of entry of the good into the country.
So, if you pay $100 for something from Canada or Mexico, you pay a $25 tariff, and your cost has increased to $125.
Which begs the question – who pays the $25 tariff?
One of the first things most importers will do is ask for a reduction in price from the exporter. If I was doing business thinking that something was only going to cost $100 and it now costs $125, I’d try to negotiate my purchase price down.
What I find “interesting” is if the exporter takes a 20% haircut, the price stays at $100. 20%off of $100 is $80. Then a 25% tariff on something for $80 is $20, getting us back to $100.
Step 1 is getting a discount, where even a 10% discount means the tariff only increases costs by 12.5%.
Now let’s look at the FX market (which maybe we should have done before step 1, but it would be a pain to rewrite stuff, and it isn’t really a step, as it is outside the control of the importer and the exporter, though no less important).
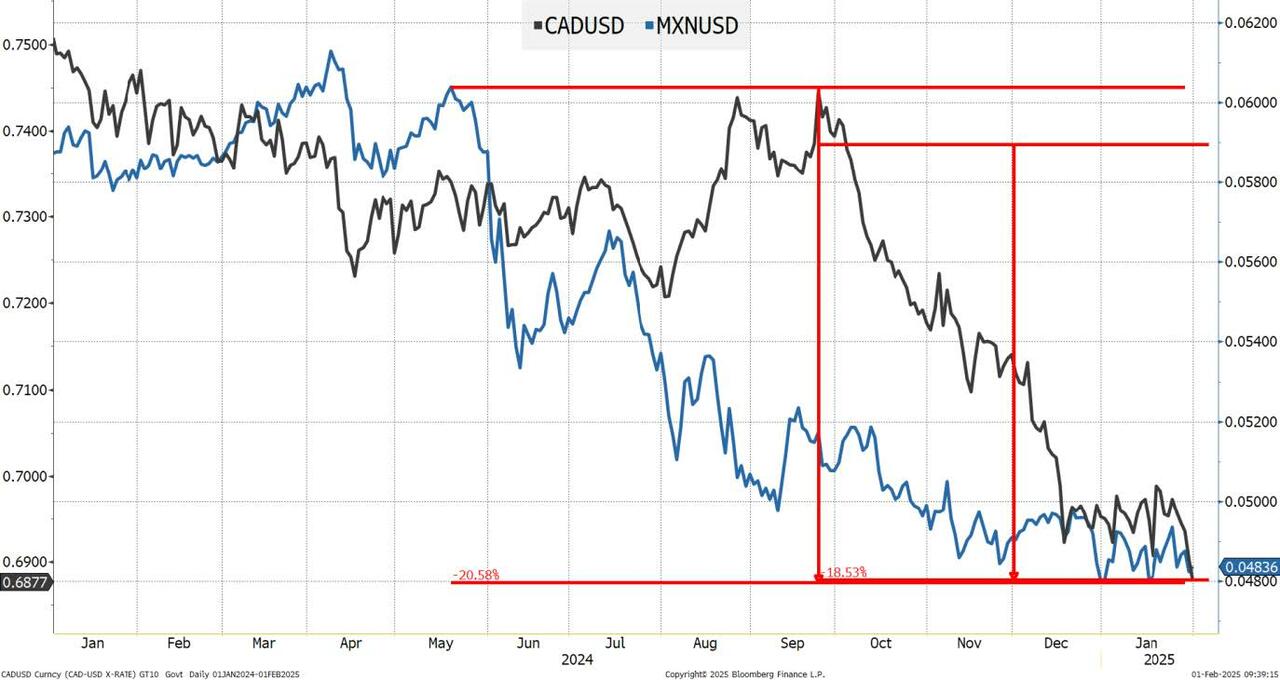
Since the summer, the Peso has declined by 20% versus the dollar and since late September, the Canadian Dollar has dropped by around 18%.
Let’s say that back in September, a Canadian exporter was happy to get paid 135 CAD. That translates into 100 USD for the importer. Let’s say that the Canadian exporter is still happy to accept the equivalent of 135 CAD. That drops the USD price to 93 for the importer. Making the “new” cost to the importer, including the tariff, “only” $116.25. This is all moving around in real time and has been a cumulative move, so this is a massive oversimplification, but still relevant.
The currency market is already helping the importer.
Step 2 is for the importer to figure out what amount of profit he is willing to forgo, if any. Assuming the importer was paying $100 it seems reasonable to assume that the price for the consumer is significantly more. For argument’s sake, let’s say the final price was $200. There is distribution and selling costs, etc. that the importer pays to sell the product on to the next leg. Maybe $200 is too high? Possibly, but I’m not sure it is that unreasonable for many finished goods. Now $25 out of $200 is “only” 12.5%. Giving up 12.5% is probably too much, but is 5% reasonable?
So, let’s look at this possibility (which as a whole, doesn’t seem too far-fetched to me).
Negotiate a 10% discount from the Canadian or Mexican exporter. Argue that it is “temporary” but crucial if you don’t want me (the importer) looking for alternative suppliers. Add in that you (the exporter) will also take a hit.
So, the Canadian exporter reduces the cost from 135 CAD to 121.5 CAD (in hopes it is temporary, and they don’t want to risk losing this customer to another provider of such goods).
Due to the big increase in the USD, the cost is only $83.40 (the importer has been making a lot of extra money in the past few months, but that is always a risk and may well have been hedged).
The 25% tariff is $20.85, bringing the total cost to $104.25.
In your planning, as of a month or two ago, you were anticipating a cost of $100. It is now just under $105. Do you raise your final prices, or leave them, at least for a little while, anticipating Canada (or Mexico) will make progress on fentanyl and the tariff will go away? That seems at least plausible, and it might depend on how easy it is for you to raise and lower prices. Is the hit to profit margin, hopefully a temporary one, worth not having to deal with a new supplier?
If the alternative supplier is Canadian or Mexican, they have the same problem.
If the supplier is from elsewhere, presumably there will be some logistics in getting their goods over in time.
The alternative, an American supplier, does look better as they were just given an effective cost benefit, but not really a 25% cost benefit. The dollar strength takes away some of the desire to shift to a domestic supplier. Presumably, the domestic supplier was already more expensive (or not as good, or there is some other reason why they weren’t being used). So, even with the indirect competitive boost, is it worth it?
Read more here: https://www.zerohedge.com/markets/all-about-new-trump-tariffs-and-why-hysteria-overblown
January 30, 2025
Dow Inc. (DOW) Q4 2024 Earnings Conference Call Transcript
Jan. 30, 2025 11:21 AM ETDow Inc. (DOW) Stock
Dow Inc. (NYSE:DOW) Q4 2024 Earnings Conference Call January 30, 2025 8:00 AM ET
Company Participants
Andrew Riker – VP, IR
Jim Fitterling – Chairman and Chief Executive Officer
Karen S. Carter – Chief Operating Officer
Jeff Tate – Chief Financial Officer
Jim Fitterling
Thank you, Andrew. Beginning on Slide 3, there’s a lot to unpack in our results this quarter, so let me first walk through the headlines. In the fourth quarter, Team Dow delivered our fifth consecutive quarter of year-over-year volume growth despite continued weak macroeconomic conditions. Net sales were $10.4 billion, which is down 2% versus the year ago period, and reflects pricing pressure seen across the industry in the quarter.
Local price was down 3% year-over-year and sequentially with declines across all our operating segments. Operating EBITDA was $1.2 billion, which is approximately flat compared to the same period last year. Cash flow from continuing operations was $811 million, resulting in free cash flow of $44 million. Returns to shareholders totaled $492 million of dividends in the quarter, and our total CapEx spend was $767 million.
As you saw in our numbers this quarter, we also had a non-cash tax adjustment impacting net income and EPS. Jeff will provide more details on that later in this call. Throughout the quarter, we announced additional actions that continued to support the optimization of our global portfolio for growth, while maintaining a best owner mindset. For example, we continued to ramp up operating rates at our Texas-8 cracker and Glycol 2 unit. We completed the sale of our flexible packaging laminating adhesive business to Arkema for an enterprise value of approximately $150 million. And we’ve designed a definitive agreement with Macquarie Asset Management for the sale of a minority stake in select U.S. Gulf Coast infrastructure assets for which we expect to receive cash proceeds of up to $3 billion.
And driven by persistently weak global macroeconomic conditions, we announced a strategic review of select European assets, primarily in our polyurethanes business, where demand has been structurally challenged over the past five years, making it the highest cost region for several of our key businesses. We are also postponing a maintenance turnaround at one of our ethylene crackers in Europe. This decision will result in us idling this asset starting in second quarter until market dynamics improve.
And today we announced targeted actions to reduce our costs by $1 billion and our CapEx by $300 million to $500 million. Collectively, the additional actions are focused on reinforcing our long-term competitiveness as we continue to navigate this prolonged economic downturn.
Turning to Slide 4. In 2024, Team Dow continued to advance both our near-term priorities and our long-term strategy to become a stronger, more innovative company. We delivered net sales of $43 billion, operating EBIT of $2.6 billion, and year-over-year volume growth of 3%, excluding merchant hydrocarbon sales. Earlier in 2024, we began construction at our Path2Zero investment in Fort Saskatchewan, Alberta. When complete, the project is expected to generate approximately $1 billion in incremental EBITDA annually by 2030.
Dow is also recognized externally through industry-leading awards and certifications. Last year, we earned 12 Edison Awards for Innovation and Great Place to Work and Fortune, named out as one of the top 25 world’s best workplaces. Team Dow navigated several challenges over the past year, including weather-related and supply chain disruptions, and continued uncertainty in many regions and markets that we serve. And in response to evolving market dynamics and sluggish demand recovery in Europe, we demonstrated our best owner mindset with more than 20 proactive actions to address higher cost assets.
I remain confident in our company’s ability to foster a sustainable future, achieve long-term profitable growth, and enhance shareholder returns.
Now, I’m pleased to turn it over to Karen S. Carter, Dow’s Chief Operating Officer, who will provide an overview of our operating segment performance on Slide 5.
Karen S. Carter
Thank you, Jim. I’m pleased to join you all today. And before I begin, I’d like to mention what an honor it is to be named Dow’s Chief Operating Officer. I look forward to engaging with many of you, our owners, in the near future. In my more than 30 years at Dow, I have progressed through the organization to most recently leading PNSP, the company’s largest operating segment. And I have worked across a broad range of businesses and functions, including global leadership positions within the building and construction and consumer electronics and markets, as well as Dow’s polyethylene franchise. This has given me a deep appreciation for our company’s competitive advantages, the strength of our innovation engine, and our commitment to delivering profitable growth.
As COO, my priorities are to further strengthen our customer engagement, accelerate the commercialization of Dow’s innovation pipeline, and enhance reliability and productivity. I am committed to driving business and operational results, while progressing our strategic priorities to deliver long-term value for our shareholders.
Moving to the Industrial Intermediates & Infrastructure segment. We benefited from strong global energy demand, as well as stable consumer and pharma demand. We also experienced typical seasonal improvements for deicing, while agricultural and coatings applications saw normal seasonal declines. Looking at fourth quarter results, local price declined 1% year-over-year, while volume was up 1% year-over-year. This was driven by improved supply availability in our Industrial Solutions business as we finished ramping-up our Glycol-2 unit ahead of schedule. Those gains were partly offset by continued softness in the Polyurethanes and Construction Chemicals business.
Operating EBIT for the segment increased $69 million versus the year-ago period. Results were primarily driven by higher operating rates and improved supply availability in the Industrial Solutions business. And in the Performance Materials & Coating segment, volume was up 5% with strong gains across both architectural coatings and downstream silicones. We achieved this despite global weakness in building and construction end-markets as high-interest rates continue to pressure spending in residential markets. Operating EBIT increased $52 million compared to the year-ago period, driven by volume gains and lower fixed costs.
Jeff Tate
In the Industrial, Intermediates & Infrastructure segment, we anticipate lower margins in our polyurethanes business from higher energy costs as well as lower catalyst sales in our Industrial Solutions business. In the quarter, we have planned maintenance activity scheduled at our ethylene oxide asset in Freeport, Texas, which will enable the start-up of additional alkoxylation capacity in the US Gulf Coast. This new capacity is one of the near-term growth investments we outlined at our last Investor Day and should support higher sales beginning in the second-quarter.
On a final note, last week the US Gulf Coast was impacted by a powerful winter storm. Our manufacturing sites have managed well, but we continue to monitor any further developments both at our sites, as well as across the industry. The current guidance does not include any impact favorable or unfavorable stemming from the storm.
Jim Fitterling
Thank you, Jeff. On Slide 8, in the midst of the prolonged downturn and slower-than-expected economic recovery that our industry is experiencing. Now it’s taking several key actions to further reduce our costs and reinforce our long-term competitiveness through the economic cycle.
First and foremost, we’re taking additional targeted actions aimed at improving our margins. We announced today that we will implement cost reductions of $1 billion on an annual run-rate basis by 2026. These actions will be primarily focused on third-party contract labor and purchase services. In addition, we are targeting the elimination of approximately 1,500 Dow roles. Last quarter, we announced that we would kick-off a strategic evaluation of our European asset footprint, and we’re on-track to provide an update on this work by mid-2025.
Lastly, as we complete our in-flight higher return growth projects this year, we’re also taking actions to preserve our strong financial foundation. We intend to recalibrate our CapEx deployment to match the current demand and macroeconomic conditions and we’ll do so by reducing our 2025 spending by $300 million to $500 million compared to our previously disclosed target of $3.5 billion. We will keep CapEx spending roughly at these levels until we see a clear recovery materialize across broad portions of the end-markets that we serve.
Turning to Slide 9. We continue our ongoing practice of reviewing our global portfolio. Last month, Dow entered into a definitive agreement to sell 40% equity stake in select infrastructure assets to Macquarie Asset Management, a leading global infrastructure investor. We anticipate the transaction will close by mid-2025. This newly formed infrastructure-focused company named Diamond Infrastructure Solutions is comprised of assets that support a wide range of services at five of Dow’s manufacturing sites along the US Gulf Coast. The new company will operate within Dow and has a dedicated management team with priorities in support of Diamond Infrastructure Solutions strategy.
Importantly, Dow will maintain operational control to ensure our standards for safe and reliable operations are upheld. This transaction is expected to generate approximately $2.4 billion of initial cash proceeds for Dow. Macquarie Asset Management has the option to increase their minority equity stake to 49% within six months of closing, which would increase cash proceeds to approximately $3 billion for Dow if exercised. The long-term partnership leverages Dow’s operational excellence and Macquarie Asset Management’s world leading infrastructure positions to generate incremental operational efficiencies, as well as future growth opportunities with existing and new customers. With enhanced financial flexibility from this partnership, Dow is in a strong position to continue to invest in growth and deliver enhanced returns to our shareholders, particularly as market conditions improve.
Closing on Slide 10, as we navigate a challenging near-term environment, we are committed to a disciplined and balanced approach to delivering our cash and capital allocation priorities. Our ability to proactively manage in an extended economic downturn will position Dow well for long-term success. As I mentioned earlier, last week we postponed a maintenance turnaround at one of our ethylene crackers in Europe. This decision will result in us idling this asset starting in second quarter until market dynamics improve. This reduction in planned turnaround spending will keep 2025 turnaround spending levels in-line with the prior year. We will continue to match supply with profitable demand until margins improve.
We continue to take proactive strategic actions to optimize our global footprint, drive operational performance and reduce our costs and capital expenditures. In 2025, our additional cost actions and reduced CapEx spending will help us to enhance near-term cash-flow, margins and earnings growth, while remaining committed to our long-term strategic priorities.
In addition, our signed agreement with Macquarie Asset Management further strengthens Dow’s financial flexibility and the potential to generate up to $3 billion in cash proceeds in 2025. This transaction is consistent with Dow’s best owner mindset and track-record of delivering unique to Dow cash-flow levers to mitigate cyclical volatility. We’re optimistic that we will continue to see demand growth in attractive end-markets such as packaging, energy and electronics. And once completed, our near-term growth investments, representing higher-return and quicker payback projects will enable improved underlying earnings and margins across the cycle.
With a differentiated portfolio and proactive actions to support our solid financial foundation, we are confident in our ability to deliver on all of our capital allocation priorities, including our industry-leading dividend. At the same time, we will continue to maintain our focus on operating and financial discipline to drive long-term shareholder value to ensure that we remain well-positioned for the cycle recovery.
Chris Parkinson
Great. Thank you so much. Jim, just want to dive a little deeper. I think we did it last-time, just how you’re thinking about some of the EU assets by country. And I think last summer you were going over the Netherlands and Germany. And there are a lot of strategic reviews going on in Intercontinental Europe right now. So just trying to think about the — how you fit into like the larger picture in terms of these developments and how they’re basically panning out over the next several years? Thank you.
Jim Fitterling
Sure. That’s a great question, Chris. If you look at the EU, obviously, the number one challenge is energy competitiveness. And so, relatively speaking, Spain has a pretty decent advantage right now from an energy standpoint. So there, we’re looking with our partners at Repsol and how do we reduce the combined cost between the two of us on operations in Spain. When you get to the Netherlands, while we announced the idling of a cracker to avoid the turnaround cost this year, I don’t want you to assume that that’s the answer to the European strategic review and if that really is just something that we have the ability to do this year to manage through the short-term situation.
The Netherlands has been pretty competitive throughout and our cost positions have been pretty good there. So we just have to look at the market for ethylene. We’re a net merchant ethylene seller, we got to look at those balances and we’ve got to look at the propylene market and balances and that will drive what we decide to do there. I’d say that the Netherlands as a country still very focused on energy and discussions recently. They still have a focus themselves on adding nuclear power generating capability, which I think is going to help them with their energy costs.
On Germany, a lot is going to depend on this election at the end of February. I think it’s shaping up that there will be a change in the German government. And if you look at what happened post-COVID, Germany moved fast to take action when the Russian supply on gas was stopped and now has five LNG import facilities operating and it’s really shifted the balance on LNG imports. However, the LNG import costs are $10 to $15 a million BTU into Europe. So longer-term, we have to look at what else can we do in Germany structurally to get the cost-down.
I think it’s going to require state action to make that happen. I don’t think the EU is going to do something that drives this. I think it’s going to require the states pushing back and there’s no state that has more heft in this discussion than Germany.
Frank Mitsch
Yes, thank you. Good morning and congratulations, Karen, on your new role. Jim, I want to ask about the III segment in terms of the first-quarter. You’re calling out $100 million sequential headwinds, mostly from one-offs excluding higher energy. Can you talk about what you’re seeing in terms of the pace of business between the polyurethanes and Construction and Industrial Solutions segments? One would thought this US Gulf Coast freeze would be fantastic for your de-icing business, etc. So can you give us — absent kind of these one-offs, what is really going on in those businesses as we sit here in the first-quarter?
Jim Fitterling
Karen, why don’t you unpack that?
Karen S. Carter
Yes. No, thanks for that question. So if I look at the first-quarter and I’ll take polyurethanes and construction chemicals first. We’re not really seeing any signs of demand recovering despite the interest-rate cuts in the US and Europe. And as you know, we have several applications in that business that are really sensitive to interest rates. So whether you’re talking about betting and furniture, but also obviously in the housing applications as well. And if you think about US home affordability, it remains at its historic lows, but then also interest rates there are above 7%.
We also saw in the fourth quarter automotive start to slow. And if you think about that from a US perspective, those inventories are at 10 years high — 10-year highs. And so that’s one of the reasons that we announced on the last earnings the strategic review of our European footprint, really where we’re looking at polyurethanes in particular. And so then if I pivot to DIS there, what I would say is that overall demand really does remain stable. We are seeing some green shoots and global energy demand and also pharma demand, which is really good for us.
De-icing, as you indicated, is a seasonal tailwind. So we’ll see if the cold weather continues to persist. But then one of the things that’s notable in the first-quarter around DIS is that we do have increased turnaround there where we’re taking our unit and Seadrift down. So that will result in a tailwind for us. So I would say overall, on the polyurethane side, just continuing to see challenging market demand, market macros. But then also on the Industrial Solutions side, with the continued ramp of Glycol-2 that’s now fully back, we should see a tailwind there. But again, some of that is being muted with the turnaround that we see in first-quarter.
Aleksey Yefremov
Thanks. Good morning, everyone. I wanted to clarify if your $1 billion cost-reduction target includes the European actions that you will be discussing in the middle of 2025 or would those European actions be in addition to the $1 billion?
Jim Fitterling
You’ll have them in addition. I think there are some things that will probably have a little bit of overlap, but the asset discussions will be in addition to what we’ve just announced.
 Everchem Updates Archive
 Sign Up for Email Updates
