
Asian Markets
May 29, 2023
PO Trade Flows in the Future
Will Shutdown of Dow’s PO Plant in U.S. Change Asian Trade Flow?
PUdaily | Updated: May 29, 2023
The end-users of propylene oxide (PO) include industries such as real estate, automobiles, furniture, refrigerators, and freezers, which are closely related to the development of the national economy. An increase in demand for polyurethane due to the rise in the prosperity of these industries will stimulate polyols suppliers to increase production, thereby increasing the demand for PO and driving up prices.
On May 16, it was reported that Dow Chemical plans to close its PO plant in Freeport, Texas, by the end of 2025.
The decision to close the PO plant arose from the fact that the plant is approaching its end-of-life, and the overall chemical industry is not prosperous due to the slowing global economic growth and various uncontrollable factors. The demand from most end-users is weakening, and polyurethane suppliers are paying more attention to higher value-added segments. Therefore, the decision to close the plant is part of Dow Chemical’s efforts to optimize costs and supply conditions.
Dow’s PO plant in Freeport will continue to operate until the end of 2025, while downstream polyether polyol plants will continue to operate after the PO plant is shut down. After 2025, Dow will use resources from other regions or third-party suppliers to supply PO to its polyol plants. Dow is also investing in logistics capabilities, such as PO tanks, pipelines, and new barges to ensure the normal supply.
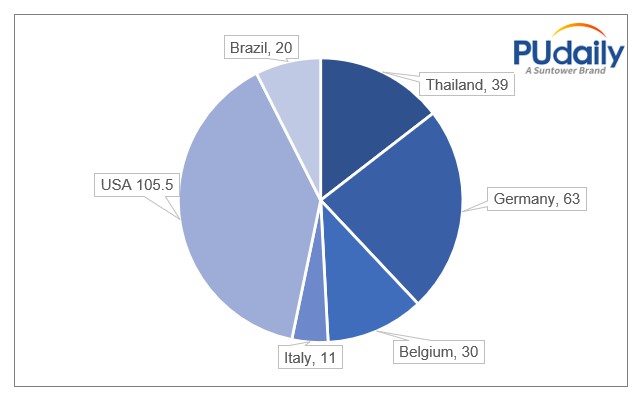
Currently, Dow Chemical is the world’s largest PO producer with an extensive layout of plants in the U.S., Germany, Brazil, Belgium, and Thailand. Its total capacity is 2.685 mtpa, contributing 20.24% of the global PO output.
Dow Chemical’s PO Capacity Layout (10kT)
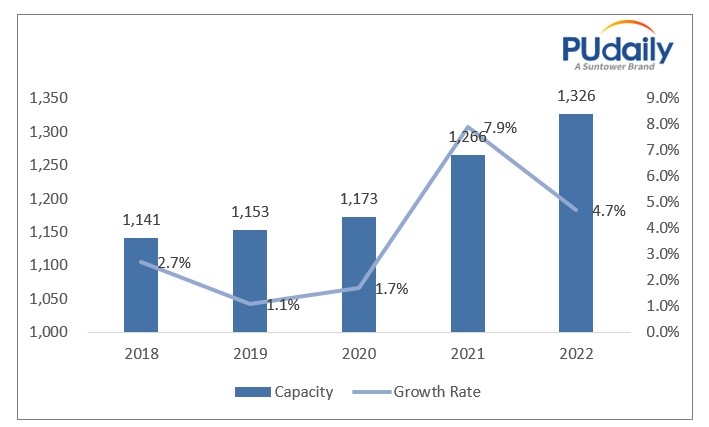
Global PO Capacity & YoY Changes, 2018-2022 (10kT, %)
Dow’s PO production uses the chlorohydrin process technology. The patent owners of the chlorohydrin process are mainly Dow in U.S., Asahi Glass, Mitsui Toatsu and Showa Denko in Japan. The chlorohydrin process was industrialized as early as 1931 and has the advantages of mature technology, short process, low purity requirements for raw materials, and low investment. The key of this technology is the chlorohydrin reactor, and Dow Chemical’s tubular reactor is representative of the chlorohydrin process.
But the chlorohydrin process causes severe environmental pollution, and under the background of increasingly stringent environmental regulations, the use of chlorohydrin technology faces enormous challenges. The US government has already eliminated chlorohydrin technology in 2000, and China has also listed chlorohydrin process as a restricted item in the Guidance Catalogue for Industrial Structure Adjustment (2011), and new facilities cannot adopt this technology.
The shutdown of Dow’s PO plant in the U.S. will cause a supply gap. Part of the gap will be filled by LyondellBasell (In March of this year, LyondellBasell successfully started up the world’s largest PO and TBA plant in Texas. These new assets on the U.S. Gulf Coast have an annual capacity of 470,000 tonnes of PO and 1 million tonnes of TBA and its derivatives). Some PO suppliers in countries such as South Korea, Saudi Arabia, and Thailand will also increase exports to the U.S. China’s PO export is constrained by process requirements and lack of export tax refunds. The tax rebate rate for downstream products of PO, such as polyether polyols, propylene glycol, and propylene glycol methyl ether, has been increased to 13%, further enhancing their export competitiveness.
May 29, 2023
Wanhua Starts TDI Plant
Wanhua’s 250kT TDI Facility in Fujian Starts Production, Phase II 300kT TDI Project is Around The Corner

PUdaily | Updated: May 24, 2023
On May 22, 2023, Wanhua Chemical successfully started its 250kT TDI facility in Fujian with producing qualified products, marking another breakthrough in the TDI industry, according to the company announcement. With this, Wanhua now has four TDI production bases globally, with a total production capacity of 950 ktpa, including 300 ktpa in Yantai, 250 ktpa in Fujian, 250 ktpa in Hungary, and 150 ktpa at former Juli Group’s plant. The company contributes 30% of the global TDI capacity, making it the largest TDI supplier in the world.
Meanwhile, Wanhua Chemical is preparing to launch its Phase II 300 ktpa TDI project in Fujian, according to public information. It is estimated that Wanhua’s TDI capacity in Fujian will exceed 550 ktpa after the operation of its Phase II 300 ktpa facility. Based on the construction speed of Wanhua’s previous projects, it is likely that the Phase II TDI facility in Fujian will start operating at the end of 2024.
The global TDI consumption will be around 2 million tonnes in 2023 and roughly 2.4 million tonnes in 2025, according to Pudaily’s forecast. It is estimated that global TDI capacity will reach 3.515 mtpa after the completion of Wanhua’s Phase II 300 ktpa TDI facility in 2024. In the future, the TDI supply-demand balance will continue to tilt, and the oversupply situation will become prominent, leading to intense competition.
May 16, 2023
Chinese Mattress Exports
China Mattress Exports Increase Significantly in Q1 2023
PUdaily | Updated: May 16, 2023
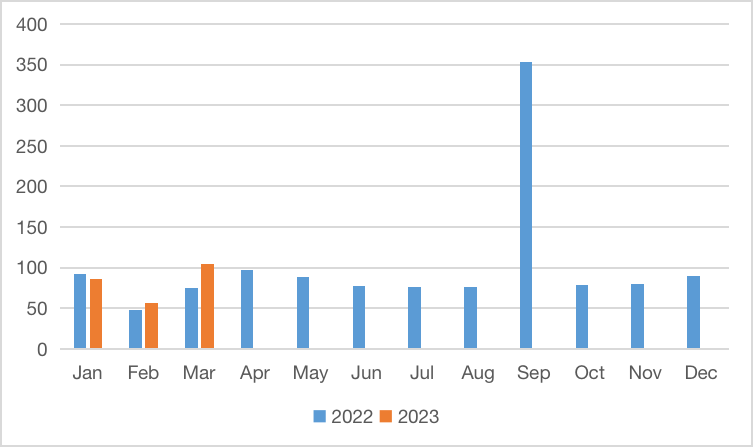
China exported a total of 2.457 million spring mattresses in the first quarter of 2023, a year-on-year increase of 14.8%. The export value reached USD 194.02 million, a year-on-year increase of 2.5%, according to customs data.
Figure 1: China Spring Mattress Export, 2022-2023 (10,000 pieces)
China exported a total of 7.511 million foam mattresses in Q1 2023, a year-on-year increase of 7.9%. The export value was USD 163.93 million, which remained basically stable compared to the same period last year.
Figure 2: China Foam Mattress Export, 2022-2023 (10,000 pieces)
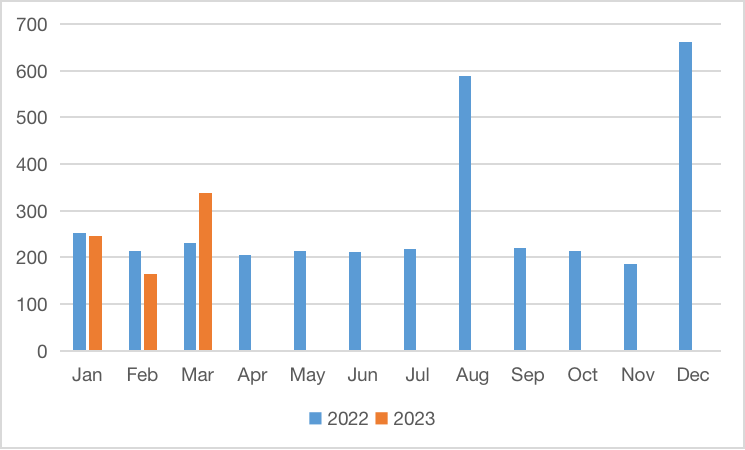
It is noteworthy that although the export volume increased significantly year-on-year, the growth rate of export value was significantly smaller, and the unit price and profit for exports declined year-on-year.
From January to March 2023, the operating revenue of furniture manufacturers above designated size in China totalled CNY 148.59 billion, a year-on-year decrease of 13.2%; operating costs reached CNY 123.12 billion, a year-on-year decrease of 14.3%; and their total profit was CNY 5.56 billion, a year-on-year decrease of 12.6%, according to the National Bureau of Statistics of China.
Looking at the quarterly reports of listed companies in Chinese home furnishing industry, among nearly 120 home furnishing companies that had already published their reports this quarter, 83 companies experienced a decline in revenue and 29 companies suffered losses.
However, the prosperity of China’s real estate industry in the first quarter partially restored, with housing completions accelerating growth in March and home sales keeping recovery. In terms of end-user spending, there have been signs of a rebound in domestic and foreign consumption. Offline store traffic has significantly increased. Under sales promotions, some demand for replacement in mature markets has been boosted. It is predicted that China’s home furnishing market will experience marginal improvement in the near future.
May 11, 2023
Chinese Furniture and Mattress Overview
Upholstered Furniture Market Situation & Trends
PUdaily | Updated: May 9, 2023
Upholstered furniture refers to furniture added with padding, foam, fabric and other materials. This involves sofas, upholstered beds, mattresses, nightstands, coffee tables and other relative products. Among them, mattresses and sofas are the two main types of upholstered furniture. The industrialization of upholstered furniture began in Europe in the early 20th century. Global upholstered furniture industry has greatly increased its production capacity thanks to continuously advanced manufacturing technologies, and the market demand has also kept growing.
As the upholstered furniture industry is labor-intensive, developed countries are continuing to transfer their manufacturing to developing countries, which have low labor costs and sufficient raw materials. The main upholstered furniture manufacturing countries currently include China, U.S., Poland, India, Italy, and Germany.
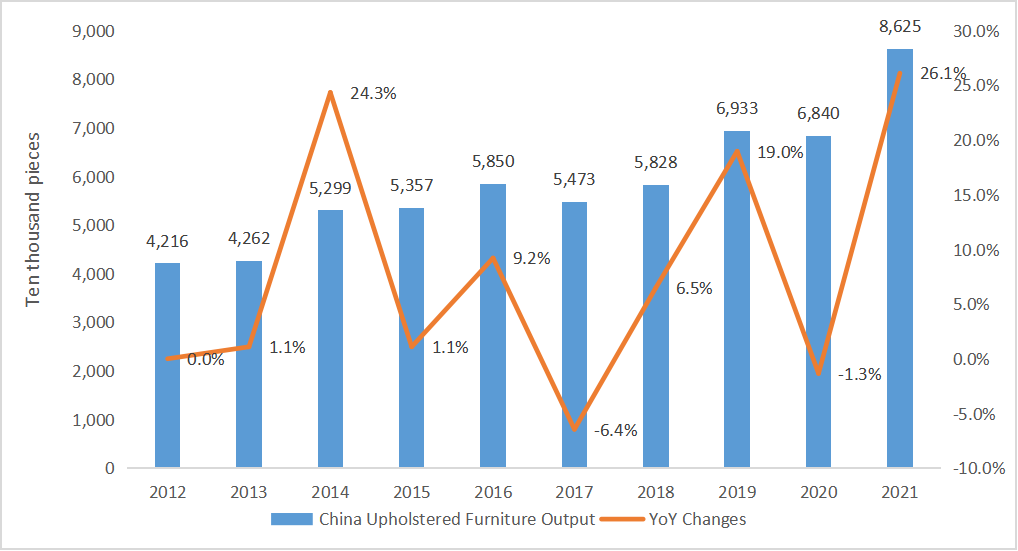
China has become one of major producers and consumers of upholstered furniture. China’s modern upholstered furniture industry began in the early 1980s. In recent years, through introduction of advanced furniture design technology and processing technology from abroad, and on the basis of fully leveraging the advantages of raw material resources and labor costs, China’s upholstered furniture industry has developed rapidly. At present, China’s upholstered furniture output value makes up 46.4% of the world, contributing about 30.7% of the global upholstered furniture consumption.
Figure 1 China Upholstered Furniture Outputs & YoY Changes, 2012-2021
The upholstered furniture industry has a long industrial chain that spans agriculture, manufacturing, and retail industries. Its upstream industries mainly include leather, wood, foam, and other raw material industries. Downstream manufacturers mainly sell products to end consumers through channels such as dealers, ODMs, and direct-sale stores. Leather is mainly used for the outer surface of upholstered furniture, primarily natural cowhide. Wood is mainly used for the main structure of upholstered furniture, and the development of forest planting directly affects the wood supply and procurement costs of the upholstered furniture industry. Foam, namely polyurethane foam, is a typical cushioning material mainly used for cushions, armrests, backrests, etc., to improve the softness and comfort of upholstered furniture. It is made from polyurethane through processes such as foaming, hot pressing, and cutting, and is a derivative product in the petrochemical processing industry. Therefore, its price is greatly affected by fluctuations in oil prices. Downstream manufacturers of upholstered furniture mainly sell products to end users through direct-sale stores, dealers, etc., and factors such as household income and real estate industry development drive consumer demand.
Commodity prices have risen sharply since 2021. The low added value and high cost of the upholstered furniture industry have been greatly affected by rising raw material prices. Meanwhile, under the policy of “housing is for living, not for speculation”, the prosperity of the real estate industry has significantly declined, which also brings obvious suppression on the demand for upholstered furniture. Under the dual impact of rising costs and weakening demand, the overall profit margin of the upholstered furniture industry has significantly decreased. Especially for small and micro manufacturers that rely on price advantages, their survival space has been squeezed.
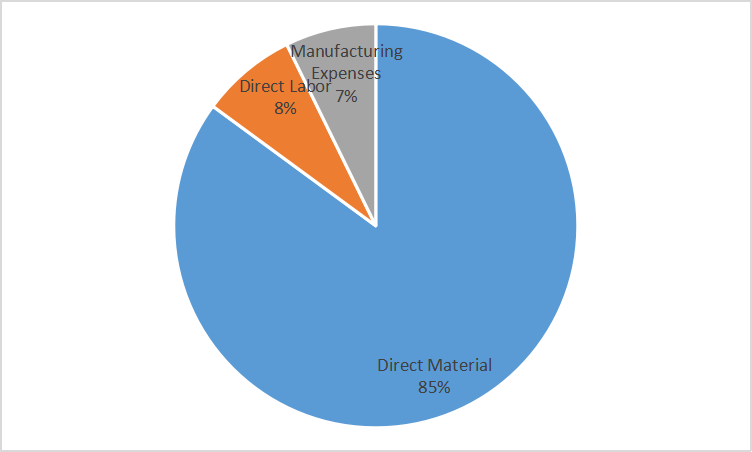
Figure 2 Cost Structure of a Mattress Manufacturer
In the future, China’s upholstered furniture industry could follow two important directions:
1) A boom in established market:
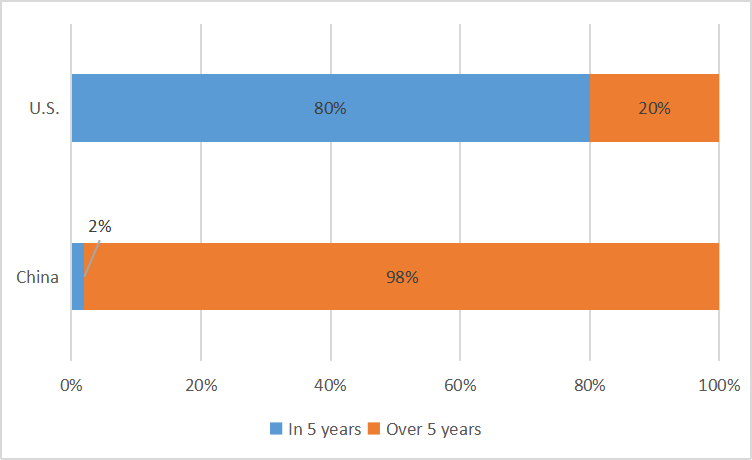
A few decades ago, spring mattresses were popularized in China. For a spring mattress, the lifespan of spring is usually 10-20 years, and that of filler and fabric is about 5-10 years. At present, the frequency of mattress replacement in China is much lower than that in U.S. 37% of Chinese consumers replace mattresses in 10-15 years, while 47% of consumers have never changed them, which are mostly under serviceability limit state. We believe that increasingly frequent mattress replacement and higher requirements for comfort level of beddings may boost the demand for mattresses.
Figure 3 Mattress Replacement Frequency in China
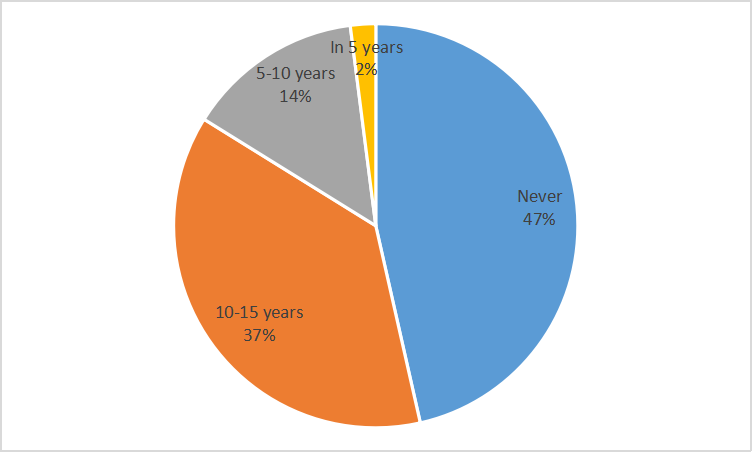
Figure 4 Comparison of Mattress Replacement Frequency in China and U.S.
2) Rising industrial concentration:
At present, China’s sofa industry is fragmented. CR4 (the concentration ratio of the top four manufacturers) in China was only 30% in 2021, with Man Wah holding the largest market share (about 12%); the concentration of U.S. sofa industry was higher, with CR4 reaching 51% and CR10 reaching 79% in 2017, and the market share of top manufacturers la-z-boy/Ashley/Man Wah reached 21%/11%/10% respectively.
In terms of the mattress industry, the U.S. market is dominated by a few top brands, while Chinese mattress market is inundated with small and medium-sized manufacturers.
The top 5 brands in U.S., (CR5), Sealy, Simmons, Serta, Tempur-Pedic and Sleep Number, together occupied 69.40% of the mattress market. CR3 and CR8 in China’s mattress market are only 11.43% and 18.66%. The market share of top three brands – Sleemon, Serta and DeRucci – is 4.38%, 3.88% and 3.17% respectively.
With the improvement of residents’ consumption levels and the broad demand for mattress replacement, top manufacturers with advantages in brand, channels, and services are expected to usher in a significant growth in the next few years.
May 8, 2023
Hydrogen Peroxide Accident Impacts HPPO Production in China
Impact of Explosion at Luxi Chemical’s Hydrogen Peroxide Plant
PUdaily | Updated: May 6, 2023
On May 1 at 12:20 pm, an explosion occurred at the hydrogen peroxide production area of Luxi Chemical, a subsidiary of Sinochem Holdings. The preliminary investigation found that when recovering the fluid, a large amount of 70% hydrogen peroxide had leaked into the kettle of the hydrogen peroxide device. The impurities in the kettle caused the hydrogen peroxide to decompose, causing overpressure explosions in the kettle that triggered explosions in the adjacent octanol storage tanks and pipeline leaks. Nine workers died, one was injured, and one is still missing.
The trigger for this accident was hydrogen peroxide, which is commonly used in medicine, sterilization, oxygen preparation, oxidants, bleaching agents, and dechlorinators. As a strong oxidiser, it is unstable and prone to decomposition. During decomposition, a large amount of heat is released. If metals, salts, and impurities are mixed in, the decomposition process may be intensified, leading to an explosion.
The HPPO process, which uses hydrogen peroxide as a raw material to directly oxidize propylene into propylene oxide (PO), is a new green technology, and the process patents are mainly held by companies such as Degussa, Uhde, Dow Chemical, and BASF. In China, Sinopec, Dalian Institute of Chemical Physics of the Chinese Academy of Sciences, and East China University of Science and Technology also have independent technologies. The process is relatively simple and does not produce too many byproducts, nor does it cause pollution to the surrounding environment. The produced propylene oxide is the only product allowed for export in China at present.
In the HPPO process, it’s key to ensure the quality of hydrogen peroxide. The most direct impact of the explosion at the hydrogen peroxide production area of Luxi Chemical is twofold:
First, the shutdown and transformation, which means that all devices that do not meet safety and environmental standards are immediately shut down, rectified, and closed within a certain time limit. The company’s current shutdown and associated devices involve hydrogen peroxide, caprolactam/nylon 6, and polyol units, and the resumption time is not decided yet.
Second, the safety production supervision has been strengthened, and the entry threshold for HPPO process to produce propylene oxide has been raised. In China, the currently operating HPPO facilities include those at Jilin Shenhua and Sinopec Changling, which were put into operation in 2014, Taixing Yida Chemical and Qixiang Tengda, which were put into operation in 2022, and Jincheng Petrochemical and Jiahong New Materials, which were put into operation in 2023. China’s total annual capacity of propylene oxide is presently1.55 million tonnes, and the future new and planned projects will add an annual capacity of 4.2 million tonnes, according to PUdaily.
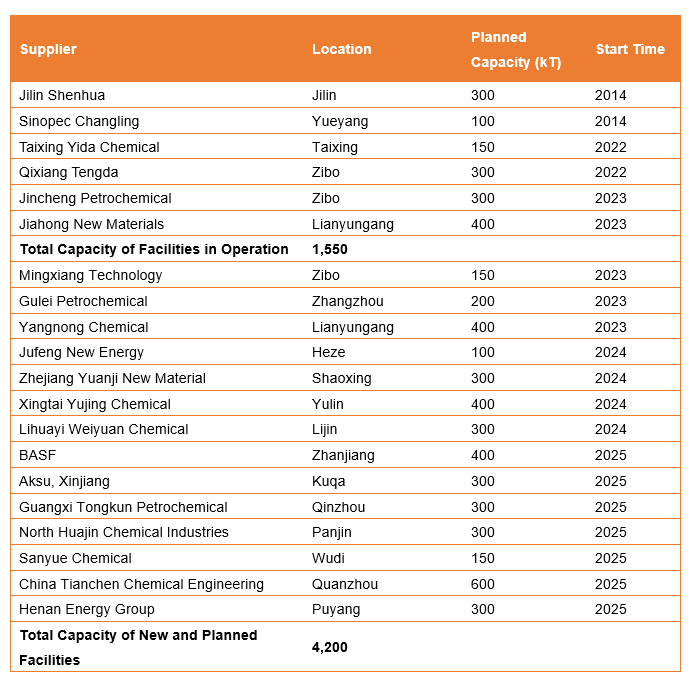
Moreover, the hydrogen peroxide explosion incident has to some extent delayed the restart of some HPPO process facilities, and the reduction in supply of propylene oxide is one of the reasons for the recent price increase. On May 5, the prevailing offers of propylene oxide in China have risen to CNY 10,000-10,100/tonne from CNY 9,600-9,700/tonne before the May Day holiday, and the uptrend will continue in the short term.
Future impacts include accelerating the relocation and transformation of hazardous chemical production companies in urban areas, increasing efforts to rectify, reduce, shift, and transform chemical companies outside of industrial parks.
 Everchem Updates Archive
 Sign Up for Email Updates