
Asian Markets
March 3, 2023
Accident Impacts Chinese MDI Production
MDI Upstream Raw Material Supplier Exploded, the Impact to China MDI Market
PUdaily | Updated: February 28, 2023
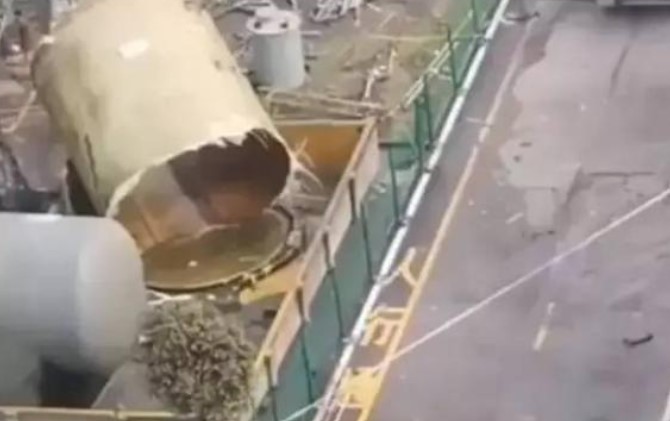
On February 24, during the maintenance period of Chongqing Yingtianhui Chlor-alkali Chemicals Co., Ltd, the storage tanks exploded, causing 1 death and 3 injuries, According to Emergency Management Agency of Chongqing Changshou Economic and Technological Development Area report on February 25, the investigation has been launched to determine the reason for the accident.
Yingtianhui is one of the upstream suppliers for BASF Chongqing’s MDI plant, supplying liquid chlorine and caustic soda.
What is the impact of explosion on China’s MDI market?
Due to the unexpected explosion, BASF Chongqing’s MDI facility, which was originally scheduled to restart this week, cannot redetermine the restart schedule. BASF has stopped trading MDI products since February 24. Subsequently, traders turned more reluctant to sell low and hold a wait-and-see stance. Some of them raised their offers slightly over the weekend.
Actually China’s MDI market had shown strong trend signals before the explosion.
February Market Review: In February, China’s MDI market showed a trend of “strong uptrend-pullbacks-rebound”. In early February, the major suppliers raised their list prices, and Covestro’s weekly guide prices were higher than market expectations. The MDI market showed a strong uptrend due to short supply after Spring Festival holiday, and some downstream manufacturers actively stocked up. But the market turned weak since the second week, and demand in industries such as pipe insulation and panels recovered slowly. Meanwhile, more speculative traders lowered offers to sell low-cost sources obtained before holidays, and low-priced Middle Eastern imports flooded into the market, driving market prices to stop hikes and experience slight pullbacks. In late February, prices of aniline, the main feedstock of MDI, kept rising. On February 24, mainstream reference offers of aniline in China had risen to CNY 12,350/tonne, lending a firm support to the MDI market. Most traders speculated that suppliers were willing to boost the MDI market in March, so the market stopped rising and moved sideways. Negotiation prices rebounded slightly.
March Market Forecast: The major MDI suppliers in China will unveil their March list prices and February settlement prices today and tomorrow. Traders have held a strong wait-and-see mood, expecting that suppliers guide prices would be high. Besides, due to ongoing maintenance of MDI facilities in Ningbo and Chongqing, the current operating rate of MDI remains low around 70%. If the Chongqing facility fails to restart as scheduled, the supplier may continue to control its supply in the near future. With probably high list prices in March and controlled supply, traders may raise their offers. And after consumption of low-cost sources, there will also be a support for the uptrend in March MDI market.
March 1, 2023
Chinese Spandex Overview
Spandex market not worry-free in March
Text size
| Spandex price strongly increased after the Spring Festival holiday driven by bullish policies, low operating rate of the whole industrial chain and active downstream procurement. Price of spandex increased the most among major raw materials of textile and apparels. However, the later market is also worrying with inadequate new export orders and surging spandex capacity. Spandex market will encounter bigger pressure. Domestic orders for fabrics better than exports Domestic orders for fabrics were good in Feb, mainly orders for light fabrics for spring and summer. Some fabric mills are hoarding up conventional varieties. The production is anticipated to sustain in the traditional peak season during Mar and Apr. Some companies went abroad to snatch orders in end-2022 and early-2023, while export orders remain insufficient. Overseas consumption is obviously depressed by high inflation and apparently soaring mortgage rate, which ends up with falling orders from Europe and US. Export orders may recover in Mar-Jun, which may be low at first but increase later within 2023. Operating rate of fabric mills apparently rose in Feb, with that of warp knitting plants at 60-70%, that of circular knitting plants and covered yarn plants in Zhejiang and Jiangsu at 50-70% and that of lace knitting plants in Changle, Fujian and circular knitting plants in Foshan at around 40% now. Many downstream plants replenished with optimized pandemic prevention and control policies. Some fabric mills focused on digesting spandex prepared before. Stocks of spandex started rising from late-Feb, which were above 27 days now. Spandex capacity soars By the end of February 2023, the capacity of spandex is revised up by 55kt to 1151.5kt/year in Chinese mainland, up by 5% on the month and 18.5% on the year. Huafon Chongqing, Hyosung Ningxia and Tayho Yantai’s spandex capacity increases by 25kt/year, 20kt/year and 10kt/year respectively. Current operating rate of spandex plants is near 85%. Above 970kt/year of capacity is running now, slanting high in recent two years, up by 7% on the year and 22.6% over the corresponding period of 2021. The run rate of plants with capacity at 30-50kt/year or above was at 72% and that of companies with capacity below 20kt/year approached 61%. BDO price turns to consolidate and PTMEG price may rise slightly Many BDO plants are scheduled to have turnaround in Mar. That means supply of BDO will reduce in short run. The supply from units with expanding capacity does not increase in short run. Therefore, the actual supply of BDO is anticipated to be flat with Feb in Mar. Stocks of BDO are low. Demand for BDO fails to improve much. Price of BDO is estimated to be in range bound in short run. Demand for PTMEG is strong when new spandex units start operation. Price of PTMEG is expected to slightly rise in Mar. In addition, Wanhua Chemical updated MMDI Mar nominations at 24,500yuan/mt, up by 2000yuan/mt on the month, and Feb settlement was at 20,600yuan/mt, up by 2,100yuan/mt on the month. With advancing feedstock prices, the feedstock cost of spandex is anticipated to climb up in Mar. In summary, the support from the feedstock cost remains strong on spandex market but the follow-up of new orders for fabrics and the recovery of consumption is crucial. Players were optimistic toward the domestic and export orders for fabrics earlier, but current export orders are scarce, which will weigh on the increase of run rate in fabric mills to a certain degree. New spandex units gradually commission operation and more products will be put into the market. The operating rate of existing spandex plants is medium-to-high. Supply of spandex rises but downstream buyers focus on digesting spandex prepared before. Price of spandex is likely to be firm in the first half of Mar under cost pressure and may move down in end-Mar or early-Apr with the release of products from new units and mounting inventory among suppliers. |
https://www.ccfgroup.com/newscenter/newsview.php?Class_ID=D00000&Info_ID=2023022830071
February 28, 2023
Lithium and China
Lithium Industry Reeling After China Shutters 10% Of Global Supply
by Tyler Durden
Monday, Feb 27, 2023 – 06:00 PM
That’s a nice little EV industry you got over there in the US, it’s be a shame if suddenly it found itself without the most important commodity.
That’s one way to interpret what just happened in China; another – a less cynical – is the way Bloomberg described it, namely that China’s lithium industry itself is reeling as its top production hub – responsible for around a 10th of the world’s supply – faces sweeping closures amid a government probe of environmental infringements.
The crackdown in Yichun, Jiangxi province, also known as the country’s “Lithium capital” follows a local lithium frenzy over the past year as miners raced to feed rampant demand for the battery material — and to benefit from record global prices. Now, they’re grappling with a close-up inspection by environment officials sent from Beijing.
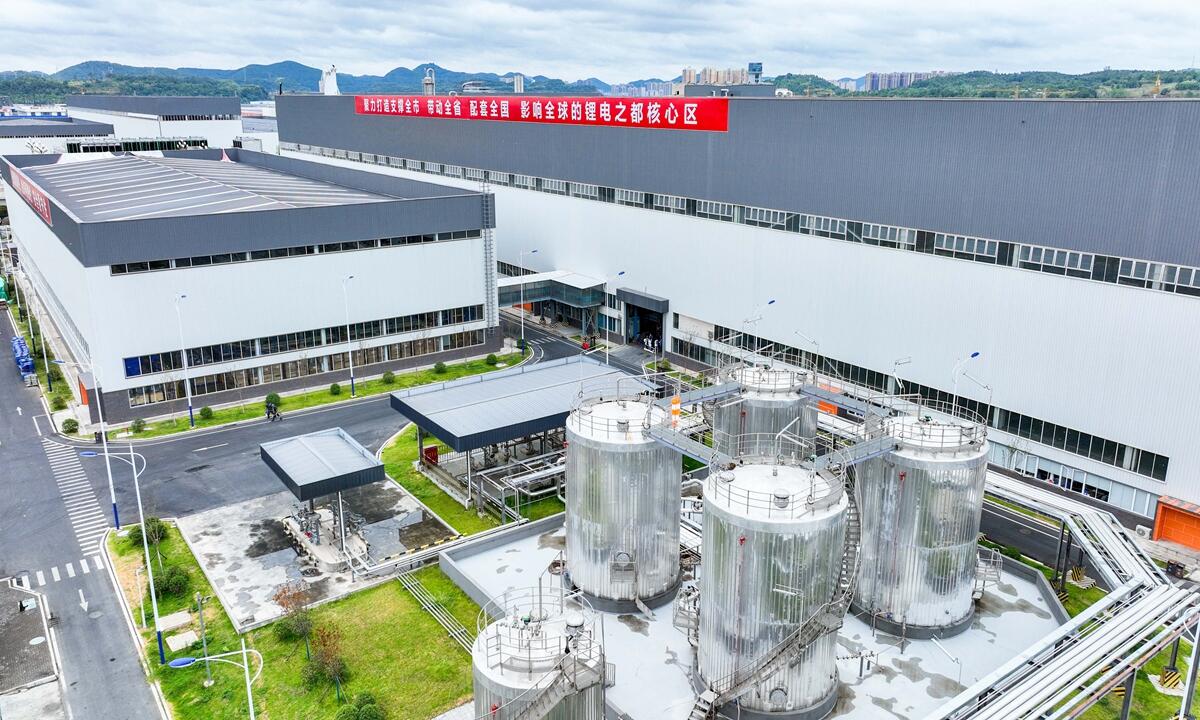
According to Yicai newspaper, ore-processing operations in Yichun have been ordered to stop as investigators probe alleged violations at lithium mines. That, Bloomberg notes, threatens somewhere between 8% and 13% of global supply, according to various analyst estimates, although it’s unclear for how long the immediate shutdowns will last.
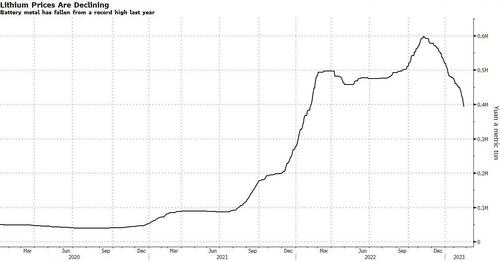
The sudden probe injects a big dose of uncertainty into a lithium market that has seen prices drop, bringing some relief to EV manufacturers, as more global output emerges. Jiangxi province was expected to be a big source of extra supply, from a lithium-bearing mineral known as lepidolite.
“This supervision may mean that the inspection and control over lepidolite mining in China will be more stringent in the future,” said Susan Zou, analyst at Rystad Energy. Companies with operations in Yichun include major battery manufacturers Contemporary Amperex Technology Co. and Gotion High-Tech Co., whose shares both fell more than 1% on Monday.
Due to the ongoing probe, all lepidolite mining in Yichun aside from those by a state-owned company have been suspended, but refineries are still operational, Daiwa analysts Dennis Ip and Leo Ho said.
Global lithium prices soared to a record high last year as demand from China’s booming electric-vehicle industry outstripped production. And, as so often happens in commodities, where the cure to high prices is more supply, leading to lower prices, this high-profit, high-demand environment has encouraged miners to skirt regulations.
Some companies had already been targeted for infringements, including incidents of pollution, over the past year. This is a much wider crackdown, and involves officials from central government departments including the Ministry of Natural Resources.
Yucai added that Beijing will mainly look at violations at lithium mines and seek to guide the “healthy development” of the industry; they will largely target those mining without permits or with expired licenses.
Curiously, a recent Goldman report found that the Chinese car industry’s demand for lithium has fallen by more than half in recent months, a dramatic reversal that will drive a further slump in the market. Meanwhile, Chinese prices have dropped more than 30% from last year’s peak.
According to calculations form Citic Securities analyst Bai Junfei, a month-long mining halt in Yichun would reduce lithium output by an amount equivalent to around 13% of the world’s total. Rystad Energy, a consultancy, estimated the amount at 8%.
“At present, the market speculation is that the probe may stop after the two sessions in China next month,” Rystad’s Zou said, referring to the annual parliamentary meetings due early March.
https://www.zerohedge.com/markets/lithium-industry-reeling-after-china-shutters-10-global-supply
February 14, 2023
China TDI Price Forecast for 2023
China TDI Price Forecast for 2023
PUdaily | Updated: February 14, 2023
After returning from the Spring Festival holiday in 2023, the already high TDI price not only did not fall, but began another round of rapid rise: Covestro and BASF guidance prices increased sharply, and the market rumored that Wanhua Chemical will permanently close the old TDI production plant in Fujian on February 1. At the end of January, the market price rose rapidly to 20500~21000 CNY/tonne. However, after the Lantern Festival, the downstream industry basically resumed work, and was cautious in the face of high prices, and just needed procurement. Subsequently, as the trading continued to be light, some traders began to waver, driven by the low-price shipment of the profit order, some chose to let the profit shipment, the market price loosened slightly, the quotation range converged significantly, and the market price returned to around 20200~20600 CNY/tonne.
Table 1 Price influencing factors and forecast of China TDI market in2023
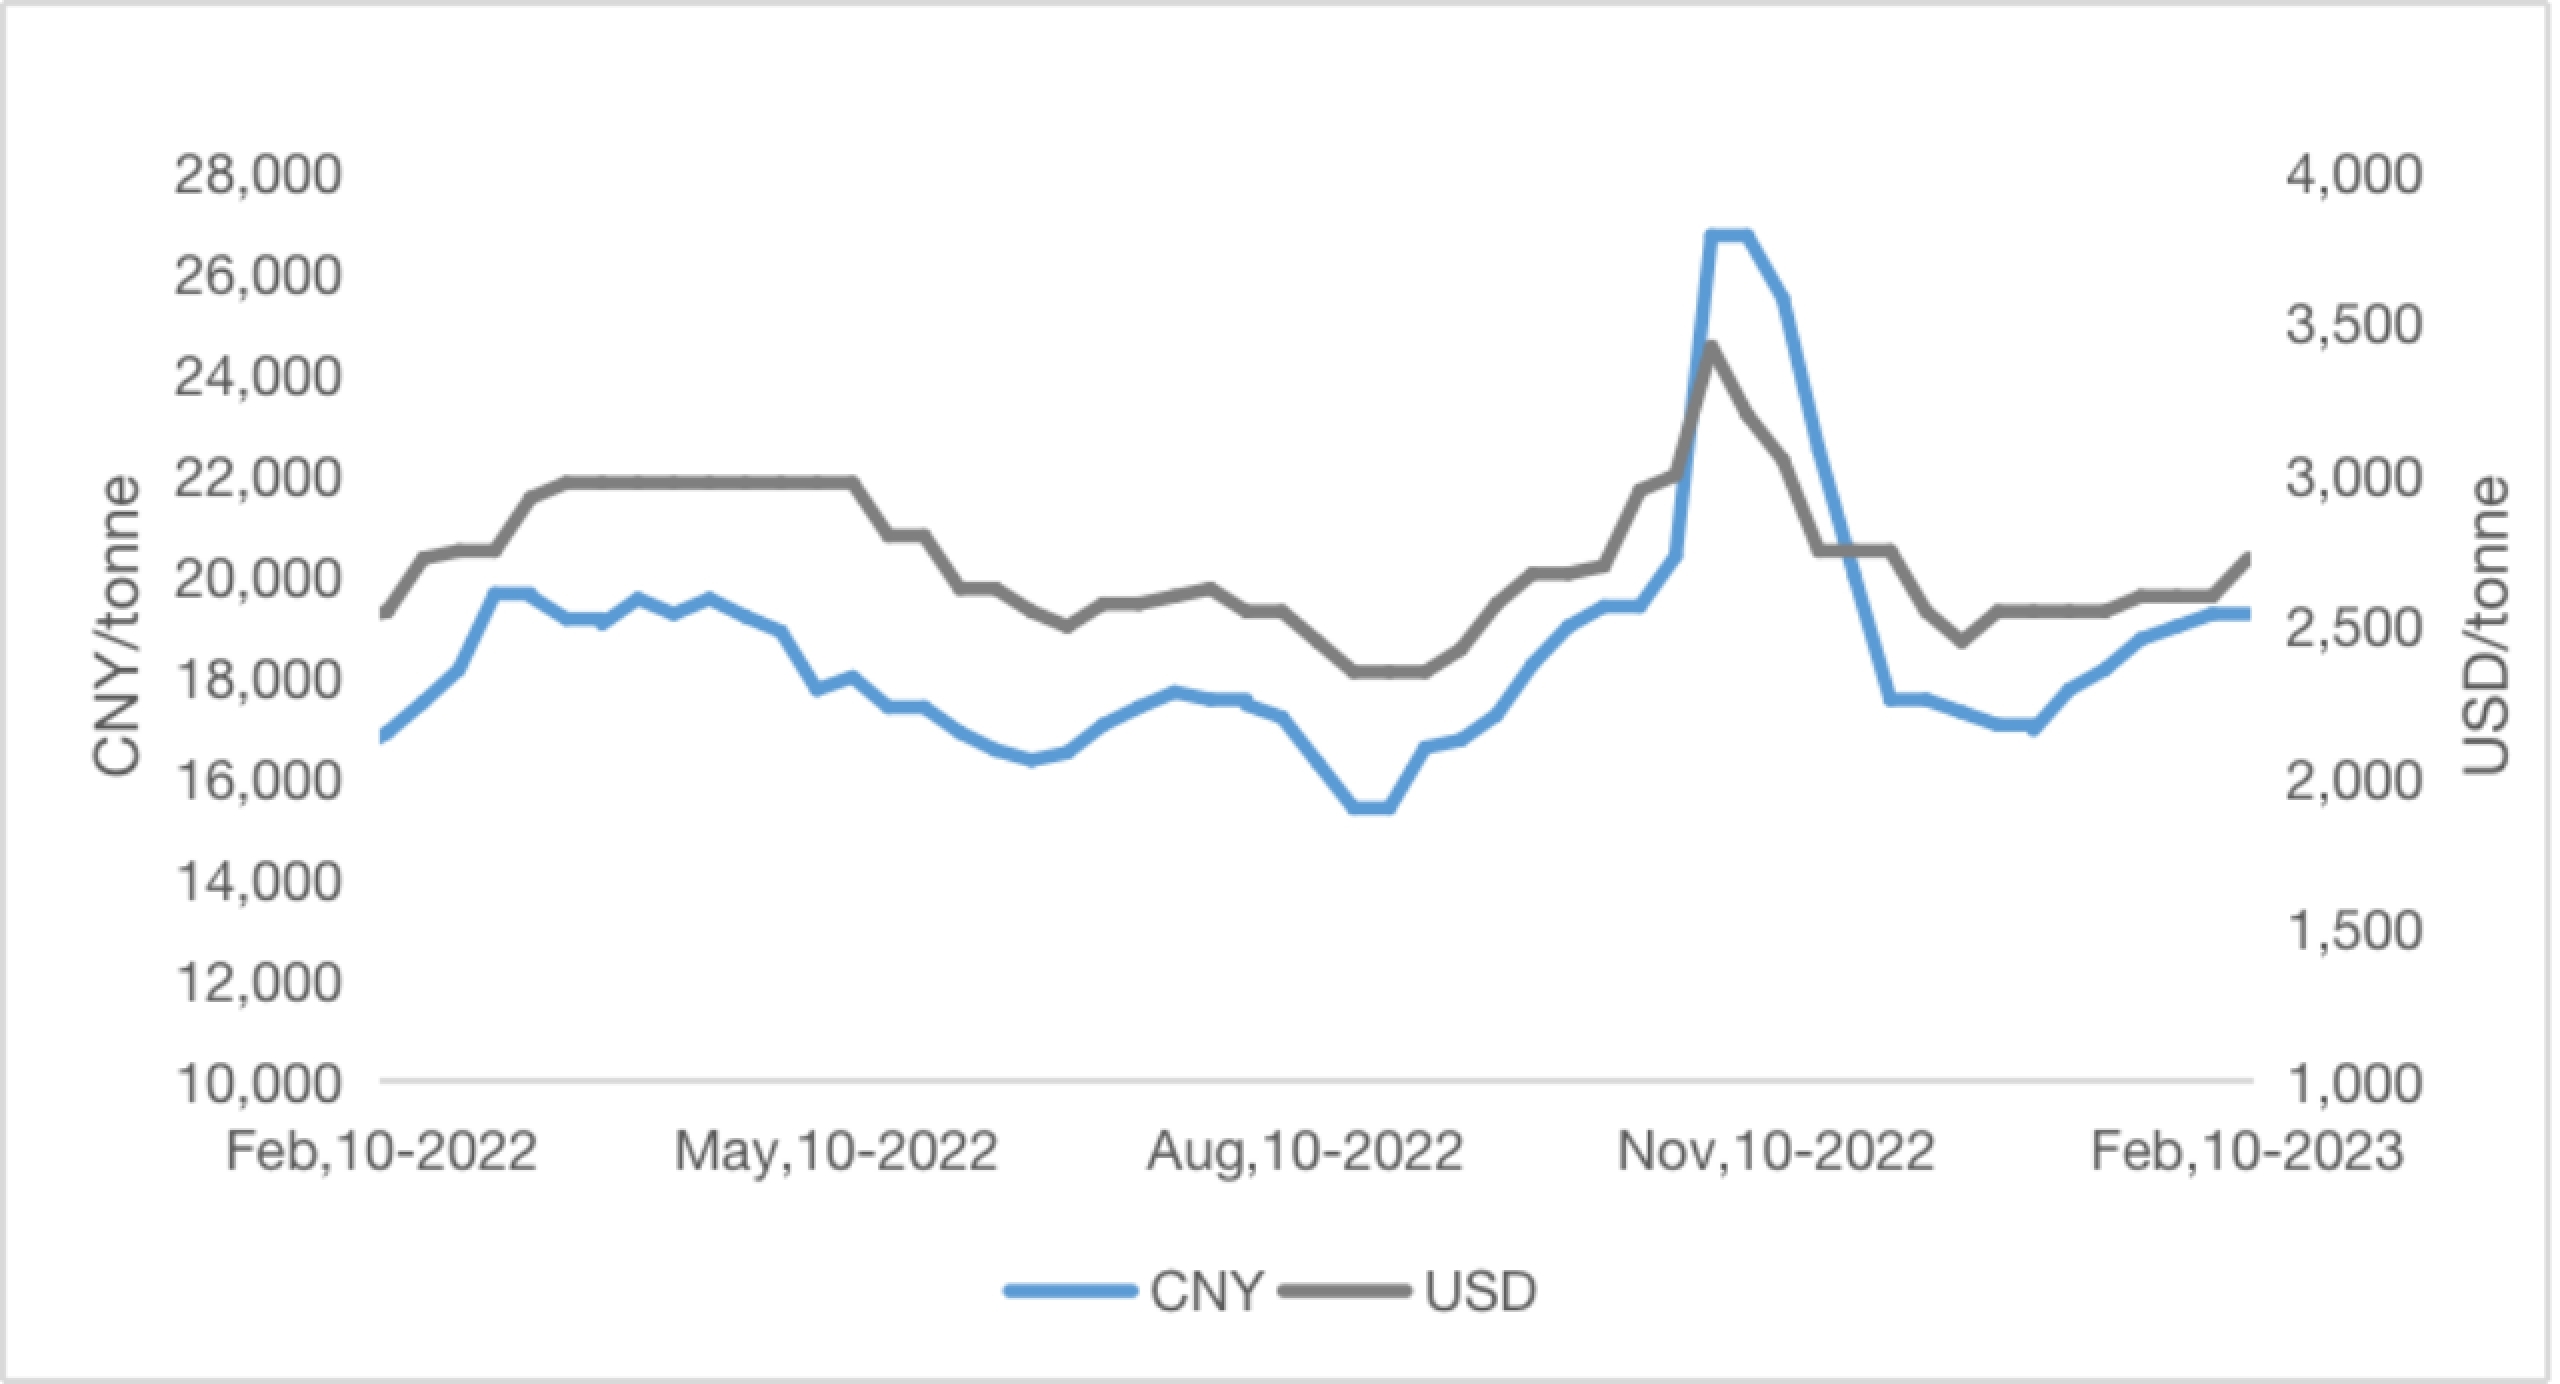
For the subsequent price trend, Pudaily combined the raw material side, supply side and demand side information to predict the TDI market price for the whole year of 2023:
Table 1 :Influencing Factors & Forecast for China TDI Market Price in 2023
| Influencing Factor | Impact on TDI Price | |
| Feedstock | It is projected that the impact of Russia-Ukraine conflict and OPEC’s oil output cuts would continue, and global crude oil prices would fluctuate at high levels in 2023. | – |
| Supply | It’s expected that Gansu Yinguang’s new 150kT facility would resume production in February 2023, and Wanhua Chemical’s new 250kT facility in Fujian would be put into production in June 2023. | ↓↓↓ |
| Demand | Domestic demand: Under China’s principle of “houses for living in, not speculation”, the demand in the main downstream industry of TDI – upholstered furniture- is unlikely to increase significantly. However, in view of the liberalization of anti-epidemic measures, demand may recover somewhat under the government’s initiatives to stimulate consumption. | ↑ |
| External demand: As many foreign TDI facilities are outmoded, their overall supply capacity is declining, thereby widening the gap between supply and demand. Meanwhile, Chinese TDI suppliers and traders have paid more attention to exports in recent years, especially after China has lifted registration system for foreign trade authorization. China’s TDI exports are expected to maintain year-on-year growth in 2023. | ↑ | |
| Comprehensive Prediction | In 2023, China’s TDI market is expected to open high and move downward, with weak fluctuations. The demand in China is projected to revive in 2023, with a slight year-on-year increase. However, owing to the increase of 300kT TDI supply capacity, and the low possibility of substantial growth of Chinese and global economy, especially the demand in the upholstered furniture industry, Chinese TDI market is forecasted to be oversupplied, and prices may open high and decline weakly in 2023. TDI prices in China would move between CNY 14,000/tonne and CNY 20,000/tonne. |
NOTE: “↑” represents positive, “↓” represents negative, and “-” represents neutral. The more the number of arrows, the greater impact the influencing factor is likely to have.
On the whole, it is expected that China’s TDI price will open high and low in 2023, which will be weak and volatile. In summary, demand is expected to recover in 2023, with a slight year-on-year increase. However, due to the supply-side production capacity will increase by 300,000 tons, and the substantial growth of China and the global economy in 2023, especially the possibility of a substantial increase in demand in the upholstered furniture industry, the overall TDI market in 2023 has a high probability of supply exceeding demand, and the price may open high and go low, weak and volatile, and the expected operating range: 14,000 yuan / ton ~ 22,000 yuan / ton.
February 13, 2023
Wanhua Chemical 2022 Results
Wanhua Chemical Group: Net profit for 2022 about 16.239 billion yuan, down 34.12% YoY
NBD
13, February, 2023,16:20 GMT+8
NBD AI Bulletin – Wanhua Chemical Group Co Ltd (SH 600309, close price: 97.97 yuan) on February 13 briefed its annual results for 2022. Operating income for the year was about 165.565 billion yuan, showing an increase of 13.76% from a year ago. Net profit attributable to the shareholders of the listed company was about 16.239 billion yuan, down 34.12% year on year. Basic earnings per share was 5.17 yuan, showing a 34.14% reduction.
Wanhua Chemical Group Co Ltd’s chairman is Liao Zengtai, male, 60 years old, with a master’s degree; The general manager is Kou Guangwu, male, 57 years old, with a master’s degree.
As at the press time, the market value of Wanhua Chemical Group Co Ltd was 307.6 billion yuan.
(By Lan Suying)
http://www.nbdpress.com/articles/2023-02-13/44873.html
 Everchem Updates Archive
 Sign Up for Email Updates
