
Asian Markets
January 25, 2023
Chinese Propylene Oxide Review
2022 Year End Summary: China’s PO Market Review
PUdaily | Updated: January 17, 2023
The pandemic, coupled with tight global supplies of energy and food, impacted consumption and manufacturing activities in China in 2022. But China’s economy is expected to pick up in 2023 as the government efforts to stimulate economy are producing effects, including the shift in pandemic prevention and control policy, which enables the economy to emerge from the negative effects of the COVID-19, the demand to recover and the manufacturing activities to return to normal levels, as well as the development of policies to increase domestic demand, which will help offset the impact of decreased exports. And the low base in 2022 also lays a foundation for the robust economic recovery in 2023. It is expected that China’s economy will grow by over 5% in 2023.
In terms of the PU raw materials market, against the backdrop of global inflation, repeated COVID-19 outbreaks and start-up of new production capacities, in 2022 buyers gained more bargaining power the market supply and demand pattern has turned from up to down, and the PO market shows a trend of falling within a range and fluctuating in a narrow range.
China PO Prices
In 2022, manufacturers in Shandong continued to have the greatest impact on the changes in domestic PO prices. Offers in Shandong and North China averaged about CNY 10,163/tonne EXW in bulk in cash, down 38.3%. And those in East China averaged CNY 10,309/tonne DEL in bulk in cash, down 38.2%.
China PO Capacity & Output
In 2022, Taixing Yida Chemical saw successful trial run of its 150kt/a PO project, and Tianjin Bohai Chemical’s PO/SM plant, with an annual capacity of 200,000 tonnes for PO and 450,000 tons for SM, was also successfully commissioned, thus bringing the national PO capacity to 4.897 million tons per year, up 14% from prior year. Further capacity expansion can be expected as Zhejiang Petroleum and Chemical’s Phase II PO/SM project is under construction and Jiangsu Eastern Shenghong is planning its PO/SM facility project, with an annual capacity of 200,000 tonnes for PO and 450,000 tons for SM. China’s total PO output in 2022 hit a record high of 3.76 million tonnes, up 8.7 percent.
China PO Import & Export
According to the General Administration of Customs of China, China imported 290,000 tonnes of PO for the January-November period, down 26.3% year-on-year and mainly from Thailand and Japan. It exported 9,000 tonnes of PO for the same period, up 268.3% year-over-year and mainly to India and the United States.
In the year, some PO units in Saudi Arabia, Japan and South Korea, Thailand and European countries were shut for routine maintenance or forced to lower their production loads due to energy crisis and cost pressure. On the other hand, as domestic production capacity continued to expand, China’s dependence on imports had been significantly reduced. All this led to shrunk PO imports…
China PO Consumption
In 2022, China’s PO consumption rose by 4.2%. Although PO production increased significantly as new capacities came online, the demand failed to expand as rapidly. The lockdown in East China was lifted in the second quarter, but no significant recovery in demand followed in July. The supply remained ample, though individual manufacturers experienced fluctuations in their production. In 2022, PPG remained the largest consumer of PO, although PPG consumption decreased by 8.3%. It is followed by PG/DMC, propylene glycol ethers, flame retardant TCPP and isopropanolamine…
In 2023, Tianjin No. 3 Petrochemical Plant, Zhejiang Petrochemical &Chemical, Shandong Minxiang Chemical Technology and Shandong Jufeng New Energy Technology are likely to put into operation their new plants. In 2022, PO manufacturers again lowered their production loads in an attempt to boost the market, resulting in an industry operating rate of 55% to 68% excluding plants shut for maintenance. But the effectiveness was quite different than in 2021. The main reason is the fierce competition resulting from more new players entering the market in addition to the sluggish demand. As supply became increasingly ample, buyers gained more bargaining power and the profit margin was squeezed.
January 25, 2023
Southeast Asia MDI Report
Southeast Asia MDI Market and Dowmstream Sectors Review 2022
PUdaily | Updated: January 19, 2023
With higher vaccination coverage and loosening pandemic restrictions, most economies in Southeast Asia showed strong recovery momentum in the past year. In December 2022, the Asian Development Bank (ADB) gave out a supplement to its flagship Asian Development Outlook(ADO) 2022, which upgraded growth outlook for 2022 to 5.5% from 5.1% on robust economic performance in Malaysia, the Philippines, Thailand, and Vietnam in the third quarter. The report noted that the strong performance on consumption, exports and tourism in these economies boosted economic growth expectations for 2022.
Southeast Asia MDI Demand 2022
Without any MDI synthesizing facilities, Southeast Asia region mainly imports MDI products from China, Japan, South Korea and even from the Middle East and Europe. The major MDI suppliers include Chinese Wanhua Chemical, Japanese Tosoh, South Korean KMCI and BASF. Moreover, Middle Eastern firm Sadara’s PMDI is sold by Dow and SABIC. The supply of MDI exported from China, Japan and South Korea to Southeast Asia kept stable from 2018 to 2022. It is estimated that the total demand for MDI in Southeast Asia will be about 300kT in 2022, of which the demand for imported goods from China, Japan and South Korea will be around 260kT, basically the same as the previous year. Vietnam, Thailand and Malaysia are the top MDI consumers in Southeast Asia. In 2022, the year-on-year growth rates of MDI consumption in Vietnam and Malaysia were higher than the overall growth level of consumption in Southeast Asia.
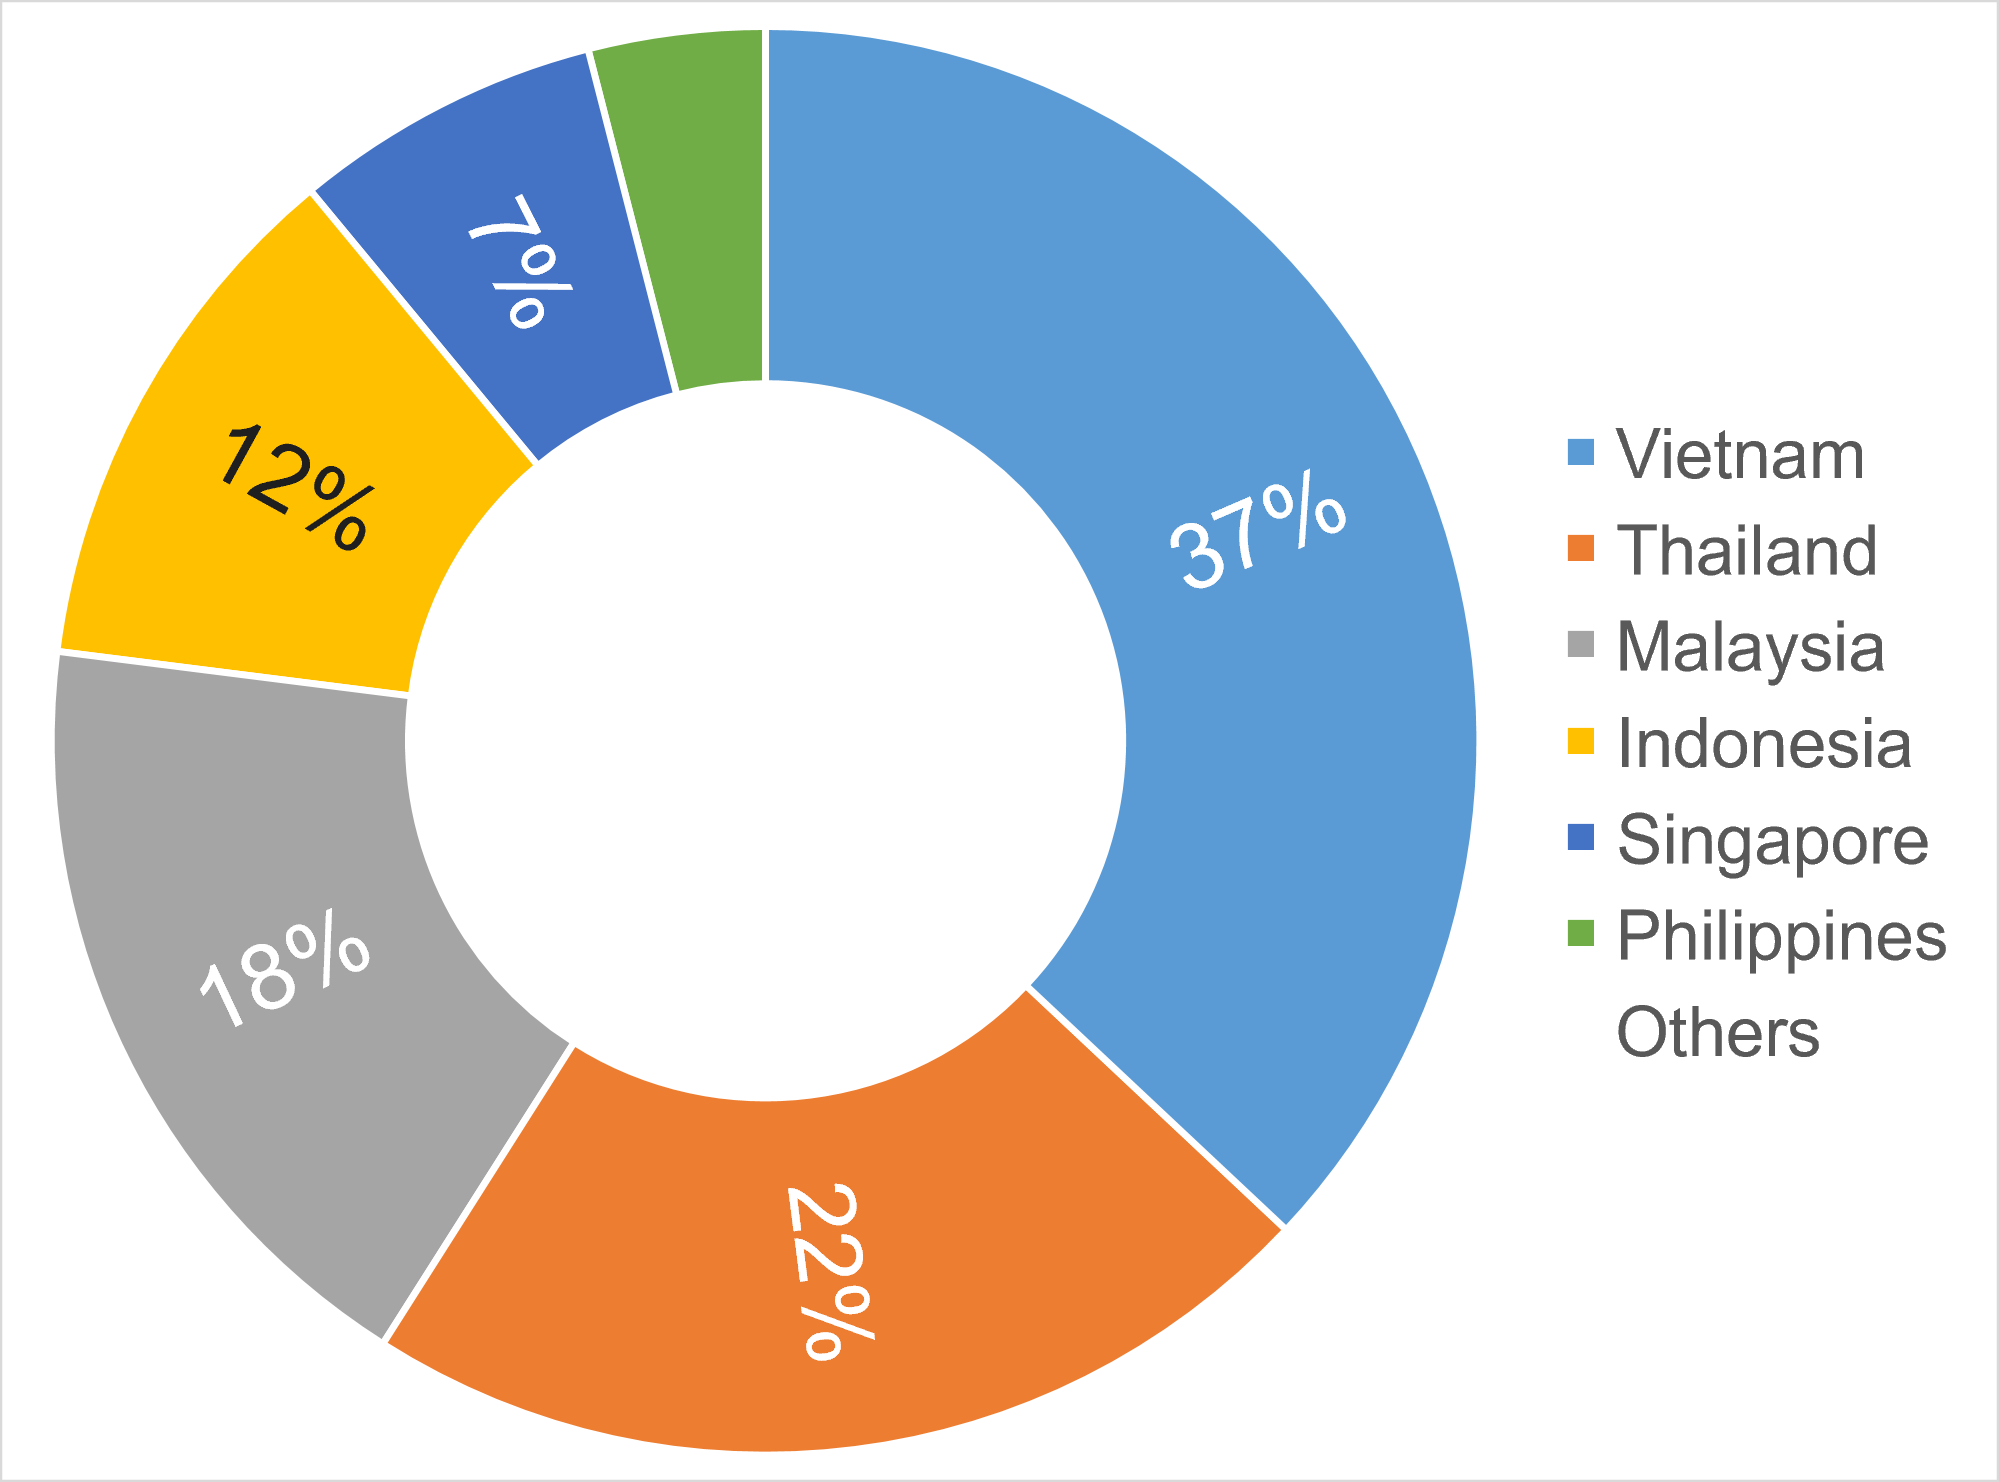
Southeast Asian (Estimated) MDI Consumption by Country, 2022 (%)
Southeast Asian Major MDI Downstream Sectors
The main downstream sectors of PMDI in Southeast Asia are insulation panels, refrigerators & freezers, automobiles, etc. And the main downstream sectors of MMDI are PU resin for shoe sole and spandex. Vietnam, Thailand, Indonesia, Malaysia and Singapore are the top MDI consumers and also the major economies in the region. Southeast Asia countries have attracted significant foreign investment in recent years, owing to low costs on land and labor, stable political environment, robust economic development and preferential tariff rates.
Cold Chain Logistics (Insulation Panel): As one of the key strategic regions for global industrial transfer, the development of Southeast Asian countries is attracting much attention, and its cold chain logistics market is expected to grow by more than 12% in 2022-2027. Thailand’s refrigeration capacity totaled 940kT, and the refrigeration capacity of Indonesia and Myanmar was 370kT and 88kT respectively, according to a report of the Economic Research Institute for ASEAN and East Asia (ERIA). Increasing meat consumption is one of the main driving factor for the development of the cold chain industry in Southeast Asian countries. Malaysia’s poultry meat industry is largely self-sufficient, with an annual per capita consumption of nearly 50 kilograms.
Automobile: With a huge population and abundant natural resources, ASEAN is one of the fastest-growing consumer market, which, in turn, will drive the automobile market. From January to November 2022, auto outputs in ASEAN amounted to 4.06 million units, up 27.4% y/y. The top three auto producers are Indonesia, Thailand and Malaysia, contributing about 92.5% of total regional outputs. Thailand, the largest auto production base in Southeast Asia, produced 1.79 million vehicles from January to November 2022, up 16.9% y/y.
Summary:
The overall MDI consumption in Southeast Asia in 2022 kept unchanged compared with the previous year. It’s mainly because Southeast Asian manufacturing PMI is above 50% throughout the year and the demand in MDI downstream sectors didn’t weaken significantly. In addition, thanks to lower labor costs, more foreign-funded enterprises chose to enter the Southeast Asian market. In 2023, MDI consumption and its downstream sectors are projected to see a rise in Southeast Asia.
January 13, 2023
Chinese Spandex Review of 2022
2022 big events of spandex industry 
Text size
| Macro environment was complex and changeable in 2022. Global economy decreased due to the raise of interest rate in US, energy price soared amid the Russia-Ukraine conflict and market liquidity weakened because of the repeat spread of COVID-19 pandemic in local China. Global economy faced high inflation and low growth rate, in stagnation stage. Spandex market was greatly affected by the macro environment in 2022. Demand for spandex was apparently insufficient. The weakness was transferred to upstream market from the downstream sector. Spandex market saw obviously worse price, operating rate, inventory and profit in 2022.Macro policies 1. Implementation of tax rate on spandex value chain in RCEP AgreementThe Regional Comprehensive Economic Partnership Agreement (RCEP) entered into force on January 1, 2022, mainly involving six ASEAN members, including Brunei, Cambodia, Laos, Singapore, Thailand and Vietnam, and four non-ASEAN members, including China, Japan, New Zealand and Australia.With the help of RCEP reciprocal tariffs, the growth rate of textile exports to Europe and the United States was greater than that to Europe and the United States. From January to October 2022, ASEAN accounted for 16.97% of China’s textile and apparel exports, surpassing the United States to become China’s largest export market, with an increase of 20.9 percent over the same period of last year; the United States took up 16.85%, with a decrease of 1.58 percent on annual basis; and the European Union accounted for 14.7%, with an increase of 4.73 percent year on year. 2023 is the second year of the entry into force of the RCEP, and trade terms and tariff dividends on exports to ASEAN will be further released. 2. Ministry of Industry and Information Technology and National Development and Reform Commission issued relevant guidance on chemical fiber and textileThe Ministry of Industry and Information Technology and the National Development and Reform Commission issued the guidance on the High-quality Development of the Chemical Fiber Industry on April 21, 2022 proposing that by 2025, the industrial added value of chemical fiber enterprises above scale will grow at an average annual rate of 5%. The proportion of chemical fiber output in the world will be basically stable. Upstream feedstock market 1. Capacity expansion 1) Shaanxi Shanhua’s BDO second phase alkynation efficiency improvement project starts operation successfully The second phase of the alkynation efficiency improvement project from Shaanxi Shanhua was successfully started up at one time in November, 2022, completed the activation of the catalyst, and produced qualified 1,4 butynediol. The second phase of BDO alkynation efficiency improvement project is a key project for Shaanxi Shanhua to improve both BDO production capacity and efficiency. 2)Inner Mongolia Dongjing commenced 280KTA BDO plant On November 24, 2022, after more than a year of intensive construction, Inner Mongolia Dongjing Biological Environmental Protection Technology Co., Ltd., located in Wuda Industrial Park of Wuhai, has successfully started up its 1,4-butanediol (BDO) plant with an annual output of 280000 ton. After a day of debugging, the purity has reached 99.91%, which indicated that Dongyuan Technology has become the world’s largest integrated production base of BDO with an annual BDO capacity at 380kt. 3) Wanhua Chemical’s MDI unit started production successfully in Fujian Wanhua Chemical Group Holding Company Wanhua Chemical (Fujian) Isocyanate Co., Ltd.’s 400kt/year MDI unit has successfully started operation on Dec 22, 2022, with qualified products available. This project will further optimize company’s MDI industrial layout and improve global industrial competitiveness. 2. New National Standard (2022 Version) for the PTMEG implemented The 2022 version of PTMEG new national standard, led by Sichuan Tianhua Fubon Chemical Co., Ltd., and jointly drafted by Chongqing Jianfeng New Materials Co., Ltd. Chiyuan Chemical Branch, Shaanxi Shanhua Coal Chemical Group Co., Ltd., CPP (Panjin) Co., Ltd., Dairen Chemical (Jiangsu) Co., Ltd., Xinjiang Blue Ridge Tunhe Energy Co., Ltd., Zhonglan Chengguang Chengdu testing Technology Co., Ltd. and CGN Juner (Zhejiang) New Materials Co., Ltd. has been issued and implemented from November, 2022.Spandex sector 1. Spandex capacity exceeded 1 million tons for the first time By the end of 2022, the capacity of spandex exceeded 1 million tons to be 1.0965 million tons/year in Chinese mainland, up by 12.9% or 125kt/year on the year. Three companies had new capacity in the first half of 2022, namely Hyosung Ningxia, Huafon Chongqing and Xinxiang Chemical Fiber, with total new capacity at 90kt/year. Four companies had new capacity in the second half of year, namely Tayho Ningxia, Zhuji Huahai, Xinxiang Chemical Fiber and Zhuji Qingrong, with total new capacity at 60kt/year. 25kt/year of capacity was eliminated at the end of 2022. The total increment of capacity was at 35kt/year combined with the new expansion and eliminated capacity in the second half of 2022.Spandex market saw extreme operation in 2022. New capacity expansion was big. However, some export orders flew to Southeast Asia and South Asia in the second and third quarter. Domestic and export demand was soft in the fourth quarter impacted by the spread of pandemic and the high inflation outside China. Demand for spandex saw a rare negative growth. The operating rate of spandex plants averaged at 76.4% in 2022, down by 18.2 percentage points on the year, with the highest and lowest level at 94% in mid-Mar and 55% in mid-Aug. 2. Huafon Group completed the M&A of bio-based business under DuPont On June 1, 2022, Beijing time, Huafon Group formally completed the delivery of the related business and technology of bio-based products spun off by DuPont of the United States. This is by far the largest overseas M&A transaction of Huafon Group. 3. Bangtai’s bio-based melt-spun spandex successfully passed the USDA Bio-based Product Certification On Jun 1, in order to realize the recycling of resources and build a sustainable future, Bangtai has a foothold in the field of new materials and plays a green role under the strategic goal of “Dual Carbon”. Bangtai’s technical team has successfully developed bio-based melt spinning spandex products and successfully passed the U.S. Department of Agriculture (USDA) Bio-based Product Certification! 4. Hyosung’s biological spandex certified by SGS On Jul 26, Hyosung is the world’s largest spandex manufacturer and the first global developer to commercialize biological spandex. Hyosung creora® bio-spandex has been certified by Standard Global Services (SGS) as an eco-product, ensuring that the product is made of plant materials and produced in a harmless and environmentally friendly environment. SGS is a leading inspection, accreditation, testing and certification organization and a globally recognized benchmark for quality and integrity. 5. The spread of pandemic affected the operation of some textile and apparel markets The COVID-19 pandemic had an obvious impact on the business of textiles and apparels in 2022. Some professional textile and apparel markets in Shanghai, Guangzhou, Hangzhou, Shenyang, Haicheng, Shaoxing, Xinjiang, Zhuzhou and Nantong were closed for a long time. 6. Textile companies went abroad to snatch orders At the end of the 2022, after China’s epidemic prevention and control measures were optimized, textile enterprises either set out on their own or joined the “order-grabbing regiment” organized by the government to get new orders and talk about new investment abroad so as to quickly expand market. |
http://www.ccfgroup.com/newscenter/newsview.php?Class_ID=D00000&Info_ID=2023011330026
January 12, 2023
Chinese Spandex Update
Spandex market may embrace a good start after LNY holiday
| The COVID-19 pandemic infection peak has been passed in fabric manufacturing bases in Zhejiang and Jiangsu. The worry of production resumption after the Lunar New Year’s (LNY) holiday has been mitigated. Buyers were active in purchasing spandex after the New Year’s Day. Price of PTMEG and MMDI stabilized and slightly rallied. Spandex market witnesses better supply, demand and cost. A good start after the Lunar New Year’s holiday may be deserved anticipation. In terms of price, the price of spandex 40D has been close to the historic bottom. Current price of spandex 40D has been higher than the low level in Sep 2,022. According to the data from CCFGroup, price of spandex 40D was at 32,000yuan/mt now, mainly discussed at 31,000-33,000yuan/mt. The discounts of some varieties have been canceled after inventory dropped substantially. Price of some medium-to-high end spandex 40D was at 33,000-36,000yuan/mt. 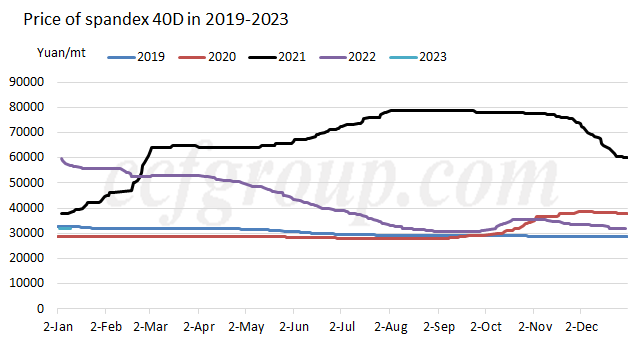 As for the feedstock cost, price of major feedstock PTMEG, BDO and MMDI all bottomed out. That meant the cost of spandex market climbed up. With rising price of BDO and in expectation of better demand, price of some PTMEG was required to rise by 2,000yuan/mt over Dec. Under the cost pressure, the discussion was in stagnation and the actual price increment was smaller at 500-1,000yuan/mt. Price of MMDI also rebounded. Wanhua Chemical updated liquid MMDI Jan nominations at 20,500yuan/mt, up by 500yuan/mt on the month. 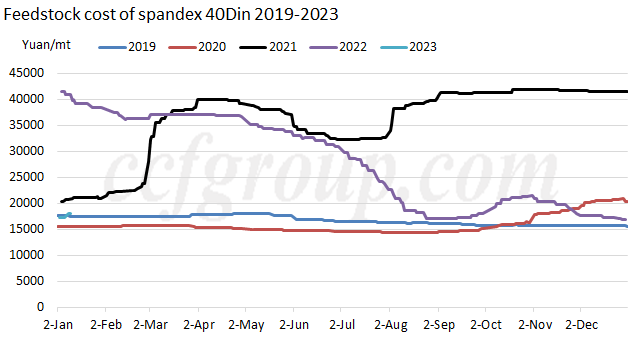 From the angle of supply, the operating rate of spandex plants rose by 15 percentage points to 72% now from 57% before the New Year’s Day holiday, which was mainly driven by better sales in Jan, but it was still low compared with the same period in recent five years. More leading companies resumed operation from earlier production curtailment or suspension. Some big spandex plants will further ramp Looking at the inventory, the inventory of spandex was rapidly transferred to medium-to-downstream market. The inventory of spandex suppliers has reduced to 27 days, the second lowest during the corresponding period in recent five years. Some buyers were active in restocking even before the Lunar New Year’s Day holiday. Stocks fell rapidly in plants who cut or suspended much production before. Sellers reduced discounts. Some suppliers even controlled the volume of orders, worrying price of major feedstock to increase in Feb. Some fabric mills may continue replenishing after recouping some capital. The spandex inventory can guarantee the production for 15 days in some downstream plants, longer for near one month. The logistics will gradually suspend from this weekend affected by Spring Festival holiday. Spandex market witnesses better supply and demand at the beginning of 2023. The operating rate of spandex plants increases but some plants still control the run rate. The price of MMDI and PTMEG bottoms out. Many market players are optimistic about the sales and price of spandex after the Lunar New Year’s holiday. Supported by the factors such as supply, cost and demand, price of spandex may be hard to reduce but easy to increase before and after the Lunar New Year’s holiday. However, cautious mindset is held toward the spandex market at the end of Q1 2023. After the capacity expansion peak in 2022-2023, spandex market will see apparent oversupply. The increase of demand may be hard to chase up that of supply, which will restrict the rebounding range of spandex price. |
http://www.ccfgroup.com/newscenter/newsview.php?Class_ID=D00000&Info_ID=2023011230066
December 12, 2022
An Entwined World
China shipyards feast on record LNG tanker orders as South Korea builders are full up
By Chen Aizhu
Summary
- Companies
- Chinese yards win nearly 30% of this year’s record orders
- Order books for Chinese yards triple as LNG freight soars
- Steep learning curves for shipbuilders new to LNG
- China needs vessels to ship U.S. LNG for energy security
SINGAPORE, Dec 12 (Reuters) – China is making fast inroads in the market for newbuild liquefied natural gas (LNG) tankers as local and foreign shipowners turn to its shipbuilders for the specialty vessels because long dominant yards in South Korea are fully booked.
Three Chinese shipyards – only one of them having experience building large LNG tankers – won nearly 30% of this year’s record orders for 163 new gas carriers, claiming ground in a sector where South Korea usually captures most of the business.
LNG tanker order books for Chinese yards tripled as China’s gas traders and fleet operators sought to secure shipping after freight rates soared to records following the upending of global energy supply flows by Russia’s invasion of Ukraine.
With South Korean shipbuilders swamped by orders to service Qatar’s massive North Field expansion, Chinese yards also attracted more foreign bookings, including first overseas orders for some ship makers only recently certified to build membrane-type LNG carriers.
“As more Chinese gas traders engage local shipyards, they will be forced to climb the learning curve and eventually grow the whole industry,” said Li Yao, founder of Beijing-based consultancy SIA Energy.
Chinese shipyards this year won 45 LNG tanker orders worth an estimated $9.8 billion, about five times their 2021 order values, according to shipping data provider Clarksons Research.
By late November, Chinese yards had grown their LNG order books to 66 from 21, giving them 21% of global orders worth around $60 billion.
Comparatively, Chinese shipyards built just 9% of the existing global LNG fleet, according to Clarksons.

STEEP CURVE
Shanghai-based Hudong-Zhonghua Shipbuilding is the only Chinese yard with experience building large LNG carriers, delivering dozens going back to 2008. This year, it took 75% of China’s new orders.
Hudong-Zhonghua shared 26 orders from local owners – versus nine the last two years – with fellow China State Shipbuilding Corporation units, Dalian Shipbuilding Industry and Jiangnan Shipyard (Group), according to Clarksons and industry officials.
Two other yards – China Merchants Heavy Industry (CMHI) and Yangzijiang Shipbuilding (YAZG.SI) – were certified to build large LNG carriers this year and have attracted interest from local and foreign shippers.
LNG tankers, like aircraft carriers, are among the most difficult vessels to build, taking up to 30 months. For membrane-type containment tanks alone, 200 workers spend two months welding barrier walls made of paper-thin steel and 130 km (81 miles) of connecting lines.
Workers on these systems for housing gas chilled to minus 160 Celsius (minus 260 Fahrenheit) for shipping also have to be certified by Gaztransport & Technigaz (GTT) (GTT.PA), a French engineering company that holds the patents and licences its designs to shipbuilders.
“The learning curve will be steeper for the newer builders … We’ll also face a shortage of skilled workers,” said Hu Keyi, corporate technology chief at Jiangnan Shipyard.
Jiangnan is building its first 80,000 cubic metre (cu m) tanker for Guangdong-based trader JOVO Energy (605090.SS) and won an order in March from Abu Dhabi National Oil Company (ADNOC) for two 175,000 cu m LNG carriers.
“Considering relatively low financing costs thanks to Chinese banks’ support … investing in a newbuild offers greater security versus term chartering,” said Jacky Cai, a director at JOVO Energy, which is considering ordering a larger tanker.
U.S. GAS
China’s demand for LNG tankers is propelled by a need to ship 20 million tonnes a year of gas from the United States, part of a boom set to swell the global LNG fleet by a third over the next five years, said Robert Songer, analyst at commodity consultancy ICIS.
China needs about 80 vessels to transport U.S. LNG, said SIA Energy’s Li.
“Apart from servicing Chinese demand … the vessels may also be used to trade cargoes on other routes,” said Stephen Gordon, managing director of Clarksons Research.
Strong local shipbuilding benefits state energy giants PetroChina , China National Offshore Oil Corporation (CNOOC) and Sinopec , and private firm ENN Natural Gas Co (600803.SS), helping to better secure a fuel key to meeting China’s 2060 carbon-neutral target.
PetroChina and CNOOC lined up orders at Hudong-Zhonghua earlier than their peers, mostly via joint ventures with state shippers COSCO Shipping Energy Transportation (600026.SS) and China Merchants Energy Shipping (CMES) (601872.SS), following President Xi Jinping’s call for energy security.
Sinopec, a minority stakeholder of CMES, is also in talks to secure newbuilds at Jiangnan and Dalian, industry officials told Reuters. Sinopec declined to comment.
COSCO Shipping Energy is “ready to work hand-in-hand with shipowners and yards,” Qin Jiong, a company vice president, told an industry seminar last month, pointing to another advantage of using local shipyards.

FOREIGN ORDERS
While their labour costs are higher, Korean yards – such as Hyundai Heavy Industries (329180.KS) and Daewoo Shipbuilding & Marine Engineering (042660.KS) – are more efficient in design and construction and have a local supply chain, said Sunny Xu, founder of Singapore-based LNG solution provider C-LNG.
“Shipowners seem to have a more positive view about Korean shipyards … to realise the design shipowners want, ability to meet deadlines, and problem-free operation,” said a South Korean shipbuilding industry source who declined to be identified.
Still, Chinese yards received 19 foreign orders for LNG tankers this year and that number is likely to grow.
“Chinese yards have become more attractive because of the South Korean backlog, as well as rising costs,” said ICIS analyst Songer.
Chinese yards’ relationship with GTT also helps, he said.
“It is a fair assumption that China will start building a lot more vessels in the future.”
 Everchem Updates Archive
 Sign Up for Email Updates