
Asian Markets
October 16, 2025
Wanhua MDI Expansion Approved
EIA Approves Wanhua Fujian’s 1.5 MTPA MDI Expansion

On October 11, 2025, the Fuzhou Ecological Environment Bureau issued the “Approval Opinion on the Environmental Impact Report for the 1.5 million t/a MDI Technology-Upgrading and Capacity-Expansion Integration Project of Wanhua Chemical (Fujian) Isocyanate Co., Ltd.”, approving the project to be built at the location, in the nature and on the scale specified in the Report, and with the environmental-protection countermeasures set out therein.
The project is located on the reserved land within the existing plant area of Wanhua Chemical (Fujian) Isocyanate Co., Ltd. in the Jiangyin Port-City Economic Zone of Fuzhou. On the basis of the original 800 kt/a MDI plant, the MDI refrigerant, condensation, phosgenation and separation units will be technologically upgraded to match a 1.5 million t/a MDI capacity. Synchronous revamping and expansion of related utility and auxiliary facilities will be carried out, and reactors, towers, heat exchangers, pumps and other ancillary equipment will be procured and pre-installed. The project will add 700 kt/a MDI, 340.5 kt/a HCl and 2.6 kt/a methanol.
According to the evaluation conclusions of the Report and the technical review report (No. 2-2025-030) issued by the Fuzhou Environmental Impact Assessment Technology Centre, the project complies with the national industrial policy,meets the ecological-environment zoning-control requirements of Fujian Province and Fuzhou City, and is in line with the Fuzhou Chemical Industry Development Special Plan (2025-2030), the Jiangyin Port-City Master Plan (2018-2035) and the Industrial Development Plan for the Fuzhou Jiangyin Port-City Economic Zone as well as their respective plan-EIA requirements. Provided that all pollution-prevention and risk-prevention measures proposed in the Report are fully implemented, the project is environmentally feasible. This Bureau hereby approves the project to be constructed at the location, in the nature and on the scale specified in the Report, and with the environmental-protection countermeasures set out therein.
September 29, 2025
India Polymer Polyol ADD
India Imposes ADD on Chinese Copolymer Polyol Following DGTR Investigation
PUdaily | Updated: September 29, 2025
On September 26, 2025, the Indian government took steps to protect its domestic chemical industry from unfairly traded imports, announcing definitive anti-dumping duties on a key polymer imported from China. The decision follows an extensive investigation by the Directorate General of Trade Remedies (DGTR), which found evidence of significant dumping causing material injury to a local producer.
The duties apply to imports of “Copolymer Polyol of hydroxyl value >= 23.5” (HS Codes 3907 2910 and 3907 2990), a chemical primarily used in the production of flexible foam for mattresses and other applications. The DGTR clarified that Polyester Polyol of the same grade is excluded from this measure.
The investigation, initiated in September 2024, concluded that imports from China were entering the Indian market at dumped prices, with margins ranging from 20% to over 50%. This unfair pricing undercut domestic sales and severely harmed the financial health of the sole Indian manufacturer, M/s Expanded Polymer Systems Pvt. Ltd.
The following key findings from the investigation formed the basis for the final determination:
- Massive Import Surge & Market Displacement: Import volumes from China surged by 287% (from 4,988 to 19,338 MT), seizing over 90% of the total import market. This massive influx displaced traditional suppliers from Europe and the USA and severely eroded the domestic industry’s market share.
- Significant Price Undercutting & Suppression: The landed value of Chinese imports was consistently 10-20% below the domestic industry’s price. This forced the domestic producer to suppress its prices below its own cost of sales for the entire period, directly preventing profitability.
- Severe Financial Injury: Despite a 96% growth in domestic demand, the domestic company operated at a loss with negative returns. Its capacity utilisation was critically low at around 32%, while inventories swelled by 137%, confirming financial distress due to unfair competition.
- Causal Link Established: The Authority definitively ruled out other factors like demand contraction or technological changes, concluding that the surge of low-priced, dumped imports was the primary cause of the material injury.
In its final findings, the DGTR affirmed that Expanded Polymer Systems Pvt. Ltd. constitutes a valid ‘domestic industry’ and that a direct causal link exists between the dumped imports and the injury suffered.
Recommended Anti-Dumping Duties
The DGTR has recommended the following duties (CIF value in USD per Metric Tonne) for a period of five years:
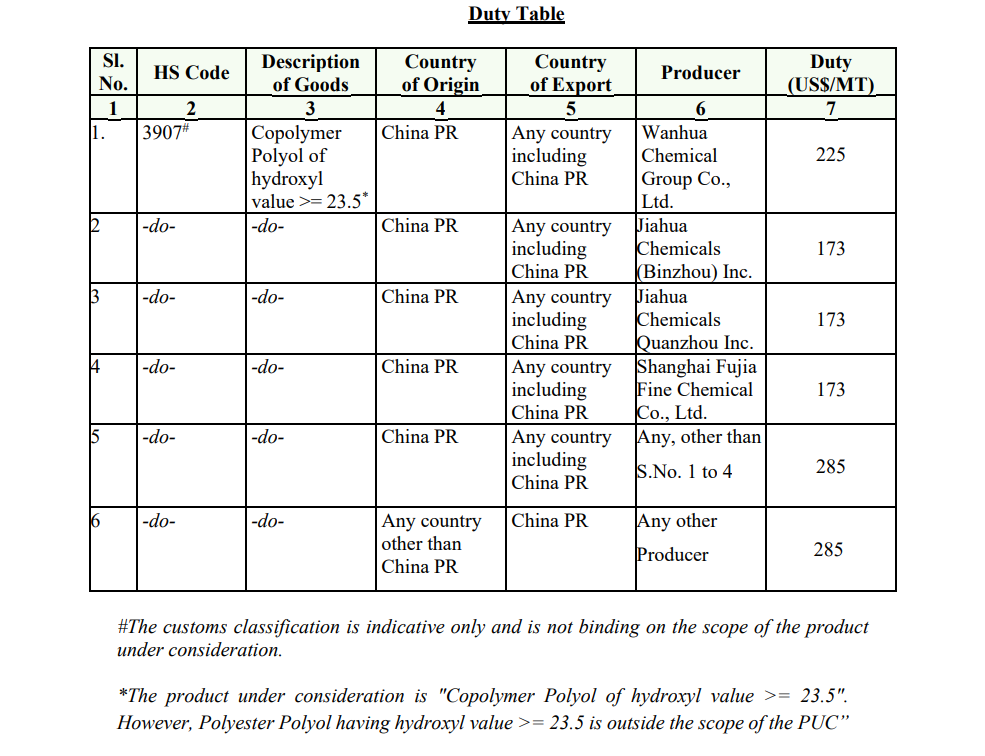
The authority stated that the imposition of these duties aligns with the World Trade Organisation’s (WTO) framework and aims to restore fair competition in the Indian market. It emphasised that the measures are not intended to restrict imports but to ensure they enter India at non-injurious prices, thereby safeguarding the interests of the domestic industry.
India’s Ministry of Finance will issue the final notification for the imposition of these duties.
September 23, 2025
Catch 22
India’s Sole TDI Plant has Shut Down Again, but China’s TDI export Dividend is Expected to Continue
It is reported that on September 19, 2025, India’s Gujarat Narmada Valley Fertilizer and Chemicals Limited (GNFC) announced that its 50000 tons/year toluene diisocyanate (TDI) Phase II plant in Dah was safely shut down due to a sudden gas leak. The company emphasized in its statement that the accident was controlled within the factory area and did not cause any casualties or property damage.
GNFC is the only large TDI manufacturer in India, with two TDI production facilities totaling 67000 tons per year. The TDI Phase I facility has a production capacity of 17000 tons per year, while the TDI Phase II facility has a production capacity of 50000 tons per year. The gas leak occurred in the TDI Phase II unit.
As the only large TDI manufacturer in India, especially the TDI Phase II unit, there have been frequent problems, including technical failures, gas leaks.
The TDI unit of GNFC, especially the large-scale Phase II unit involved in this incident, has experienced multiple technical failures, gas leaks, and even more serious safety accidents in history. As a company that adopts DuPont technology from the United States and is controlled by local governments in India, GNFC was originally a strategic pillar for India to achieve import substitution of key chemicals. But the long-term instability of its device operation still requires imported TDI from overseas as a supplement.
Despite the fragility of domestic supply, India has repeatedly targeted China, Japan, South Korea, the European Union, Saudi Arabia, and the United Arab Emirates since 2016
Wait for countries and regions to initiate anti-dumping investigations into imported TDI. The shutdown of GNFC will undoubtedly cause a shortage of TDI supply in India.
The supply-demand imbalance in the global TDI market is rapidly worsening
The discontinuation of GNFC is not an isolated event. Since the third quarter of 2025, the global TDI market has been affected by a series of unexpected and planned supply disruptions.
In July, global chemical giant Covestro’s 300000 tons/year TDI plant in Europe encountered force majeure; During the same period, there were disruptions in BASF’s facilities in South Korea, and the production capacity of Japanese companies such as Mitsui has not yet fully recovered from early shutdowns. This series of events has led to a significant contraction in overseas supply. Wanhua Chemical’s 250000 ton/year plant in Hungary has entered a 30 day maintenance period, further reducing its supply capacity to the European market. At the same time, major Chinese manufacturers have also entered the maintenance season. The abnormality of Wanhua Chemical’s domestic equipment has led to extreme shortage of spot supply and delayed shipment; Covestro and Shanghai BASF have also stated that their supply will be very limited in September and have significantly increased their product guidance prices.
On the demand side, exports have become the strongest growth engine. According to Chinese customs data, from January to August 2025, the total export volume of TDI in China reached 357000 tons, a year-on-year increase of 67.78%. Among them, 18400 tons were exported to India, accounting for 5.2%, ranking fourth among export countries. The force majeure in Europe, slow recovery of Japanese facilities, and subsequent maintenance plans for American facilities have collectively created a huge overseas demand gap.
China’s TDI export dividend is expected to continue
The unexpected shutdown of GNFC undoubtedly exacerbates the already severe overseas supply situation in the fourth quarter, and is expected to lead to severe shortages in the international market, thereby providing strong support for global TDI prices. Domestic production enterprises therefore have a broader export arbitrage window, but it may exacerbate the tight supply of goods in the domestic market, providing strong support for domestic TDI prices.
August 21, 2025
Chinese PMDI Trade Flows
China PMDI Trade Update: Exports Regionalize, Imports Increase from ME with Lower Prices
PUdaily | Updated: August 21, 2025
PMDI Export
In July 2025, China exported 64,100 tonnes of polymeric MDI, down 18% year‑on‑year and down 24.8% month-on-month, according to data released by the General Administration of Customs (GAC).
China’s polymeric MDI exports from January to July amounted to 476,500 tonnes, down 18% year-on-year.
Exports to ASEAN Countries and India Rise, With Pronounced Regionalization Trend
From January to July, cumulative exports from China to most of Top 10 destinations fell year-on-year, with the exceptions of India, Vietnam, and Thailand, which recorded increases. The polyurethane supply chain is exhibiting an increasingly pronounced regionalization trend. U.S. tariff policies have disrupted global trade flows, accelerating a shift from globalization toward regional trade for China’s polymeric MDI exports.
China’s FTAs with ASEAN economies, and geographic proximity, have also encouraged Chinese appliance, textile and automobile manufacturers to invest in or relocate production to Vietnam, Thailand, Indonesia and other nearby countries. These shifts hedge the trade uncertainty and reduce supply chain disruption risks of enterprises.
Table 1: China’s Top 10 PMDI Export Destinations, Jan-Jul 2025
| No. | Export Destination | Export Volume (tonne) | Export Value (US$1,000) | Avg. Price (USD/tonne) | Share (%) | YoY Change |
| 1 | Russia | 50,309 | 111,730 | 2,221 | 10.6% | -2.2% |
| 2 | Netherlands | 44,852 | 58,270 | 1,299 | 9.4% | -49.7% |
| 3 | Turkey | 38,863 | 64,410 | 1,657 | 8.2% | -18.6% |
| 4 | India | 35,570 | 62,330 | 1,752 | 7.5% | 18.3% |
| 5 | USA | 30,697 | 36,140 | 1,177 | 6.4% | -82.1% |
| 6 | S. Korea | 30,625 | 52,560 | 1,716 | 6.4% | -30.6% |
| 7 | Vietnam | 23,790 | 46,480 | 1,954 | 5.0% | 0.1% |
| 8 | Brazil | 23,075 | 38,500 | 1,668 | 4.8% | -14.5% |
| 9 | Thailand | 22,366 | 41,740 | 1,866 | 4.7% | 5.7% |
| 10 | UAE | 22,301 | 42,360 | 1,899 | 4.7% | -31.1% |
| Others | 154,100 | 273,660 | 1,776 | 32.3% | – | |
| Total | 476,548 | 828,170 | 1,738 | 100.0% | -34.0% |
PMDI Import
In July 2025, China imported 42,300 tonnes of polymeric MDI, up 70.1% year-on-year and up 85.6% month-on-month.
China’s polymeric MDI imports from January to July totaled 205,400 tonnes, up 16.9% year-on-year. Monthly imports had ranged between 20,000-35,000 tonnes from January through June, but surged to 42,000 tonnes in July, driven by higher imports from Saudi Arabia and South Korea, the increase from Saudi Arabia was particularly notable.
China imported 19,700 tonnes of polymeric MDI from Saudi Arabia in July, up 50.7% month-on-month. January-July imports from Saudi Arabia totaled 92,200 tonnes, up 27.6% year-on-year. Strength in China’s PMDI market in May-June, combined with relatively low price levels in the Middle East and Europe (around USD 1,700/tonne), encouraged increased Middle East shipments into China.
Imports from South Korea also rose (Jan-Jul volumes up 27% year-on-year), but Korean goods carried a higher average price – about USD 1,949/tonne – exceeding the average import prices from Saudi Arabia and Japan.
Table 2: China’s polymeric MDI Imports, Jan-July 2025
| No. | Import Source | Import Volume (tonne) | Import Value (US$1,000) | Avg. Price (USD/tonne) | Share (%) | YoY Change |
| 1 | Saudi Arabia | 92,167 | 124,970 | 1,356 | 44.9% | 27.6% |
| 2 | Japan | 53,810 | 77,270 | 1,436 | 26.2% | -14.3% |
| 3 | S Korea | 48,593 | 94,700 | 1,949 | 23.7% | 27.2% |
| Others | 10,838 | 22,250 | 1,776 | 32.3% | – | |
| Total | 205,408 | 319,190 | 1,738 | 100.0% | -34.0% |
August 12, 2025
Wanhua Results
Wanhua Chemical Released 1H 2025 Financial Report

PUdaily | Updated: August 12, 2025
On August 11, Wanhua Chemical released its 1H 2025 financial report. The company posted revenue of CNY 90.90 billion, down 6.4 % year-on-year; net profit attributable to shareholders was CNY 6.12 billion, down 25.1 %; recurring net profit was CNY 6.24 billion, down 22.9 %; and net cash from operating activities was CNY 10.53 billion, up 2.3 %.
In the second quarter, revenue reached CNY 47.83 billion (-6.0 % YoY); net profit attributable to shareholders was CNY 3.04 billion (-24.3 % YoY); and recurring net profit was CNY 3.20 billion (-19.3 % YoY).
In the report, the company noted that despite weak global demand and geopolitical tensions, the chemical industry remained stable overall. Wanhua continued to optimize the structure of its polyurethane, petrochemicals, specialty chemicals and advanced materials businesses. Within polyurethane, demand from new-energy and high-end manufacturing segments was robust, while overseas energy-efficient construction markets underperformed.
In petrochemicals, concentrated capacity additions created supply-demand imbalances, pushing prices lower and compressing margins. Specialty chemicals and advanced materials benefited from supportive national policies and achieved steady growth with promising prospects. Under the management theme of “Year of Transformation,” the company reorganized structures and mindsets, strengthened cost control and resource-allocation efficiency, and responded actively to market shifts to sustain optimization.
Wanhua remains innovation-driven to upgrade its portfolio. It is advancing next-generation MDI technology, expanding capacity and implementing energy-saving projects to achieve best-in-class cost competitiveness. In-house technologies are being commercialized rapidly: the MS unit started up successfully on the first attempt, enriching the optical product line; tert-butylamine reached industrial scale, extending the specialty amine chain; sulfone polymers have produced on-spec material, rounding out Wanhua’s engineering-plastics solutions; bio-based 1,3-butanediol has been qualified by cosmetics customers. Battery-material R&D continues to accelerate: fourth-generation lithium iron phosphate is already in mass production, and the fifth generation has completed its initial release. A differentiation strategy yielded multiple high-value-added POE, polyolefin, nylon 12 and modified-material grades, penetrating niche markets and boosting new-business capabilities. AI-enabled research projects are progressing in an orderly manner; the National Key Laboratory for High-Performance Organic Optical Polymers and Advanced Manufacturing Technologies remains focused on strategic needs, deepening external collaboration and building mutually beneficial ecosystems with industry partners. In 2025, the company filed 469 domestic and international invention patents and was granted 269, accelerating overseas patent deployment to support global expansion of new businesses.
 Everchem Updates Archive
 Sign Up for Email Updates