
Asian Markets
August 7, 2025
Hanwha TDI Issues
Hanwha Temporarily Suspends T65 and T100 Production, Repair Expected in 10 Days
PUdaily | Updated: August 7, 2025
According to overseas market sources, Hanwha Solutions has temporarily suspended the production of T65 and T100 due to a leakage detected in the heat exchanger used for freezing TDI 80/20. The repair work is currently underway and is expected to be completed within approximately 10 days. Meanwhile, the T80 production line is also experiencing operational difficulties due to issues at the HYCO plant, which have led to a decrease in operating rates. Hanwha is working to resolve these problems and will provide an update on the expected date of normal operation.
August 6, 2025
Korean Spandex Producer to Exit China

Taekwang Industrial to Withdraw from China, Halts Spandex Operations
PUdaily | Updated: August 6, 2025
Taekwang Industrial has made the final decision to completely halt operations of its Chinese subsidiary, Taekwang Synthetic Fiber (Suzhou), and withdraw from business in China after 20 years of presence. This drastic measure was taken due to global oversupply and weak demand, which resulted in operating losses of 93.5 billion won over the past three years.
Taekwang Industrial announced on July 31 that its board of directors held a meeting on July 30 and resolved to cease operations of Taekwang Synthetic Fiber (Suzhou). The company plans to halt all production at its factories in August and conclude sales activities for inventory disposal by October. Currently, 502 employees work at Taekwang Synthetic Fiber, and the company aims to complete the collection of accounts receivable and terminate employee contracts by the end of the year.
The board of directors also resolved to raise 100 billion won through a rights offering to facilitate the withdrawal from China. The funds will be used to repay loans due to accumulated deficits and for operating capital. A Taekwang Industrial official stated, “The decision to withdraw from China is a measure to prevent further accumulation of losses and strengthen the competitiveness of our core businesses,” adding, “Based on this decision, we will improve management efficiency and accelerate the discovery of new growth engines.”
Taekwang Industrial was the first in Korea to successfully commercialize spandex in 1979. In 2003, when former Chairman Lee Ho-jin was serving as the representative, the company established its Chinese subsidiary and began commercial production in 2005, securing an overseas spandex production base.
Taekwang Synthetic Fiber has been producing 27,000 tons of spandex annually. Since its establishment until last year, it recorded cumulative sales of 2.6143 trillion won and cumulative operating losses of 68.6 billion won. Recently, operating losses reached 93.5 billion won over the past three years, and in the first quarter of this year, it recorded a loss of 7.2 billion won, falling into a state of complete capital impairment with negative total equity.
July 23, 2025
Chinese TDI Update
Chinese TDI Prices Surge 20% in a Week amid Force Majeure in Europe and Supply Cuts
PUdaily | Updated: July 23, 2025
China’s TDI market has surged in July due to an array of positive news:
– On July 9, Covestro Shanghai raised its TDI guide price to CNY 12,700/tonne in bulk;
– On July 9, Wanhua Chemical stopped taking orders in Southeast Asia due to excessive demand and planned to raise its July TDI price by USD 100/tonne;
– On July 10, Covestro Shanghai announced suspension of TDI trading;
– On July 11, Wanhua Chemical increased its mid-July price for TDI by CNY 1,000/tonne to CNY 13,500/tonne;
– On July 12, a fire broke out at an external transformer station in building L26 at Chempark Dormagen. On July 16, Covestro declared force majeure on TDI;
– On July 14, Covestro Shanghai raised its TDI price to CNY 13,200/tonne;
– On July 14, Covestro Shanghai again halted TDI trading;
– On July 16, Covestro Shanghai further raised the TDI price to CNY 14,200/tonne;
– On July 17, Wanhua Chemical stopped taking orders from distributors for TDI;
– On July 17, BorsodChem increased TDI price by EUR 500/tonne;
– On July 18, Wanhua Chemical raised the July TDI price for direct sales by CNY 4,500/tonne to CNY 18,500/tonne;
– On July 18, Covestro Shanghai raised the TDI price to CNY 17,100/tonne.
Meanwhile, multiple TDI facilities are under maintenance. Wanhua Chemical’s Phase I TDI facility in Fujian has been shut down for maintenance since June 5. This maintenance, expected to span 45 days, has yet to come to an end. Xinjiang Heshan Juli’s TDI facility started maintenance on July 15 and is expected to last 33 days. Gansu Yinguang’s TDI facility is scheduled to undergo maintenance at the end of July for 7-15 days. BorsodChem’s 250 ktpa TDI facility began routine maintenance on July 19, which was scheduled for four weeks.
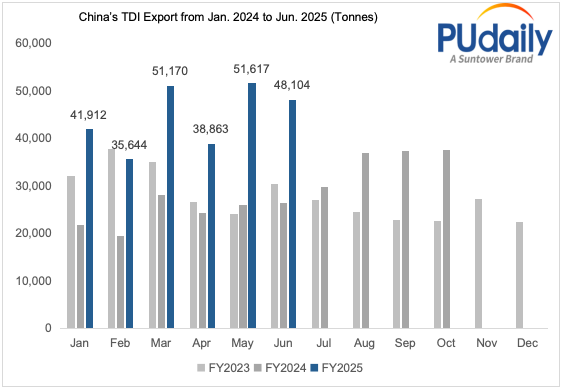
China’s TDI exports continued to see better-than-expected performance.
China exported 48,000 tonnes of TDI in June 2025, a year-on-year increase of 81.6%. China’s TDI exports from January to June 2025 amounted to 267,000 tonnes, up 82.9% year-on-year. The total annual export volume is expected to exceed 400,000 tonnes, reaching a record high.
Buoyed by multiple bullish factors, traders have mostly halted trading or maintained high prices starting mid-July. As of July 18, TDI prices in China had risen sharply to around CNY 15,000/tonne, up nearly CNY 2,500/tonne month on month, representing a weekly increase of nearly 20%. Some traders even quoted prices as high as CNY 17,000/tonne or above.
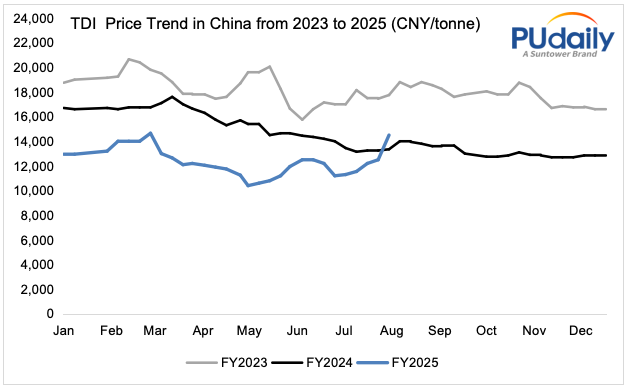
Actually, the current TDI price is still at historically low levels and just surpassing the producers’ break-even point. Although TDI prices have seen significant increases recently, there remains some upward momentum due to supply reductions and robust export demand. Moving forward, as some facilities resume production after maintenance, TDI supply will fluctuate and price trends will be impacted. If facilities are restarted as scheduled and production levels return to normal, increased supply may slow the price rise or even lead to a correction. If restarts are delayed or production falls short of expectations, it can lead to further price hikes due to ongoing supply tightness.
Given these unpredictable dynamics, access to accurate, real-time market intelligence has become essential. PUdaily’s Pricing Intelligence Service and dedicated Asia-Pacific TDI reports help industry participants anticipate shifts, benchmark prices, and make better-informed procurement and sales decisions amid the uncertainty.
July 1, 2025
China TDI Exports
China’s TDI Exports Registered a Sharp Increase in January-May 2025
PUdaily | Updated: July 1, 2025
In May 2025, China imported 85 tonnes of TDI worth USD 197,100 at an average price of USD 2,311/tonne, according to data by the General Administration of Customs. The import volume decreased 28.96% month-on-month and slumped 87.08% year-on-year.
China exported 51,617 tonnes of TDI in the month, earning around USD 84.13 million at an average price of USD 1,630/tonne. Export volume increased 32.82% month-on-month and jumped 98.45% year-on-year.
Table 1 China’s TDI Imports & Exports, 2024-2025 (tonne)
| Month | Import Volume | Export Volume | ||||||
| 2024 | 2025 | YoY Change | MoM Change | 2024 | 2025 | YoY Change | MoM Change | |
| Jan. | 1,160 | 280 | -75.90% | -75.10% | 21,749 | 41,912 | 92.70% | 4.50% |
| Feb. | 1,992 | 260 | -86.90% | -7.10% | 19,562 | 35,644 | 82.20% | -15.00% |
| Mar. | 3,140 | 290 | -90.80% | 11.50% | 28,062 | 51,170 | 82.30% | 43.60% |
| Apr. | 2,503 | 120 | -95.20% | -58.60% | 24,258 | 38,863 | 60.20% | -24.10% |
| May | 660 | 85 | -87.10% | -29.20% | 26,010 | 51,617 | 98.50% | 32.80% |
| Jun. | 2,182 | 26,486 | ||||||
| Jul. | 929 | 29,781 | ||||||
| Aug. | 1,747 | 37,007 | ||||||
| Sep. | 1,364 | 37,302 | ||||||
| Oct. | 1,220 | 37,656 | ||||||
| Nov. | 245 | 38,559 | ||||||
| Dec. | 1,124 | 40,089 | ||||||
| Total (Jan-May) | 8,795 | 1,030 | -88.30% | – | 93,631 | 219,206 | 134.10% | – |
Figure 1: China’s Monthly TDI Exports, 2023-2025 (tonne)

Table 2. China’s TDI Export Destinations & Export Volumes, Jan.-May 2025 (tonne)
| Destination | Export Volume | Share |
| Indonesia | 22,213 | 10.1% |
| Vietnam | 20,892 | 9.5% |
| India | 11,941 | 5.4% |
| Brazil | 11,266 | 5.1% |
| Nigeria | 11,240 | 5.1% |
| Kenya | 8,100 | 3.7% |
| Mexico | 7,166 | 3.3% |
| Turkey | 7,136 | 3.3% |
| Columbia | 7,100 | 3.2% |
| Argentina | 6,554 | 3.0% |
| Others | 105,599 | 48.2% |
| Total | 219,206 | 100.0% |
China’s TDI exports from January to May 2025 amounted to 219,206 tonnes, registering a sharp increase of 134.1% compared to the same period last year. The total annual export volume is poised to achieve a remarkable growth this year.
June 13, 2025
Chinese Mattress Exports
China’s Foam Mattress Exports Demonstrated Resilience Due to Stable Demand in Jan-Apr
PUdaily | Updated: June 10, 2025
China exported a total of 9.975 million foam mattresses during January to April 2025, down 2.5% year-on-year. The export value was USD 236 million, a decrease of 3.2% compared to the same period last year, according to customs data. The declines in the two key indicators were both below 3%, demonstrating the industry’s resilience amid rising uncertainties. The total weight of mattresses exported from China during this period reached 47,900 tonnes, up 2.1% year-on-year, reflecting a slight adjustment in product structure and an overall stable demand.
| Foam Mattress Exports(Under HS Code 94042100) | Quantity (1,000 pieces) | Weight (1,000 tonnes) | Value (USD 100 million) |
| Jan-Apr 2025 | 9,974.80 | 47.9 | 2.36 |
| Jan-Apr 2024 | 10,226.30 | 46.9 | 2.44 |
| YoY Change | -2.50% | 2.10% | -3.20% |
China’s Monthly Foam Mattress Exports 2023-2025 (tonne)
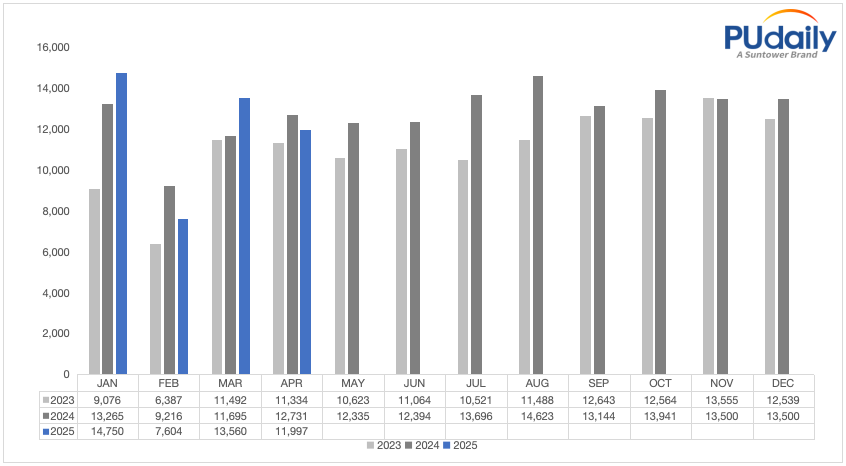
From January to April, Japan was the first export destination for Chinese foam mattresses, with exports totaling 7,881 tonnes, up 5.2% year-on-year, accounting for 16.4% of China’s total exports.
Table 1: Top 15 Export Destinations for China’s Foam Mattresses (Jan-Apr 2025)
| Destination | Weight (tonnes) | Share (%) |
| Japan | 7,881 | 16.44% |
| USA | 7,146 | 14.91% |
| Germany | 3,974 | 8.29% |
| Mexico | 3,461 | 7.22% |
| Australia | 3,219 | 6.71% |
| France | 2,516 | 5.25% |
| UK | 2,037 | 4.25% |
| South Korea | 1,827 | 3.81% |
| Thailand | 1,103 | 2.30% |
| Poland | 1,083 | 2.26% |
| Others | 13,693 | 28.56% |
| Total | 47,940 | 100.00% |
Among these export destinations, traditional markets such as Japan, the USA and Germany made up 44.55% of the total exports (with the top three destinations combined to occupy 39.64% of the market share). Exports to Japan increased by 5.2% year-on-year to 7,881 tonnes, highlighting strong resilience in key markets. Although some market shares fluctuated slightly, the top 15 destinations accounted for over 70% of exports, indicating a stable market landscape and endorsing the robust demand for Chinese mattress products in the international market.
It indicates that China’s mattress industry could hold on in the face of an ever-changing global environment. Chinese manufacturers have made risk mitigation efforts to counter external uncertainties, such as retaining existing customer bases and optimizing product structure. The slight changes in export volume and value mostly reflect normal market fluctuations rather than a shift in demand trends. The fundamentals remain stable and strong.
Going forward, China’s mattress exports are expected to keep resilient amid stable recovery in global consumer demand. Chinese businesses should continue to focus on market needs and optimize supply chain, steadily increasing added value while maintaining cost advantages, thereby further enhancing market share and promoting sustainable industrial development.
 Everchem Updates Archive
 Sign Up for Email Updates