
Current Affairs
September 10, 2024
East Coast Shipping Strike
Customs broker urges importers to delay their shipments to avoid East Coast strike
Bobby Dalheim //Senior Editor of Case Goods and Global Sourcing//September 9, 2024
NORFOLK, Va. – With a potentially massive strike looming over East Coast ports in early October, one customs broker and logistics provider is suggesting importers delay their shipments.
“Leading up to the U.S./Canada East and Gulf Coast labor contract expiration on Sept. 30, there is a lot of uncertainty throughout the market,” said Rachel Shames, vice president of pricing and procurement for CV International, in a blog post. CV is a member of the American Home Furnishings Alliance and often does business with furniture importers.
“There’s been no progress in labor negotiations over recent months, and it seems likely that a labor disruption will occur effective Oct. 1,” she said. “It’s also possible we will see port work slowdowns begin before the official contract expiration date. The duration of any disruption or strike is unknown; hopefully any action will last only a few days, if that long.”
As such, Shames says shippers should be prepared for delays in the coming weeks.
“If shipments can be delayed until later in October or November, it would be a good idea to consider postponing until the market settles,” she said.
Container rates to both U.S. coasts have been dropping steadily for the past six or so weeks but remain volatile. An increase in West Coast rates is expected as East Coast importers begin to shift away from the East Coast in anticipation of the strike.
“Levels have been softening gradually since July, but we expect West Coast rates will increase as of Sept.15,” Shames said. “East and Gulf Coast from Asia may continue to decline, but with the potential for major congestion, we could see extra charges announced. There is still a wide range of rates in the market: FAK levels remain relatively strong compared with fixed contract rates, but carriers are still offering special spot deals for specific sailings (although many of those sailings are filling up fast, and cargo booked on those low deals is likely to roll).”
As of early September, both parties involved in the strike – the International Longshoremen’s Assn., which represents 85,000 dockworkers, and the U.S. Maritime Alliance (USMX) – still indicate that a successful negotiation is far off. The primary issue of contention seems to be automation, as the ILA has alleged that certain ports are using an auto gate system, which allegedly violates the current contract.
“The ILA most definitely will hit the streets on Oct. 1 if we don’t get the contract we deserve,” said ILA President Harold Daggett in a recently surfaced video. “Mark my words, we’ll shut them down.”
In a press release dated Sept. 5, the USMX said the ILA continues to “strongly signal it has already made the decision to call a strike” and that it hopes the ILA “reopens dialogue.” The ILA issued a letter to its members as a response, calling the USMX release “propaganda” and explaining its stance in detail.
September 9, 2024
Gulf Storm This Week
Oil Rises As Major US Refineries In Path Of Strengthening Gulf Storm
by Tyler Durden
Monday, Sep 09, 2024 – 08:45 AM
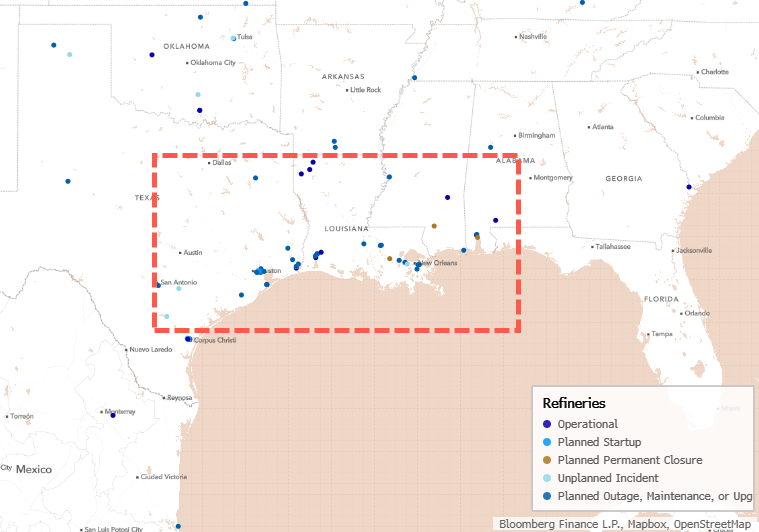
Oil and gasoline futures moved higher early Monday as the National Hurricane Center tracked a potential tropical system that threatened parts of the US Gulf Coast later this week. The storm could slam into the upper Texas and Louisiana coasts, accounting for about 60% of US refining capacity.
Potential Tropical Cyclone Six, or Invest 91L, churns in the southwestern Gulf of Mexico early Monday and is forecasted to become a hurricane before it reaches the northwestern US Gulf Coast late Wednesday. The storm emerges right on time, at the peak of the Atlantic hurricane season. It is interesting to note that this hurricane season has been very quiet.
“While it is too soon to pinpoint the exact location and magnitude of impacts, the potential for life-threatening storm surge and damage winds are increasing for portions of the Upper Texas and Louisiana coastlines beginning Tuesday night,” the NHC wrote in its latest update.
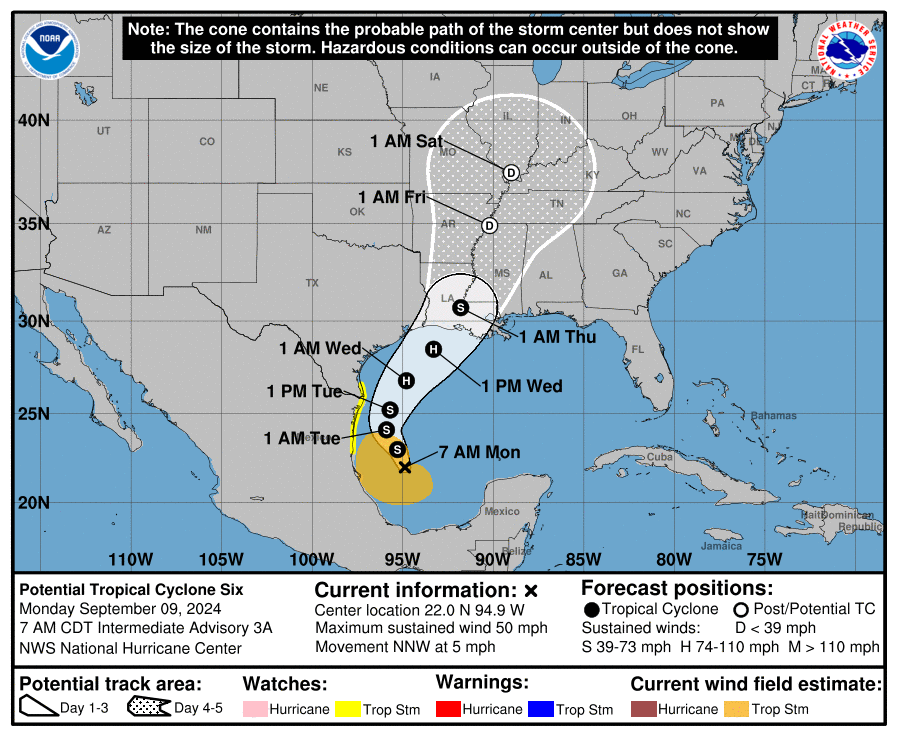
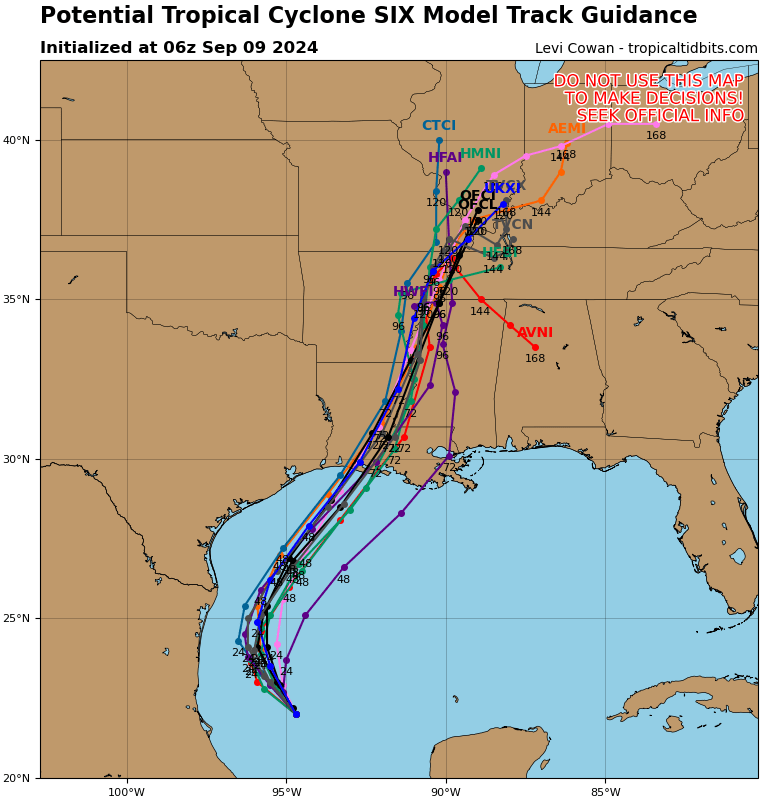
The latest hurricane trajectory models show strong consensus that the tropical system could make landfall along the Louisiana coast.
This area of the Gulf Coast is home to approximately 60% of US refining capacity. Bloomberg data shows several refineries are in the storm’s cone of uncertainty.
“A small recovery in prices is underway this morning, inspired by hurricane warnings that might threaten the US Gulf Coast, but the wider conversation remains on where demand will come from and what OPEC+ can do,” PVM analyst John Evans told Reuters.
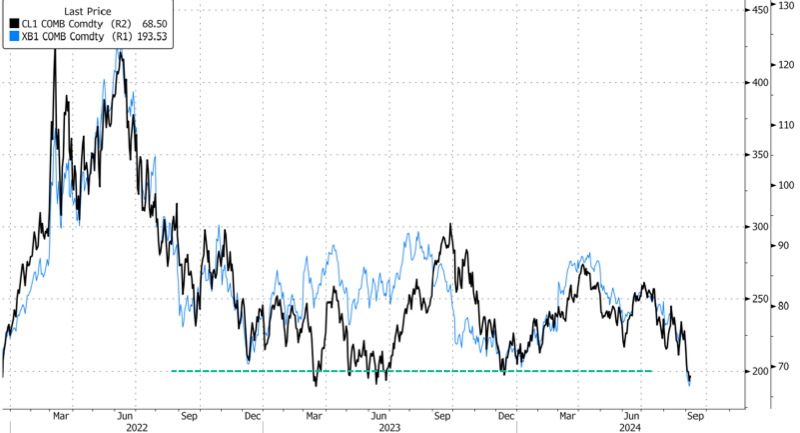
In recent weeks, Goldman’s commodity analyst—now without “supercycle” permeable Jeff Currie—Daan Struyven slashed his expected range for Brent oil prices by $5 to $70-$85 per barrel, citing weaker Chinese oil demand, high inventories, and rising US shale production. The biggest driver for the cut is his belief that “OPEC will raise production in Q4…”
Morgan Stanley has also recently revised its oil price forecasts downward, reflecting expectations of increased supply from OPEC and non-OPEC producers amid signs of weakening global demand. The bank now anticipates that while the crude oil market will remain tight through the third quarter, it will begin to stabilize in the fourth quarter and potentially move into a surplus by 2025.
Morgan Stanley has cut its forecast for the fourth quarter to $80 per barrel, down from $85, and now expects prices to gradually decline to $75 per barrel by the end of 2025, slightly lower than their previous estimate of $76.
None of this is new to the market, where sentiment is ultra-bear…
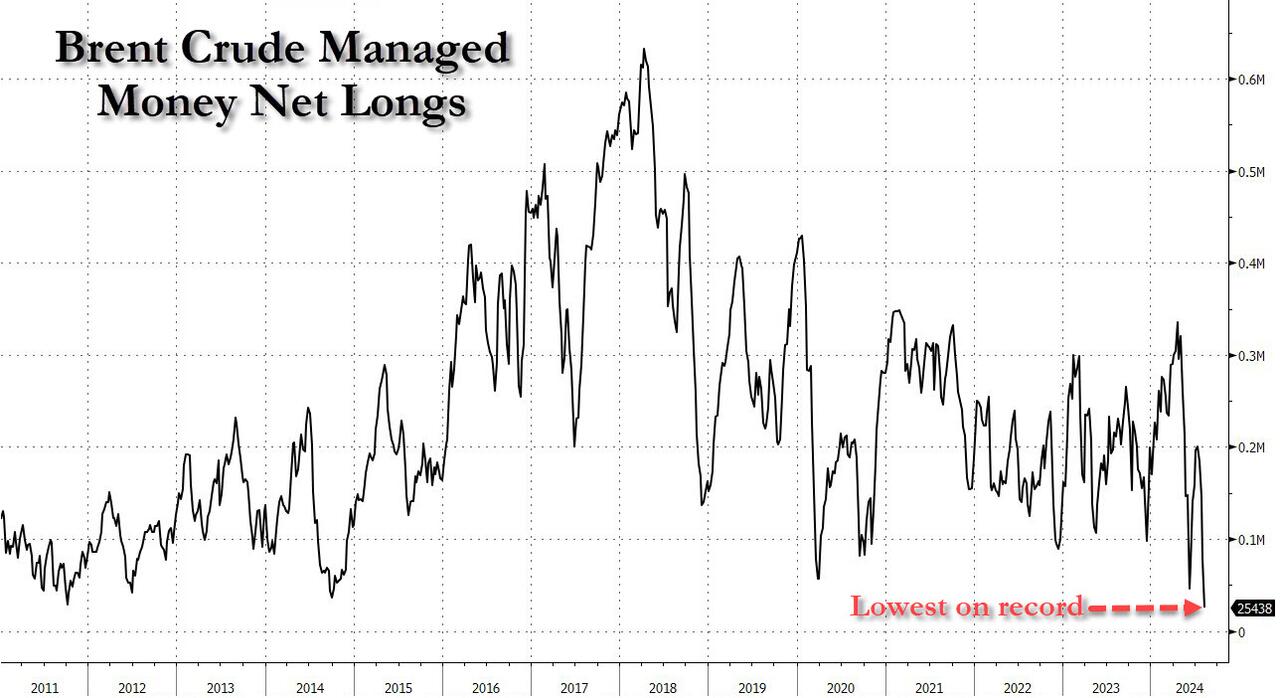
However, a tropical system that supercharges in the Gulf of Mexico’s warm waters and knocks out a few refineries could easily send energy prices back up.
https://www.zerohedge.com/commodities/oil-rises-major-us-refineries-path-strengthening-gulf-storm
September 9, 2024
Acoustic Foam for Tires
Henkel and 4JET revolutionize silent tire production for EVs

Share LinkedIn Twitter Facebook Email

L-R: Dr. Armin Kraus, co-CEO at 4JET, Imke Vogel, Market Segment Head Automotive Components Europe at Henkel, Dr. Jan Flohre, Head of Laser Process Development at 4JET and Dr. Rainer Schönfeld, Global Market Strategy Head Automotive Components at Henkel.
As EVs lack engine noise, tire rolling sound becomes more noticeable, often perceived as intrusive and unpleasant. To combat this, manufacturers have been equipping EVs with “Silent Tires,” featuring acoustic polyurethane foam linings. However, this solution has presented logistical and cost challenges, increasing tire production expenses by up to 25%.
The new Laser-Fit process, developed by Henkel and 4JET, promises to streamline production and reduce costs. This method involves creating acoustic foam directly inside the tire from liquid materials at the end of the production line, eliminating complex logistics and manual steps.
“Our new to market Loctite Laser-Fit acoustic foam achieves its sound absorption effect through a large inner surface and a pore design specifically tailored for tire noise suppression,” said Dr. Rainer Schönfeld, Global Market Strategy Head in Henkel’s Automotive Component business unit.
The process utilizes a patented laser activation technique to remove the foam’s air-impermeable skin, allowing for effective sound absorption. This innovation not only simplifies production but also offers manufacturers greater flexibility in foam design and reduces waste.
“This revolutionary direct-foam-to-tire technology represents our joint commitment to innovation and sustainability,” said George Kazantzis, Global Head of Henkel’s Automotive Components business unit. “By eliminating the transportation of pre-fabricated foam and reducing cutting waste, we will enable our customers to lower their carbon footprint.”
The partners developed this technology in record time, showcasing the innovative strength of German SMEs. Dr. Armin Kraus, co-CEO of the 4JET Group, praised the collaboration: “In Henkel, we have found the ideal development partner for this innovation… From the idea to the finished application in record time.”
The complete solution will be presented at RubberTech24 in Shanghai this month, marking, the companies hope, a significant advancement in EV tire technology.
www.electrichybridvehicletechnology.com/news/henkel-and-4jet-revolutionize-silent-tire-production-for-evs.html
September 8, 2024
Epoxy Resin Anti-dumping Analysis
Epoxy Resin Anti-dumping in an Era of Keen Economic Protectionism
Jane Denny : Aug 19, 2024 2:35:26 PM
Petrochemical TrendsNorth American Chemical MarketEpoxy Resin
European and US-based epoxy resin producers have triggered anti-dumping investigations against Asian producers in a bid to stop cheap imports. Meanwhile, India—the subject in the US complaint—claims to be a victim of dumping activity, too.
Last month, US-based chemical manufacturing companies Olin and Westlake and Spolchemie—based in the Czech Republic—submitted data to the European Commission (EC) outlining uncompetitive practice. Following the complaint, the EC initiated investigations into trading by producers in China, South Korea, Taiwan, and Thailand.
The move follows the initiation of a probe into the same countries—with the addition of Indian epoxy resin producers—by the US Department of Commerce and the US International Trade Commission in April 2024.
India’s Ministry of Commerce meanwhile, has initiated an anti-dumping investigation into liquid epoxy resin imports from the same countries as those under European Union (EU) and US scrutiny, and Saudi Arabia too.
Source: ResourceWise
What Is Anti-dumping?
Dumping occurs when imported products are made available to buyers at prices lower than fair market value. Investigations are triggered when domestic producers raise concerns about the prices of foreign goods sold in their domestic markets.
Under EU conditions, there is a two-step test to ascertain whether dumping has occurred. Firstly, the export price of a product must be lower than its selling price in the exporting country. Secondly, the product’s availability in the market must have been injurious to the domestic producer community’s business.
If investigators find that dumping has occurred, measures are put in place to mitigate the problem.
 China’s Capacity Growth Key
Jennifer Hawkins, Chemicals Sector Business Manager at ResourceWise, points to China’s significant increase in epoxy resin capacity in recent years, as shown in the infographic above.
“The growth in China’s domestic capacity has forced producers in South Korea and Taiwan to export their epoxy resins to other markets outside China—their erstwhile customer. At the same time, China, historically a net importer of epoxy resins, has started to export volumes to other regions too,” says Hawkins.
White Paper Download
Download Hawkins’ analysis of EU and US ADD investigations and International Trade Commission conference submissions, including insight from her epoxy resin market contacts.

In our 2022 blog post, How Will New Capacities Reshape the Epoxy Resin Market?, we explored China’s extra epoxy resin production capacity. With more of that planned expansion now realized, an oversupply scenario has replaced the tightness in global supply that triggered the expansions.
Back then, we predicted that “a supply glut… will undoubtedly create fierce competition, drive prices down, and possibly encourage a rise in exports.” This has now come to fruition.

Source: ResourceWise
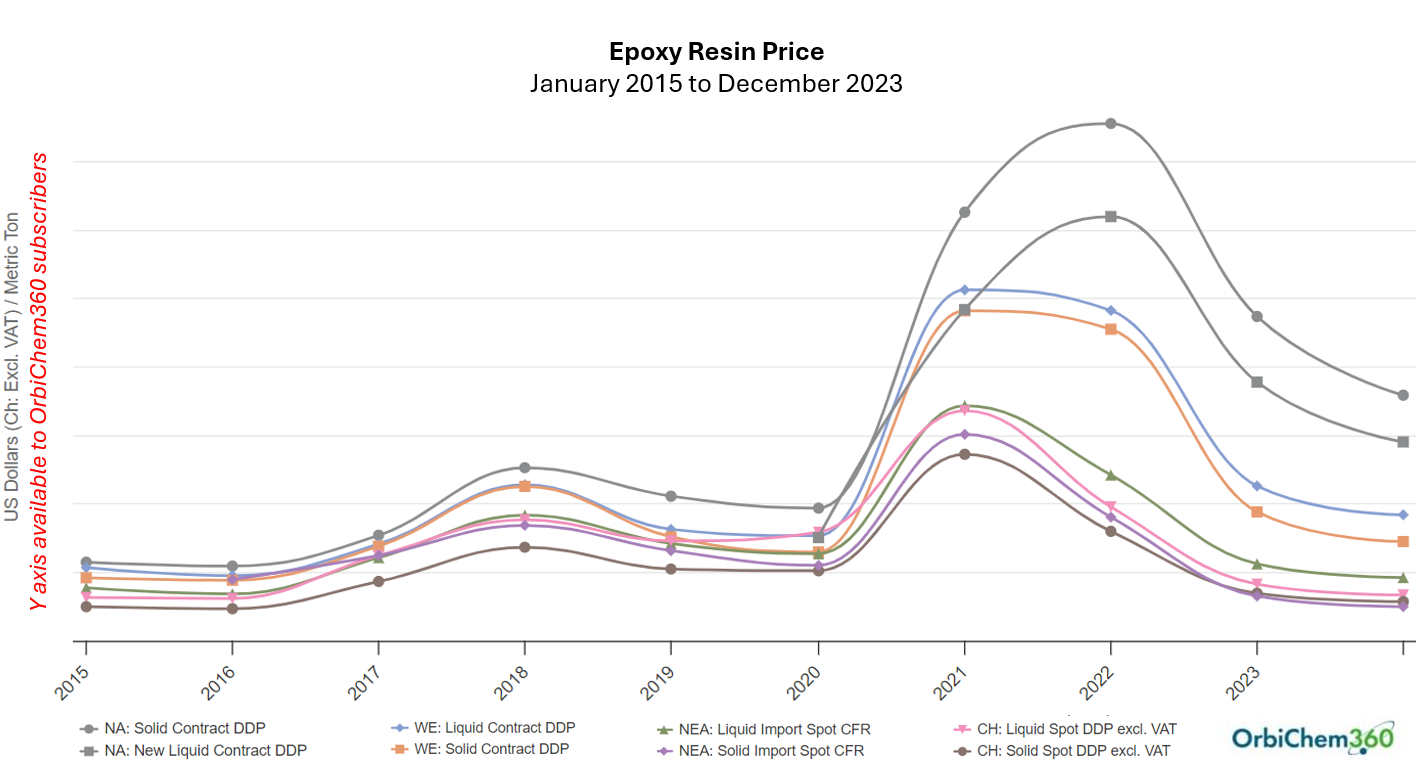
China’s current spot liquid and solid epoxy resin prices are close to their lowest price point over the past near-decade, back in 2016. And even then, the drop was relatively fleeting. Both products have remained low and relatively flat since the close of 2023, as they have in Northeast Asia.
Modest rises have been seen in North American and European pricing structures this year. However, as the graph below shows, North American prices alone did not see any significant increase up to the end of 2023, which producers there have maintained to this day.

Measures to Protect
Anti-dumping duties are imposed by authorities within the country—in the case of the US—or region—such as the EU trading block. They are designed to level up the prices of incoming goods with those produced and sold domestically.
In the EU, producers selling into the region may be taxed according to transaction value or per specific amount of the product. The exporter may even agree to sell products at a minimum price.
In both Europe and the US, complainants sought an investigation into the level of dumping by China, South Korea, Taiwan, and Thailand. They seek adjudication on the question of whether dumped imports have caused material injury to the domestic epoxy resin industry.
The US-focused scrutiny was initiated following a complaint by Olin and Westlake. Unlike the EU complaint, the US complaint requests an investigation of India’s alleged dumping activities.
European Epoxy Resin Anti-dumping
In the EU-focused complaint—in which Spolchemie is a complainant alongside Olin and Westlake—it is alleged that exporting producers from Asian countries have injured European epoxy resin producers. The countries claim that they are selling products in the EU market at unfairly low prices, which significantly undercuts the prices of European producers.
| Country | Dumping margins alleged |
| China | From 140% |
| Korea | From 10% |
| Taiwan | From 20% |
| Thailand | From 60% |
∗ See our free-to-download white paper for upper margins alleged
Epoxy Resins Plant Shutdowns
Speaking to the EU complaint, Olin Epoxy & International president Florian Kohl president said: “Although this issue is not unique to epoxy, nor to the EU, the significant volume of what we believe are unfairly dumped imports of epoxy resin have a seriously negative impact on the EU.”
In March 2023, Olin announced plans to cease operations at its Cumene facility in Terneuzen, Netherlands. and solid epoxy resin production at its facilities in Gumi, South Korea, and Guaruja, Brazil.
At the time, the company described it as a “step to right-size our global epoxy asset footprint to the most cost-effective asset base to support our strategic operating model.” However, as part of that announcement, Olin referenced the softness of global epoxy demand and the surplus supply in the market.

Source: ResoureWise
Market Dynamics At Play
In the US-focused complaint, the country’s Department of Commerce has been asked to assess allegations involving exponentially higher margins.In part, the elevated price tags attached to epoxy resins in the US account for the significant price gap compared to all other regions.
In fact, global epoxy resin price graphs from the chemicals business intelligence platform OrbiChem360 indicate the price differential between North American products and Asian output is several thousand dollars. With Asian producers subject to lower output costs, that price gap creates an opportunity for exports to US buyers.
| Trading Partner | Dumping Margin alleged |
| China | From 266.37% |
| India | From 9.92% |
| Korea | From 35.29% |
| Taiwan | From 91.15% |
| Thailand | From 143.73% |
∗ See our free-to-download white paper for upper margins alleged
Subsidized Industry and Anti-competition
According to a report by the US International Trade Administration (ITA), all countries under investigation for anti-dumping (except Thailand) will also be tested for Countervailing Duties (CVD). Also termed anti-subsidy duties, they are designed to counter the negative effects of subsidies.
The suggestion is that within all the countries named in the US complaint except Thailand, respective governments are propping up the epoxy resin sector with incentives. Established under World Trade Organization (WTO) rules, a subsidy includes grants, loans or tax credits.
Anti-dumping Duties: A Trending Solution
Anti-dumping measures are being implemented with increasing frequency as companies—and nations—seek to protect regional and local market shares.
In 2023, the EC proposed duties of between 6.6% and 24.2% for Chinese polyethylene terephthalate (PET) producers found to be importing goods at uncompetitive prices.
Similarly, the EC’s recent initiation of provisional anti-dumping duties against the majority of China’s biodiesel and hydrotreated vegetable oil (HVO) exporters has rocked natural product markets. Our blog post, Oleochemicals Volatility on the Horizon, explores the impacts.
Countries also rely on other means to halt the import of goods from competitor nations. In a blog post, India Halts Imports For Key Intermediate Chemical From China, we explored the Bureau of Indian Standards ruling, which has halted China’s PTA imports.
Future-gazing: Epoxy Resin Supply Chain
China continues to roll out expansion plans that were set in motion before the current downturn. Those expansions are rendering deals formerly made between China and countries such as South Korea and Taiwan unnecessary today. Producers that previously found buyers in China are now looking further afield.
China’s producers, who are faced with a weak domestic market, are also looking for customers in Europe and the US. If offering products at prices significantly lower than domestic producers wins the sale, they will likely do that.
If epoxy resins are subject to provisional anti-dumping duties after the investigations, how will Asia respond? Will the region’s producers still offer products at prices that bear the duty charge and remain attractive to buyers?
Only time will tell…
September 5, 2024
Housing Update
Single-family demand is up, multifamily construction down
By Dakota Smith
September 3, 2024 | 10:12 am CDT

A lack of resale homes and pent-up demand more than offset high mortgage rates and contributed to solid single-family permit growth across nearly all geographic regions in the second quarter. However, multifamily construction permit activity continued its slide downward across the board to the start 2024. Meanwhile, single-family and multifamily construction exhibited strong growth in second-home markets over the past decade, according to the latest findings from the National Association of Home Builders (NAHB) Home Building Geography Index (HBGI) for the second quarter of 2024.
Single family
“Despite the elevated interest rate environment, single-family construction continues to move along at a better pace than 2023 and has been led by a rebound in construction activity in high-density areas,” said NAHB Chairman Carl Harris, a custom home builder from Wichita, Kansas. “Multifamily construction continues to slow as builders deal with higher rates, a shortage of workers, and supply chain concerns for some building materials.”
“The strength in single-family construction at the start of the year continued in higher density areas, matching other data indicating a gain for townhouse construction in 2024,” said NAHB chief economist Robert Dietz. “New data on second homes points to most housing construction taking place in areas with fewer second homes, as most second family homes are located in less urban areas such as non-metro counties.”
The HBGI is a quarterly measurement of building conditions across the country and uses county-level information about single- and multifamily permits to gauge housing construction growth in various urban and rural geographies.
The single-family permit growth rates for all of the HBGI geographic regions were positive in the second quarter, with five of the seven posting double-digit gains. Large metro core counties had the highest growth rate for the second straight quarter at 17.6%. Micro counties had the smallest growth rate, posting a 3.4% gain.
All seven HBGI geographic regions posted negative multifamily permit rates in the second quarter because financing remained tight and high levels of construction inventory of just under 900,000 units are limiting the need for new multifamily permits. This weakness is consistent with the NAHB Multifamily Production Index, which had a second-quarter reading of just 44, marking a year-over-year decrease of 12 points.
Second homes
Using the latest government data on second homes, the HBGI found that 17.5% of single-family home construction and 8.6% of multifamily development occurred in second-home areas during the second quarter of 2024. NAHB defines a second home area as a county where at least 10.3% of the total housing stock consists of a second home.
The county that had the highest share of second homes was Hamilton County, N.Y., where 75.3% of homes were considered a second home based on NAHB’s definition. By contrast, Scott County, Kan.; Andrews County, Texas; Crane County, Texas; and Hansford County, Texas all had no second homes.
The 17.5% of single-family construction in second-home counties during the second quarter of 2024 is up significantly from the fourth quarter of 2014, when these second-home counties posted a single-family market share of 12.9%.
On a percentage basis, multifamily construction in second-home counties experienced a higher growth during the same 10-year span, rising from 4.6% in the fourth quarter of 2014 to 8.6% in the second quarter of 2024.
Key findings
- The year-over-year growth rates for all single-family markets further increased to positive territory, adding to the gains recorded in the first quarter. This positive news was fueled by the limited amount of existing inventory and pent-up demand for single-family construction.
- In the multifamily sector, growth rates remained negative for all markets, continuing the downward trend from last quarter. With over 900,000 apartments currently under construction (the most since 1973) and tighter financial conditions, multifamily construction is slowing from the last year’s highs.
- Labor shortages, supply shortages and higher mortgage rates continue to be issues for both the single-family and multifamily markets.
The full HBGI data with geographic market shares and growth rates can be found here
 Everchem Updates Archive
 Sign Up for Email Updates


